
 Fischer-Tropsch (FT) Wax Market | 2026-2036
Fischer-Tropsch (FT) Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Fischer-Tropsch (FT) Wax Market Analysis
Specialty coatings formulators is collapsing as the dominant buyer archetype for high-melt FT wax grades, while pharmaceutical compounders gain share in controlled-release applications. Sasol leverages integrated gas-to-liquids infrastructure to sustain feedstock cost advantages across African and European supply nodes. Shell anchors large-scale Fischer-Tropsch output from its Pearl GTL complex, competing on volume availability for industrial emulsion grades. Evonik Industries AG differentiates through polymer-modified wax derivatives that command premium positioning in personal care formulations.
Fischer-Tropsch wax denotes a saturated paraffinic hydrocarbon produced via catalytic hydrogenation of carbon monoxide over cobalt or iron catalysts, typically exhibiting congealing points between 60°C and 115°C and zero oil content. Manufacturers deploy these materials as internal lubricants, release agents, and surface modifiers where petroleum-derived slack waxes fail purity or performance specifications. Synthetic wax and microcrystalline wax categories capture the fastest expansion, driven by packaging hot-melt adhesive formulations that demand narrow molecular weight distributions and thermal stability. Solid form factors dominate tonnage shipments, though emulsion and gel forms are gaining traction in waterborne coatings and cosmetic emollients where dispersion uniformity determines end-product performance.
REACH registration requirements and EPA Toxic Substances Control Act filings shape product entry barriers, forcing reformulation where linear FT chains substitute branched petroleum waxes in food-contact and cosmetic applications. ECHA substance evaluation protocols and FDA indirect food additive regulations further constrain additive migration limits, redirecting R&D investment toward hydrogenated Fischer-Tropsch fractions with certified pharmacopeial compliance. Stakeholders must monitor evolving PFAS restrictions in Europe and state-level chemical disclosure laws in the US, as regulatory spillover risks reclassifying wax processing aids and triggering downstream reformulation mandates across adhesive and coatings value chains.
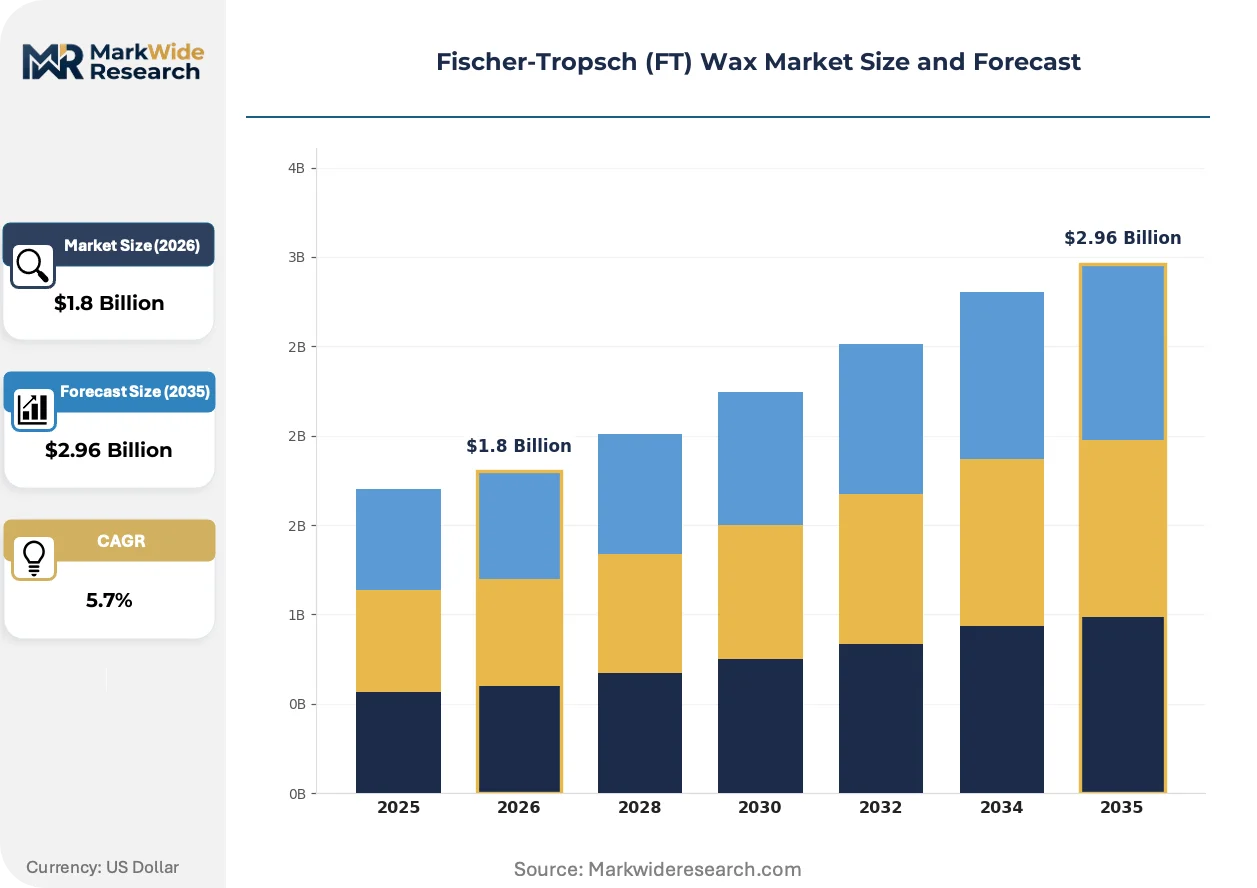
Market Dynamics
Coatings manufacturers are collapsing their supplier bases around high-purity FT waxes as REACH and EPA VOC emission limits force reformulation away from petroleum-derived alternatives. This regulatory compression is restructuring procurement patterns across automotive, packaging, and industrial adhesive value chains.
Growth Catalysts
- REACH VOC Limits:European coatings formulators must substitute branched petroleum waxes with linear FT grades to comply with emission ceilings, concentrating demand in Germany's specialized production clusters.
- Hot-Melt Adhesive Specifications:Packaging manufacturers require narrow molecular weight distributions for thermal stability, pulling synthetic wax volumes into e-commerce fulfillment infrastructure.
- Pharmaceutical Controlled-Release:Compounders adopt hydrogenated FT fractions for tablet matrix systems where pharmacopeial compliance and zero oil content prove critical.
Market Restraints
- Syngas Feedstock Volatility:Natural gas and coal price swings directly compress margins at gas-to-liquids facilities, particularly across African supply nodes.
- Cobalt Catalyst Concentration:Limited suppliers of high-activity cobalt catalysts create single-source vulnerability for premium-grade FT wax production.
- Petroleum Wax Substitution:Slack wax refiners in the US Gulf Coast compete on price for industrial emulsion grades where purity thresholds remain permissive.
Strategic Opportunities
- India Packaging Expansion:Domestic hot-melt adhesive production for corrugated board and flexible packaging remains underpenetrated by certified FT wax suppliers.
- EU Green Deal Incentives:Carbon intensity scoring for synthetic materials creates preferential positioning for biomass-derived syngas pathways in FT wax production.
- Cosmetic Emollient Convergence:Personal care formulators combine polymer-modified FT derivatives with natural oils, opening premium positioning in skin-care applications.
Industry Challenges
- Pharmacopeial Certification Timelines:FDA indirect food additive and USP-NF compliance documentation extends qualification cycles by 18-24 months for new FT wax grades.
- Legacy Adhesive System Integration:Waterborne coatings manufacturers face formulation instability when substituting FT emulsions for conventional microcrystalline wax dispersions.
- PFAS Cross-Contamination Risk:Processing aid reclassification under evolving European restrictions threatens downstream reformulation mandates across adhesive value chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fischer-Tropsch (FT) Wax Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Synthetic Wax, Amide Wax Application: Coatings, Candles, Cosmetics, Adhesives Form: Solid, Liquid, Gel, Emulsion End User: Automotive, Packaging, Personal Care, Pharmaceutical |
| Companies Covered | Hywax GmbH, Nippon Seiro Co. Ltd., Sasol, Mitsui Chemicals, Inc., Deurex AG, Shell, Clariant, King Honor International, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fischer-Tropsch (FT) Wax Market Emerging Trajectories
Technology convergence and regulatory precision are fragmenting the FT wax competitive landscape. Manufacturers now compete on molecular architecture rather than commodity volume, with certification credentials replacing price as the primary procurement filter.
Microcrystalline wax formulations is decomposing as the default lubricant choice in high-performance coatings. Automotive OEMs specify FT-based release agents for underbody sealants where thermal stability above 105°C prevents sagging during curing. This substitution is compressing demand for petroleum-derived alternatives in German and Japanese automotive supply chains.
REACH substance evaluation protocols now require full supply chain disclosure for wax additives in food-contact applications. ECHA's 2024 updated guidance on polymer migration limits forces reformulators to document linear paraffin chain provenance. Personal care and pharmaceutical segments respond by demanding certified hydrogenated FT fractions with batch-level traceability.
Specification-driven purchasing now dominates procurement patterns in specialty coatings. Large formulators consolidate vendor lists to three approved FT wax suppliers per region, replacing spot-market buying. This concentration is most visible in German automotive coatings clusters, where BASF and Axalta mandate pre-qualified wax grades for all new product development.
Fischer-Tropsch (FT) Wax Market Segmentation
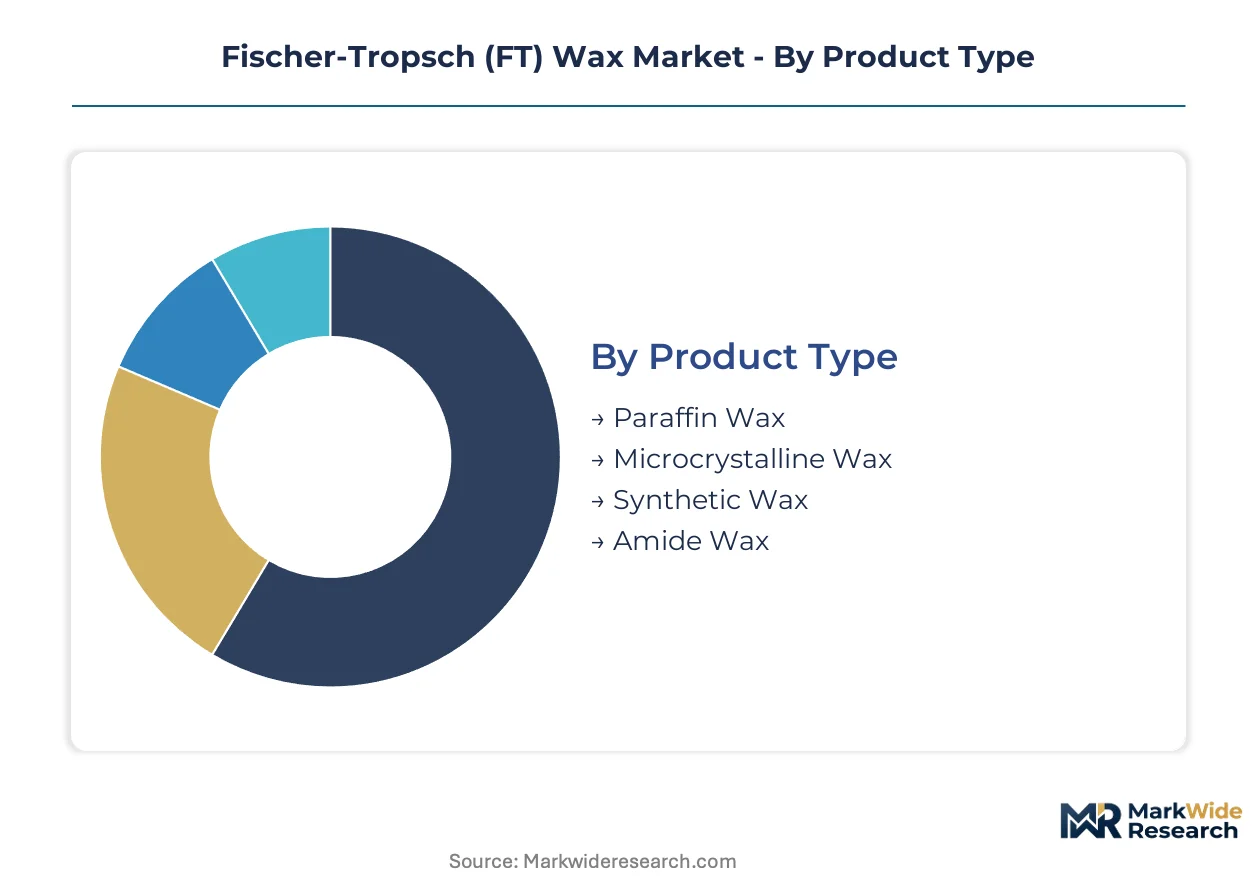
FT wax segmentation reveals how molecular architecture and form factor determine substitution vulnerability across end-use verticals. Specification divergence between commodity petroleum waxes and certified synthetic grades is fragmenting procurement patterns by purity tier and regulatory exposure.
Product Type:
Paraffin wax faces the most acute displacement pressure as REACH VOC ceilings force coatings formulators toward linear synthetic alternatives with documented chain provenance.
- Synthetic Wax:Saturated paraffinic hydrocarbons produced via cobalt or iron catalysis deliver congealing points between 60°C and 115°C with zero oil content. German automotive OEMs now mandate these grades for underbody sealants where thermal stability above 105°C prevents sagging during paint shop curing cycles.
- Microcrystalline Wax:Branched petroleum-derived structures with higher oil content are decomposing as the default lubricant choice in high-performance coatings. Japanese automotive supply chains specify FT-based release agents instead, compressing demand for conventional microcrystalline dispersions.
- Paraffin Wax:Petroleum slack wax refiners in the US Gulf Coast compete on price for industrial emulsion grades where purity thresholds remain permissive under EPA TSCA frameworks.
- Amide Wax:Functionalized derivatives command premium positioning in personal care formulations where polymer modification creates skin-feel differentiation.
Synthetic wax anchors the volume base while microcrystalline wax loses share at the steepest rate to certified FT substitutes.
Application:
Cost tier stratification separates specification-driven buyers from price-sensitive commodity purchasers across adhesive and coatings value chains.
- Coatings:REACH and EPA VOC emission limits force reformulation away from branched petroleum waxes toward linear FT grades with narrow molecular weight distributions. Large formulators consolidate vendor lists to three approved suppliers per region.
- Adhesives:Packaging hot-melt formulations for e-commerce fulfillment infrastructure pull synthetic wax volumes based on thermal stability requirements during high-speed application.
- Cosmetics:Personal care formulators combine polymer-modified FT derivatives with natural oils, opening premium positioning in skin-care applications.
- Candles:Fragrance load compatibility and clean-burn specifications drive adoption of hydrogenated FT fractions with certified pharmacopeial compliance.
Coatings applications concentrate procurement spend while adhesive applications expand most quickly through packaging infrastructure buildout.
Form:
Customer type divergence separates industrial bulk buyers from precision formulators requiring dispersion uniformity.
- Solid:Dominant tonnage shipments serve hot-melt adhesive compounders and candle manufacturers where melt point precision determines processing parameters.
- Emulsion:Waterborne coatings manufacturers face formulation instability when substituting FT emulsions for conventional microcrystalline wax dispersions, extending qualification cycles.
- Liquid:Low-viscosity grades penetrate cosmetic emollient applications where blend compatibility with natural oils creates texture engineering opportunities.
- Gel:Structured formulations gain traction in pharmaceutical controlled-release matrix systems where batch-level traceability satisfies USP-NF documentation requirements.
Solid form factors dominate current shipments while emulsion forms climb the fastest through waterborne coatings conversion.
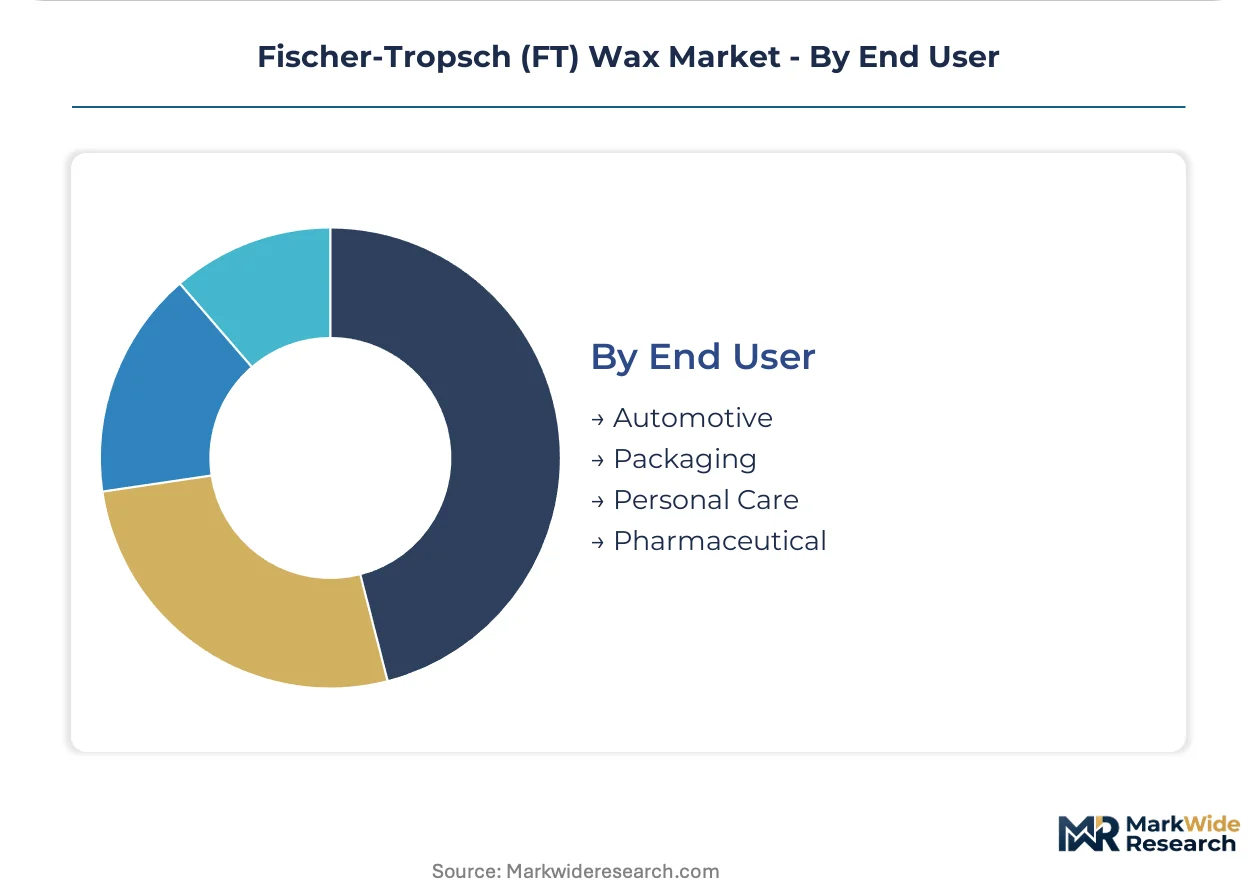
End User:
Supply concentration in Germany's specialized production clusters aligns with automotive and packaging grade demand from European formulators.
- Packaging:Corrugated board and flexible packaging adhesive production in India remains underpenetrated by certified FT wax suppliers, creating qualification opportunities for exporters meeting BIS standards.
- Automotive:OEM specification of FT-based release agents for underbody sealants compresses demand for petroleum-derived alternatives in German and Japanese supply chains.
- Pharmaceutical:FDA indirect food additive and USP-NF compliance documentation extends qualification cycles by 18-24 months for new FT wax grades entering tablet matrix systems.
- Personal Care:ECHA substance evaluation protocols on polymer migration limits force reformulators to document linear paraffin chain provenance for batch-level traceability.
Packaging end users anchor the volume base while pharmaceutical end users gain share at the steepest rate through controlled-release application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German FT wax exports flow primarily into automotive coatings supply chains across France, Italy, and Poland, while South African gas-to-liquids output reaches Asian adhesive compounders through Singaporean distribution nodes.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify FT-based release agents for underbody sealants where thermal stability above 105°C prevents sagging during paint shop curing. REACH substance evaluation protocols require full supply chain disclosure for wax additives in food-contact applications. Hywax GmbH and Deurex AG anchor specialized production clusters in Saxony and Thuringia, supplying certified grades to BASF and Axalta formulators.
United States
Packaging hot-melt adhesive producers in the Midwest pull synthetic wax volumes for e-commerce fulfillment infrastructure expansion. EPA Toxic Substances Control Act filings shape product entry barriers, forcing reformulation where linear FT chains substitute branched petroleum waxes. Slack wax refiners along the US Gulf Coast compete on price for industrial emulsion grades where purity thresholds remain permissive.
China
Corrugated board and flexible packaging manufacturers in the Yangtze River Delta and Pearl River Delta drive adhesive-grade FT wax consumption. The country's national chemical regulator enforces GB standards for indirect food additive migration limits. Domestic producers concentrate in Shandong Province, though certified pharmaceutical-grade supply remains import-dependent.
India
Domestic hot-melt adhesive production for corrugated board and flexible packaging remains underpenetrated by certified FT wax suppliers, creating qualification opportunities for exporters. BIS standards govern wax additive specifications in food-contact applications. Maharashtra and Gujarat host emerging packaging manufacturing clusters where adhesive compounders seek certified synthetic wax alternatives.
South Africa
Sasol leverages integrated gas-to-liquids infrastructure at its Secunda complex to sustain feedstock cost advantages for export-oriented production. Natural gas price volatility directly compresses margins at gas-to-liquids facilities. The industrial corridor between Johannesburg and Durban serves as the primary export node for African and European supply chains.
Fischer-Tropsch (FT) Wax Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive syngas infrastructure, supplemented by specialized wax refiners and polymer modification specialists. Market structure concentrates around three strategic tiers: gas-to-liquids operators with backward integration into feedstock production, regional wax refiners serving specification-driven coatings formulators, and polymer-modified derivative specialists commanding premium positioning in personal care. Dominant competitive moves include capacity expansion at Pearl GTL-scale facilities and strategic partnerships between wax refiners and automotive coatings formulators for pre-qualified supply agreements.
Within the integrated petrochemical tier, Sasol and Shell exemplify archetypes that combine syngas production with downstream wax fractionation, occupying positions where feedstock cost control determines margin sustainability. Among specialized German refiners, Hywax GmbH and Deurex AG represent the specification-driven segment, anchoring supply relationships with automotive OEMs that mandate batch-level traceability and REACH-compliant documentation. Evonik Industries AG sits within the polymer-modified derivative specialists, exemplifying how functionalized wax architectures command premium positioning in pharmaceutical and personal care applications where pharmacopeial compliance creates qualification barriers for commodity producers.
| Leading Market Players |
|---|
| Hywax GmbH |
| Nippon Seiro Co. Ltd. |
| Sasol |
| Mitsui Chemicals, Inc. |
| Deurex AG |
| Shell |
| Clariant |
| King Honor International |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Linear FT wax substitution for branched petroleum slack waxes simultaneously redraws supply geography toward German and South African production clusters and compresses pricing power among US Gulf Coast refiners unable to meet REACH documentation requirements. This displacement dynamic concentrates procurement leverage with coatings formulators who consolidate vendor lists to three approved suppliers per region.
Pricing Analysis
Cobalt-catalyzed premium grades command substantial premiums over iron-catalyzed standard offerings and legacy petroleum-derived economy tiers. Three-tier pricing structure across pharmacopeial-certified, industrial-grade, and uncertified commodity levels reflects differentiation by ECHA REACH compliance depth and batch-level chain-of-custody documentation. Cost compression in industrial emulsion segments is intensifying because US slack wax refiners compete aggressively on price where EPA TSCA purity thresholds remain permissive. Packaging adhesive compounders exhibit highest price sensitivity due to volume scale and specification flexibility, while pharmaceutical formulators show least sensitivity given USP-NF compliance barriers.
Supply Chain Analysis
Strategic stockpiling of cobalt catalyst precursors dominates inventory strategy among premium-grade producers facing single-source catalyst vulnerability, whereas just-in-time feedstock management prevails at integrated gas-to-liquids facilities with captive syngas. Supply concentrates in South Africa, Germany, and China, with raw material dependencies centering on natural gas or coal syngas feedstocks, high-activity cobalt catalysts, and hydrogen supply. Single-source vulnerability for specialized catalyst suppliers creates structural supply chain risk. Distribution runs through regional distribution nodes in Singapore for Asian adhesive compounders and Rotterdam for European coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across REACH-compliant, FDA-registered, and uncertified grade tiers creates multiple niche entry points for specialized producers as coatings formulators abandon spot-market purchasing for pre-qualified supply agreements.
For Market Incumbents: Shield margin position by deepening backward integration into syngas production or catalyst regeneration capabilities, and accelerate pharmacopeial certification investments to capture pharmaceutical controlled-release expansion before qualification timelines extend further. Petroleum wax substitution pressure from US Gulf Coast refiners threatens industrial-grade pricing floors. For New Entrants and Emerging Players: Differentiate on biomass-derived syngas pathways to capture EU Green Deal carbon intensity scoring advantages, and target India's underpenetrated corrugated board adhesive segment where BIS certification gaps create qualification windows for exporters with documented linear chain provenance. Direct technical sales engagement with Maharashtra and Gujarat packaging clusters offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed German wax refiners holding automotive OEM pre-qualification status but lacking pharmaceutical certification depth. Five-to-ten year viability hinges on regulatory compliance moat sustainability rather than volume scale. Watch for ECHA PFAS restriction spillover into wax processing aid reclassification as the critical inflection signal triggering downstream reformulation mandates and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Syngas Production | Sasol and Shell sustain margin control through captive natural gas and coal feedstock access at Secunda and Pearl complexes. |
| Pharmacopeial Certification Investment | Hywax GmbH and Deurex AG extend qualification cycles to capture pharmaceutical tablet matrix expansion. |
| Biomass-Derived Syngas Transition | EU Green Deal carbon scoring creates preferential positioning for renewable pathway producers against fossil-based competitors. |
| Long-term Supply Agreement with Automotive OEMs | BASF and Axalta mandate pre-qualified wax grades, locking in volume commitments for Bavarian underbody sealant specifications. |
| Joint Venture for India Market Entry | Maharashtra packaging clusters seek certified synthetic wax alternatives through local compounding partnerships meeting BIS standards. |
Methodological Framework
The analysis maps synthetic wax, microcrystalline wax, paraffin wax, and amide wax sub-sectors, each validated through coatings formulators, adhesive compounders, pharmaceutical technical directors, and automotive OEM procurement managers. Primary interviews with plant managers at gas-to-liquids facilities, downstream procurement leads, and distribution channel partners combined with secondary validation from customs/trade data, ECHA substance evaluation protocols, SEC 10-K filings, and FDA indirect food additive registrations. Bottom-up grade-by-grade volume builds triangulated against top-down end-use consumption estimates.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework models grade tier, end-use industry, form factor, and regional production hub segmentation dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating syngas feedstock cost trajectories and regulatory compliance timeline assumptions. Industry-specific inputs include REACH substance evaluation protocol adoption rates and pharmaceutical USP-NF qualification cycle extensions.
Material uncertainties — syngas feedstock volatility, cobalt catalyst supply disruption, and ECHA PFAS restriction spillover — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory compliance depth and substitution elasticity. Revision becomes warranted when automotive OEM specification shifts or catalyst supply concentration crosses critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Hydrogen Sulphide Market
Industrial Chemicals
North America Molecular Sieve Market