
 Explosion Venting Market | 2026-2036
Explosion Venting Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Venting Market Insights
ATEX Directive 2014/34/EU is pivoting European manufacturers toward certified explosion venting architectures. REMBE GmbH leverages its German engineering base to dominate high-performance rupture disc assemblies. Fike Corporation anchors North American demand through NFPA-compliant venting systems for chemical processing. ZOOK Enterprises, LLC specializes in custom-fabricated panels that navigate complex vessel geometries.
Explosion venting encompasses pressure-relief devices—rupture discs, vent panels, and flameless vents—engineered to open at precise burst pressures between 0.1 and 10 bar, protecting vessels and ductwork from deflagration damage. The technology serves pharmaceutical cleanrooms, grain handling facilities, and petrochemical reactors where combustible dust or vapor hazards exist. Vents and panels capture the largest share of product type revenue, while flameless vent variants for indoor installations represent the fastest-growing sub-category. Oil and gas applications command premium pricing due to offshore certification requirements, though food processing demand is expanding fastest as NFPA 68 compliance spreads through grain milling and sugar refining.
NFPA 68 and NFPA 69 standards in the United States, ATEX directives across European Union member states, and China's GB standards through SAMR collectively mandate explosion protection in hazardous process environments. OSHA enforcement of combustible dust National Emphasis Programs in the United States drives facility retrofit cycles. Stakeholders must monitor evolving flameless venting certification protocols and weigh modular installation architectures against permanent fixed systems when planning capital deployment.
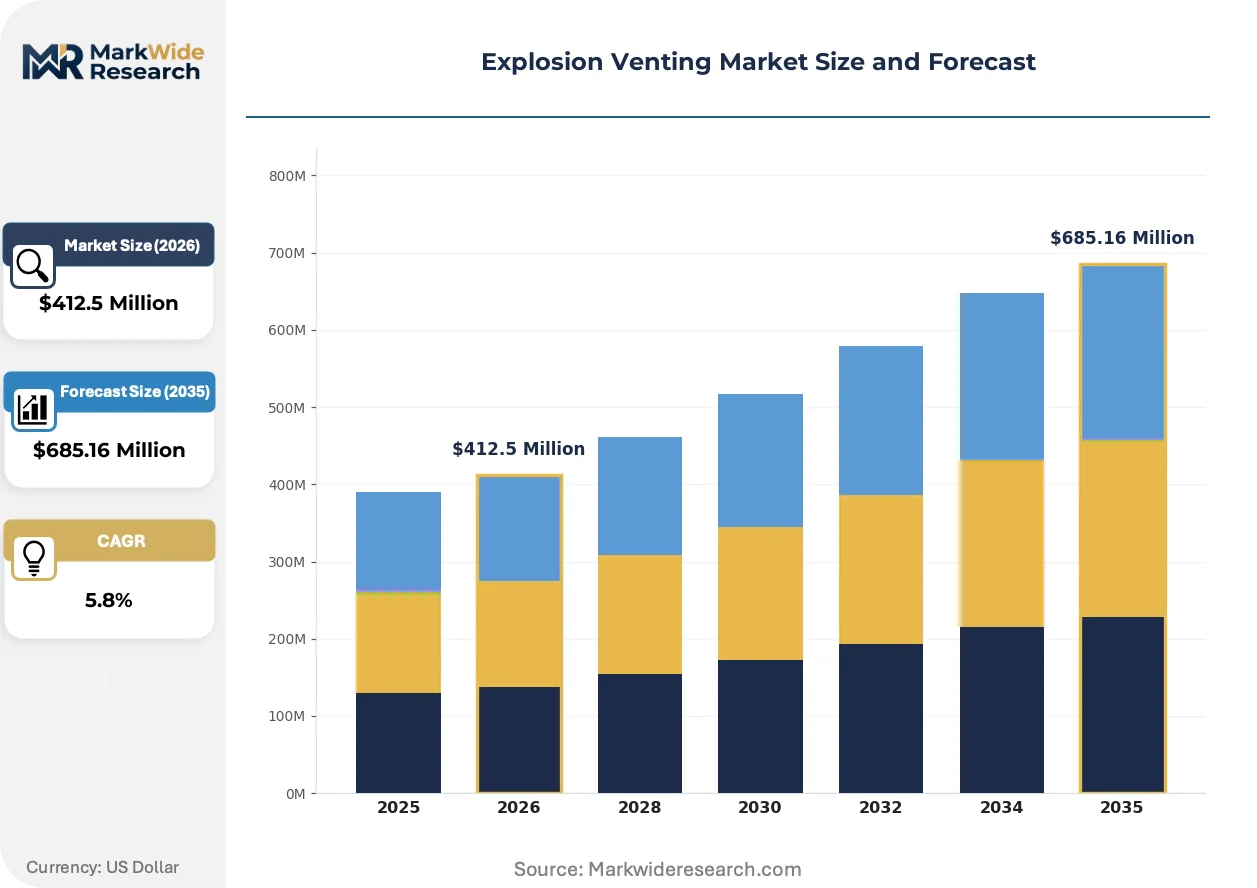
Market Dynamics
ATEX Directive 2014/34/EU enforcement is compressing facility retrofit timelines across European process industries, forcing capital deployment toward certified explosion venting architectures ahead of original maintenance cycles.
Growth Catalysts
- OSHA Combustible Dust National Emphasis Programs:United States grain milling and sugar refining facilities face stepped-up inspection protocols, triggering replacement of legacy venting systems with NFPA 68-compliant assemblies.
- Stainless steel corrosion resistance:Petrochemical corridors along the United States Gulf Coast specify 316L-grade vent panels for salt-air environments, extending replacement intervals versus carbon steel alternatives.
- Modular flameless vent designs:Indoor pharmaceutical cleanrooms in Germany adopt cartridge-based vent units that eliminate external ductwork, reducing installation footprint and maintenance access requirements.
Market Restraints
- Nickel alloy price volatility:Inconel and Hastelloy rupture disc materials face supply pressure from aerospace and nuclear sector competition, compressing margins for high-temperature venting applications.
- German engineering concentration:Certified ATEX testing laboratories cluster in Bavaria and Baden-Württemberg, creating bottlenecks for manufacturers seeking rapid product validation.
- Suppression system substitution:Chemical reactor operators in high-value processes increasingly specify explosion suppression over venting for toxic material containment, limiting addressable market in pharmaceutical API synthesis.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Greenfield manufacturing parks in Gujarat and Maharashtra require ATEX-equivalent protection systems, opening demand for cost-optimized vent panel designs.
- Hybrid vent-suppression integration:Converging mechanical venting with optical detection and chemical isolation creates bundled safety architectures for dust collection systems in food processing.
- Digital twin certification:Computational fluid dynamics modeling for deflagration scenarios accelerates custom vent sizing, enabling remote engineering services for vessel fabricators without in-house explosion dynamics expertise.
Industry Challenges
- Explosion dynamics modeling specialization:Facility engineers lack training in dust KSt values and vent area calculations, forcing manufacturers to provide embedded technical support that strains field service capacity.
- Legacy vessel retrofit geometry:Existing reactors and silos present irregular nozzle configurations that resist standard panel mounting, requiring site-specific fabrication that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Venting Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vents, Panels, Valves, Breakaway Seal Application: Pharmaceutical, Food Processing, Chemical Manufacturing, Oil & Gas Installation Type: Static, Portable, Fixed, Modular End User: Manufacturers, Contractors, Consultants, Facility Managers |
| Companies Covered | Fike Corporation, ZOOK Enterprises, LLC, Elfab Ltd, BS&B Safety Systems, L.L.C., REMBE GmbH, IEP Technologies, CV Technology, STIF France, Construction Specialties, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Venting Market Trends and Innovations
Wireless pressure monitoring and predictive burst detection are reconfiguring how explosion venting systems integrate into plant safety architectures, shifting value capture from hardware sales toward continuous monitoring services.
Membrane-based rupture discs with integrated burst indicators are decentralizing maintenance scheduling across pharmaceutical and food processing facilities. These sensors transmit real-time integrity status to distributed control systems, enabling condition-based replacement rather than calendar-based intervals. Bayer and BASF manufacturing sites in Germany have piloted this architecture, compressing unplanned downtime events.
REACH chemical registration requirements are tightening material traceability for vent panel coatings and gaskets used in European process equipment. Manufacturers must now document full substance inventories for PTFE and graphite sealing elements, adding compliance overhead that favors larger suppliers with dedicated regulatory affairs functions. Stainless steel vent fabricators serving the German chemical sector have reorganized supply chains to segregate REACH-compliant material flows.
Specification authority is migrating from plant maintenance departments to centralized corporate safety engineering teams, consolidating vendor selection across multi-site operators. This concentration favors suppliers with global service networks and standardized product platforms over regional fabricators. Grain handling cooperatives in the United States Midwest have adopted this model, reducing qualified vendor lists from twelve to three national suppliers.
Explosion Venting Market Segmentation
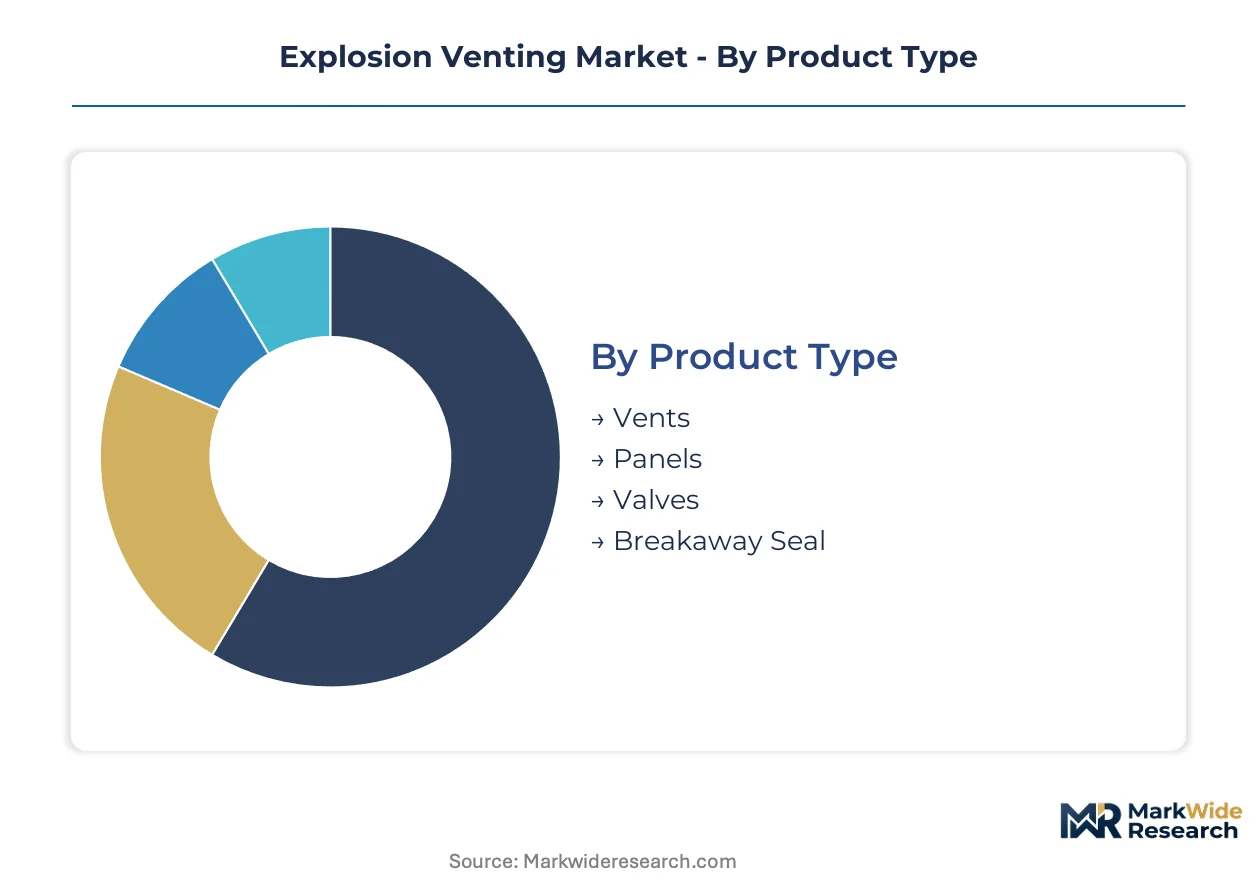
Explosion venting procurement varies sharply across product architectures, operational contexts, and installation constraints. Facility engineers match venting technology to deflagration hazard class, vessel geometry, and regulatory jurisdiction—creating distinct demand pockets with specialized specification requirements.
Product Type:
Upgrade cycles for legacy venting systems concentrate on pressure-relief performance and corrosion resistance specifications.
- Vents:Rupture discs and vent openings engineered to activate at precise burst pressures between 0.1 and 10 bar protect vessels from deflagration damage. Chemical manufacturing facilities in Germany specify these for reactor vessels under tightened ATEX Directive 2014/34/EU enforcement.
- Panels:Stainless steel vent panels—particularly 316L-grade—dominate United States Gulf Coast petrochemical corridor demand for salt-air corrosion resistance. Grain handling facilities specify these for silo protection under OSHA Combustible Dust National Emphasis Programs.
- Valves:Reclosing pressure-relief devices suit processes where containment must resume after venting events.
- Breakaway Seal:Single-use rupture elements for low-pressure ductwork applications.
Volume placements concentrate in Panels; the faster expansion belongs to Vents as pharmaceutical cleanrooms adopt cartridge-based designs.
Application:
Cost tier stratification separates premium-certified systems for hazardous processes from standard configurations in lower-risk environments.
- Pharmaceutical:Cleanroom-grade flameless vents with integrated burst indicators enable condition-based maintenance scheduling. Modular cartridge designs eliminate external ductwork in German Bayer and BASF manufacturing sites.
- Food Processing:NFPA 68 compliance spreads through grain milling and sugar refining as OSHA enforcement intensifies. Stainless steel panels face stepped-up replacement cycles in United States Midwest grain cooperatives.
- Chemical Manufacturing:ATEX-certified rupture disc assemblies dominate European process industry procurement.
- Oil & Gas:Offshore certification requirements command premium pricing for corrosion-resistant venting architectures.
Procurement volumes cluster in Chemical Manufacturing; Food Processing climbs the fastest as NFPA compliance extends beyond traditional grain handling.
Installation Type:
Customer type determines flexibility requirements—permanent facilities favor fixed systems while contract processors need redeployable protection.
- Static:Permanent venting configurations for dedicated process lines with stable hazard profiles.
- Portable:Mobile venting units for temporary dust collection systems in contract manufacturing.
- Fixed:Hard-piped installations dominate United States petrochemical and German chemical manufacturing infrastructure.
- Modular:Cartridge-based flameless vent designs reduce installation footprint in indoor pharmaceutical cleanrooms.
Fixed systems capture the largest installed base; Modular configurations gain share fastest as facility retrofit timelines compress.
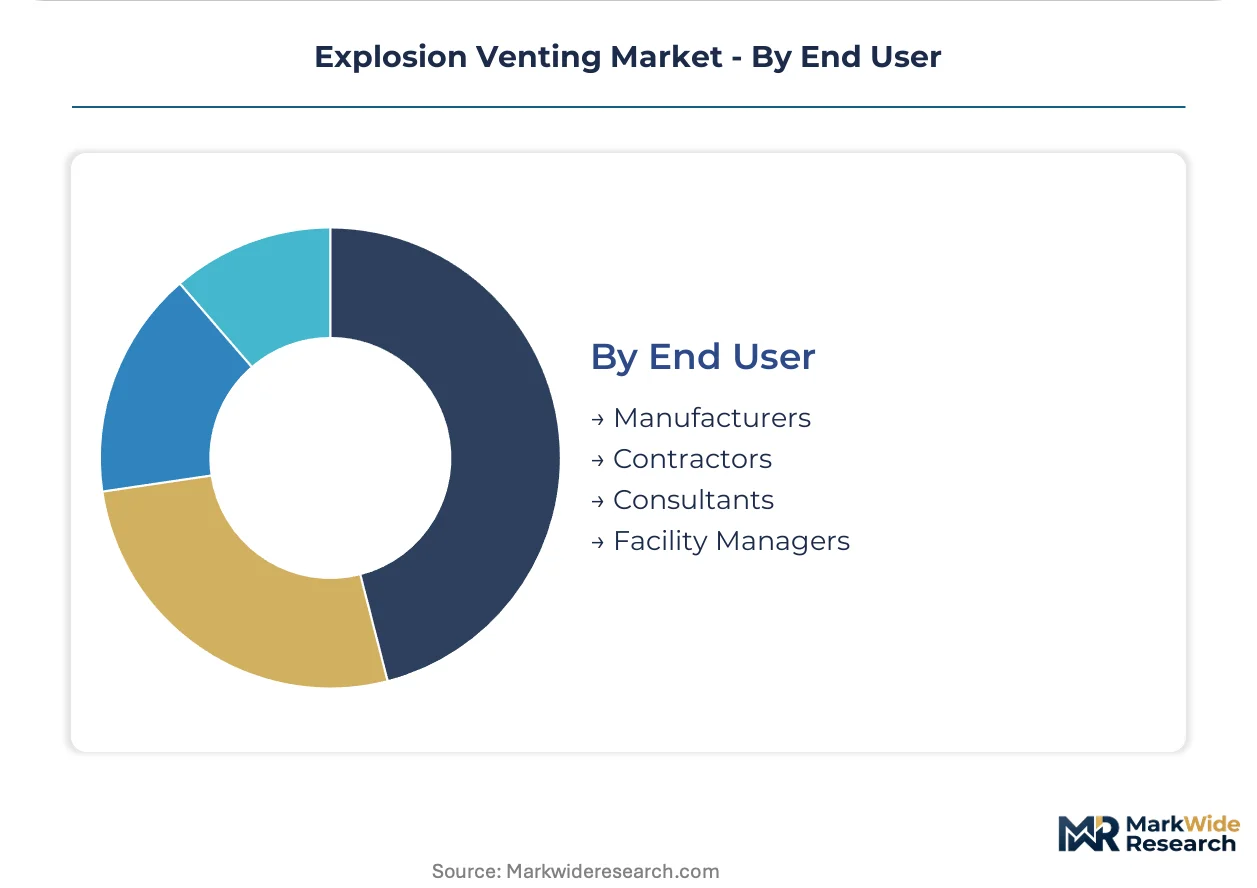
End User:
Supply concentration favors vendors with embedded technical support capacity to address specification complexity.
- Manufacturers:Original equipment fabricators specify venting during vessel design, enabling integrated safety architectures.
- Contractors:Installation specialists navigate irregular nozzle configurations in legacy vessel retrofits.
- Consultants:Safety engineering teams consolidate vendor selection across multi-site operators, reducing qualified supplier lists.
- Facility Managers:Maintenance departments shift toward centralized corporate safety teams for specification authority.
Specification authority is migrating toward Consultants; Facility Managers show the steepest adoption curve for wireless monitoring integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for explosion venting systems concentrates in industrial corridors with dense chemical processing and grain handling infrastructure. Facility retrofit cycles and regulatory enforcement timelines vary sharply across national jurisdictions, creating asynchronous procurement waves.
United States
OSHA Combustible Dust National Emphasis Programs drive replacement cycles across grain milling and sugar refining facilities. NFPA 68 and NFPA 69 standards mandate vent sizing calculations for dust collection systems. The Gulf Coast petrochemical corridor specifies 316L-grade stainless steel panels for salt-air corrosion resistance in offshore and coastal installations.
Germany
ATEX Directive 2014/34/EU enforcement compresses retrofit timelines for chemical manufacturing facilities. REACH chemical registration requirements tighten material traceability for vent panel coatings and gaskets. Bavaria and Baden-Württemberg host certified testing laboratories that validate rupture disc assemblies for European process industries.
China
GB standards through SAMR mandate explosion protection in hazardous process environments for specialty chemical manufacturing. Dual carbon goals accelerate facility modernization in state-owned petrochemical complexes. The Yangtze River Delta chemical parks require ATEX-equivalent protection systems for foreign joint ventures.
India
The PLI scheme for specialty chemicals generates greenfield demand in Gujarat and Maharashtra manufacturing parks. Central Electricity Authority regulations govern hazardous area classification for process equipment. Pharmaceutical API clusters around Hyderabad and Ahmedabad specify flameless vent designs for indoor reactor protection.
United Kingdom
Post-Brexit alignment with ATEX frameworks maintains certification requirements for chemical and pharmaceutical manufacturing. The Health and Safety Executive enforces combustible dust regulations through COMAH inspections. Grangemouth and Teesside industrial clusters drive demand for corrosion-resistant venting in refinery and petrochemical applications.
Explosion Venting Market Competitive Landscape
German engineering specialists anchor one tier; North American diversified safety conglomerates hold another. The vendor base separates into certification-heavy European fabricators and scale-oriented US system integrators. Three archetypes dominate: ATEX-certified rupture disc specialists, NFPA-compliant full-line suppliers, and custom panel fabricators for irregular vessel geometries. Competitive moves concentrate on geographic licensing partnerships and modular product platform expansion.
Among German-based specialists, REMBE GmbH exemplifies the engineering-intensive archetype with Bavarian manufacturing roots. Fike Corporation and ZOOK Enterprises, LLC represent North American market presence—Fike as a Missouri-anchored diversified safety systems provider, ZOOK as a Kansas-based custom fabrication specialist. These three occupy positions spanning standardized certification platforms to site-specific engineering services.
| Leading Market Players |
|---|
| Fike Corporation |
| ZOOK Enterprises, LLC |
| Elfab Ltd |
| BS&B Safety Systems, L.L.C. |
| REMBE GmbH |
| IEP Technologies |
| CV Technology |
| STIF France |
| Construction Specialties, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cartridge-based flameless vent designs are compressing manufacturing economics while redrawing supplier concentration across German pharmaceutical corridors and United States Gulf Coast petrochemical zones. This technology transition favors fabricators with captive machining capacity over outsourced panel producers, tightening margin capture at the high-performance tier.
Pricing Analysis
Volume placements concentrate in standard-grade stainless steel panels; margin capture concentrates in ATEX-certified rupture disc assemblies with integrated burst indicators. Price differentiation rests on certification grade—ATEX versus NFPA tiers—and corrosion-resistant alloy specification, with 316L-grade commanding premiums over carbon steel alternatives. Pricing pressure stems from nickel alloy volatility in Inconel and Hastelloy sourcing, compressing margins for high-temperature applications. Grain handling cooperatives in the United States Midwest exhibit highest price sensitivity; offshore oil and gas operators show lowest sensitivity given certification rigidity.
Supply Chain Analysis
Specialized welding technicians and explosion dynamics engineers cluster in Bavaria and Baden-Württemberg, constraining capacity expansion for certified German fabricators. Raw material flows draw from Swedish stainless steel mills, Japanese specialty alloy producers, and Chinese graphite suppliers for sealing elements. Single-source vulnerability concentrates in REACH-compliant PTFE and gasket material certification, where European testing laboratory bottlenecks delay validation. Distribution runs through OEM vessel fabricators and aftermarket service networks, with direct procurement by multi-site chemical operators gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless pressure monitoring and predictive burst detection are displacing calendar-based maintenance scheduling, creating a technology-transition window for vendors with embedded sensor integration capabilities.
For Market Incumbents: Deploy backward integration into nickel alloy sourcing to hedge aerospace sector competition for Inconel and Hastelloy. Expand certified testing laboratory partnerships in Germany to reduce ATEX validation bottlenecks. Explosion suppression systems threaten venting market share in pharmaceutical API synthesis; counter with hybrid vent-suppression bundled offerings.
For New Entrants and Emerging Players: Enter via India's PLI scheme for specialty chemicals, targeting greenfield manufacturing parks in Gujarat and Maharashtra with cost-optimized vent panel designs. White-space exists in digital twin certification services for vessel fabricators lacking in-house explosion dynamics expertise. Pursue remote engineering partnerships with regional fabricators as the go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with modular flameless vent specialists given pharmaceutical cleanroom retrofit acceleration and indoor installation footprint constraints. Long-term viability favors vendors with integrated monitoring service platforms over pure hardware fabricators. Watch for OSHA enforcement intensity in United States grain milling as the inflection signal for replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | In-house Inconel sourcing insulates margins from aerospace competition for rupture disc materials. |
| Certified Testing Laboratory Expansion | Additional ATEX validation capacity in Germany compresses product launch timelines for European process industries. |
| Hybrid Vent-Suppression Platform Launch | Converged safety architectures address pharmaceutical API synthesis substitution threat from pure suppression systems. |
| Digital Twin Certification Service | Computational fluid dynamics modeling enables remote custom vent sizing for vessel fabricators without explosion dynamics expertise. |
| Wireless Monitoring Service Tier | Condition-based replacement contracts shift value capture from hardware sales toward recurring revenue streams. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers, safety directors at chemical manufacturers, procurement leads at grain handling cooperatives, and aftermarket service heads at OEM vessel fabricators. Secondary validation drew from OSHA enforcement databases, ATEX certification registries, NFPA standards documentation, and SEC filings from listed safety systems providers. Bottom-up vessel counts by industry vertical were triangulated against top-down market value estimates.
Data-stream reconciliation across shipment volumes, certification registrations, and installed base replacement cycles generated consistent growth trajectories across the projection horizon. Segmentation modeling incorporated product architecture, application hazard class, installation type flexibility, and end-user specification authority. CAGRs were derived from regression analysis of historical retrofit cycles against regulatory enforcement intensity. Industry-specific inputs included dust KSt value distributions by commodity type and vessel pressure rating specifications by process industry.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt nickel alloy price spikes or accelerated OSHA enforcement timelines. Forecasts reflect documented assumptions regarding regulatory continuity and technology substitution rates. Material deviation in ATEX directive amendment timing or REACH chemical registration scope expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Honing Oil Market