
 Nonylphenol Ethoxylate Market | 2026-2036
Nonylphenol Ethoxylate Market Size, Share, and Industry Trends Forecast 2026-2036
Nonylphenol Ethoxylate Market Outlook
Specialty chemical processors is reorganizing procurement priorities around NP-9 and NP-10 grades for precision cleaning formulations. Dow Inc. leverages captive ethylene oxide supply chains to stabilize feedstock costs across North American manufacturing. Stepan Company anchors its position through dedicated R&D facilities focused on low-foam industrial variants. Solvay differentiates via specialized emulsion-grade production serving European coatings manufacturers.
Nonylphenol ethoxylates are nonionic surfactants synthesized through ethoxylation of nonylphenol with ethylene oxide, typically yielding hydrophilic-lipophilic balance values between 13 and 15 for detergent and wetting applications. These compounds function primarily as emulsifiers, dispersants, and detergents in aqueous and solvent-based systems across industrial and consumer formulations. NP-9 dominates volume consumption in household cleaners and textile scouring where moderate ethoxylation balances cost and performance. Liquid formulations capture the largest share of commercial shipments due to easier handling in automated dosing systems. Powder grades retain relevance in concentrated laundry and institutional cleaning compounds where shipping density reduces logistics expenditure.
REACH restrictions through ECHA govern nonylphenol ethoxylate content in European consumer and industrial products, driving substitution toward alcohol ethoxylates in sensitive applications. EPA oversight under the Toxic Substances Control Act shapes permissible concentrations in US industrial degreasers and textile processing aids. China's MEE enforces wastewater discharge standards that limit nonylphenol metabolite concentrations from manufacturing facilities. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and regional supply reallocations.
Market Dynamics
REACH restrictions through ECHA are compressing formulation freedom across European industrial applications, forcing specialty chemical processors to rebuild supply chains around alcohol ethoxylate substitutes while maintaining performance thresholds in textile scouring and coatings manufacturing.
Growth Catalysts
- Industrial degreaser demand:Precision cleaning requirements in automotive and aerospace maintenance operations are pulling NP-9 and NP-10 grades into high-throughput automated systems. Metal fabrication facilities specify these surfactants for heavy-duty soil removal.
- China's domestic surfactant scale-up:Textile processing clusters in Zhejiang and Jiangsu provinces are absorbing rising volumes of nonylphenol ethoxylates as local producers displace imports. Coatings manufacturers in the Yangtze River Delta anchor consumption growth.
- Ethoxylation process refinements:Narrower ethylene oxide distribution curves are yielding more consistent HLB values, improving batch-to-batch reliability for emulsion-grade applications. Specialty chemical buyers recognize performance gains in water-based industrial coatings.
Market Restraints
- Ethylene oxide feedstock volatility:Captive supply advantages favor integrated producers while merchant buyers absorb price swings from upstream petrochemical cycles. Dow Inc.'s North American ethylene oxide infrastructure exemplifies this structural divide.
- Substitution pressure from alcohol ethoxylates:Linear and branched alcohol ethoxylates are capturing share in European consumer cleaning products where biodegradability metrics dominate procurement scoring. Stepan Company's R&D pivot reflects this displacement threat.
- Wastewater metabolite limits:China's MEE discharge standards constrain manufacturing facility expansions in major production zones. Environmental compliance capital requirements are rising for nonylphenol ethoxylate producers serving domestic textile processors.
Strategic Opportunities
- Low-foam industrial variants:Dedicated R&D investment in controlled-foam chemistry opens penetration into high-shear metalworking fluid applications. Machine tool coolant formulators seek surfactants that tolerate extreme agitation without foam-induced pump cavitation.
- Emulsion-grade specialization:European coatings manufacturers demand narrow-specification products for waterborne architectural and industrial paint systems. Solvay's production focus in this segment demonstrates viable premium positioning.
- Automated dosing system compatibility:Liquid formulation designs optimized for precision injection equipment are capturing share from manual-handling alternatives. Institutional and commercial cleaning operations prioritize labor reduction through equipment integration.
Industry Challenges
- Reformulation timeline compression:REACH sunset dates for specific nonylphenol ethoxylate applications are forcing simultaneous technical qualification and supply chain revalidation. Product stewardship teams face overlapping regulatory deadlines across multiple European member states.
- Cross-jurisdiction compliance fragmentation:Divergent EPA state-level rules in the United States create formulation complexity for national industrial degreaser brands. Texas and California environmental standards differ sufficiently to require state-specific product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonylphenol Ethoxylate Market |
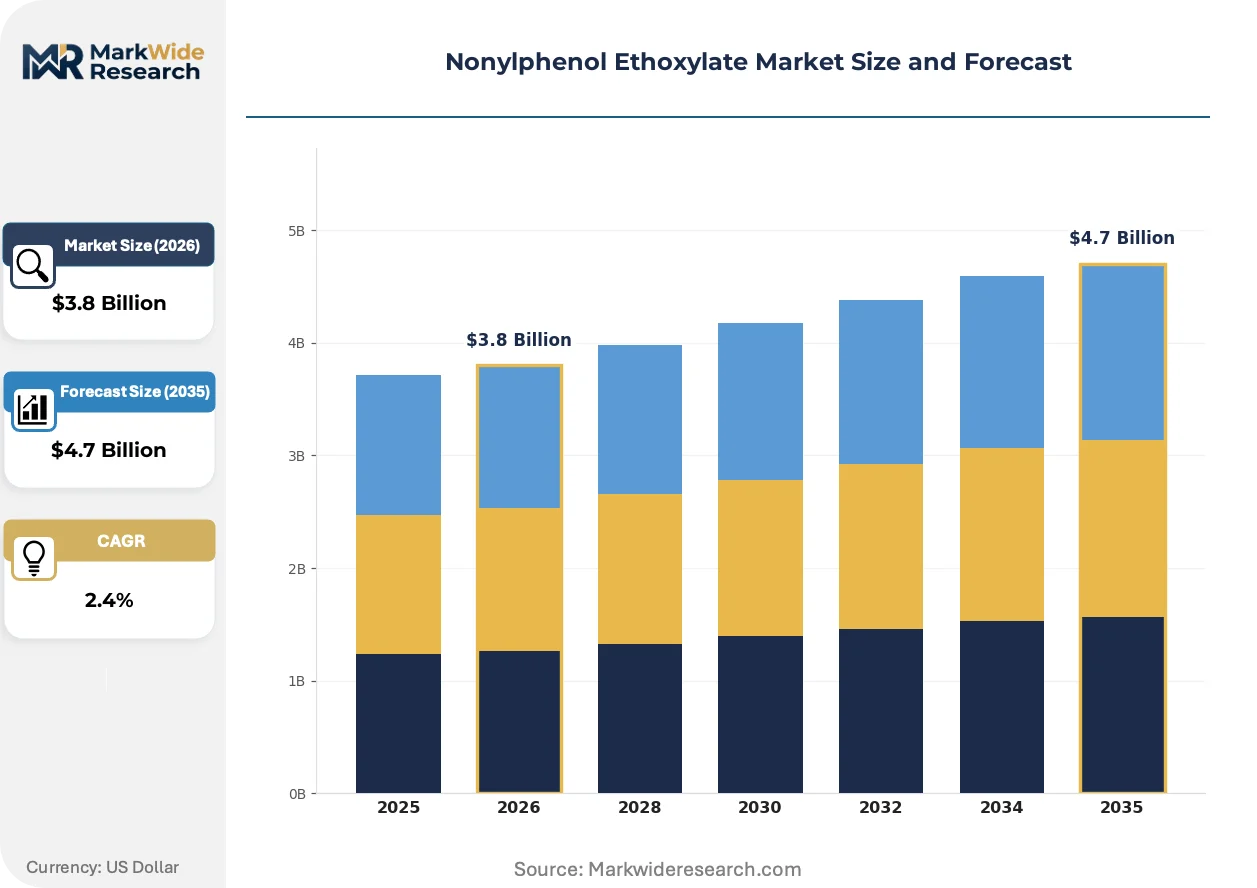
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NP-9, NP-10, NP-20, NP-30 Application: Household Cleaners, Industrial Degreasers, Paints, Textiles End User: Manufacturers, Chemical Processors, Retailers, Distributors Form: Liquid, Powder, Concentrate, Emulsion |
| Companies Covered | Dow Inc., India Glycols Limited, Oxiteno, Shree Vallabh Chemicals, Solvay, Stepan Company, LyondellBasell Industries, Borealis AG, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonylphenol Ethoxylate Market Strategic Shifts
Formulation chemistry is pivoting toward performance-optimized specialty grades as regulatory pressure eliminates commodity positioning, with technology investments concentrating on process control and application-specific functional design rather than volume scale.
Advanced ethoxylation catalyst systems are miniaturizing molecular weight distribution spans from traditional broad-spectrum outputs to tightly controlled ranges. Specialty chemical processors in Germany and Japan are adopting these systems to produce emulsion-grade nonylphenol ethoxylates with consistent cloud points for waterborne coatings. The technology is miniaturizing batch-to-batch variation, enabling just-in-time supply contracts that were previously impractical for surfactant procurement.
ECHA's REACH authorization timeline for nonylphenol ethoxylates in consumer applications is compressing viable product lifecycles for European formulators. Industrial cleaning compound manufacturers must accelerate alcohol ethoxylate substitution programs while maintaining equivalent detergency and wetting performance. Textile scouring operations in Portugal and Italy face the most acute transition pressure given their reliance on established nonylphenol-based process aids.
Buyers in China's textile belt are consolidating surfactant procurement around domestic producers with integrated ethylene oxide supply, displacing historical import dependence from Korean and Taiwanese suppliers. Zhejiang-based processors now specify local nonylphenol ethoxylate grades for polyester fabric scouring and dyeing auxiliaries. This geographic demand rotation is reshaping regional trade flows and forcing established exporters to reposition toward Southeast Asian emerging textile clusters.
Nonylphenol Ethoxylate Market Segmentation
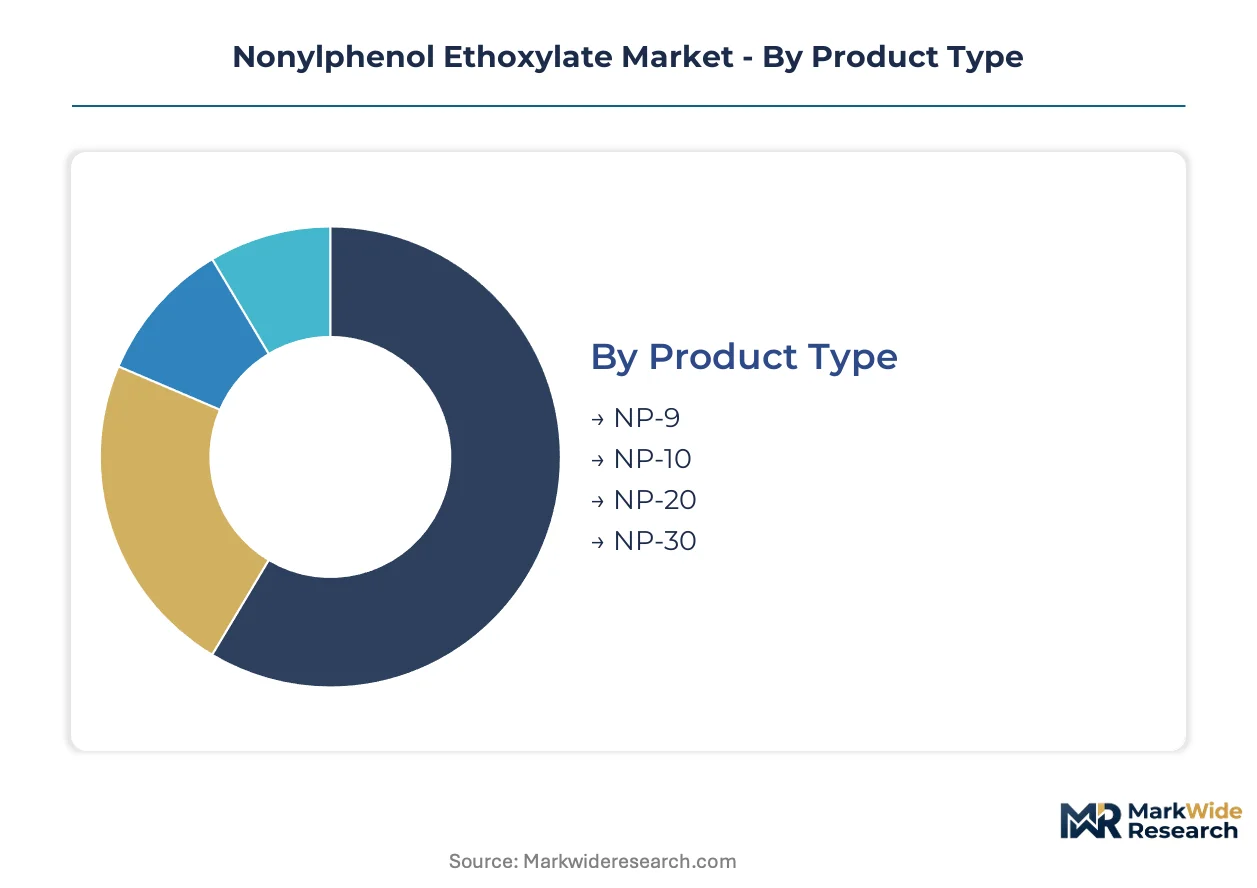
Nonylphenol ethoxylate procurement channels diverge sharply by segment, with industrial buyers favoring direct manufacturer relationships while consumer-facing applications route through formulated product distributors. Channel economics and regulatory handling requirements determine which segments flow through captive supply agreements versus merchant distribution networks.
Product Type:
Channel access varies by ethoxylation degree, with lower-EO grades moving through bulk chemical distributors and higher-EO variants requiring specialized handling infrastructure.
- NP-9:Moderate ethoxylation yields HLB values around 13, balancing hydrophilic and lipophilic properties for detergent formulations. Demand concentrates in textile scouring operations across China's Zhejiang province, where local processors specify NP-9 for polyester fabric preparation. REACH authorization pressures in Europe are compressing viable product lifecycles for this grade.
- NP-10:Slightly higher ethoxylation extends water solubility for precision cleaning applications. Automotive maintenance facilities in Germany specify NP-10 for automated degreasing systems, driven by residue-free performance requirements. ECHA's regulatory timeline is forcing substitution planning among European industrial compounders.
- NP-20:Extended ethoxylation chain produces high-HLB emulsifiers for waterborne coatings systems.
- NP-30:Maximum ethoxylation yields specialized dispersants for pigment grinding and suspension applications.
NP-9 dominates installed base. NP-10 is where expansion concentrates.
Application:
Cost tier stratification separates commodity household formulations from premium industrial specifications, with mid-tier paints and textiles occupying intermediate value positions.
- Household Cleaners:Standardized NP-9 formulations serve mass-market laundry and all-purpose cleaning products. Procurement in the United States routes through national retail distributors, with EPA state-level rules creating formulation complexity between Texas and California markets. Alcohol ethoxylate substitution is accelerating in this price-sensitive segment.
- Industrial Degreasers:High-performance NP-10 and NP-20 grades tolerate extreme soil loads in metal fabrication maintenance. Aerospace and automotive facilities in Japan specify these surfactants for precision component cleaning, driven by residue specifications and automated system compatibility. METI industrial chemical guidelines shape permissible formulations.
- Paints:Emulsion-grade nonylphenol ethoxylates stabilize waterborne architectural and industrial coatings.
- Textiles:Scouring and dyeing auxiliaries rely on NP-9 for polyester fabric preparation in processing clusters.
Household cleaners represent the largest volume outlet. Industrial degreasers are climbing the fastest as precision cleaning specifications tighten.
End User:
Customer type determines technical service intensity, with chemical processors demanding formulation support and retailers prioritizing supply reliability over technical engagement.
- Manufacturers:Captive ethoxylation facilities at integrated producers like Dow Inc. supply internal derivative production and external sales. These buyers optimize around feedstock cost stability and narrow ethylene oxide distribution curves for consistent HLB values.
- Chemical Processors:Specialty compounders blend nonylphenol ethoxylates into formulated cleaning and coatings products. Stepan Company's dedicated R&D facilities exemplify the technical service investment this segment demands for low-foam industrial variants.
- Retailers:Mass-market distributors handle packaged consumer cleaning products with standardized specifications.
- Distributors:Merchant chemical distributors serve small and mid-sized industrial accounts without direct manufacturer relationships.
Chemical processors command the highest service requirements. Manufacturers represent the steadiest volume commitment through captive supply structures.
Form:
Supply concentration favors liquid production for automated dosing compatibility, with powder and concentrate formats serving niche density and handling requirements.
- Liquid:Dominant commercial format enables precision injection in automated industrial and institutional cleaning systems. Solvay's emulsion-grade specialization targets waterborne coatings manufacturers with narrow-specification liquid products. Handling infrastructure requirements limit producer participation in premium liquid segments.
- Powder:Concentrated laundry and institutional cleaning compounds favor powder for shipping density and logistics cost reduction. China's domestic surfactant scale-up includes powder processing capacity for textile belt distribution.
- Concentrate:Dilution-at-use formats reduce packaging and transport expenditure for high-volume industrial accounts.
- Emulsion:Pre-dispersed formats serve coatings manufacturers requiring immediate incorporation without additional processing steps.
Liquid captures the broadest commercial penetration. Emulsion is gaining share fastest in European coatings manufacturing where just-in-time supply contracts are proliferating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated ethylene oxide supply chains concentrate manufacturing advantage in three countries with deep petrochemical infrastructure. Regulatory divergence between jurisdictions is fragmenting formulation standards and reshaping trade flows.
United States
Automotive maintenance facilities in Michigan and Ohio specify NP-10 grades for precision degreasing operations. EPA state-level rules in Texas and California create formulation complexity requiring product variants. Gulf Coast petrochemical corridors anchor captive ethylene oxide production serving domestic surfactant manufacturing.
Germany
Waterborne coatings manufacturers in Bavaria and North Rhine-Westphalia demand narrow-specification emulsion grades for architectural paint systems. ECHA REACH authorization timelines compress viable product lifecycles for industrial compounders. Frankfurt-Rhine-Main chemical clusters are accelerating alcohol ethoxylate substitution programs in textile scouring.
China
Textile processors in Zhejiang and Jiangsu provinces absorb rising NP-9 volumes for polyester fabric preparation. MEE wastewater discharge standards constrain manufacturing facility expansions in Yangtze River Delta production zones. Domestic surfactant scale-up is displacing historical import dependence from Korean suppliers.
Japan
Aerospace component cleaners in Aichi Prefecture specify residue-free NP-10 formulations for automated systems. METI industrial chemical guidelines shape permissible surfactant concentrations in metalworking fluids. Kansai manufacturing belt facilities prioritize batch-to-batch consistency for high-shear coolant applications.
Brazil
Institutional cleaning operations in São Paulo state specify liquid NP-9 formulations for automated dosing compatibility. ANVISA chemical substance regulations govern surfactant content in consumer-facing formulations. Southeast industrial corridors are consolidating procurement around merchant chemical distributors.
Nonylphenol Ethoxylate Market Competitive Environment
Concentration sits with integrated petrochemical conglomerates possessing captive ethylene oxide infrastructure. Merchant producers without upstream supply face structural cost disadvantages during feedstock volatility cycles. Two strategic archetypes dominate: backward-integrated multinational chemical groups and specialty surfactant houses with dedicated R&D facilities. Competitive moves center on ethoxylation catalyst system licensing and geographic repositioning toward Asia-Pacific demand clusters.
Within the integrated producer tier, Dow Inc. and LyondellBasell Industries exemplify scale-driven positioning through Gulf Coast ethylene oxide supply chains. Solvay occupies a position representing European emulsion-grade specialization for coatings manufacturers. Stepan Company anchors the specialty surfactant archetype with dedicated technical service capabilities for low-foam industrial variants. India Glycols Limited and Shree Vallabh Chemicals represent regional fabrication strength serving domestic textile belt demand.
| Leading Market Players |
|---|
| Dow Inc. |
| India Glycols Limited |
| Oxiteno |
| Shree Vallabh Chemicals |
| Solvay |
| Stepan Company |
| LyondellBasell Industries |
| Borealis AG |
| Huntsman Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between integrated ethylene oxide producers and specialty chemical processors lock in feedstock price visibility while securing volume allocation for NP-9 and NP-10 grades. These arrangements insulate captive supply chains from spot market volatility in Gulf Coast petrochemical corridors, though merchant buyers absorb price swings without upstream integration.
Pricing Analysis
Volume-discount tiering separates bulk industrial procurement from spot purchases in merchant channels. Three-tier pricing structure across premium emulsion grades, standard industrial formulations, and economy household variants reflects ethoxylation precision and certification overhead. Cost compression in economy tiers is intensifying because alcohol ethoxylate substitution programs in Europe are forcing price convergence. Household cleaner manufacturers exhibit highest price sensitivity, while aerospace compounders tolerate premiums for residue-free specifications.
Supply Chain Analysis
Inventory cycles stretch 6-8 weeks for liquid formulations moving through automated dosing systems, with powder grades extending lead times for bulk textile belt deliveries. Manufacturing concentrates in the United States, China, and Germany where integrated ethylene oxide infrastructure anchors surfactant output. Feedstock supply rests on naphtha crackers and dedicated ethylene oxide units, with catalyst systems and specialized handling equipment as secondary dependencies. Single-source vulnerability runs through Gulf Coast ethylene oxide corridors exposed to hurricane disruption. Distribution runs through direct manufacturer relationships for large chemical processors and merchant distributors for mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment protects incumbents: REACH authorization timelines and ECHA compliance burdens create switching costs that lock in qualified suppliers and repel unqualified challengers.
For Market Incumbents: Secure captive ethylene oxide supply through backward integration or long-term offtake arrangements to defend margin position against feedstock volatility. Deepen R&D investment in low-foam industrial variants and emulsion-grade specialization to create technical barriers against alcohol ethoxylate substitution threats in European coatings and textile applications. For New Entrants and Emerging Players: Differentiate on wastewater-compliant manufacturing processes that satisfy China's MEE discharge standards without legacy facility retrofit burdens. Target Southeast Asian textile clusters in Vietnam and Indonesia where import dependence from established Korean and Taiwanese suppliers creates white-space opportunity, and lead with just-in-time liquid formulation capabilities for automated dosing systems. For Investors and Strategic Acquirers: Regional surfactant specialists with integrated ethylene oxide supply and established textile belt relationships represent the most defensible acquisition profile. Long-term viability hinges on regulatory arbitrage capability across jurisdictions with divergent sunset timelines. Watch ECHA authorization enforcement patterns as the inflection signal for substitution acceleration or compliance extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Dow Inc.'s Gulf Coast infrastructure demonstrates feedstock cost stabilization against merchant price cycles. |
| Emulsion-Grade Specialization | Solvay's narrow-specification production serves Bavarian coatings manufacturers with just-in-time supply contracts. |
| Low-Foam Industrial Variant R&D | Stepan Company's dedicated facilities address machine tool coolant formulators seeking cavitation-resistant surfactants. |
| Long-Term Supply Agreement | Zhejiang textile processors consolidate procurement around domestic producers with integrated ethylene oxide supply. |
| Geographic Expansion to Southeast Asia | Established Korean exporters reposition toward Vietnamese and Indonesian textile clusters amid China's domestic scale-up. |
Study Parameters
Operator-level perspectives from plant managers at ethoxylation facilities, procurement leads at downstream textile and coatings manufacturers, distribution channel partners, and technical R&D directors anchored the qualitative base for this study. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates across the analysis window.
Sensitivity analysis tested forecast robustness against ethylene oxide feedstock volatility scenarios and regulatory acceleration cases. Segmentation dimensions modeled include ethoxylation degree, application end-use, formulation form, and regional production hub classification. CAGRs were derived from trend extrapolation adjusted for substitution elasticity and capacity expansion timelines. Industry-specific inputs incorporated REACH authorization sunset assumptions and China's MEE enforcement intensity projections.
Forecasts assume regulatory continuity in ECHA REACH implementation and EPA state-level enforcement; material policy shifts would require re-modeling across affected jurisdictions. Substitution technology cost curves and feedstock price cycles represent additional revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market