
 North America Molecular Sieve Market | 2026-2036
North America Molecular Sieve Market Size, Share, and Industry Trends Forecast 2026-2036
North America Molecular Sieve Market Analytics
Aftermarket regeneration services is rewriting margin allocation across the value chain. Honeywell International Inc leverages its captive fleet of adsorption units to lock in long-term service contracts. W. R. Grace & Co.-Conn. anchors its position through backward integration into zeolite powder synthesis. Zeolyst International specializes in custom catalyst formulations for refinery hydrogen purification.
A molecular sieve is a microporous crystalline aluminosilicate material with pore diameters typically ranging from 3 to 10 angstroms, engineered for selective adsorption based on molecular size and polarity. The synthetic zeolite segment dominates value capture due to precisely tunable pore architectures demanded by petrochemical separations. Natural molecular sieves retain cost advantages in bulk natural gas dehydration across Permian Basin operations. Bead and pellet forms command premium positioning where pressure drop minimization determines system economics.
EPA New Source Performance Standards and OSHA Process Safety Management rules mandate adsorbent replacement cycles and emissions containment protocols across US chemical facilities. The Department of Transportation PHMSA regulations govern molecular sieve packing standards for hazardous gas transport containers. Stakeholders must track evolving state-level carbon intensity benchmarks in California and Colorado that could redirect investment toward lower-energy regeneration technologies.
Market Dynamics
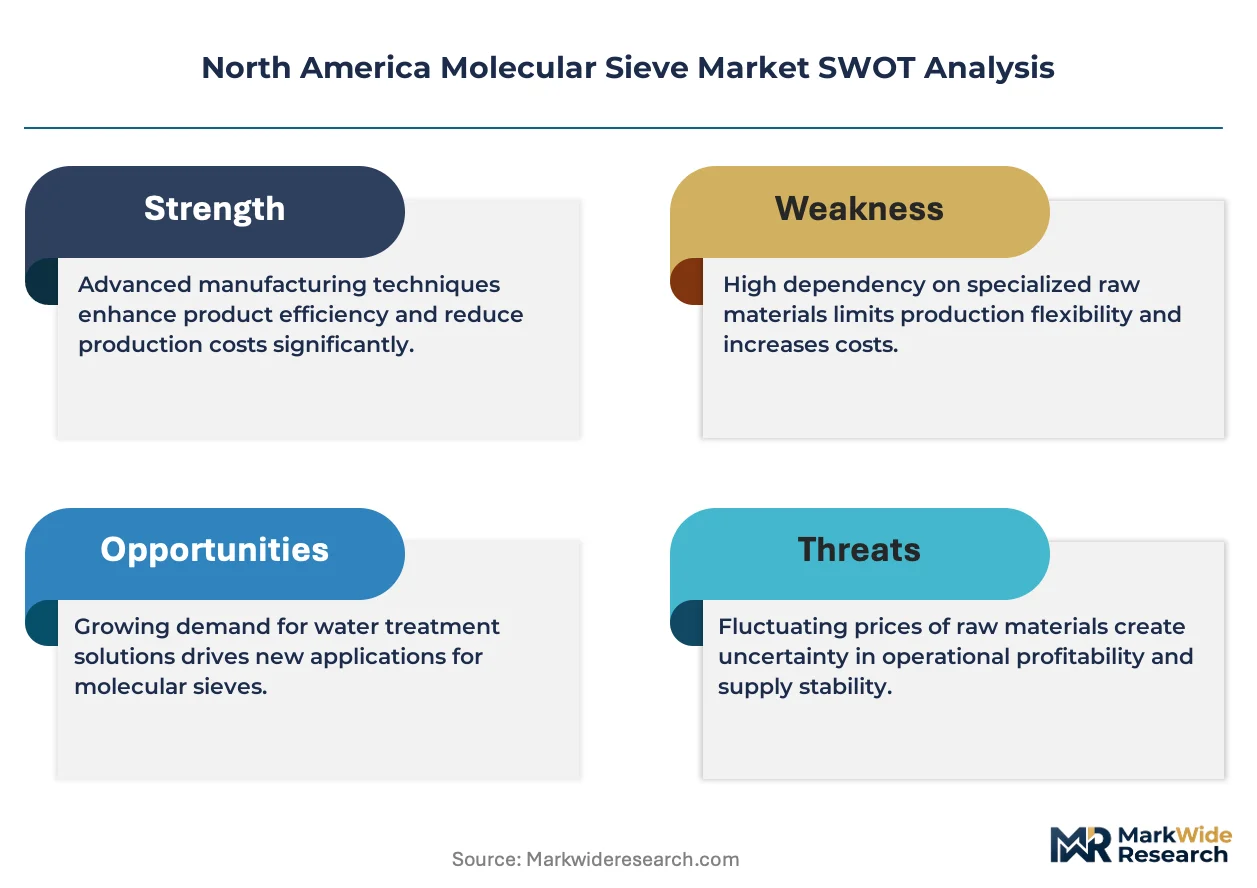
EPA New Source Performance Standards and OSHA Process Safety Management mandates are compressing adsorbent replacement cycles across Texas and Louisiana petrochemical corridors. Refiners face simultaneous pressure to cut emissions intensity while maintaining ethylene purification throughput.
Growth Catalysts
- Ethylene capacity expansion:Gulf Coast petrochemical complexes are commissioning new steam crackers requiring molecular sieve trains for feedstock dehydration. Louisiana facilities alone account for concentrated demand pull.
- OSHA PSM enforcement:Stricter Process Safety Management audits are mandating documented adsorbent integrity protocols. Chemical facilities must upgrade aging molecular sieve installations to meet containment standards.
- Permian Basin gas processing:Natural gas dehydration demand concentrates in West Texas operations where pipeline specifications require ultra-low water content. Natural zeolite cost advantages dominate this geography.
Market Restraints
- Zeolite powder supply concentration:Synthetic zeolite precursor manufacturing clusters in limited domestic production sites. Buyers face single-source risk for specialized powder grades.
- Energy-intensive regeneration:Thermal cycling requirements consume substantial natural gas input. Rising energy costs compress operating margins for continuous adsorption units.
- Silica gel substitution:Natural gas dehydration applications in marginal wells increasingly specify silica gel for initial drying stages. Cost-sensitive operators accept performance trade-offs.
Strategic Opportunities
- Canadian oil sands upgrading:Alberta heavy oil facilities underutilize molecular sieve purification for synthetic crude conditioning. Regulatory pressure on sulfur content creates specification openings.
- Hydrogen economy infrastructure:Gulf Coast hydrogen hub development requires ultra-high purity standards. PSA molecular sieve systems for fuel cell-grade hydrogen represent emerging specification tier.
- Electric regeneration technology:Microwave and radio-frequency regeneration methods reduce thermal energy dependence. Technology convergence with renewable power sourcing aligns with Colorado and California carbon intensity benchmarks.
Industry Challenges
- Zeolite synthesis expertise scarcity:Formulation chemists with aluminosilicate crystallization experience command premium compensation. Workforce development lags behind capacity expansion timelines.
- Legacy unit integration complexity:Brownfield petrochemical sites require molecular sieve retrofits compatible with existing pressure vessel footprints. Custom engineering extends project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Molecular Sieve Market |
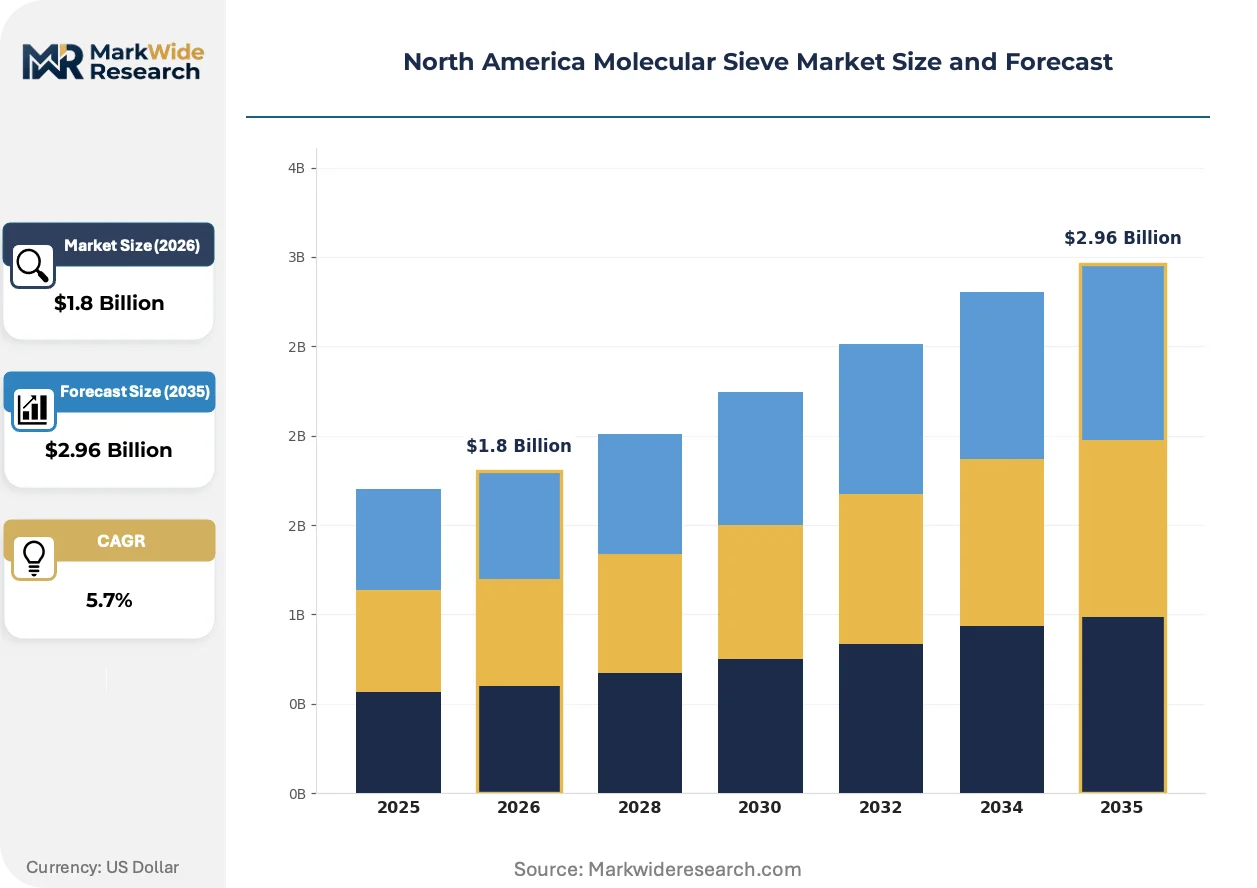
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Zeolite, Activated Alumina Application: Petrochemicals, Air Separation, Natural Gas, Environmental End User: Oil & Gas, Chemical, Water Treatment, Automotive Form: Granules, Pellets, Powder, Beads |
| Companies Covered | Honeywell International Inc, Arkema Group, Zeochem, W. R. Grace & Co.-Conn., Tosoh Corporation, BASF SE, Clariant, Cabot Corporation, Zeolyst International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Molecular Sieve Market Evolving Landscape
Adsorbent technology is converging with process intensification engineering to reduce regeneration energy loads. Refiners now specify molecular sieve systems as integrated purification modules rather than commodity replacements.
Lithium-exchanged zeolite formulations is hybridizing traditional 3A and 4A separations into single-unit operations. Ethylene producers in Texas are piloting these materials to consolidate dehydration and co-adsorption steps. The technology is compressing vessel count and regeneration frequency in grassroots plant designs.
EPA enforcement of New Source Performance Standards for petrochemical facilities is tightening volatile organic compound containment requirements. Adsorbent replacement protocols must now document fugitive emission prevention during changeout operations. Louisiana refiners are responding by specifying closed-loop handling systems for molecular sieve loading.
Service contracting is displacing spot procurement for molecular sieve changeout and regeneration. Large Gulf Coast petrochemical operators now bundle adsorbent supply with turnkey replacement services. This shift concentrates procurement authority with integrated service providers rather than distributed maintenance teams.
North America Molecular Sieve Market Segmentation
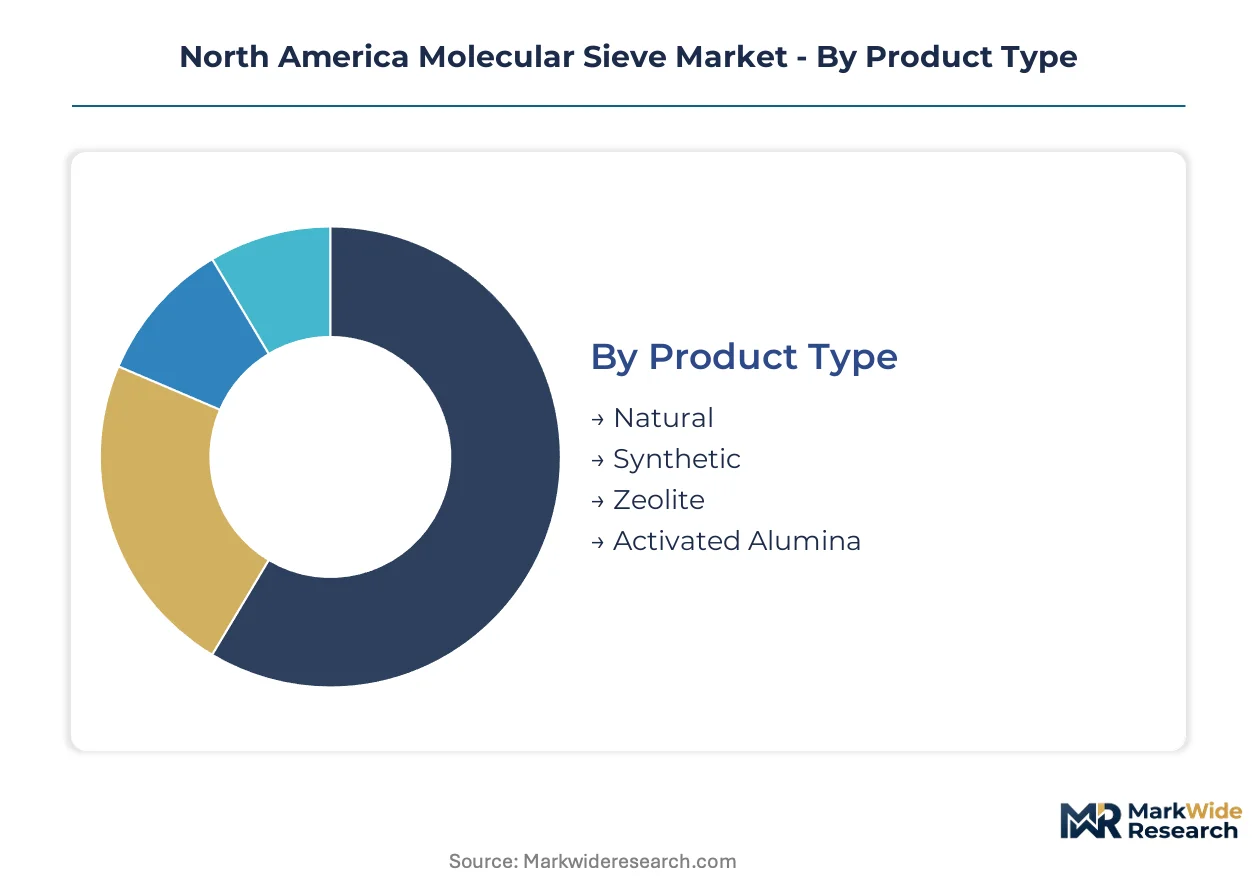
Molecular sieve segmentation reflects divergent technical requirements across North American energy infrastructure. Product chemistry, physical form, and end-use specifications each create distinct procurement patterns and margin structures for suppliers.
Product Type:
Mature synthetic formulations dominate petrochemical value capture while natural variants retain cost advantages in bulk dehydration.
- Synthetic:Manufactured aluminosilicate crystals with precisely engineered pore architectures from 3 to 10 angstroms. Texas and Louisiana ethylene producers specify synthetic grades for co-adsorption of water and polar contaminants in high-throughput crackers. OSHA Process Safety Management documentation requirements favor synthetic consistency over natural variability.
- Zeolite:Crystalline microporous structures enabling molecular-level selectivity based on size and polarity. Gulf Coast refiners deploy lithium-exchanged zeolite formulations to consolidate dehydration and purification steps into single-unit operations. EPA New Source Performance Standards enforcement tightens performance tolerances that zeolite chemistry satisfies.
- Natural:Mined aluminosilicate deposits with broader pore distribution and lower unit costs. Permian Basin gas processors specify natural molecular sieves for pipeline dehydration where ultra-precise selectivity is secondary to throughput economics.
- Activated Alumina:High-surface-area aluminum oxide for applications requiring fluoride resistance or thermal stability. Water treatment facilities in Colorado specify activated alumina for arsenic removal under state-level contaminant mandates.
Synthetic zeolite handles the majority of throughput; lithium-exchanged formulations are gaining share fastest in grassroots petrochemical designs.
Application:
Cost tier separation runs from premium petrochemical separations to commoditized environmental remediation.
- Petrochemicals:Ethylene and propylene purification requiring sub-ppm moisture levels to prevent catalyst poisoning. Louisiana steam cracker expansions drive concentrated demand for 3A and 4A molecular sieve trains. Regeneration energy costs compress margins for operators without integrated utility sourcing.
- Natural Gas:Dehydration to meet pipeline water content specifications across West Texas and Appalachian production basins. Silica gel substitution pressure intensifies in marginal well economics where initial capital outlay dominates lifecycle cost.
- Air Separation:Pressure swing adsorption systems for oxygen and nitrogen production. Medical and industrial gas facilities in the US Midwest specify molecular sieve 13X for high-purity nitrogen generation.
- Environmental:Volatile organic compound recovery and hazardous gas containment. California refiners deploy carbon-molecular-sieve hybrids to meet South Coast Air Quality Management District emission limits.
Petrochemicals commands the premium pricing tier; environmental applications show the steepest expansion trajectory under tightening EPA enforcement.
End User:
Customer type determines procurement authority concentration versus distributed maintenance decision-making.
- Oil & Gas:Integrated majors and midstream operators with centralized engineering standards. Permian Basin and Gulf Coast operations bundle molecular sieve supply with regeneration service contracts to lock in lifecycle cost predictability.
- Chemical:Specialty and commodity chemical producers with process-specific adsorbent requirements. Texas and Louisiana facilities face simultaneous pressure from OSHA PSM audits and EPA emission containment mandates.
- Water Treatment:Municipal and industrial facilities specifying adsorbents for contaminant removal. Colorado and California utilities track emerging state carbon intensity benchmarks that could redirect investment toward lower-energy regeneration technologies.
- Automotive:Fuel cell and battery manufacturing requiring ultra-high purity process gases. Gulf Coast hydrogen hub development creates emerging specification tier for PSA molecular sieve systems in fuel cell-grade hydrogen production.
Oil & Gas concentrates procurement volume; automotive end-use is climbing the fastest as hydrogen infrastructure scales.
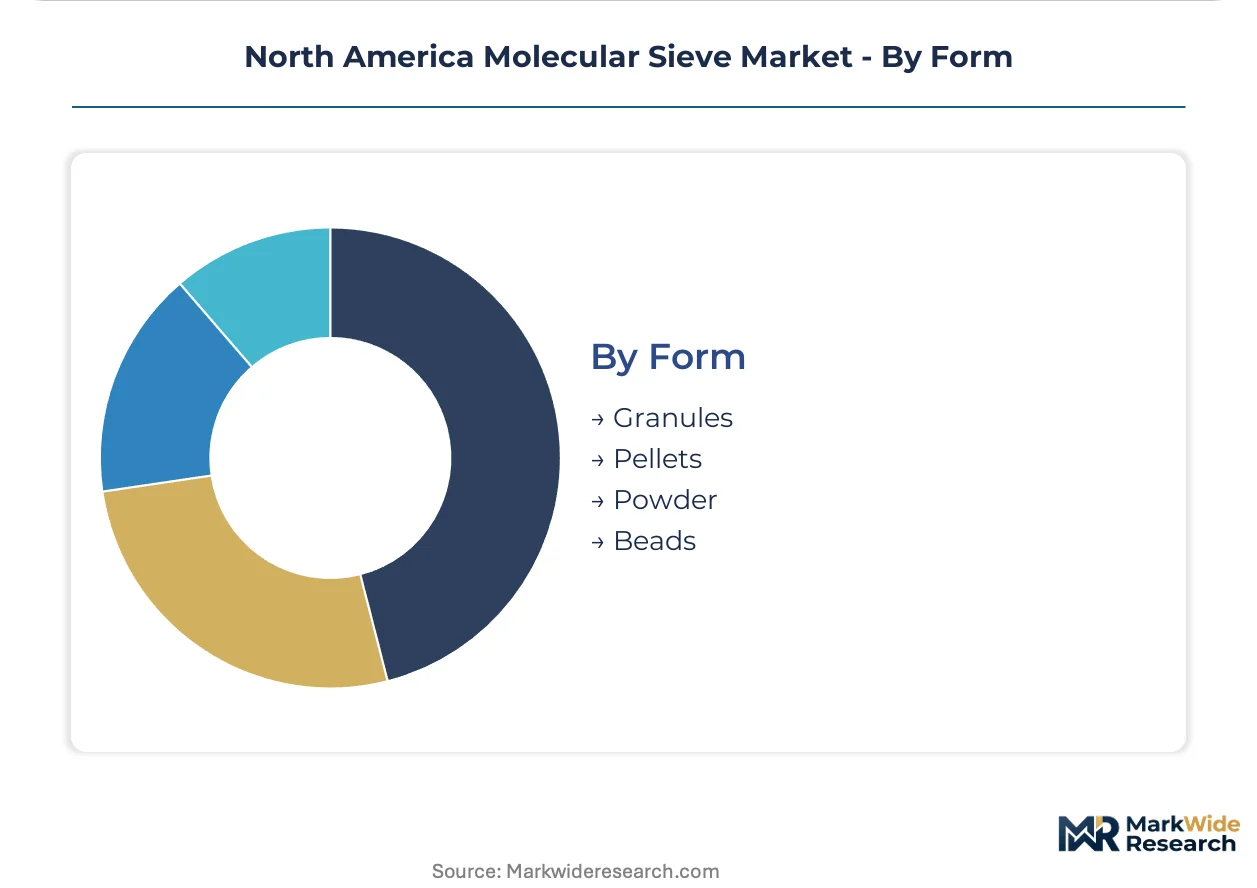
Form:
Physical configuration directly determines pressure drop economics and vessel design constraints.
- Beads:Spherical morphology minimizing attrition and pressure drop in cyclic adsorption systems. Gulf Coast petrochemical operators specify bead form for high-frequency regeneration cycles where mechanical integrity determines replacement intervals.
- Pellets:Extruded cylindrical shape balancing surface area with structural strength. Natural gas dehydration units across the Permian Basin deploy pellets for fixed-bed applications with moderate pressure drop tolerance.
- Granules:Irregular particulate form for bulk fill applications where packing density is secondary to cost. Initial drying stages in marginal well operations specify granules for capital-constrained deployments.
- Powder:Fine particulate requiring binder incorporation for structured applications. Zeolite powder supply concentration in limited domestic production sites creates single-source risk for specialized grades.
Beads capture the majority of premium positioning; pellet form is expanding most quickly in midstream gas processing standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic zeolite precursor manufacturing clusters in limited domestic production sites across the continent. Buyers face single-source risk for specialized powder grades. Demand concentrates in petrochemical corridors and gas processing basins.
United States
Gulf Coast petrochemical complexes in Texas and Louisiana drive concentrated demand for ethylene purification systems. EPA New Source Performance Standards and OSHA Process Safety Management rules mandate documented adsorbent integrity protocols. Louisiana steam cracker expansions account for disproportionate procurement volume in grassroots molecular sieve installations.
Canada
Alberta heavy oil facilities underutilize molecular sieve purification for synthetic crude conditioning. Regulatory pressure on sulfur content from Environment and Climate Change Canada creates specification openings for adsorbent upgrades. Calgary-area upgrading facilities represent untapped demand for dehydration and contaminant removal systems.
Mexico
Pemex refinery modernization programs specify molecular sieve trains for fuel gas dehydration and hydrogen purification. Mexican energy reform implementation attracts private petrochemical investment requiring adsorption technology. Altamira and Coatzacoalcos industrial corridors emerge as procurement nodes for Gulf Coast supply chain integration.
North America Molecular Sieve Market Competitive Landscape
Integrated service providers and specialized powder manufacturers split the market into distinct competitive domains. The vendor base organizes around captive regeneration capabilities versus backward integration into zeolite synthesis. Three archetypes dominate: multinational conglomerates with bundled service contracts, mid-cap specialists in custom catalyst formulations, and regional players competing on natural zeolite cost structures. Capacity expansion in Gulf Coast corridors and technology licensing for electric regeneration methods represent the dominant competitive vectors.
Among North American-based multinationals, Honeywell International Inc exemplifies the integrated service archetype through captive adsorption unit fleets. W. R. Grace & Co.-Conn. anchors the backward-integrated tier with in-house zeolite powder production capabilities. Zeolyst International occupies the specialist position in custom catalyst formulations for refinery hydrogen applications. These three entities collectively represent the strategic positioning spectrum available to market participants.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Arkema Group |
| Zeochem |
| W. R. Grace & Co.-Conn. |
| Tosoh Corporation |
| BASF SE |
| Clariant |
| Cabot Corporation |
| Zeolyst International |
| Others |
Value Network & Pricing Analysis
Gulf Coast zeolite powder undercapacity is tightening supplier leverage and compressing procurement timelines for Texas and Louisiana petrochemical operators. This utilization squeeze feeds directly into pricing posture, with buyers accepting premium positioning to secure synthetic molecular sieve allocations amid OSHA-mandated replacement cycles.
Pricing Analysis
EPA New Source Performance Standards dictate the pricing tier structure across North American molecular sieve procurement. Contract-based long-term offtake dominates, with pricing stratifying across premium synthetic grades, standard natural zeolite, and economy silica gel alternatives. Certification to OSHA Process Safety Management documentation requirements drives the widest spreads, while energy-intensive regeneration costs intensify margin pressure on continuous adsorption units. Natural gas dehydration operators in marginal Permian Basin wells exhibit highest price sensitivity; Gulf Coast ethylene producers show lowest, prioritizing throughput reliability over unit economics.
Supply Chain Analysis
Extended payment terms from integrated service providers are restructuring working capital requirements for downstream buyers. Synthetic zeolite precursor manufacturing concentrates in the United States, with limited domestic production sites drawing from bauxite-derived alumina and silica feedstocks. Zeolite powder supply rests on single-source vulnerability for specialized grades. Distribution runs through captive regeneration fleets and regional distribution hubs serving Texas and Louisiana petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with aluminosilicate crystallization expertise command premium compensation that outstrips workforce development pipelines, constraining capacity expansion timelines across the value chain.
For Market Incumbents: Insulate margin position through backward integration into zeolite powder synthesis and captive regeneration fleet expansion. Lock in long-term service contracts with Gulf Coast petrochemical operators facing compressed OSHA PSM audit schedules. Counter silica gel substitution pressure in natural gas dehydration by bundling adsorbent supply with documented emissions containment protocols. For New Entrants and Emerging Players: Alberta heavy oil upgrading facilities represent geographic underpenetration with specification openings driven by Environment and Climate Change Canada sulfur content mandates. Target Calgary-area synthetic crude conditioning installations with dehydration and contaminant removal systems. Lead with electric regeneration technology offerings aligned with Colorado and California carbon intensity benchmarks to differentiate from incumbent thermal-cycling infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers with captive adsorption unit fleets. Long-term viability across the analysis window favors backward-integrated specialists with in-house zeolite powder production capabilities. Monitor EPA enforcement intensity for New Source Performance Standards as the inflection indicator for accelerated replacement cycle demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Powder Synthesis | W. R. Grace & Co.-Conn. anchors competitive positioning through captive precursor manufacturing. |
| Electric Regeneration Technology Licensing | Microwave and radio-frequency methods align with Colorado and California carbon intensity mandates. |
| Long-term Service Contract Bundling | Honeywell International Inc leverages captive fleets to lock in lifecycle procurement authority. |
| Custom Catalyst Formulation Specialization | Zeolyst International targets refinery hydrogen purification with application-specific designs. |
| Closed-loop Handling System Specification | Louisiana refiners deploy EPA-compliant changeout protocols to meet fugitive emission requirements. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with molecular sieve procurement leads at Gulf Coast petrochemical facilities, plant engineers at Permian Basin gas processing operations, and technical R&D directors at zeolite manufacturers; and secondary validation through EPA enforcement records, OSHA Process Safety Management audit disclosures, SEC 10-K filings from listed suppliers, and American Chemistry Council trade data. Bottom-up volume estimates from end-use application sizing were triangulated against top-down supplier capacity assessments.
Forecast inputs included capacity utilization rates at domestic zeolite powder production sites, ethylene cracker expansion timelines across Texas and Louisiana, and regulatory enforcement intensity for EPA New Source Performance Standards. Segmentation modeling covered product chemistry tiers, physical form specifications, end-use industry verticals, and regional production hub clusters. CAGRs were derived from trend extrapolation of historical procurement patterns and projected replacement cycle compression under tightening OSHA mandates.
Practitioners should monitor zeolite synthesis workforce development gaps, electric regeneration technology cost curves, and state-level carbon intensity benchmark adoption for early signals of structural shift. Forecasts reflect assumptions about regulatory enforcement continuity and energy cost trajectories; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Global Antifreeze Market