
 Synthetic Wax Market | 2026-2036
Synthetic Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Wax Market Analytics
Specialty coatings formulators are rotating share toward synthetic waxes as automotive OEMs phase out solvent-heavy systems. BASF SE leverages its integrated Fischer-Tropsch feedstock position in Ludwigshafen to secure supply continuity for European coating houses. Sasol anchors its competitiveness through captive gas-to-liquids output in South Africa, while Clariant AG differentiates via micronized polyethylene wax grades tailored for powder coating applications.
Synthetic wax denotes hydrocarbon or ester-based materials engineered through polymerization, Fischer-Tropsch synthesis, or petroleum refining to achieve controlled melting points between 50°C and 150°C and narrow molecular weight distribution, serving primarily as surface modifiers, lubricants, and barrier agents in formulated products. Polyethylene wax dominates volume owing to its cost position in PVC processing and masterbatch lubrication, while Fischer-Tropsch wax captures expanding margin pools in high-performance coatings where low viscosity and excellent hardness prove critical. Industrial grade material remains the largest revenue block, though cosmetic grade segments attract premium pricing as personal care brands reformulate around vegan and consistent supply claims.
REACH registrations in Europe and FDA food-contact notifications in the United States govern monomer residuals and migration limits, compelling producers to invest in hydrogenation depth and catalyst selectivity. China's GB standards for food packaging and Japan's METI chemical substance classifications add compliance layers for exporters serving Asia-Pacific formulation houses. Stakeholders must monitor regulatory divergence on microplastic definitions, as pending restrictions in the European Union could reclassify certain polyethylene wax particles and force substitution toward biosynthetic or FT-derived alternatives.
Market Dynamics
Fischer-Tropsch synthesis capacity expansion is compressing supply lead times for high-purity wax grades while REACH compliance costs filter out smaller European compounders. This dual squeeze is redrawing competitive boundaries between integrated producers and toll manufacturers.
Growth Catalysts
- Fischer-Tropsch Capacity Expansion:Gas-to-liquids investments in South Africa and the Middle East are expanding feedstock availability for coating-grade synthetic waxes with sub-5 ppm sulfur content.
- REACH Phase-In Substances:ECHA's 2023-2028 registration deadlines for low-volume chemicals are accelerating substitution of unregistered petroleum wax blends with documented synthetic alternatives in EU adhesive formulations.
- Powder Coating Migration:Automotive refinishing shops in Germany and the United States are converting solvent lines to powder systems, pulling micronized polyethylene wax demand for flow control and degassing.
Market Restraints
- Ethylene Feedstock Volatility:Naphtha-cracker economics in Northeast Asia swing polyethylene wax production costs by 15-25 percent quarterly, compressing margin visibility for non-integrated compounders.
- South African Supply Concentration:Over half of global Fischer-Tropsch wax exports originate from Secunda and Mossel Bay, exposing coating formulators to logistics disruptions at the Cape of Good Hope route.
- Microplastic Regulatory Uncertainty:Pending ECHA restriction proposals on intentionally added microplastics threaten reclassification of certain polyethylene wax dispersions in personal care and coating applications.
Strategic Opportunities
- India Industrial Coatings:BIS certification mandates for architectural paints are creating first-mover advantages for synthetic wax suppliers offering pre-documented impurity profiles to domestic formulators.
- Bio-Based Fischer-Tropsch:Biomass gasification routes using forestry residue are enabling carbon-negative wax claims for cosmetic brands targeting EU Green Deal procurement criteria.
- Direct E-Commerce Channels:Specialty distributors in the United States are launching digital platforms for kilogram-scale synthetic wax sampling, compressing qualification cycles for independent coating labs.
Industry Challenges
- Hydrogenation Catalyst Expertise:Deep hydrogenation for food-contact compliance requires rare-metal catalyst management skills that command 40 percent wage premiums over standard petrochemical operations.
- Multi-Jurisdiction Certification Lag:Simultaneous FDA food-contact notification, REACH registration, and China's GB standard testing extends product launch timelines by 18-24 months for global wax suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Wax Market |
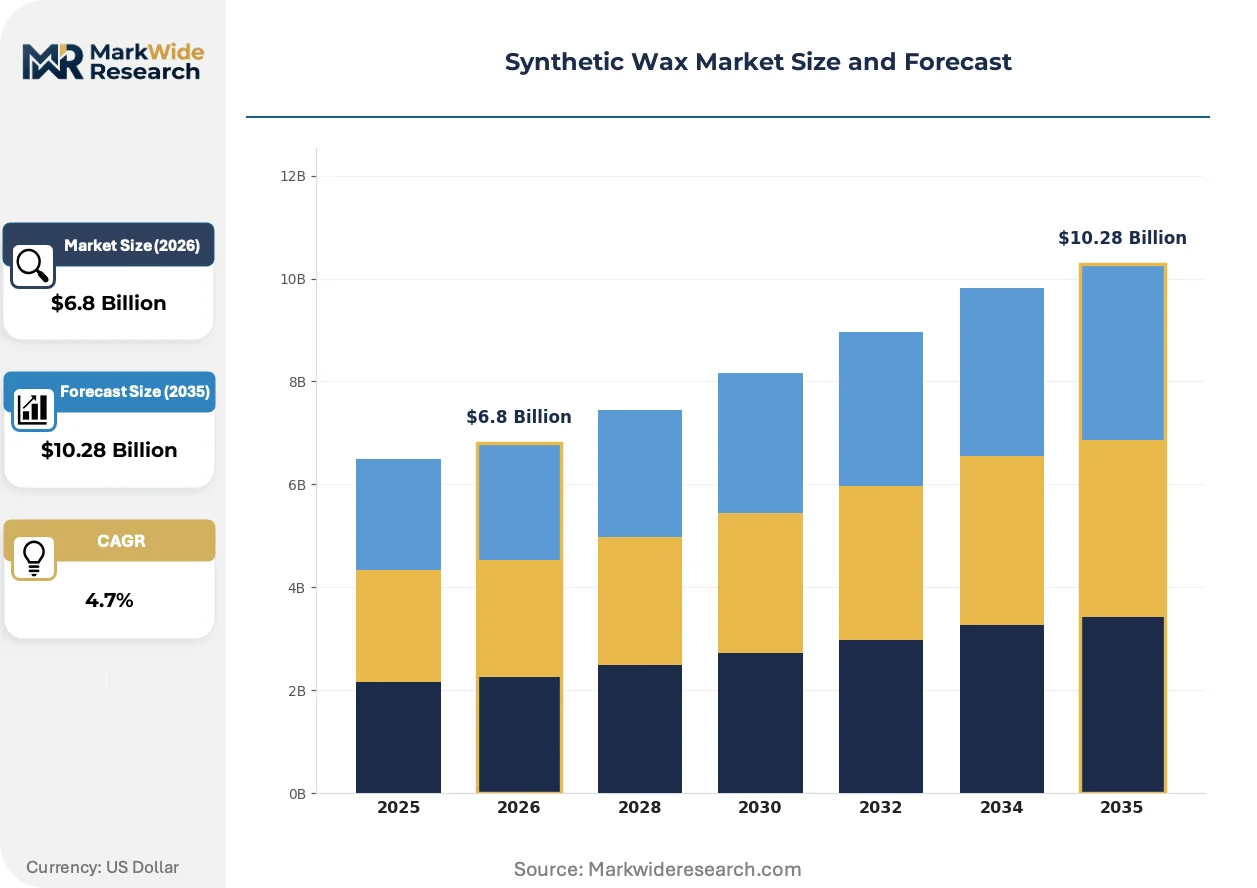
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
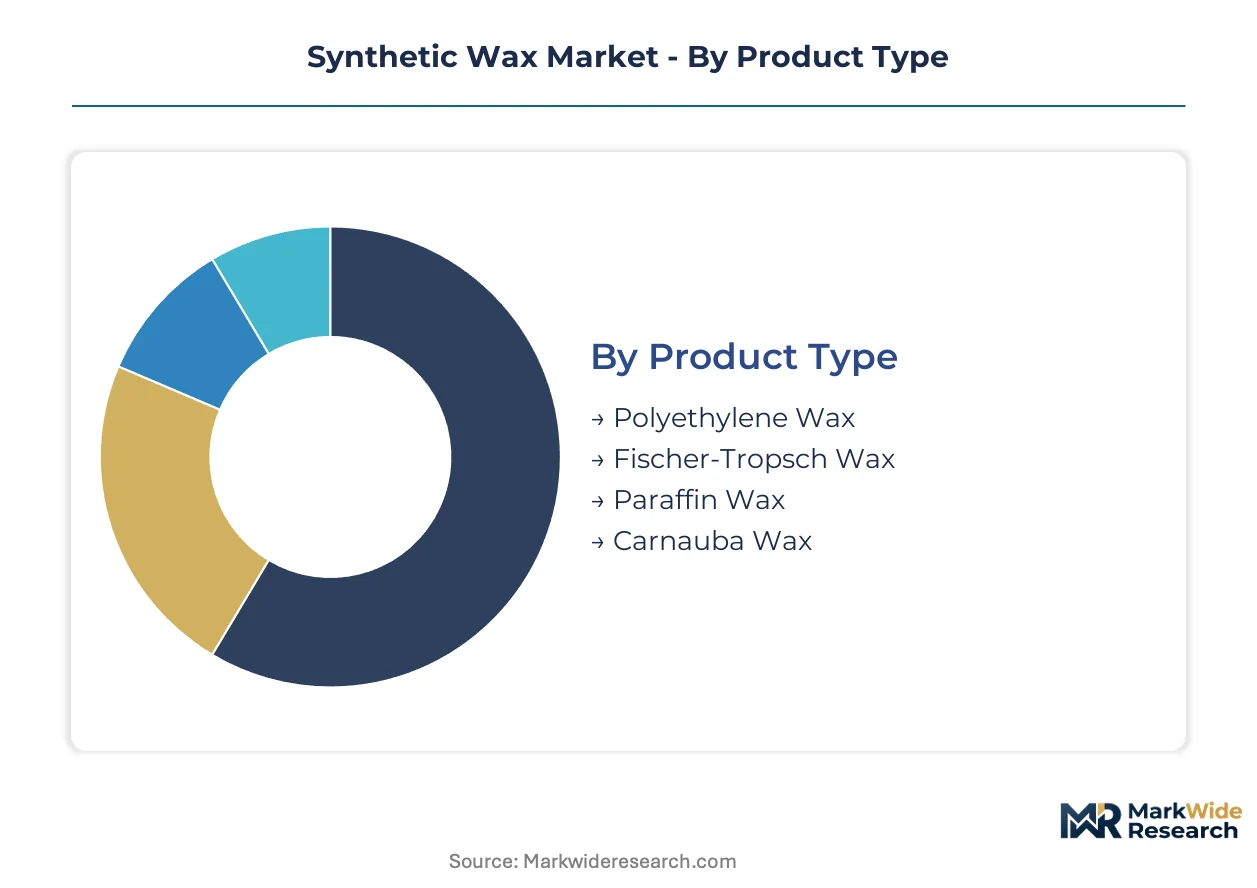
| Segmentation | Product Type: Polyethylene Wax, Fischer-Tropsch Wax, Paraffin Wax, Carnauba Wax Application: Coatings, Cosmetics, Food Packaging, Adhesives Grade: Industrial Grade, Food Grade, Cosmetic Grade, Pharmaceutical Grade End Use Industry: Paints, Personal Care, Food & Beverage, Textiles |
| Companies Covered | BASF SE, Clariant AG, Sasol, Evonik Industries AG, Honeywell International Inc., Mitsui Chemicals, Inc., Eastman Chemical Company, The Lubrizol Corporation, Westlake Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Wax Market Evolving Landscape
Digital formulation platforms are compressing R&D cycles for wax-modified coatings while regulatory transparency requirements pull blockchain-enabled supply chain documentation into mainstream procurement specifications.
Micronization technology is bifurcating the polyethylene wax segment into coarse-cut grades for commodity PVC lubrication and sub-10-micron fractions commanding 3x premiums in automotive clearcoat applications. Tier-one automotive refinish suppliers in Germany and Japan are locking in multi-year offtake for the ultrafine fraction. This particle-size stratification is compressing margin pools in standard-grade masterbatch markets while concentrating profitability in coating-specialty channels.
REACH microplastic restriction proposals are forcing reformulation of personal care waxes ahead of final ECHA determinations. Cosmetic brands are accelerating qualification of Fischer-Tropsch and bio-based alternatives to polyethylene-derived opacifiers. The regulatory uncertainty is freezing capital allocation for new polyethylene wax capacity in Europe while redirecting investment toward gas-to-liquids expansion.
Coating houses are consolidating supplier panels from 12-15 wax vendors to 3-4 strategic partners with integrated documentation capabilities. Procurement teams in the United States are embedding FDA food-contact and EPA TSCA compliance data directly into e-procurement platforms. This vendor rationalization is most advanced in Midwest industrial coating clusters, where qualification costs now exceed annual material spend for mid-volume accounts.
Synthetic Wax Market Segmentation
Synthetic wax procurement patterns diverge sharply by segment, with coating-grade Fischer-Tropsch wax commanding premium logistics networks while polyethylene wax flows through commodity distribution channels. Grade certification requirements further stratify supplier relationships, as food-contact and cosmetic applications demand documented purity chains that industrial buyers rarely require.
Product Type:
Domestic production of polyethylene wax concentrates in Northeast Asian crackers serving regional PVC compounders, while Fischer-Tropsch grades move through South African and Middle Eastern export terminals to European and North American coating houses. Paraffin wax sourcing remains fragmented across petroleum refiners in the United States, Germany, and Saudi Arabia.
- Polyethylene Wax:Polymerized ethylene chains with molecular weights between 2,000 and 10,000 daltons provide lubrication in PVC processing and masterbatch dispersion. Demand clusters in China where domestic pipe and profile extruders upgrade formulation standards under stricter GB specifications for construction materials.
- Fischer-Tropsch Wax:Saturated linear hydrocarbons synthesized from syngas deliver narrow polydispersity and sub-5 ppm sulfur content for high-performance coatings. German automotive refinish suppliers and Japanese clearcoat formulators anchor import demand for ultrapure grades with controlled crystallization behavior.
- Paraffin Wax:Petroleum-derived alkanes with carbon chain lengths from C20 to C40 serve candle manufacturing and food coating applications in the United States and India.
- Carnauba Wax:Natural exudate from Brazilian palm leaves provides hardness and gloss in premium cosmetic and food glazing formulations subject to vegan labeling requirements.
Polyethylene wax holds the largest share; momentum sits with Fischer-Tropsch wax as coating formulators phase out solvent-heavy systems.
Application:
Margin structures vary threefold across applications, with cosmetics and food packaging justifying certification investments that coatings buyers amortize across volume contracts. Procurement centralization is most advanced in coatings, where automotive OEMs consolidate qualified supplier lists to under five vendors per region.
- Coatings:Powder and liquid formulations employ micronized wax for flow control, matting, and scratch resistance. German industrial paint producers and United States automotive refinishing shops drive specification tightening around VOC compliance and surface durability metrics.
- Cosmetics:Lipstick, cream, and lotion formulations utilize wax as structure agents and emulsion stabilizers. European personal care brands accelerate substitution away from polyethylene-derived opacifiers ahead of ECHA microplastic restriction determinations.
- Food Packaging:Coatings and laminates require FDA food-contact notification or EFSA compliance for direct food contact. Migration limits on monomer residuals compel hydrogenation depth investments that filter out smaller compounders.
- Adhesives:Hot-melt and pressure-sensitive systems incorporate wax for viscosity modification and open-time control. REACH registration deadlines for low-volume chemicals accelerate substitution of unregistered petroleum wax blends with documented synthetic alternatives in EU formulation houses.
Coatings generate the highest absolute revenue; cosmetics and food packaging are climbing the fastest as certification premiums expand addressable pricing.
Grade:
Certification intensity determines supplier economics, with pharmaceutical and food grades requiring 18-24 month multi-jurisdiction approval timelines that industrial grades bypass entirely. Wage premiums for hydrogenation catalyst expertise concentrate in facilities serving regulated grades.
- Industrial Grade:Standard purity waxes for lubrication, processing aids, and general coatings without food-contact or dermal exposure requirements. Chinese PVC compounders and Indian textile processors anchor volume demand at cost-optimized specification levels.
- Food Grade:Hydrogenated products meeting FDA food-contact notification and EFSA migration limits for direct and indirect food contact. United States confectionery coating and European dairy laminate producers enforce batch-level documentation of monomer residuals and catalyst residues.
- Cosmetic Grade:Purified and often micronized waxes meeting ISO 16128 natural origin claims or vegan certification standards. Japanese and South Korean skincare formulators drive sub-10-micron particle size requirements for sensorial performance.
- Pharmaceutical Grade:Highest purity tier for excipient and topical drug delivery applications subject to USP-NF or EP monograph compliance. Limited qualified supply concentrates in German and Swiss chemical manufacturing sites with dedicated GMP wax finishing lines.
Industrial grade dominates volume; pharmaceutical grade commands the steepest expansion trajectory as topical drug delivery formulations multiply.
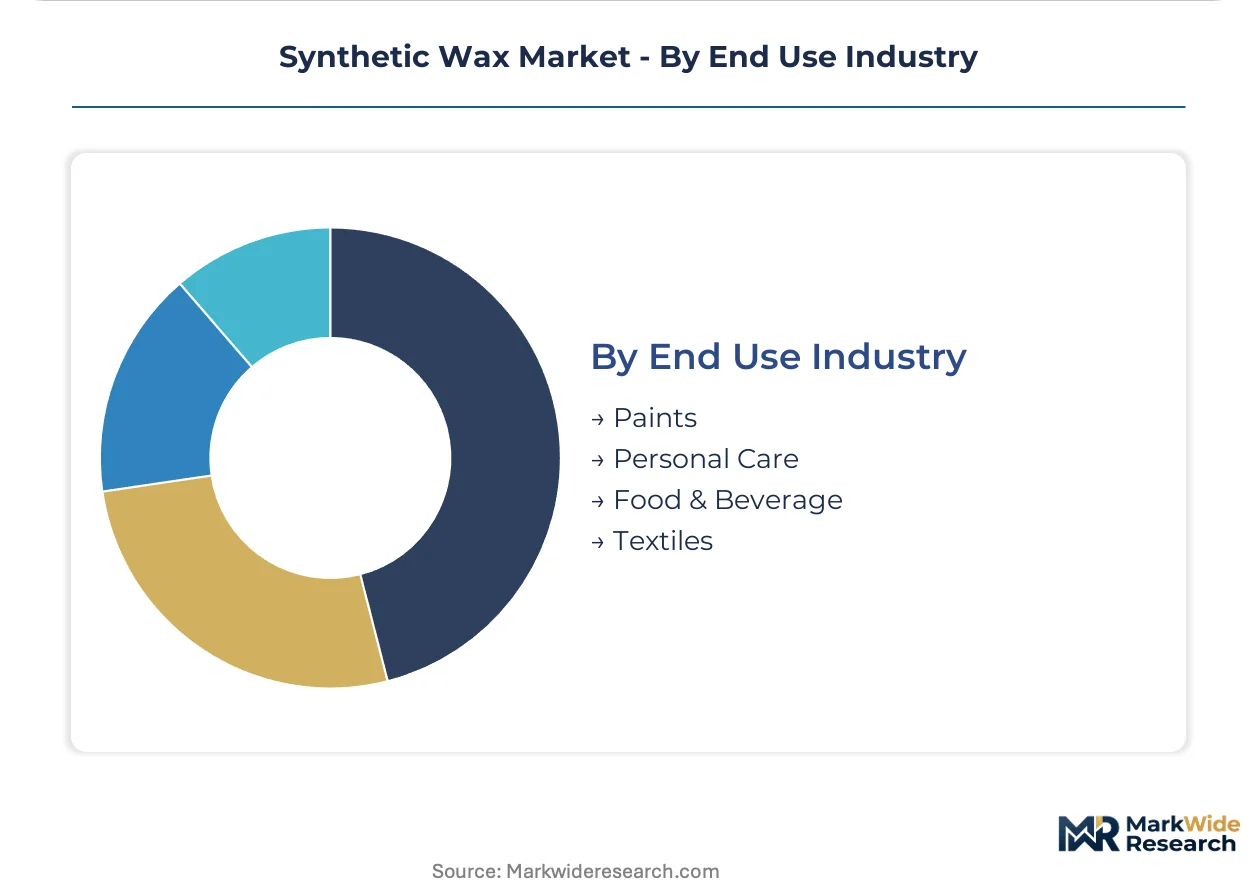
End Use Industry:
Customer technical capability shapes procurement patterns, with paints and personal care demanding collaborative formulation development while food and textile buyers prioritize specification compliance and supply continuity.
- Paints:Architectural, industrial, and automotive coatings incorporate wax for surface protection and application properties. German automotive OEMs and United States industrial maintenance coating houses consolidate supplier panels to three-to-four strategic partners with integrated documentation capabilities.
- Personal Care:Skincare, haircare, and color cosmetics utilize wax as emulsion stabilizers and texture modifiers. European Union Green Deal procurement criteria pull bio-based and carbon-negative wax claims into premium product positioning.
- Food & Beverage:Coatings, glazes, and packaging laminates require compliance with jurisdiction-specific food contact regulations. India's FSSAI and China's SAMR add testing layers for exporters serving Asia-Pacific formulation houses.
- Textiles:Yarn lubrication, finishing agents, and water-repellent coatings employ wax for processing efficiency and hand modification. Bangladeshi and Vietnamese garment manufacturers source through regional distributors with limited technical service requirements.
Paints represent the largest revenue block; personal care gains share fastest as vegan and consistent supply claims displace natural wax alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cape of Good Hope shipping lane funnels over half of global Fischer-Tropsch wax exports from South African gas-to-liquids facilities to coating houses in Germany, the United States, and Japan. This maritime chokepoint concentrates supply risk for automotive refinish formulators dependent on ultrapure wax grades with sub-5 ppm sulfur content.
United States
Automotive refinishing shops in Michigan and Ohio are converting solvent lines to powder coating systems, pulling micronized polyethylene wax demand for flow control. EPA TSCA compliance requirements are embedding chemical safety documentation directly into e-procurement platforms used by Midwest industrial coating clusters. Houston-area petrochemical complexes supply standard-grade polyethylene wax to domestic PVC compounders.
Germany
BASF SE leverages its integrated Fischer-Tropsch feedstock position in Ludwigshafen to secure supply continuity for European coating houses facing stricter volatile organic compound rules. ECHA's REACH registration deadlines for low-volume chemicals are accelerating substitution of unregistered petroleum wax blends with documented synthetic alternatives. Automotive OEMs in Bavaria consolidate qualified supplier lists to under five vendors per region.
China
Domestic paint producers in the Yangtze River Delta are upgrading formulation standards under stricter GB specifications for construction materials. SAMR food packaging standards and MEE environmental enforcement are tightening purity specifications for wax imports. Shanghai and Jiangsu province house the largest concentration of polyethylene wax demand from PVC pipe and profile extruders.
South Africa
Secunda and Mossel Bay gas-to-liquids facilities anchor global Fischer-Tropsch wax production capacity with captive syngas feedstock. Logistics disruptions at Durban port expose coating formulators worldwide to supply interruptions. Sasol maintains competitiveness through integrated gas-to-liquids output serving export markets in Europe and North America.
Japan
Clearcoat formulators in the Kansai region anchor import demand for ultrapure Fischer-Tropsch grades with controlled crystallization behavior. METI chemical substance classifications add compliance layers for exporters serving Japanese formulation houses. Osaka-based automotive refinish suppliers are locking in multi-year offtake agreements for sub-10-micron wax fractions.
Synthetic Wax Market Competitive Landscape
Listed leaders compete with private specialists across integrated feedstock control and certification depth. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive Fischer-Tropsch or polyethylene production, mid-scale compounders serving regional coating clusters, and toll manufacturers dependent on merchant feedstock. Strategic moves concentrate on backward integration into syngas or ethylene supply, and portfolio diversification toward cosmetic-grade certifications that command 3x premiums over industrial grades.
Within the multinational tier, BASF SE, Sasol, and Clariant AG exemplify divergent competitive positions. The Ludwigshafen-based chemical conglomerate represents integrated Fischer-Tropsch feedstock control. The South African energy-chemical group anchors gas-to-liquids scale. The Swiss specialty chemicals company occupies a position in micronized polyethylene wax differentiation for powder coating applications.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Sasol |
| Evonik Industries AG |
| Honeywell International Inc. |
| Mitsui Chemicals, Inc. |
| Eastman Chemical Company |
| The Lubrizol Corporation |
| Westlake Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Fischer-Tropsch wax substitution for polyethylene-derived opacifiers in European cosmetics simultaneously redraws procurement geography toward South African gas-to-liquids terminals and compresses pricing power for legacy petroleum wax compounders dependent on volatile ethylene feedstock economics.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade certifications commanding triple-digit premiums from industrial-grade spot transactions. Price differentiation rests on hydrogenation depth for FDA food-contact compliance and sub-10-micron particle size specifications for automotive clearcoats. Cost compression in standard-grade polyethylene wax intensifies because naphtha-cracker economics swing production costs quarterly. Chinese PVC compounders exhibit highest price sensitivity; German automotive OEMs prioritize supply continuity over unit economics.
Supply Chain Analysis
South Africa and the Middle East anchor Fischer-Tropsch wax production through captive syngas from gas-to-liquids facilities. Feedstock dependencies draw from natural gas reserves, rare-metal hydrogenation catalysts, and specialized micronization equipment. Single-source vulnerability concentrates at Durban port and the Cape of Good Hope shipping lane. Distribution runs through European coating house supplier panels consolidated to three-to-four strategic partners per region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through recovery as automotive OEMs phase out solvent-heavy coating systems and rebuild inventory positions. Powder coating migration and REACH compliance deadlines provide the cyclical impetus.
For Market Incumbents: Compound certification depth in pharmaceutical and food-contact grades to defend margin pools against toll manufacturers lacking hydrogenation catalyst expertise. Prioritize backward integration into syngas or ethylene supply to buffer naphtha-cracker volatility. Lock multi-year offtake agreements with Japanese clearcoat formulators to secure volume visibility.
For New Entrants and Emerging Players: Differentiate on bio-based Fischer-Tropsch claims using biomass gasification routes to capture EU Green Deal procurement criteria in European personal care. Target India's BIS-certified architectural paint segment where domestic formulators seek pre-documented impurity profiles. Deploy direct e-commerce sampling platforms to compress qualification cycles with independent coating labs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed mid-scale compounders serving regional coating clusters without integrated feedstock control. Five-to-ten year viability hinges on regulatory divergence on microplastic definitions and carbon-intensity benchmarking. Watch ECHA restriction proposals on intentionally added microplastics as the inflection signal for polyethylene wax reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Syngas | Sasol's captive gas-to-liquids output in Secunda secures supply continuity for European coating houses facing REACH deadlines. |
| Pharmaceutical Grade Certification | German and Swiss GMP wax finishing lines command triple-digit premiums over industrial grades in topical drug delivery. |
| Bio-Based Fischer-Tropsch Expansion | Forestry residue gasification enables carbon-negative claims for cosmetic brands targeting EU Green Deal procurement. |
| Supplier Panel Consolidation | Midwest industrial coating clusters embed FDA and EPA compliance data into e-procurement platforms. |
| Micronization Technology Investment | Sub-10-micron fractions for Japanese clearcoat formulators capture 3x premiums over coarse-cut grades. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Fischer-Tropsch plant managers, coating procurement leads at automotive OEMs, distribution channel partners, and cosmetic R&D directors; and secondary validation through customs trade data, ECHA registration databases, SEC chemical company filings, and GB standard documentation. Bottom-up triangulation across grade-specific volume estimates and top-down reconciliation against regional production capacity anchored forecast integrity.
Across the projection horizon, analytical frameworks modeled grade tier, end-use industry, and regional production hub segmentation. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH registration timelines, powder coating adoption rates, and ethylene feedstock cost trajectories. Forecast inputs included automotive refinish shop conversion velocities and BIS certification penetration in Indian architectural paints.
Forecasts assume regulatory continuity in REACH, FDA food-contact, and China's GB standards; material policy shifts on microplastic restrictions or dual carbon enforcement would require re-modeling. Recalibration cycles align with ECHA restriction determinations and automotive OEM solvent-phase-out milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Paraffin Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
US Esters Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Squalane Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Oily Waste Cans Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Cetyl Esters Market