
 Fireproof Cladding Market | 2026-2036
Fireproof Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Fireproof Cladding Market Foresight
The performance gap between premium engineered systems and commodity-grade panels is broadening as fire-safety certification becomes a non-negotiable specification criterion. Kingspan Group leverages its insulated panel expertise to dominate specification-led commercial projects across Northern Europe. Saint-Gobain sustains technology leadership through continuous R&D in mineral wool-based facade solutions. Etex Group anchors its competitive position with deep vertical integration from raw fiber processing through prefabricated system delivery.
Fireproof cladding comprises non-combustible or limited-combustible facade materials engineered to resist flame propagation, typically achieving Euroclass A1 or A2 ratings through mineral fiber, phenolic resin, or rock wool compositions bonded to structural substrates. These systems serve the primary commercial purpose of preventing vertical fire spread across building exteriors while meeting thermal insulation and weatherproofing requirements. Phenolic resin panels currently occupy the highest margin pool due to their superior strength-to-weight ratio in high-rise applications. Mineral fiber systems lead volume demand across infrastructure projects where cost sensitivity intersects with stringent code compliance. Prefabricated installation methods are accelerating fastest as contractors seek to compress on-site labor hours and reduce weather-dependent scheduling risk.
The EU Construction Products Regulation mandates CE marking under EN 13501-1 fire classification, while the UK Building Safety Regulator enforces gateway compliance for higher-risk residential buildings post-Grenfell reforms. These frameworks are reshaping procurement patterns by disqualifying sub-A2 materials from projects above 18 meters. Stakeholders must monitor evolving national implementations of the EU Green Deal's embodied carbon thresholds, which threaten to restrict certain phenolic resin chemistries unless bio-based feedstock substitutions achieve technical validation.
Market Dynamics
Post-Grenfell regulatory tightening across high-rise construction corridors is compressing specification windows for combustible materials, forcing rapid substitution toward mineral-based facade systems. This structural pressure is redrawing competitive boundaries between engineered panel producers and commodity suppliers.
Growth Catalysts
- EU Construction Products Regulation:CE marking mandates under EN 13501-1 are eliminating sub-A2 materials from projects above 18 meters, creating immediate specification pull for certified systems.
- UAE Fire and Life Safety Code:High-rise residential towers in Dubai and Riyadh are accelerating A2-rated facade adoption as Gulf Cooperation Council megaprojects prioritize non-combustible core materials.
- Prefabricated installation methods:Contractors across Northern European commercial projects are specifying factory-finished panels to compress on-site labor hours and reduce weather-dependent scheduling risk.
Market Restraints
- Mineral fiber raw material concentration:Supply of basalt and slag feedstock concentrates in a limited number of processing regions, exposing panel producers to input volatility and freight cost spikes.
- EU Green Deal embodied carbon thresholds:Pending restrictions on phenolic resin chemistries threaten to disqualify certain high-performance panels unless bio-based feedstock substitutions achieve technical validation.
- Technical limitation in retrofit applications:Existing building substrate conditions often prevent direct adhesion of A2-rated systems, requiring costly structural reinforcement that compresses project margins.
Strategic Opportunities
- Saudi Arabia Vision 2030 infrastructure pipeline:Neom and Red Sea Project developments are specifying fire-rated facade systems at scale, creating demand corridors for certified suppliers with local fabrication partnerships.
- Digital specification platforms:Building information modeling-integrated product libraries are enabling direct architect-to-manufacturer engagement, bypassing traditional distributor markups in UK and German markets.
- UK Building Safety Regulator gateway compliance:Higher-risk residential building reforms are mandating third-party certification for all facade materials, creating a compliance services revenue stream adjacent to panel supply.
Industry Challenges
- Fire-safety engineer talent scarcity:Shortage of professionals qualified to interpret EN 13501-1 test protocols is extending project approval timelines and increasing consultant costs.
- CE marking certification backlog:Notified body capacity constraints are delaying product approvals by six to twelve months, freezing new product launches.
- Legacy facade liability exposure:Building owners are pursuing recladding claims against original contractors, forcing insurers to exclude facade work from standard professional indemnity coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fireproof Cladding Market |
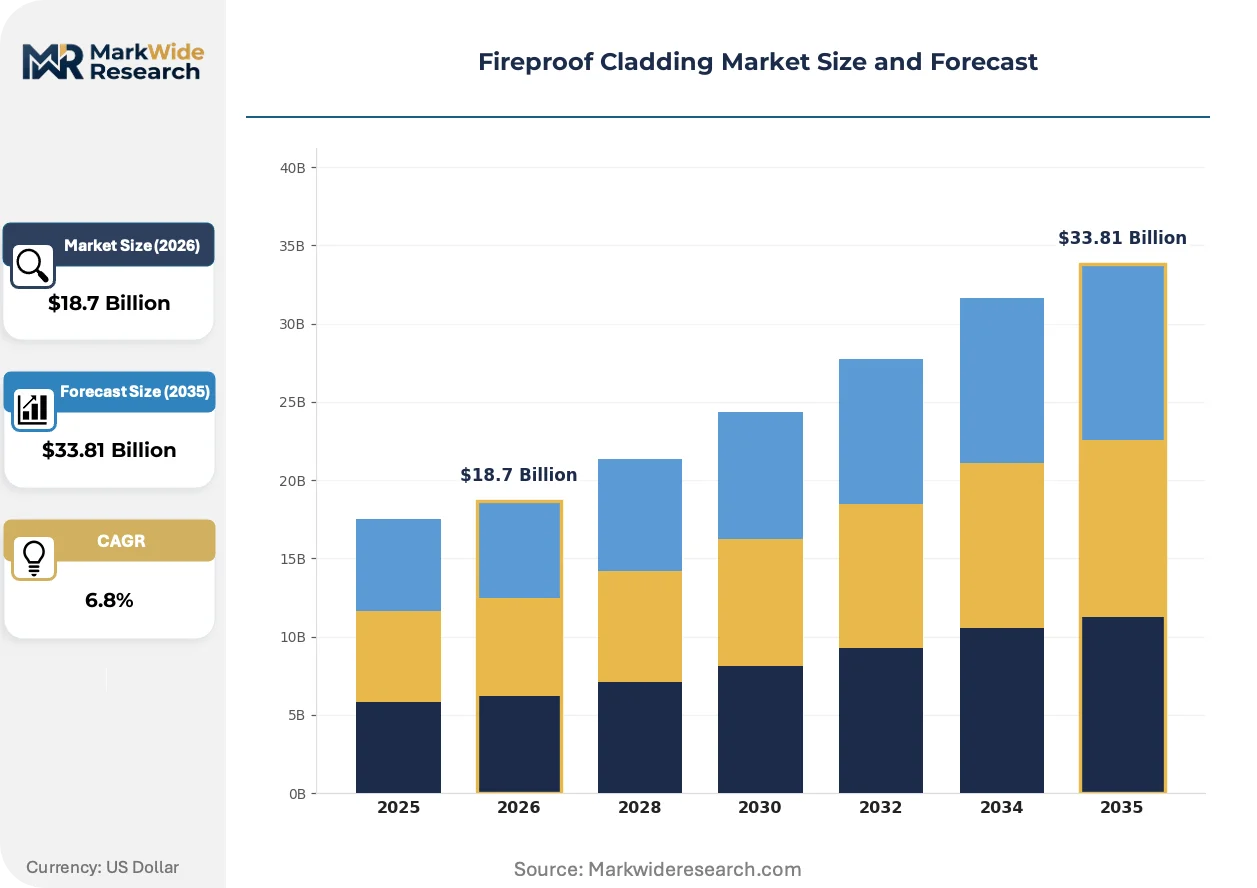
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Phenolic Resin, Rock Wool, Mineral Fiber Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Infrastructure Projects Installation Method: Mechanical Fixing, Adhesive Application, Fusion Bonding, Prefabricated Systems End User: Contractors, Architects, Building Owners, Government Agencies |
| Companies Covered | Etex Group, 3A Composites GmbH, Kingspan Group, Cembrit Holding A/S, Tata Steel, Saint-Gobain, James Hardie Industries plc, Nichiha Corporation, ROCKWOOL International A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fireproof Cladding Market Shifts & Advancements
Material science advances and installation methodology changes are compressing the performance gap between premium and standard facade systems. Three developments are restructuring how fire-rated cladding is specified, procured, and deployed.
Mineral fiber composite panels are overtaking phenolic resin systems in high-rise specification across Northern European markets. Architects in London and Berlin are prioritizing non-combustible core materials for residential towers above 18 meters. This shift is compressing margins for resin-based producers while expanding volume opportunities for basalt fiber suppliers with certified supply chains.
REACH regulation amendments targeting formaldehyde emissions are forcing reformulation of certain binder chemistries used in mineral wool production. German and French manufacturers are investing in alternative resin systems to maintain CE marking eligibility. Panel categories relying on legacy binders face accelerated obsolescence unless substitution timelines align with certification renewal cycles.
Direct procurement from system houses is fragmenting traditional distribution channels across UK commercial construction. Main contractors are negotiating frame agreements with Kingspan Group and Etex Group for multi-project supply, bypassing regional merchants. This concentration is most visible in speculative office developments where repeatability and schedule certainty outweigh upfront material cost considerations.
Fireproof Cladding Market Segmentation
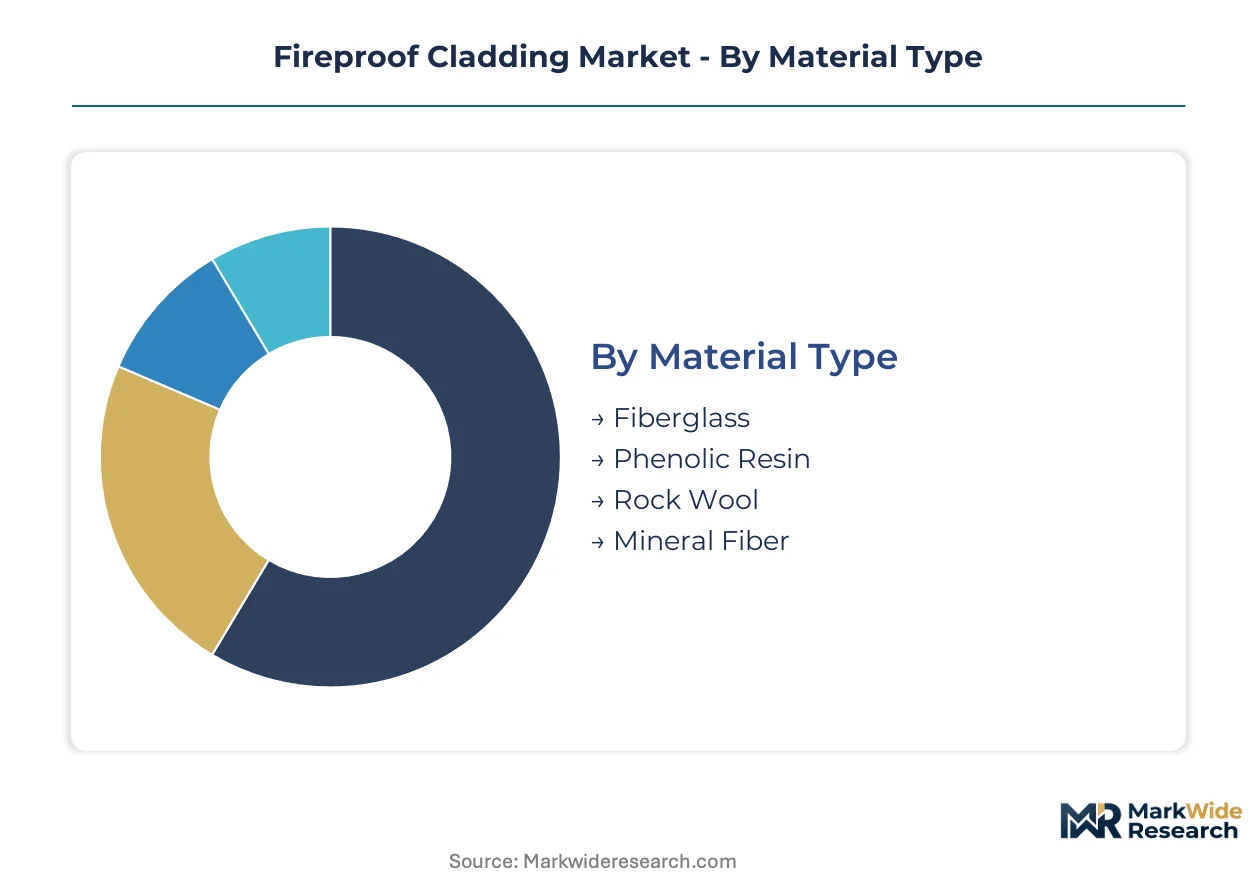
Fireproof cladding procurement varies sharply by decision-maker priority: architects chase Euroclass A1 ratings, contractors optimize installation speed, and building owners weigh lifecycle liability exposure. Segmentation reveals where specification power sits and which technical attributes command price premiums.
Material Type:
Buyers in this category differentiate primarily by combustibility grade and structural load-bearing requirements, with high-rise developers paying premiums for non-combustible cores that satisfy post-Grenfell regulatory thresholds.
- Phenolic Resin:Thermoset polymer matrix delivers superior strength-to-weight ratios for curtain wall applications above 18 meters. Demand concentrates in London and Berlin speculative office towers where architects prioritize thin-profile aesthetics alongside EN 13501-1 A2 certification.
- Mineral Fiber:Basalt and slag-derived non-combustible cores achieve Euroclass A1 ratings without additional fire barriers. Gulf Cooperation Council megaprojects in Dubai and Riyadh are specifying mineral fiber composite panels as primary facade substrates under updated UAE Fire and Life Safety Code mandates.
- Rock Wool:Stone wool compositions offer acoustic dampening alongside thermal insulation for infrastructure tunnels and transit stations.
- Fiberglass:E-glass reinforced systems serve lower-rise commercial retrofits where cost sensitivity outweighs premium fire ratings.
Mineral fiber leads volumes today; phenolic resin is gaining share fastest in premium high-rise specification.
Application:
Project scale and regulatory scrutiny intensity separate segments here, with residential towers above 18 meters facing the strictest material disqualification rules.
- Residential Buildings:High-rise towers trigger mandatory third-party certification under UK Building Safety Regulator gateway compliance, forcing direct architect-to-manufacturer procurement. London developers are bypassing distributors to secure certified supply chains for repeat project portfolios.
- Commercial Buildings:Northern European speculative office developments prioritize schedule certainty through prefabricated system contracts with integrated installation warranties.
- Infrastructure Projects:Saudi Arabia Vision 2030 developments including Neom specify fire-rated facade systems at scale for transportation and utility buildings.
- Industrial Facilities:Petrochemical and power generation sites require blast-resistant cladding assemblies with integrated fire barriers.
Commercial buildings dominate current specification value; residential towers are expanding most quickly as recladding mandates accelerate.
Installation Method:
Contractor risk allocation and weather dependency shape selection, with main contractors increasingly transferring on-site labor exposure to system houses.
- Prefabricated Systems:Factory-finished panels with integrated insulation and weatherproofing compress installation schedules by 40-60% versus stick-built alternatives. German and UK main contractors are negotiating multi-project frame agreements with system houses to lock in pricing and delivery certainty.
- Mechanical Fixing:Rainscreen cladding with visible fixings dominates infrastructure and industrial applications where substrate conditions vary unpredictably.
- Adhesive Application:Direct-bond systems face technical limitations in retrofit scenarios requiring costly structural reinforcement.
- Fusion Bonding:Specialized metallurgical joining serves niche high-performance facades with extreme wind-load requirements.
Mechanical fixing retains the largest installed base; prefabricated systems are climbing the fastest as labor costs and schedule risk concentrate contractor preferences.
End User:
Specification authority and liability exposure define this category, with professional indemnity insurance availability increasingly constraining contractor choices.
- Architects:Building information modeling-integrated product libraries enable direct digital specification of certified systems, bypassing traditional merchant markups in UK and German markets. London practices are embedding fire-safety engineers earlier in design development to preempt regulatory rejection.
- Contractors:Frame agreement negotiations with Kingspan Group and Etex Group concentrate procurement power among tier-one main contractors with multi-project pipelines.
- Building Owners:Recladding liability exposure is driving forensic facade audits and insurance coverage exclusions for legacy systems.
- Government Agencies:Public procurement mandates for Euroclass A1 materials are reshaping hospital and school construction specifications across France and Germany.
Contractors control the largest share of procurement volume; architects are expanding their influence fastest through digital specification platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fire-safety engineer talent concentrates in London, Berlin, and Dubai, anchoring specification authority for high-rise facade projects across their respective markets. These technical clusters translate regulatory complexity into enforceable building codes that reshape material procurement patterns.
United Kingdom
London's reclamation pipeline drives demand for third-party certified A2-rated systems as the UK Building Safety Regulator enforces gateway compliance for residential towers above 18 meters. The Building Safety Act mandates traceable supply chains from raw fiber through installation. Manchester and Birmingham developers are negotiating direct frame agreements with system houses to preempt certification delays.
Germany
Berlin's speculative office construction prioritizes prefabricated mineral fiber panels that compress installation schedules by 40-60% versus stick-built alternatives. REACH amendments targeting formaldehyde emissions force reformulation of legacy binder chemistries in mineral wool production. The Rhine-Ruhr industrial corridor hosts concentrated basalt fiber processing capacity serving Northern European facade manufacturers.
United Arab Emirates
Dubai's high-rise residential towers accelerate A2-rated facade adoption following UAE Fire and Life Safety Code updates that disqualify combustible core materials. MOHAP collaborates with civil defense authorities to harmonize Gulf Cooperation Council certification standards. Abu Dhabi's Al Reem Island developments specify mineral fiber composite panels as primary facade substrates for megaproject portfolios.
Saudi Arabia
Neom and Red Sea Project developments specify fire-rated facade systems at scale under Vision 2030 infrastructure commitments. The Saudi Building Code mandates non-combustible materials for government-funded transportation and utility buildings. Riyadh's King Abdullah Financial District anchors demand for certified systems as local fabrication partnerships reduce import dependency.
France
Parisian hospital and school construction faces public procurement mandates for Euroclass A1 materials under national fire-safety frameworks. ANSM enforces strict interpretation of EN 13501-1 test protocols, extending approval timelines for novel panel compositions. The Lyon-Grenoble corridor concentrates technical expertise in mineral wool engineering for infrastructure tunnel applications.
Fireproof Cladding Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the fireproof cladding market, creating a tiered structure where integrated system houses hold specification power over commodity panel suppliers. The vendor base separates into three strategic archetypes: vertically integrated mineral fiber processors, engineered panel specialists with captive R&D pipelines, and regional fabricators serving cost-sensitive retrofit segments. Consolidation pressure intensifies as CE marking certification backlogs freeze new entrants and incumbents pursue capacity expansion in Gulf Cooperation Council markets. Strategic partnerships between European system houses and Saudi fabricators represent the dominant competitive move alongside portfolio diversification into prefabricated installation services.
Within the integrated-processor tier, Etex Group and Saint-Gobain occupy positions defined by backward integration from raw fiber processing through prefabricated system delivery. Kingspan Group exemplifies the engineered-panel archetype through its insulated panel expertise and specification-led commercial project focus. These three anchors illustrate how competitive positioning depends on supply chain control depth rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Etex Group |
| 3A Composites GmbH |
| Kingspan Group |
| Cembrit Holding A/S |
| Tata Steel |
| Saint-Gobain |
| James Hardie Industries plc |
| Nichiha Corporation |
| ROCKWOOL International A/S |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied carbon thresholds gate qualified supply and premium-tier pricing access for phenolic resin systems, forcing manufacturers to validate bio-based feedstock substitutions or surrender high-margin specification slots to mineral fiber competitors. Buyers seeking A2-rated facade systems face bifurcated procurement: certified European system houses command project-based premiums while commodity panel suppliers compete on volume contracts with compressed margins.
Pricing Analysis
The bundled-versus-unbundled service split separates project-based system contracts from commodity panel transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and installation warranty scope. Cost compression in economy-grade phenolic resin panels is intensifying because REACH amendments threaten legacy binder chemistries with accelerated obsolescence. Residential tower developers above 18 meters exhibit lowest price sensitivity, prioritizing traceable supply chains over unit cost.
Supply Chain Analysis
Basalt and slag feedstock supply rests on concentrated processing capacity in Germany, China, and Russia. Mineral fiber composite panels draw from captive basalt quarries, slag from steel production, and specialized phenolic resin chemistries. Single-source vulnerability in certified fiber processing exposes panel producers to freight cost spikes and qualification delays. Distribution runs through direct frame agreements between system houses and tier-one main contractors, bypassing traditional regional merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: European system houses face tightening embodied carbon compliance while Gulf Cooperation Council projects offer specification volume with less stringent feedstock scrutiny, creating margin expansion opportunity for producers with dual-hemisphere fabrication footprints.
For Market Incumbents: Acquire local fabrication partnerships in Saudi Arabia to anchor Neom and Red Sea Project supply corridors. Lock in multi-year frame agreements with UK main contractors before Building Safety Regulator gateway compliance freezes specification windows. Defend against mineral fiber substitution by accelerating bio-based phenolic resin validation to preserve curtain wall premium positioning. For New Entrants and Emerging Players: Digital specification platforms enable direct architect engagement without distributor markup burden. Target UK residential recladding mandates where certification backlogs freeze incumbent capacity and third-party compliance services create adjacent revenue. Enter through prefabricated installation partnerships that transfer on-site labor risk from contractors. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with Saudi local content credentials because Vision 2030 infrastructure commitments guarantee offtake volume through the decade. Focus on mid-cap specialists with backward integration into basalt fiber processing and existing CE marking portfolios. Watch CE marking certification queue length as inflection indicator: extended delays signal pricing power concentration among approved suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Fiber Processing | Captive feedstock supply from Rhine-Ruhr corridor insulates margin against mineral raw material volatility. |
| Prefabricated System Partnership | Factory-finished panel contracts with German main contractors compress installation schedules and lock repeat revenue. |
| CE Marking Certification Investment | Notified body approval under EN 13501-1 qualifies products for UK residential towers above 18 meters. |
| Saudi Local Fabrication Joint Venture | King Abdullah Financial District demand anchors regional supply without import dependency exposure. |
| Bio-Based Binder Reformulation | Alternative resin systems maintain eligibility under REACH amendments targeting formaldehyde emissions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from facade system engineers, fire-safety consultants interpreting EN 13501-1 protocols, procurement directors at tier-one main contractors, and specification architects at London and Berlin practices. Secondary validation drew from UAE Fire and Life Safety Code documentation, Saudi Building Code updates, UK Building Safety Regulator gateway compliance guidance, EU Construction Products Regulation implementation notices, and customs trade data for mineral fiber panel imports. Bottom-up project pipeline assessment triangulated against top-down construction spend forecasts.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions included material combustibility grade, installation methodology, application height threshold, and regional regulatory cluster. CAGRs were derived from fitted trend analysis applied to certified system adoption curves and recladding mandate implementation timelines. Forecast inputs incorporated notified body certification capacity constraints and REACH amendment implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for bio-based phenolic resin substitution would alter the outlook if technical validation timelines slip or mineral fiber systems capture unanticipated specification share. Forecasts embed assumptions regarding CE marking queue resolution and Gulf Cooperation Council harmonization progress. A small set of named triggers warrants ongoing watch: EU Green Deal threshold finalization, UK Building Safety Regulator enforcement intensity, and Saudi local content requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
India Cement Market
Building Materials
Block Paving Market
Building Materials
Mass Timber Construction Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Construction Coatings Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Steel Slag Market
Building Materials
Exterior Doors Market
Building Materials
Aluminum Door and Window Market
Building Materials
France Architectural Coatings Market
Building Materials
Long Steel Market
Building Materials
Qatar Facade Market
Building Materials
Building Asphalt Market
Building Materials
Global Building Panels Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market