
 Middle East and Africa Occupancy Sensors Market | 2026-2036
Middle East and Africa Occupancy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Occupancy Sensors Market Foresight
Electrical distributor networks across the Gulf Cooperation Council is reconfiguring as integrated building automation bundles displace standalone sensor sales. Schneider Electric leverages its EcoStruxure platform to anchor specification pipelines across Abu Dhabi and Dubai mega-developments. Johnson Controls sustains project engineering relationships through its Metasys ecosystem, while Legrand competes on wiring device compatibility with European-standard lighting infrastructure prevalent in Moroccan and Tunisian commercial builds.
Middle East and Africa occupancy sensors detect human presence through infrared radiation, ultrasonic sound waves, or combined modalities, typically operating at detection ranges of 15–30 feet with adjustable time delays of 30 seconds to 30 minutes for load switching. These devices serve primarily to automate lighting, HVAC, and security systems in commercial and institutional environments where energy costs and sustainability targets drive procurement. Passive infrared products dominate volume shipments across the region due to lower unit costs and simpler commissioning, though dual-technology variants command premium positioning in high-occupancy corridors and atrium spaces where false-trigger sensitivity must be minimized. Wireless connectivity segments are gaining specification share as retrofit activity accelerates in aging Riyadh and Johannesburg office stock where pulling new control wiring proves cost-prohibitive.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) efficiency labeling requirements are tightening standby power thresholds for sensor-connected luminaires, effectively filtering lower-efficiency imports from East Asian suppliers. South Africa's National Energy Regulator (NERSA) and municipal rebate structures through Eskom's Integrated Demand Management program directly influence procurement specifications in commercial retrofit tenders. Stakeholders must track evolving Gulf Cooperation Council harmonization timelines and local content requirements that could shift supply chain sourcing from European hubs toward regional assembly operations.
Market Dynamics
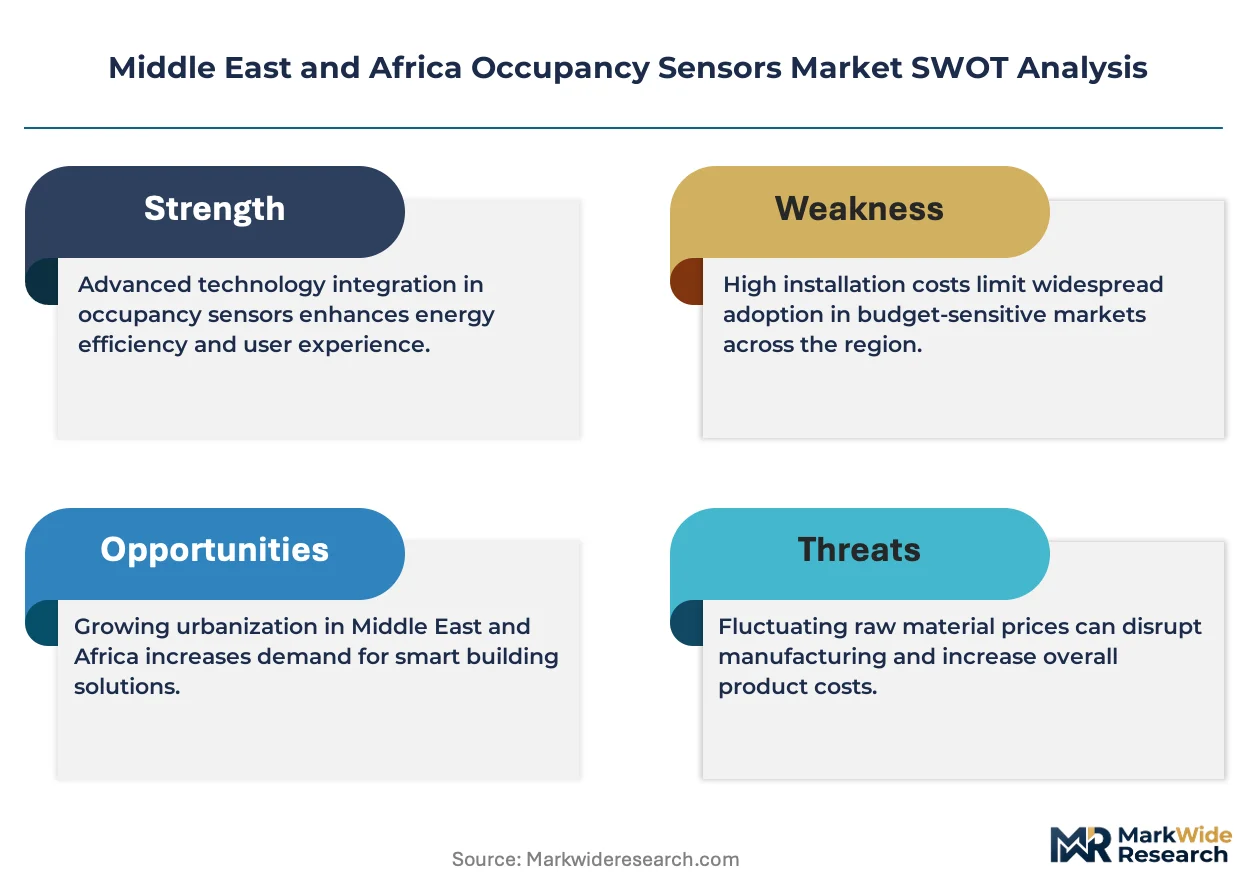
Smart building mandates across Saudi Arabia and the UAE are compressing specification timelines for integrated detection systems, forcing distributors to bundle sensors with broader automation platforms rather than sell standalone hardware.
Growth Catalysts
- SASO Technical Regulations:Saudi Arabia's tightening standby power thresholds for sensor-connected luminaires are filtering out low-efficiency imports and elevating procurement standards for domestic commercial builds.
- Wireless retrofit demand:Aging office stock in Riyadh and Johannesburg where new control wiring proves cost-prohibitive is accelerating specification of battery-powered and mesh-network sensors.
- Dual-technology corridors:High-occupancy atrium spaces in UAE mega-developments require false-trigger minimization, pulling premium ultrasonic-infrared hybrid systems into specification pipelines.
Market Restraints
- Import dependency:Regional assembly operations remain limited, leaving distributors exposed to European and East Asian supply chain disruptions and extended lead times.
- Commissioning complexity:Ultrasonic variants require specialized calibration expertise that remains scarce across Moroccan and Tunisian installer networks, slowing deployment velocity.
- Standby power thresholds:ESMA efficiency labeling requirements are disqualifying legacy sensor inventories, forcing write-downs among distributors holding pre-compliant stock.
Strategic Opportunities
- Eskom IDM rebates:South Africa's municipal rebate structures through the Integrated Demand Management program create direct procurement pull for certified sensors in commercial retrofit tenders.
- Sensor-to-BMS convergence:Integration of occupancy data with HVAC analytics platforms opens specification pathways for vendors offering API-ready hardware in Gulf commercial developments.
- Tunisian hospitality buildouts:European-standard lighting infrastructure prevalent in Moroccan and Tunisian commercial projects favors wiring-device-compatible sensor formats.
Industry Challenges
- Installer certification gaps:Commissioning dual-technology systems requires acoustic calibration skills that remain underdeveloped across regional electrical contractor networks.
- Legacy BMS integration:Proprietary communication protocols in aging Johannesburg and Riyadh building automation systems complicate sensor retrofit compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Occupancy Sensors Market |
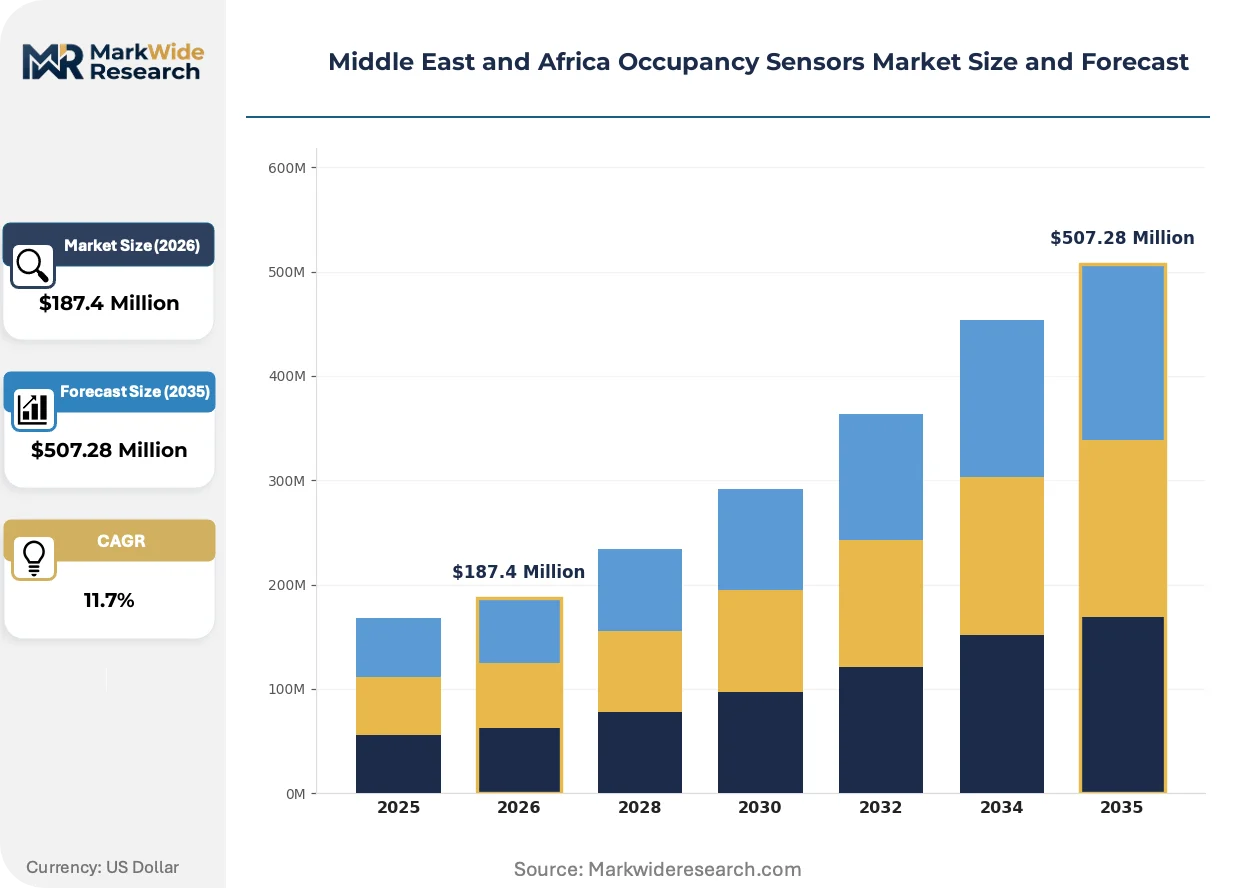
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Infrared, Ultrasonic, Dual Technology, Microphonics End User: Residential, Commercial, Industrial, Institutional Installation Type: Indoor, Outdoor, Wall-mounted, Ceiling-mounted Connectivity: Wired, Wireless, Zigbee, Bluetooth |
| Companies Covered | Schneider Electric, Legrand, Johnson Controls, Signify Holding, Honeywell International, Eaton, Texas Instruments, Acuity Brands, Lutron Electronics, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Occupancy Sensors Market Shifts & Advancements
Detection hardware is converging with building analytics platforms, compressing the boundary between standalone sensors and fully integrated environmental management systems across commercial real estate portfolios.
Bluetooth Low Energy mesh networking is digitizing commissioning workflows for retrofit deployments. Facility managers in aging Saudi and South African office stock are specifying battery-powered sensors with smartphone-based configuration to bypass wiring constraints. This connectivity shift is digitizing how distributors quote projects, collapsing the distinction between hardware supply and ongoing system management services.
UAE's Emirates Authority for Standardization and Metrology is tightening efficiency labeling requirements for sensor-connected luminaires. The regulation is forcing distributors to purge non-compliant inventory and reorient procurement toward certified European and regional assembly sources. Commercial retrofit segments in Dubai and Abu Dhabi are responding by accelerating specification timelines to lock in compliant hardware before phase-in deadlines.
Building automation bundles are displacing standalone sensor transactions across Gulf distributor networks. Electrical contractors in mega-developments are specifying integrated platforms where detection hardware ships pre-configured with lighting and HVAC controls. Saudi commercial real estate developers are driving this pattern most visibly, using procurement scale to demand single-source accountability for sensor performance within broader environmental systems.
Middle East and Africa Occupancy Sensors Market Segmentation
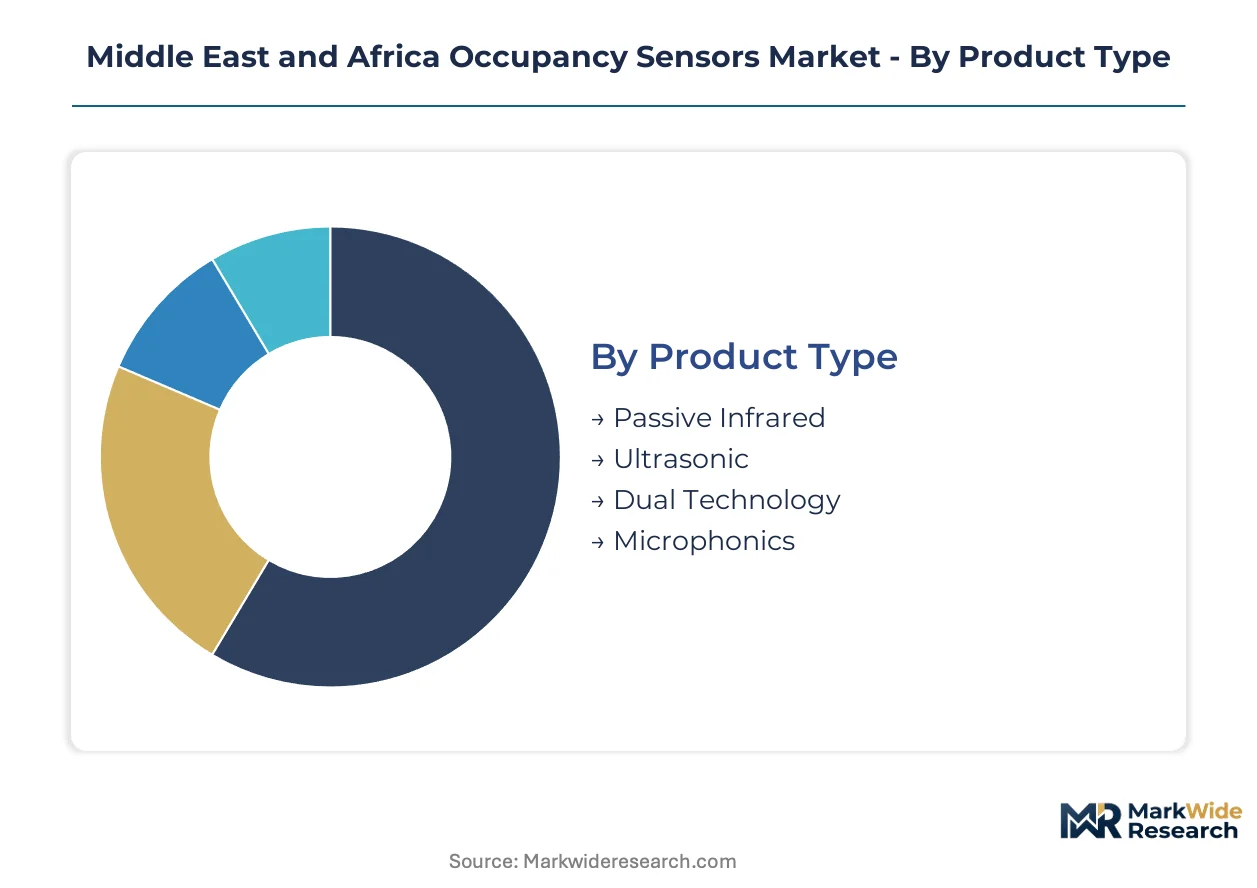
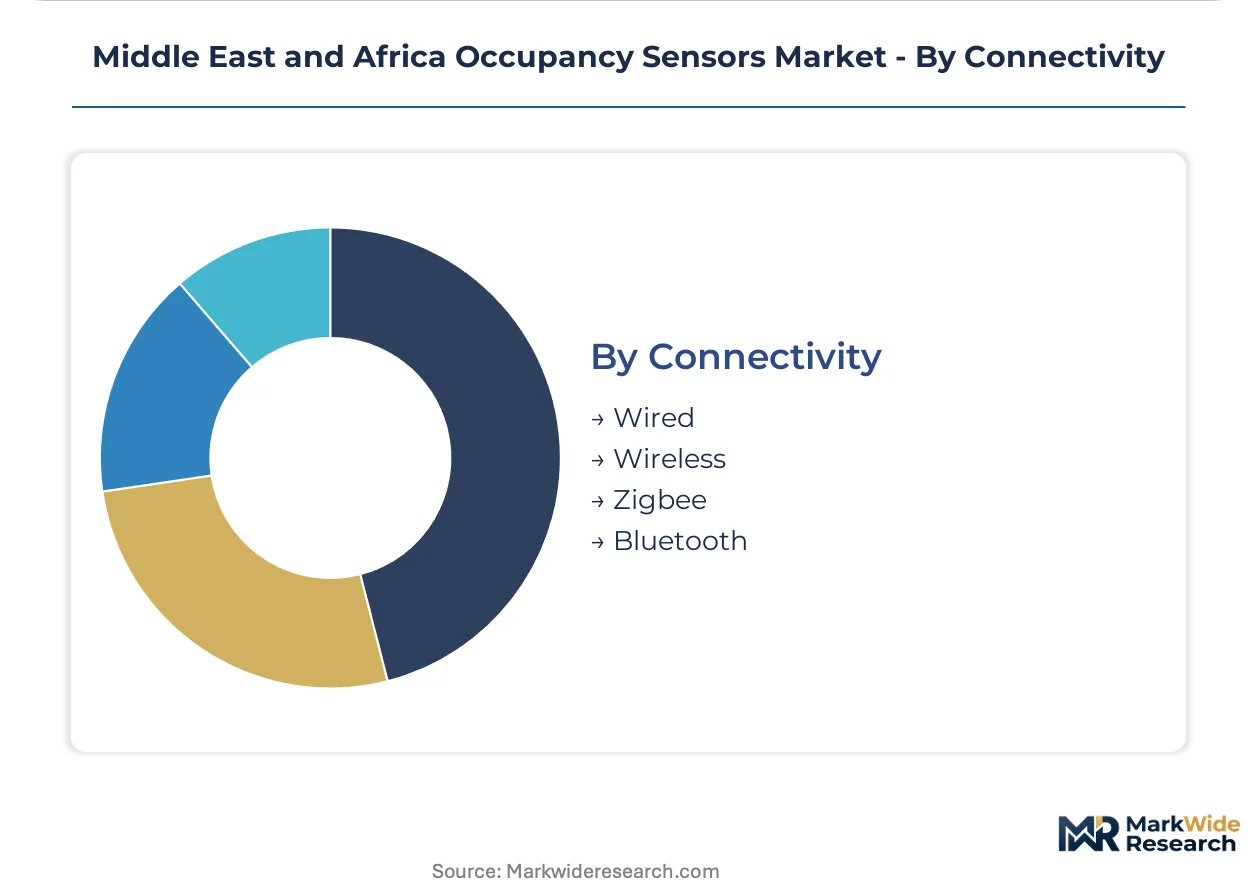
Segmentation in the Middle East and Africa occupancy sensors market reveals how procurement decisions split across detection physics, building typologies, and infrastructure constraints. Each dimension carries distinct specification requirements driven by regional energy mandates, retrofit economics, and installer capability gaps.
Product Type:
Mature infrared technology dominates volume shipments while emerging dual-technology variants capture premium positioning in high-specification corridors.
- Passive Infrared:These sensors detect body heat through pyroelectric elements, offering detection ranges of 15–30 feet with minimal power draw. Passive infrared products command the majority of unit shipments across Saudi commercial real estate and South African retail retrofit projects where unit economics prioritize simplicity over sophistication. SASO standby power thresholds favor this technology's inherent efficiency.
- Dual Technology:Combining infrared and ultrasonic detection modalities, these systems minimize false triggers through cross-correlation algorithms. Demand concentrates in UAE mega-development atriums and high-occupancy corridors where nuisance switching carries operational penalties. Premium positioning reflects commissioning complexity and acoustic calibration requirements.
- Ultrasonic:Emitting high-frequency sound waves to detect Doppler shifts from moving bodies, these sensors excel in irregular spaces with line-of-sight obstructions. Moroccan and Tunisian hospitality buildouts specify ultrasonic variants for partitioned office layouts.
- Microphonics:Acoustic detection systems identify occupancy through ambient sound pattern recognition. Emerging specification in noise-controlled environments such as Saudi healthcare facilities and UAE educational institutions.
Passive infrared handles the majority of throughput; dual technology is expanding most quickly on share.
End User:
Procurement authority concentrates in commercial and institutional segments where energy efficiency mandates create budgetary pull for automated detection systems.
- Commercial:Office towers, retail complexes, and hospitality properties across Dubai, Riyadh, and Johannesburg drive specification volume. Eskom IDM rebates directly influence procurement timelines in South African commercial retrofit tenders. Building automation bundles increasingly displace standalone sensor transactions.
- Institutional:Healthcare facilities, educational campuses, and government buildings in Abu Dhabi and Saudi Arabia's NEOM development specify integrated detection platforms. ESMA efficiency labeling requirements filter procurement toward certified hardware.
- Industrial:Warehousing and manufacturing environments in South Africa's Gauteng province and Saudi industrial cities deploy ruggedized sensors with extended detection ranges. Dust and vibration tolerance drive specification criteria.
- Residential:Smart home penetration remains limited across the region outside high-net-worth enclaves in Dubai and Riyadh. Price sensitivity and installer fragmentation constrain mass-market development.
Commercial installations generate the dominant revenue share; institutional projects are climbing the fastest as Gulf smart city mandates accelerate.
Installation Type:
Mounting configuration selection depends on ceiling height, wiring accessibility, and aesthetic requirements across building vintages.
- Ceiling-mounted:Recessed and surface-mount variants dominate new construction across UAE mega-developments and Saudi giga-projects. Clean sight lines and centralized coverage patterns optimize open-plan commercial layouts.
- Wall-mounted:Retrofit-preferred configuration in aging Riyadh and Johannesburg office stock where ceiling access proves disruptive. Battery-powered wireless variants accelerate specification in these applications.
- Indoor:Climate-controlled environments constitute the overwhelming majority of sensor deployments. Temperature stability preserves detection accuracy and extends hardware lifespan.
- Outdoor:Weatherized housings with IP ratings protect detection elements in Saudi exterior lighting and South African perimeter security applications. Limited volume reflects harsh climate exposure and maintenance concerns.
Ceiling-mounted hardware accounts for the greatest installation base; wall-mounted wireless configurations are gaining share fastest in retrofit segments.
Connectivity:
Communication protocol selection increasingly determines total cost of ownership as building automation integration deepens across regional commercial portfolios.
- Wireless:Battery-powered and energy-harvesting sensors eliminate wiring constraints in heritage Riyadh office buildings and Johannesburg commercial stock. Bluetooth Low Energy mesh networking enables smartphone-based commissioning workflows.
- Wired:Hardwired power and data connections persist in new Saudi and UAE developments where infrastructure planning permits integrated deployment. Lower lifecycle costs favor this approach in greenfield construction.
- Bluetooth:Mesh networking protocols digitize sensor configuration and maintenance workflows. Facility managers in aging stock specify Bluetooth-enabled hardware to bypass proprietary BMS integration challenges.
- Zigbee:Low-power mesh protocol finds specification in integrated lighting control systems where interoperability with broader building automation platforms matters. European-standard infrastructure in Moroccan and Tunisian projects favors Zigbee compatibility.
Wired connectivity retains the largest installed base; wireless configurations are expanding most rapidly as retrofit activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the UAE and Saudi Arabia where mega-development scale commands bundled procurement discounts, while South African distributors absorb margin compression from municipal rebate-driven specification cycles.
Saudi Arabia
NEOM giga-projects and Riyadh commercial towers drive specification volume for ceiling-mounted infrared systems. SASO technical regulations on standby power thresholds filter import sourcing toward certified European assembly operations. Jeddah's hospitality retrofit pipeline accelerates wireless sensor deployment where heritage building wiring constraints dominate.
United Arab Emirates
Dubai and Abu Dhabi mega-developments compress specification timelines through single-source building automation accountability. ESMA efficiency labeling requirements force distributor inventory purges and reorientation toward compliant hardware. Sharjah's educational campus expansions specify integrated detection platforms with API-ready HVAC analytics convergence.
South Africa
Eskom's Integrated Demand Management program creates direct procurement pull through municipal rebate structures in Gauteng commercial retrofits. Johannesburg's aging office stock accelerates battery-powered wireless specification to bypass disruptive ceiling access. Cape Town's institutional buildouts concentrate demand for dual-technology corridors in high-occupancy healthcare environments.
Morocco
Casablanca and Rabat hospitality buildouts favor European-standard lighting infrastructure compatibility in wiring device formats. The country's national standardization body aligns efficiency thresholds with Gulf Cooperation Council harmonization timelines. Tangier's logistics and industrial zones deploy ruggedized sensors with extended detection ranges for warehousing applications.
Tunisia
Tunis commercial developments specify ultrasonic variants for partitioned office layouts with line-of-sight obstructions. The national energy efficiency agency structures rebate programs modeled on South African IDM frameworks. Sfax's manufacturing corridors concentrate industrial-grade sensor procurement for dust-tolerant deployment environments.
Middle East and Africa Occupancy Sensors Market Competitive Landscape
Integrated building automation platforms and standalone hardware specialists split the market along bundled-versus-component procurement fault lines. Schneider Electric anchors specification pipelines through EcoStruxure platform dominance in UAE mega-developments. Johnson Controls sustains project engineering relationships via Metasys ecosystem integration. Legrand competes on wiring device compatibility with European-standard infrastructure prevalent in North African commercial builds. Competitive moves concentrate on platform convergence partnerships and distributor network reconfiguration toward bundled solution sales.
Within the integrated platform tier, Schneider Electric, Johnson Controls, and Legrand occupy archetypal positions representing distinct strategic vectors—French-headquartered multinational electrical infrastructure, American building automation systems integration, and European wiring device compatibility respectively. These three exemplify how specification authority migrates from hardware supply toward environmental system accountability in Gulf commercial real estate procurement cycles.
| Leading Market Players |
|---|
| Schneider Electric |
| Legrand |
| Johnson Controls |
| Signify Holding |
| Honeywell International |
| Eaton |
| Texas Instruments |
| Acuity Brands |
| Lutron Electronics |
| Others |
Supply & Pricing Matrix
Import dependency on European and East Asian sensor modules compresses both margin structures and procurement flexibility across Gulf distributor networks. SASO technical regulations and ESMA efficiency labeling requirements simultaneously filter supplier eligibility and force inventory write-downs, tightening the spread between certified premium hardware and non-compliant legacy stock.
Pricing Analysis
Configured-to-order pricing for dual-technology systems with acoustic calibration support commands substantial premiums over standard passive infrared units. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling, with ESMA-compliant hardware capturing margin premiums. Cost compression in economy-tier infrared products is intensifying because East Asian suppliers face SASO standby power disqualification. Commercial retrofit contractors in Johannesburg and Riyadh exhibit highest price sensitivity, while UAE mega-developments prioritize single-source accountability over unit economics.
Supply Chain Analysis
Extended payment terms from European component suppliers strain working capital across regional distributor networks. Manufacturing concentrates in Germany, France, and China, with pyroelectric elements and ultrasonic transducers drawing from specialized semiconductor foundries. Single-source vulnerability around Bluetooth Low Energy mesh chipsets threatens retrofit project timelines. Distribution runs through electrical wholesaler networks reconfiguring toward integrated building automation bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates sticky specification relationships. Switching costs escalate as building automation platforms deepen integration with HVAC analytics.
For Market Incumbents: Harden platform lock-in through API-ready sensor-to-BMS convergence that embeds occupancy data into broader environmental management systems. Expand backward integration into regional assembly operations to deflect tariff exposure on finished European imports. Certification investment in SASO and ESMA pre-approval pipelines secures specification priority in Saudi and UAE commercial tenders.
For New Entrants and Emerging Players: Establish a beachhead in South Africa's municipal rebate-driven retrofit segment where Eskom IDM program structures create procurement pull without incumbent platform dominance. Target wall-mounted wireless configurations for aging Johannesburg and Riyadh office stock where installer fragmentation and wiring constraints favor agile hardware specialists. Partner with electrical contractor networks lacking acoustic calibration expertise to bundle commissioning services with dual-technology shipments.
For Investors and Strategic Acquirers: Gulf Cooperation Council harmonization timelines reshape the acquisition landscape by elevating regional assembly capabilities over pure import distribution models. Long-term viability centers on platform convergence plays with HVAC analytics integration rather than standalone hardware volume. Monitor installer certification gap closure as the signal indicating competitive pressure on premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Assembly Localization | SASO technical regulations favor certified regional production over European import dependency. |
| Sensor-to-BMS API Development | Sharjah educational campuses specify HVAC analytics convergence with occupancy data streams. |
| Bluetooth Mesh Certification | Riyadh retrofit projects demand smartphone-based commissioning bypassing proprietary BMS protocols. |
| Installer Training Partnerships | Moroccan and Tunisian contractor networks lack acoustic calibration skills for dual-technology deployment. |
| Eskom IDM Rebate Alignment | Gauteng commercial tenders require certified sensor specifications for municipal incentive eligibility. |
Research Methodology
A spread of perspectives from building automation systems integrators, electrical distributor procurement leads, facilities management directors, and regulatory compliance officers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through SASO technical regulation filings, ESMA efficiency labeling databases, Eskom Integrated Demand Management program documentation, and customs import records for sensor hardware. Bottom-up shipment estimates by product type and installation configuration triangulated against top-down construction spending forecasts across the analysis window.
Demand-supply balance modeling anchored volume projections to commercial real estate development pipelines and retrofit activity cycles across Saudi Arabia, UAE, South Africa, Morocco, and Tunisia. Segmentation dimensions included detection physics, connectivity protocol, mounting configuration, and building typology, with CAGRs derived from regression analysis against historical efficiency mandate adoption curves. Industry-specific forecast inputs incorporated Gulf Cooperation Council harmonization timelines and municipal rebate program renewal patterns.
Sensitivities concentrate around regulatory phase-in acceleration, supply chain disruption severity, and installer certification program rollout pace. Forecasts reflect documented assumptions on mandate enforcement consistency and technology substitution thresholds. Macroeconomic contraction, regulatory delay, or wireless protocol standardization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
MEMS Gyroscope Market