
 Steam Flow Meter Market | 2026-2036
Steam Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Flow Meter Market Outlook
A widening capability gap between integrated multinationals and regional specialists is reorganizing competitive dynamics in steam flow metering. Emerson Electric Co. leverages its Rosemount instrumentation platform to dominate high-temperature industrial applications. Endress+Hauser AG sustains European market presence through Proline thermal mass technology leadership. Yokogawa Electric Corporation anchors Asian demand with vortex flow meter specialization for power generation utilities.
Steam flow meters are precision instruments that measure mass or volumetric flow rates of saturated or superheated steam using differential pressure, vortex shedding, thermal dispersion, or electromagnetic principles, typically operating at temperatures exceeding 150°C and pressures above 10 bar to optimize boiler efficiency and process heat transfer. Differential pressure flow meters occupy the largest installed base due to decades of proven reliability in harsh steam environments, though thermal mass variants are capturing faster growth in food and beverage pasteurization lines where direct mass measurement eliminates density compensation errors. Electromagnetic technology leads R&D investment for wet steam applications, while mechanical segment meters retain cost-sensitive utility markets despite gradual displacement.
EPA mandates under the Clean Air Act and OSHA boiler safety standards shape North American product certification requirements, while the EU F-Gas Regulation and CE marking under the Pressure Equipment Directive govern European market access. ISO 5167 orifice plate standards and IEC 60534 valve sizing protocols create baseline interoperability demands across jurisdictions. Stakeholders must monitor evolving carbon accounting rules that could mandate sub-metering granularity beyond current plant-level steam measurement.
Market Dynamics
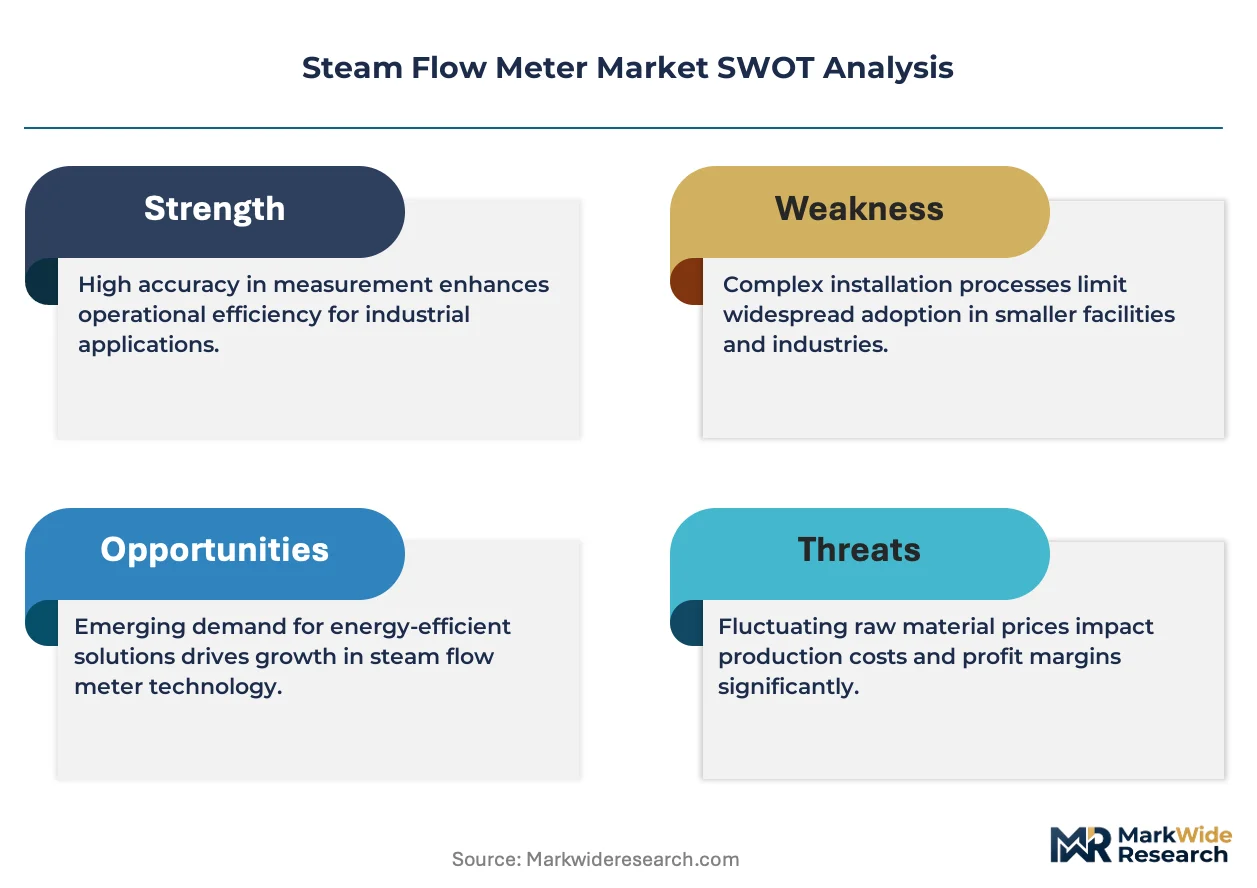
Steam flow meter procurement is pivoting toward integrated thermal mass solutions as chemical processors abandon legacy orifice plate maintenance cycles. The EPA's Clean Air Act enforcement is forcing facilities to install sub-metering granularity that differential pressure systems cannot deliver without costly density compensation infrastructure.
Growth Catalysts
- EPA Clean Air Act mandates:Emissions compliance deadlines in US chemical processing and power generation facilities are accelerating instrumentation replacement cycles.
- Food and beverage pasteurization:Direct mass measurement requirements in dairy and brewing operations are eliminating density calculation errors that plague volumetric alternatives.
- Germany's industrial corridor:Process manufacturers in the Rhine-Ruhr region are prioritizing energy efficiency audits that flag steam leakage and optimize boiler utilization.
Market Restraints
- Stainless steel price volatility:Fluctuations in 316L and 304 grade alloys directly impact thermal mass sensor housing costs and project quoting stability.
- Orifice plate installed base inertia:Decades of differential pressure infrastructure in US refineries creates switching friction against vortex and thermal alternatives.
- Wet steam measurement limitation:Condensate carryover degrades vortex shedding accuracy, restricting deployment in certain pulp and paper drying applications.
Strategic Opportunities
- EU F-Gas Regulation alignment:Refrigeration and cold chain facilities retrofitting heat pump systems need precise steam metering for efficiency certification.
- India PLI scheme:Process manufacturing incentives in Gujarat and Maharashtra are greenfielding plants without legacy instrumentation lock-in.
- Digital twin integration:Convergence of IIoT-enabled thermal mass meters with predictive maintenance platforms opens subscription revenue models for meter OEMs.
Industry Challenges
- High-temperature calibration scarcity:Qualified technicians capable of 300°C+ loop verification are concentrated in Germany and Japan, creating service bottlenecks elsewhere.
- CE marking timeline compression:The Pressure Equipment Directive's evolving conformity assessment routes are extending product launch cycles for multinationals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Flow Meter Market |
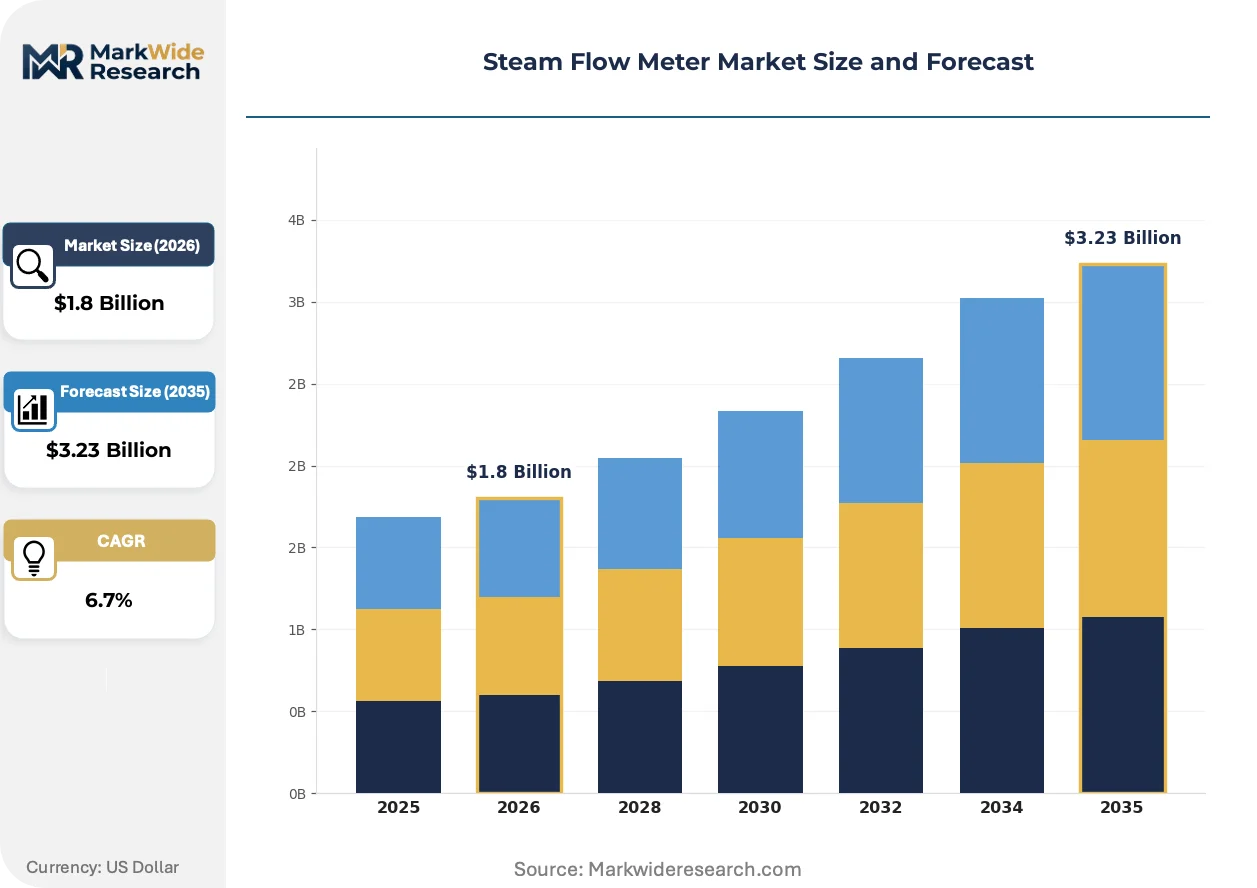
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Flow Meters, Volumetric Flow Meters, Differential Pressure Flow Meters, Vortex Flow Meters Technology: Electromagnetic, Thermal, Ultrasonic, Mechanical End User: Energy, Food & Beverage, Pharmaceutical, Chemical Installation: In-line, Insertion, Portable, Clamp-on |
| Companies Covered | Emerson Electric Co., Endress+Hauser AG, ABB Ltd., Siemens AG, Yokogawa Electric Corporation, Honeywell International Inc., Krohne Messtechnik GmbH, Badger Meter, Inc., Azbil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Flow Meter Market Strategic Shifts
Steam flow instrumentation is shedding its mechanical heritage as solid-state sensing and edge computing redefine performance benchmarks. Three developments are compressing the competitive window for legacy suppliers.
Coriolis mass flow technology is displacing differential pressure orifice installations in superheated steam applications above 200°C. Combined cycle power plants in Texas and Louisiana are piloting these meters for feedwater measurement, eliminating impulse line freezing and drift calibration cycles. The shift is compressing maintenance budgets and redirecting capital toward single-instrument redundancy rather than dual-orifice backup schemes.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is redirecting industrial heat pump investment toward steam-driven absorption systems. Food processors in Denmark and the Netherlands are retrofitting district heating connections that require precise steam allocation metering. This regulatory vector is elevating thermal mass meter specification priority in HVAC-R contractor procurement templates.
Plant engineering teams are unbundling after-sales service contracts from initial hardware procurement. Japanese power utilities now separate calibration scheduling from meter purchase agreements, soliciting third-party metrology labs for ISO 17025-accredited loop verification. This procurement fragmentation is compressing OEM service margins while opening independent calibration specialist entry in the Osaka and Nagoya industrial zones.
Steam Flow Meter Market Segmentation
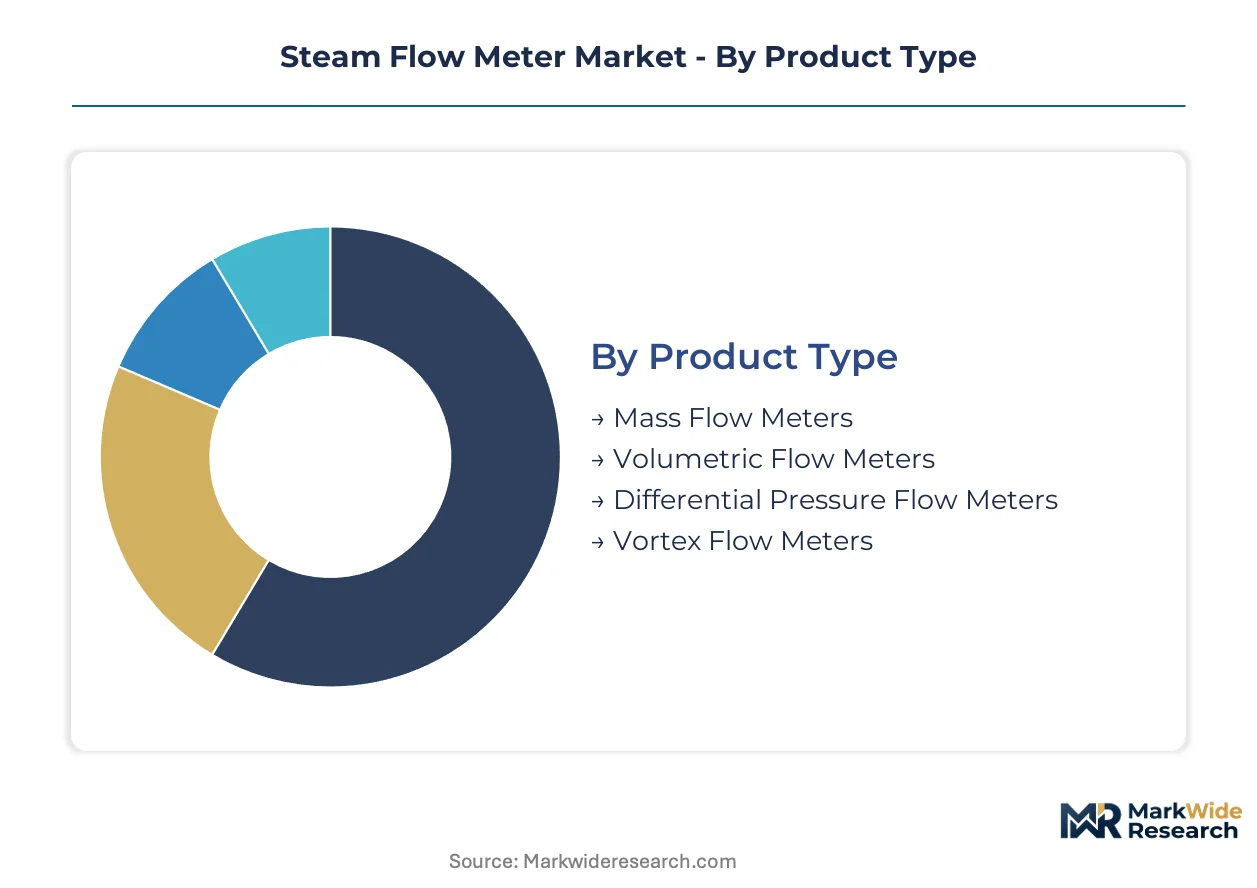
Steam flow meter procurement diverges sharply across product architectures and deployment contexts. Margin pools concentrate where measurement precision intersects with regulatory compliance mandates.
Product Type:
Premium pricing accrues to instruments eliminating density compensation infrastructure and reducing calibration cycles.
- Mass Flow Meters:Thermal and Coriolis principles deliver direct mass measurement without temperature-pressure compensation. Dairy pasteurization lines in Denmark and brewing operations across the Netherlands specify these for regulatory traceability.
- Differential Pressure Flow Meters:Orifice plate and venturi designs dominate legacy installations in US refineries and petrochemical corridors. Decades of proven reliability sustain replacement demand despite higher maintenance burdens.
- Volumetric Flow Meters:Positive displacement and turbine variants serve utility billing applications where custody transfer accuracy matters less than capital cost containment.
- Vortex Flow Meters:Bluff-body shedding sensors excel in saturated steam above 150°C. Power generation utilities in Japan specify these for boiler feedwater monitoring.
Differential pressure meters hold installed capacity. Mass flow meters are rotating up the share rankings.
Technology:
Technology selection pivots on steam condition, with dry superheated applications commanding hardware premiums over wet steam tolerance requirements.
- Thermal:Heated-sensor mass measurement eliminates impulse lines and suits food-grade stainless requirements. German process manufacturers prioritize these for energy audit compliance.
- Electromagnetic:Faraday induction coils tolerate condensate carryover better than vortex alternatives. Pulp and paper drying lines in Finland pilot these for wet steam accuracy.
- Ultrasonic:Transit-time and Doppler clamp-on configurations enable retrofit without pipe shutdown. Maintenance contractors favor these for aging infrastructure surveys.
- Mechanical:Spring-loaded and target-style meters retain position in developing markets where capital constraints override precision requirements.
Thermal technology anchors current revenue. Electromagnetic variants are expanding most quickly into wet steam niches.
End User:
End-use verticals separate into emissions-regulated heavy process and hygiene-critical consumables production.
- Chemical:EPA Clean Air Act enforcement drives sub-metering granularity for emissions reporting. Texas and Louisiana processors replace orifice plates with thermal mass instruments.
- Energy:Combined cycle plants and district heating operators prioritize redundancy and SIL-rated safety integrity. German utilities specify dual-path verification.
- Food & Beverage:Pasteurization and sterilization demand hygienic design with 3-A sanitary standards. Direct mass measurement eliminates density calculation errors in dairy processing.
- Pharmaceutical:Steam-in-place validation requires documented metrological traceability. FDA 21 CFR Part 11 compliance elevates calibration documentation requirements.
Chemical processors dominate current procurement volume. Food and beverage applications are climbing the fastest on regulatory hygiene mandates.
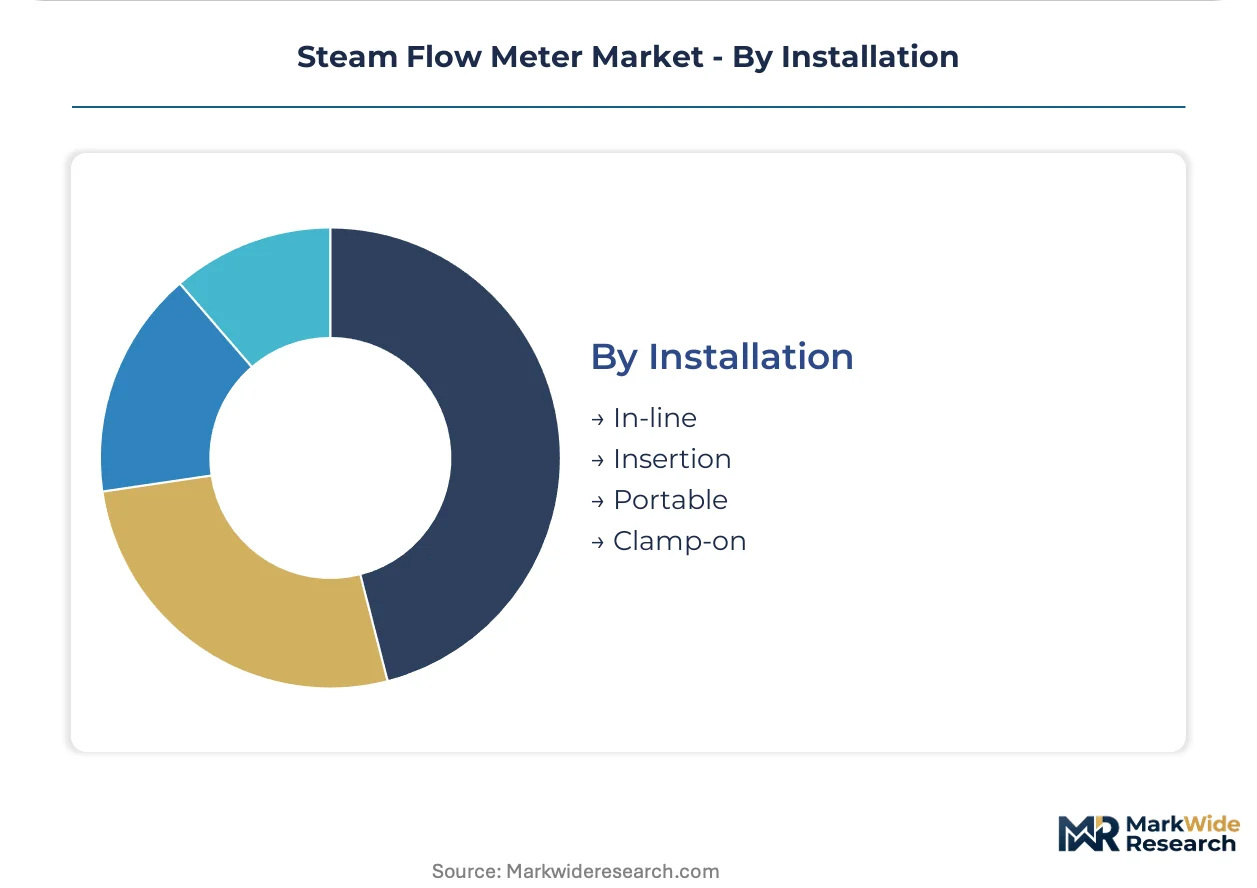
Installation:
Installation geometry determines project economics, with permanent in-line configurations capturing lifecycle value and temporary clamp-on formats serving diagnostic applications.
- In-line:Flanged and wafer-body meters integrate permanently into piping with maximum accuracy. Greenfield chemical plants in Gujarat specify these for baseline metrology.
- Insertion:Retractable probe configurations enable hot-tap installation without process shutdown. Refinery turnaround schedules favor these for maintenance windows.
- Portable:Battery-powered transit-time ultrasonic sets serve verification and dispute resolution. Third-party metrology labs deploy these for ISO 17025-accredited loop checks.
- Clamp-on:External transducer mounting eliminates pressure boundary penetration. Aging infrastructure assessments in Japan's Osaka industrial zone utilize these for non-invasive surveys.
In-line meters retain the revenue base. Clamp-on configurations are gaining share fastest on retrofit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial corridors while Texas Gulf Coast processors absorb premium thermal mass meter costs under EPA enforcement timelines. Japan's calibration infrastructure scarcity creates service bottlenecks that inflate maintenance contracts. India's greenfield installations bypass legacy switching friction entirely.
United States
Texas and Louisiana chemical processors face EPA Clean Air Act sub-metering mandates that differential pressure infrastructure cannot satisfy. OSHA boiler safety standards shape certification requirements for high-temperature installations. Houston's petrochemical corridor accelerates thermal mass replacement cycles to meet emissions compliance deadlines.
Germany
Rhine-Ruhr process manufacturers prioritize energy efficiency audits flagging steam leakage and boiler optimization. EU F-Gas Regulation alignment drives heat pump retrofit instrumentation demand. Baden-Württemberg's precision engineering clusters specify thermal mass meters for direct mass measurement traceability.
Japan
Kanto and Kansai power utilities demand vortex flow meter specialization for boiler feedwater monitoring. METI industrial standards elevate SIL-rated safety integrity requirements. Osaka and Nagoya industrial zones fragment procurement by unbundling calibration contracts from hardware purchases.
India
Gujarat and Maharashtra greenfield plants deploy in-line meters without legacy orifice plate switching costs. PLI scheme incentives attract process manufacturing capacity requiring baseline metrology. National thermal power corridors specify electromagnetic technology for wet steam tolerance in coastal humidity.
China
Yangtze River Delta chemical parks expand instrumentation budgets under dual carbon goals for steam utilization optimization. GB standards and SAMR metrology rules govern domestic certification. Shandong Province's petrochemical concentration pilots Coriolis mass flow technology for superheated steam above 200°C.
Steam Flow Meter Market Competitive Environment
Concentration sits with integrated multinationals possessing Rosemount-level instrumentation platforms and thermal mass technology leadership. The vendor base stratifies across three tiers: premium-tier full-line automation suppliers, mid-tier European specialists with Proline-equivalent thermal platforms, and regional fabricators serving cost-sensitive utility markets. Strategic moves center on IIoT-enabled predictive maintenance subscription models and third-party calibration service partnerships that fragment traditional OEM service margins.
Among the named players, Emerson Electric Co., Endress+Hauser AG, and Yokogawa Electric Corporation occupy positions exemplifying the premium-tier archetype. Emerson's Milwaukee-based operations represent North American full-line automation dominance. Endress+Hauser's Swiss-German structure exemplifies European thermal mass specialization. Yokogawa anchors Asian demand concentration through its Tokyo-listed industrial electronics focus. These three sit within the integrated multinational tier where hardware-platform breadth determines competitive positioning.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Endress+Hauser AG |
| ABB Ltd. |
| Siemens AG |
| Yokogawa Electric Corporation |
| Honeywell International Inc. |
| Krohne Messtechnik GmbH |
| Badger Meter, Inc. |
| Azbil Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day sensor housing lead times for 316L stainless steel assemblies have compressed procurement flexibility and handed pricing leverage to German and Japanese mills serving thermal mass meter manufacturers. This inventory pressure concentrates cost pass-through capability among integrated multinationals while regional fabricators absorb margin erosion.
Pricing Analysis
Configured-to-order thermal mass meters command 35-50% premiums over standard orifice plate configurations due to application-specific calibration and high-temperature sensor matching. Three-tier pricing structure across premium, standard, and economy levels segments by SIL safety rating and calibration documentation depth. Cost compression in economy-tier mechanical meters is intensifying because Indian and Chinese regional suppliers are expanding 304-grade stainless capacity. Chemical processors in Texas and Louisiana show least price sensitivity due to EPA compliance deadlines, while municipal utilities in developing markets prioritize capital containment over precision specifications.
Supply Chain Analysis
Just-in-time inventory strategies dominate sensor electronics procurement, while strategic stockpiling of 316L and 304 stainless steel persists among German thermal mass specialists hedging alloy price volatility. Manufacturing concentration sits in Germany, Japan, and Switzerland for precision sensor assemblies, with China expanding capacity in standard differential pressure castings. Supply chains draw from nickel ore processing in Indonesia, specialty steel rolling in South Korea, and semiconductor-grade sensor fabrication in Taiwan. Single-source vulnerability concentrates in high-temperature platinum RTD elements sourced from Japanese metallurgical specialists. Distribution runs through authorized instrumentation distributors serving EPC contractors and direct OEM procurement for utility-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated chemical processing conglomerates in Texas and Louisiana that negotiate enterprise-wide instrumentation frameworks, fragmenting vendor pricing discipline.
For Market Incumbents: Secure calibration service capacity in Osaka and Nagoya before third-party metrology labs capture ISO 17025-accredited loop verification contracts. Deepen backward integration into 316L stainless sensor housings to offset alloy price volatility and defend margins against emerging Asian fabricators. For New Entrants and Emerging Players: Anchor in India's Gujarat and Maharashtra greenfield chemical corridors where PLI scheme incentives eliminate legacy orifice plate switching friction. Target wet steam electromagnetic niches in Finnish pulp and paper drying lines where vortex shedding accuracy degrades. Pursue clamp-on ultrasonic retrofit opportunities in Japan's aging Osaka industrial zone infrastructure assessments. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA Clean Air Act enforcement and EU F-Gas Regulation alignment create durable replacement demand independent of industrial capex cycles. Target mid-tier European thermal mass specialists with Proline-equivalent technology platforms and established CE marking pathways. Monitor stainless steel alloy price spreads as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Housings | Captive 316L stainless supply insulates German manufacturers from alloy price volatility. |
| Third-Party Calibration Partnership | Osaka and Nagoga labs fragment OEM service margins while expanding addressable verification market. |
| Digital Twin Platform Integration | IIoT-enabled thermal mass meters open subscription revenue models for predictive maintenance. |
| Greenfield Plant Specification Capture | Gujarat and Maharashtra installations bypass legacy orifice plate infrastructure lock-in entirely. |
| Wet Steam Electromagnetic R&D | Finnish pulp and paper pilots validate condensate-tolerant Faraday induction technology. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across plant engineering, maintenance management, and procurement functions at chemical processors, power utilities, and food manufacturers. Secondary validation drew from EPA enforcement databases, EU ETS transaction registries, SEC 10-K instrumentation segment disclosures, and German VDMA industry association statistics. Bottom-up unit shipment estimates triangulated against top-down energy efficiency audit spending patterns.
Across the analysis window, projections segmented by measurement principle, steam condition tolerance, end-use vertical, and regional regulatory cluster. CAGRs derived from replacement cycle analysis of installed orifice plate bases against thermal mass adoption curves. Forecast inputs incorporated stainless steel price indices, EPA compliance deadline schedules, and district heating retrofit pipeline data.
Underlying assumptions cover sustained EPA Clean Air Act enforcement intensity and EU F-Gas Regulation phase-down timelines, with deviation risk concentrated in stainless steel alloy price spikes and calibration technician availability bottlenecks. Revision becomes warranted when thermal mass meter cost parity against differential pressure alternatives crosses threshold in refinery applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Battery Free Sensor Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Rangefinder Market