
 Middle East and Africa Wireless Sensors Market | 2026-2036
Middle East and Africa Wireless Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Wireless Sensors Market Foresight
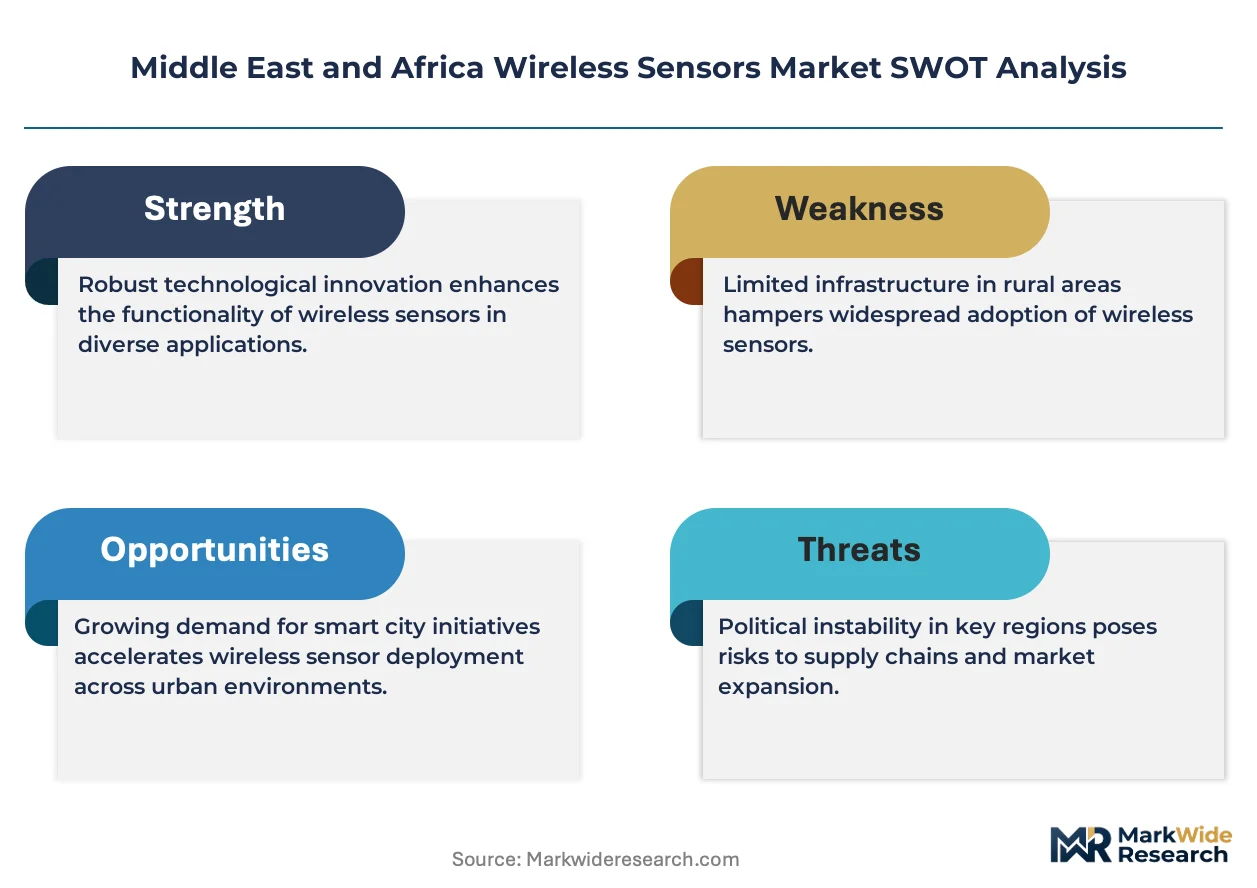
Buyer concentration among Middle Eastern oil and gas operators is expanding as national energy companies consolidate field instrumentation procurement under centralized digital transformation programs. Honeywell International Inc leverages its distributed control systems heritage to anchor wireless sensor contracts across Saudi Aramco's upstream facilities. Emerson Electric Co competes through its Plantweb digital ecosystem, which sustains long-term service relationships with Abu Dhabi National Oil Company. Siemens AG differentiates by integrating wireless sensing into power generation asset management across Eskom's South African fleet.
Wireless sensors are self-contained measurement nodes that transmit data via radio frequency protocols without physical cabling, typically operating on battery or energy-harvesting power with transmission ranges from ten meters to several kilometers depending on protocol and environment. These devices serve industrial process monitoring, environmental surveillance, and infrastructure automation by eliminating wiring costs in hazardous or remote locations. Temperature sensors dominate product type revenue across the region's petrochemical complexes, while Bluetooth-enabled devices represent the fastest-growing technology segment due to smartphone integration in building automation. Industrial automation applications command the largest application share, though smart home deployments in Gulf urban developments show the steepest growth trajectory.
Saudi Arabia's Communications and Information Technology Commission governs radio spectrum allocation for industrial IoT devices, while South Africa's ICASA enforces type approval requirements that filter non-compliant hardware from national infrastructure projects. The UAE's Telecommunications and Digital Government Regulatory Authority recently streamlined certification pathways for low-power wide-area sensors used in utility metering. Stakeholders must monitor spectrum harmonization negotiations between Gulf regulators and African telecommunications unions, as divergent frequency allocations threaten cross-border equipment standardization and supplier scale economies.
Market Dynamics
The Middle East and Africa Wireless Sensors Market is experiencing structural transformation as Gulf national oil companies consolidate field instrumentation procurement under centralized digital transformation programs, compressing vendor selection cycles and elevating systems integration capabilities over component sales.
Growth Catalysts
- NEOM Infrastructure Mandates:Saudi Arabia's megacity project requires wireless sensing networks for smart infrastructure, creating sustained demand for temperature and pressure monitoring nodes across its linear city and industrial zones.
- Radio Equipment Compliance Acceleration:South Africa's National Regulator for Compulsory Specifications enforces type approval requirements that filter non-compliant hardware, accelerating certified sensor deployment in national infrastructure tenders.
- Bluetooth-Enabled Building Automation:Smartphone integration capabilities are displacing proprietary handheld configurators in Gulf urban developments, reducing commissioning costs for facility management operators.
Market Restraints
- Spectrum Fragmentation Risk:Divergent frequency allocations between Gulf regulators and African telecommunications unions threaten cross-border equipment standardization, forcing suppliers to maintain multiple hardware variants.
- Battery Supply Concentration:Lithium primary cell sourcing concentrates in East Asian manufacturing clusters, exposing MEA-deployed sensors to input cost volatility and extended lead times.
- LoRaWAN Range Limitations:Sub-GHz propagation constraints in dense petrochemical complexes necessitate costly mesh repeater deployments, compressing total cost of ownership advantages against wired alternatives.
Strategic Opportunities
- UAE Utility Metering Streamlining:The Telecommunications and Digital Government Regulatory Authority recently streamlined certification pathways for low-power wide-area sensors, reducing time-to-revenue for smart grid entrants.
- Energy Harvesting Convergence:Thermoelectric and photovoltaic harvesting modules are converging with vibration-powered nodes to eliminate battery maintenance in remote pipeline monitoring applications.
- Jubail Economic City Expansion:Saudi Arabia's industrial hub is integrating wireless sensing into masterplanned infrastructure, creating captive demand for environmental and safety monitoring networks.
Industry Challenges
- Radio Frequency Engineering Talent Scarcity:Field deployment of industrial IoT networks requires specialized expertise in antenna placement and propagation modeling that remains concentrated in vendor engineering teams.
- Legacy DCS Integration Complexity:Honeywell and Emerson control system architectures demand protocol gateway development for seamless wireless sensor data ingestion, extending project timelines.
- ICASA Certification Timelines:South Africa's type approval process creates six-to-nine month delays between product completion and market entry, compressing effective product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Wireless Sensors Market |
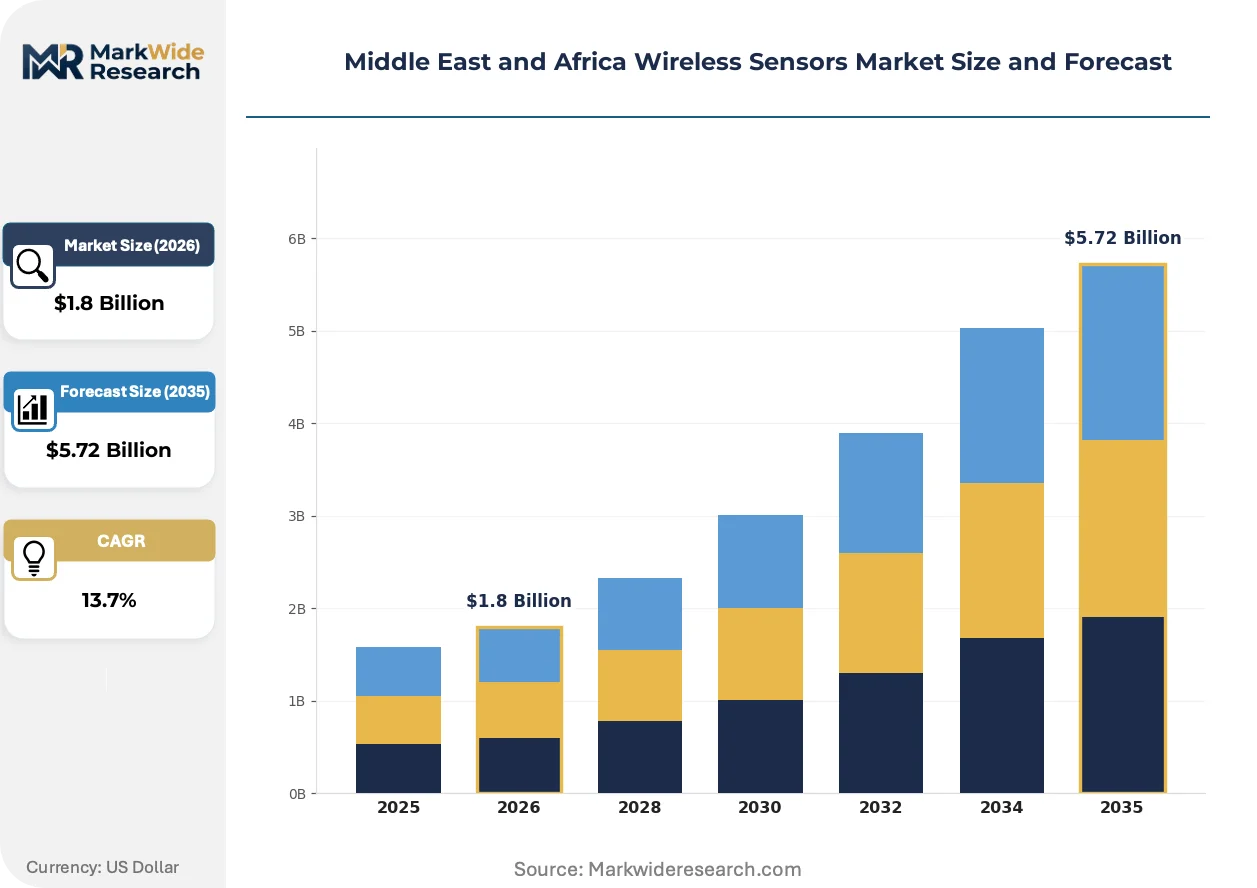
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Humidity Sensors Technology: RFID, Zigbee, Bluetooth, Wi-Fi End User: Healthcare, Agriculture, Automotive, Building Automation Application: Environmental Monitoring, Industrial Automation, Smart Homes, Wearable Devices |
| Companies Covered | Honeywell International Inc, Emerson Electric Co, Texas Instruments Incorporated, ABB Ltd, Pasco Scientific, Schneider Electric, Siemens AG, Monnit Corporation, Phoenix Sensors LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Wireless Sensors Market Shifts & Advancements
Wireless sensor architectures across the Middle East and Africa are pivoting from standalone measurement nodes toward edge-computing platforms capable of local analytics, driven by bandwidth constraints in remote oilfield and mining deployments.
Energy harvesting technologies are converging with ultra-low-power microcontrollers to enable perpetual operation in pipeline and tank farm applications. Saudi Aramco's upstream facilities are piloting thermoelectric generators on steam injection wells, eliminating battery replacement logistics in hazardous areas. This convergence is compressing lifecycle service contract margins for traditional instrumentation suppliers.
South Africa's ICASA and Saudi Arabia's Communications and Information Technology Commission are harmonizing industrial IoT spectrum allocations in the 800-900 MHz bands, reducing hardware SKU complexity for regional suppliers. The regulatory alignment enables economies of scale for low-power wide-area module manufacturers. Petrochemical complexes in Jubail and Ras Laffan are the primary beneficiaries, deploying unified sensor platforms across multi-site operations.
Buyer concentration among Gulf national oil companies is consolidating maintenance, repair and operations procurement under long-term framework agreements. Independent system integrators are displacing traditional distributor networks in Abu Dhabi and Doha, capturing margin through bundled deployment and calibration services. This channel shift is most visible in Saudi Arabia, where Saudi Aramco's In-Kingdom Total Value Add program mandates local content in sensor installation and commissioning workflows.
Middle East and Africa Wireless Sensors Market Segmentation
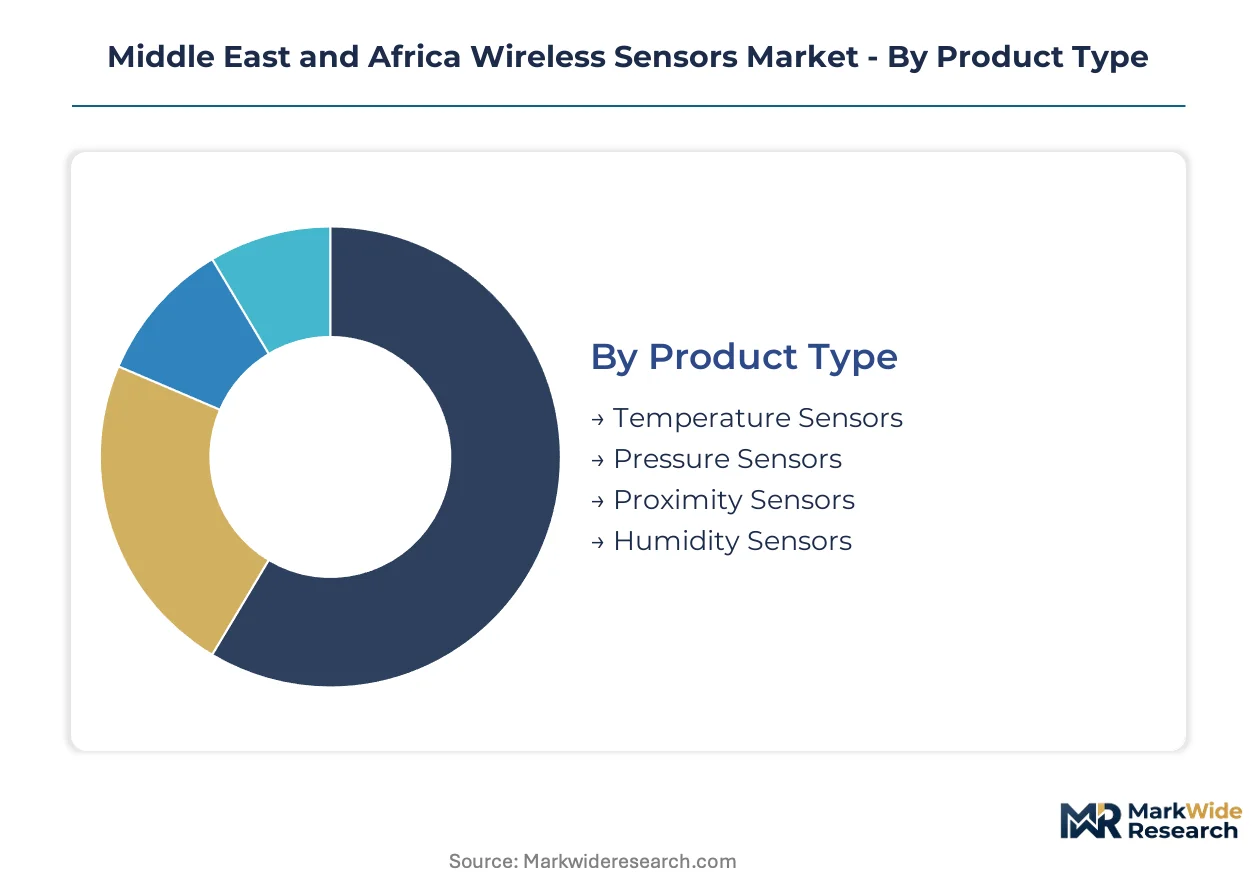
Wireless sensor deployment across the Middle East and Africa fragments across distinct technical specifications, each carrying different capital requirements and integration complexity. Procurement teams in Saudi Aramco facilities and South African mining operations prioritize segments based on hazardous area certification costs and legacy system compatibility rather than unit price alone.
Product Type:
Capital intensity varies sharply across sensor categories, with hazardous-area-rated pressure transmitters requiring five-figure certification investments per SKU while standard temperature probes deploy with minimal regulatory overhead.
- Temperature Sensors:Thermocouple and RTD-based nodes dominate petrochemical process streams across Jubail and Ras Laffan complexes. Saudi Aramco's upstream steam injection wells specify these for continuous vessel monitoring, with thermoelectric harvesting eliminating battery logistics in hazardous zones.
- Pressure Sensors:Differential and absolute pressure variants command premium positioning due to SIL-rated safety instrumented system requirements. Abu Dhabi National Oil Company mandates these for wellhead integrity monitoring, compressing vendor selection to suppliers with IECEx certification in-house.
- Proximity Sensors:Inductive and capacitive detection nodes serve rotating machinery protection in Eskom's South African power generation fleet.
- Humidity Sensors:Capacitive polymer and resistive ceramic elements support HVAC optimization in Dubai's commercial tower developments.
Most installed capacity flows through Temperature Sensors. Expansion is steepest in Pressure Sensors.
Technology:
Protocol selection determines infrastructure overlay costs, with sub-GHz mesh networks requiring dedicated gateway hardware while unlicensed 2.4 GHz solutions piggyback on existing enterprise Wi-Fi.
- Bluetooth:Low-energy 5.x implementations displace proprietary handheld configurators in Gulf facility management workflows. Dubai's smart building mandates accelerate smartphone-commissioned sensor deployment, collapsing commissioning timelines from days to hours.
- Wi-Fi:IEEE 802.11ah (HaLow) variants penetrate concrete-intensive hospital and university campuses across Johannesburg and Cairo with extended range over standard 802.11n.
- RFID:Passive UHF and active 433 MHz tags track high-value equipment in Qatar's LNG liquefaction trains.
- Zigbee:Mesh-native 3.0 stacks serve residential energy management in Saudi Arabia's NEOM residential districts.
Bluetooth captures the dominant share of new node shipments. Wi-Fi is climbing fastest in institutional deployments.
End User:
Customer-type economics separate capital-project buyers with multi-year framework agreements from spot purchasers in fragmented agricultural cooperatives.
- Building Automation:Integrated mechanical-electrical systems specify wireless sensing for zone-level climate control across UAE commercial developments. Dubai's mandatory smart building codes require real-time occupancy and air quality feedback, locking in recurring sensor refresh cycles.
- Healthcare:Medical-grade temperature and humidity monitoring satisfies Joint Commission International accreditation for Saudi hospital networks. Cold chain verification for pharmaceutical distribution concentrates demand in Riyadh and Jeddah logistics hubs.
- Automotive:Tire pressure and battery management systems integrate wireless telemetry in North African vehicle assembly plants.
- Agriculture:Soil moisture and weather station networks serve irrigation optimization in Egypt's Nile Delta farming cooperatives.
Building Automation channels the majority of current procurement volume. Healthcare is expanding most quickly as hospital accreditation standards tighten.
Application:
Use-case maturity separates established process control environments with documented ROI models from emerging consumer-facing deployments with unproven monetization paths.
- Industrial Automation:Process variable monitoring in hydrocarbon processing satisfies functional safety requirements through wirelessHART and ISA100.11a implementations. Saudi Aramco's In-Kingdom Total Value Add program mandates local installation and calibration workflows, reshaping channel economics.
- Environmental Monitoring:Air quality and emissions sensing networks support regulatory compliance in South Africa's Highveld Priority Area. Eskom's power station stack monitoring drives continuous particulate and SO2 sensor deployment.
- Smart Homes:Residential security and energy management nodes penetrate Gulf urban developments with high disposable income demographics.
- Wearable Devices:Personal health and safety monitors serve lone worker protection in remote mining and pipeline inspection roles.
Industrial Automation absorbs the greatest sensor volume. Environmental Monitoring is gaining share fastest as South African air quality enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's wireless sensor procurement dwarfs South Africa's installed base by an order of magnitude, yet both markets exhibit divergent regulatory maturities that shape vendor entry strategies.
Saudi Arabia
NEOM and Jubail Economic City generate concentrated demand for smart infrastructure sensing. The Communications and Information Technology Commission governs radio spectrum allocation for industrial IoT devices, streamlining deployment protocols. Riyadh's industrial corridors anchor upstream oilfield instrumentation contracts under Saudi Aramco's centralized digital transformation programs.
United Arab Emirates
Dubai's mandatory smart building codes drive Bluetooth-enabled sensor deployment in commercial towers. The Telecommunications and Digital Government Regulatory Authority streamlined certification pathways for low-power wide-area sensors used in utility metering. Abu Dhabi's industrial zones concentrate petrochemical process monitoring networks serving ADNOC facilities.
South Africa
Eskom's power generation fleet sustains proximity sensor demand for rotating machinery protection. The National Regulator for Compulsory Specifications enforces type approval requirements that filter non-compliant hardware from national infrastructure tenders. The Highveld Priority Area concentrates air quality monitoring networks for regulatory compliance.
Qatar
LNG liquefaction trains deploy RFID tracking for high-value equipment monitoring. The country's telecommunications regulator maintains spectrum harmonization with Gulf Cooperation Council standards. Ras Laffan Industrial City anchors unified sensor platforms across multi-site petrochemical operations.
Egypt
Nile Delta farming cooperatives pilot soil moisture and weather station networks for irrigation optimization. The national telecommunications regulator aligns industrial IoT frequency allocations with regional harmonization initiatives. Cairo's hospital networks drive medical-grade temperature monitoring for cold chain verification.
Middle East and Africa Wireless Sensors Market Competitive Landscape
Gulf-based systems integrators anchor one tier; European and North American component specialists hold established positions through legacy control system relationships. Market structure concentrates around national oil company framework agreements that compress vendor selection cycles. Three archetypes dominate: diversified industrial conglomerates with distributed control heritage, pure-play wireless instrumentation specialists, and regional system integrators capturing installation margins. Competitive moves center on local content compliance and long-term service contract capture.
Within the diversified industrial tier, Honeywell International Inc and Emerson Electric Co exemplify control system heritage strategies. Honeywell occupies a position leveraging distributed control systems integration for upstream oilfield contracts. Emerson anchors relationships through digital ecosystem platforms serving national oil company facilities. Siemens AG represents the European industrial archetype with power generation asset management positioning. Texas Instruments Incorporated sits within the semiconductor supplier tier providing wireless connectivity modules to regional device manufacturers.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Emerson Electric Co |
| Texas Instruments Incorporated |
| ABB Ltd |
| Pasco Scientific |
| Schneider Electric |
| Siemens AG |
| Monnit Corporation |
| Phoenix Sensors LLC |
| Others |
Supply & Pricing Matrix
Radio frequency engineering talent concentration in South Africa's Gauteng province creates labor-cost differentials that widen pricing-tier spreads between certified industrial-grade sensors and uncertified alternatives.
Pricing Analysis
Capacity additions in China's lithium primary cell manufacturing are reshaping price floors for battery-powered sensor nodes across the Middle East and Africa. Three-tier pricing structure across premium, standard, and economy levels separates IECEx-certified pressure transmitters for Saudi Aramco wellheads from Bluetooth-enabled temperature nodes for Gulf smart buildings. Price differentiation hinges on hazardous area certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because East Asian module suppliers are absorbing margin to secure framework agreement volumes with national oil companies. Spot purchasers in Egyptian agricultural cooperatives exhibit highest price sensitivity, while Saudi Aramco's centralized procurement demonstrates lowest sensitivity due to total cost of ownership framing.
Supply Chain Analysis
Single-source vulnerability sits with East Asian lithium primary cell suppliers, exposing MEA-deployed sensors to input cost volatility and extended replenishment cycles. Component sourcing draws from China for wireless connectivity modules, South Korea for advanced microcontrollers, and Taiwan for precision sensing elements. Raw material dependencies center on lithium carbonate, rare earth magnets for energy harvesting, and ceramic substrates for humidity sensing elements. Supply chain risk concentrates in logistics chokepoints through the Strait of Hormuz, where customs delays disrupt just-in-time delivery to Jubail and Ras Laffan petrochemical complexes. Distribution runs through Dubai-based regional hubs serving Gulf national oil companies, with Johannesburg warehouses supplying South African mining and power generation sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with South Africa's ICASA type approval mandates and Saudi Arabia's CITC spectrum harmonization driving certified sensor demand across infrastructure tenders.
For Market Incumbents: Anchor long-term service relationships through Plantweb-style digital ecosystems that capture calibration and maintenance revenue from Abu Dhabi National Oil Company facilities. Defend against pure-play wireless specialists by deepening backward integration into energy harvesting module production, eliminating battery supply exposure. Prioritize certification investment in IECEx and ATEX variants to compress vendor selection cycles in Saudi Aramco's In-Kingdom Total Value Add program. For New Entrants and Emerging Players: Launch via smartphone-commissioned Bluetooth sensor platforms targeting Dubai's mandatory smart building code compliance, collapsing traditional distributor margins. White-space opportunity concentrates in Egypt's Nile Delta agricultural cooperatives, where soil moisture networks remain underpenetrated by industrial-grade suppliers. Target healthcare cold chain verification in Riyadh and Jeddah logistics hubs, where Joint Commission International accreditation tightens medical-grade monitoring requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with captive installation workflows in Doha and Abu Dhabi, positioned to consolidate as channel economics shift away from traditional distributors. Five-to-ten year viability favors suppliers with demonstrated local content compliance in Saudi Aramco's procurement frameworks. Signal to monitor: harmonization completion between Gulf regulators and African telecommunications unions on 800-900 MHz spectrum allocations, which would enable hardware SKU consolidation and supplier scale economies.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Streamlining | UAE's TDRA reduced LPWA sensor approval timelines, accelerating smart grid entrant revenue recognition. |
| Energy Harvesting Convergence | Thermoelectric and photovoltaic modules eliminate battery maintenance in Saudi Aramco steam injection wells. |
| Local Content Compliance | In-Kingdom Total Value Add mandates reshape channel economics toward Saudi-based installation workflows. |
| Spectrum Harmonization | CITC-ICASA alignment on 800-900 MHz bands reduces hardware SKU complexity for regional suppliers. |
| Digital Ecosystem Integration | Plantweb and similar platforms capture long-term service contracts from national oil company frameworks. |
Research Methodology
Coverage spans the Gulf Cooperation Council, South Africa, and Egypt, with primary inputs from each region's dominant industrial clusters. The approach combines structured interviews with instrumentation procurement managers at Saudi Aramco and ADNOC facilities, regulatory affairs leads at South Africa's National Regulator for Compulsory Specifications, and system integration specialists in Dubai and Doha. Secondary validation draws from ICASA type approval databases, CITC spectrum allocation filings, SEC 10-K disclosures from listed industrial conglomerates, and customs records tracking wireless module imports through Jebel Ali and Durban ports. Bottom-up sensor shipment estimates triangulate against top-down infrastructure spending projections from national oil company digital transformation programs.
Granularity-level modeling disaggregates volume and value across product type, technology protocol, end-user vertical, and application use-case throughout the forecast period. Segmentation dimensions include hazardous area certification tier, wireless protocol selection, and buyer archetype distinguishing framework agreement purchasers from spot procurement. CAGRs derive from logistic diffusion curves fitted to infrastructure deployment timelines, cross-referenced with regulatory milestone schedules. Industry-specific inputs incorporate NEOM construction phase commitments, Eskom power station stack monitoring mandates, and Dubai smart building code compliance deadlines.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Strait of Hormuz shipping lanes, abrupt lithium supply embargoes, and unilateral spectrum reallocation by national regulators. Forecasts reflect assumptions about continued Gulf-African regulatory harmonization progress and stable battery chemistry cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Europe Smart Air Purifier Market