
 Global Optogenetics Actuators and Sensors Market | 2026-2036
Global Optogenetics Actuators and Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optogenetics Actuators and Sensors Market Foresight
Platform licensing revenue is reshaping competitive economics in optogenetics hardware as vendors monetize control software and light-delivery protocols separately from physical devices. Coherent Inc. leverages its laser source expertise to anchor supply relationships with academic core facilities. Thorlabs, Inc. competes through vertically integrated micro-LED fabrication that sustains price positioning in waveguide-coupled actuator modules. Danaher Corporation extends its life sciences instrumentation footprint into optogenetic behavioral rigs through subsidiary channel networks.
Optogenetics actuators and sensors comprise genetically targeted light-responsive proteins and compatible photonic hardware that modulate cellular activity with millisecond precision across visible and near-infrared spectra. These systems enable all-optical interrogation of neural circuits without pharmacological latency, serving fundamental neuroscience and emerging therapeutic development. Channelrhodopsin-based actuators dominate installed base volumes due to established viral delivery protocols and broad spectral compatibility, while silicon photonic sensors capture expanding margin pools through foundry-scalable manufacturing and multiplexed recording density. OptoXR technology leads growth trajectories as engineered G-protein coupled receptors expand addressable cell types beyond excitable tissues into metabolic and immunological research domains.
FDA breakthrough device pathways and EMA adaptive licensing frameworks are compressing clinical validation timelines for optogenetic therapies, directly shaping R&D investment allocation across pharmaceutical end users. ISO 13485 quality management requirements and NIH guidelines on recombinant DNA research impose parallel compliance burdens that filter vendor participation toward established medical device and laboratory supply firms. Stakeholders must monitor convergence between semiconductor photonics roadmaps and neural interface material biocompatibility standards to anticipate next-generation actuator-sensor integration architectures.
Market Dynamics
NIH circuit-mapping funding priorities are compressing procurement cycles for integrated optogenetics platforms while photonics manufacturing clusters in Germany, Japan, and the United States constrain supply elasticity for waveguide-coupled modules.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated clinical validation pathways for optogenetic retinal implants compress development timelines and attract pharmaceutical R&D investment toward therapeutic applications.
- Viral Delivery Protocol Maturation:Standardized adeno-associated virus vectors for channelrhodopsin deployment reduce technical barriers in academic core facilities across neuroscience departments.
- Silicon Photonics Foundry Scaling:Semiconductor manufacturing roadmaps from Taiwan and South Korea enable multiplexed sensor density at unit economics inaccessible to discrete optical component assembly.
Market Restraints
- Recombinant DNA Research Compliance:NIH guidelines impose institutional biosafety committee oversight that extends procurement lead times for viral vector materials.
- Photonics Component Supply Concentration:Micro-LED and laser diode fabrication clusters in Japan and Germany create single-source dependencies for waveguide-coupled actuator modules.
- Near-Infrared Actuator Efficiency Ceiling:Existing opsin variants exhibit reduced photocurrent at tissue-penetrating wavelengths, limiting deep-brain interrogation without invasive fiber implantation.
Strategic Opportunities
- Metabolic Disease Research Expansion:OptoXR-engineered G-protein coupled receptors enable optogenetic control of hepatocyte and adipocyte signaling pathways previously inaccessible to excitable-tissue actuators.
- EMA Adaptive Licensing Framework:Conditional approval pathways for gene therapy-photonics combination products reduce clinical trial duration for European therapeutic developers.
- Behavioral Rig Integration Services:Unbundled software licensing and protocol customization create recurring revenue streams separate from capital equipment sales to academic buyers.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Convergent expertise in viral vector engineering, photonics hardware, and systems neuroscience remains concentrated at a limited number of academic medical centers.
- ISO 13485 Certification Burden:Medical device quality management system implementation timelines of 12-18 months filter vendor participation toward established life sciences instrumentation firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optogenetics Actuators and Sensors Market |
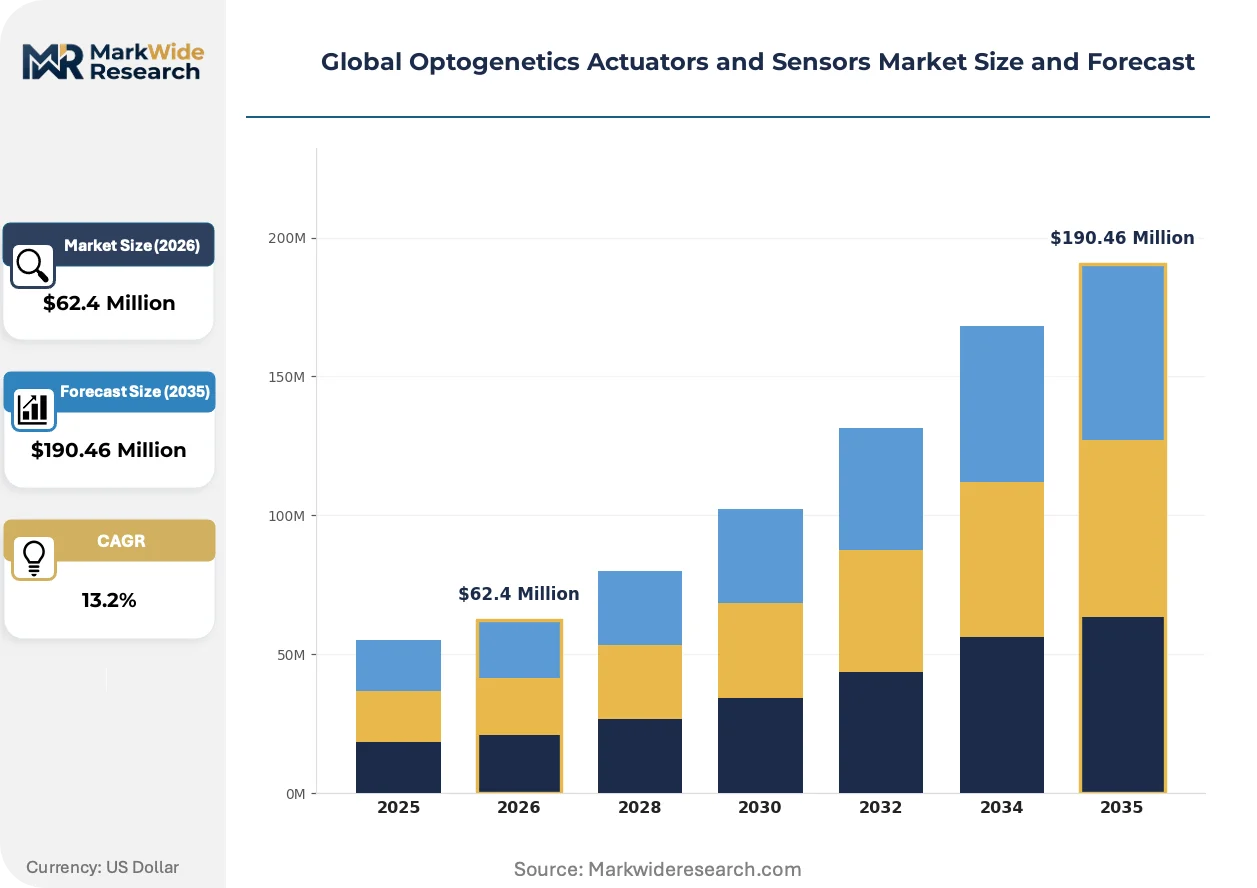
| Market Size in 2026 | $62.4 Million |
| Market Size in 2035 | $190.46 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optrodes, Micro LEDs, Waveguides, Silicon Photonic Sensors Technology: Channelrhodopsin, Halorhodopsin, Archaeorhodopsin, OptoXR Application: Neuroscience Research, Cardiac Studies, Behavioral Modulation, Retinal Prosthesis End User: Academic Institutions, Pharmaceutical Companies, Research Laboratories, Medical Device Manufacturers |
| Companies Covered | Bruker Corporation, Coherent Inc., Elliot Scientific Ltd., Noldus Information Technology BV, Merck KGaA, Thorlabs, Inc., Danaher Corporation, Thermo Fisher Scientific, Inc., The Jackson Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optogenetics Actuators and Sensors Market Shifts & Advancements
Computational control architectures are displacing analog hardware interfaces across optogenetics platforms, compressing experimental protocol development cycles while expanding accessible user bases beyond specialized photonics laboratories.
Wireless power and data telemetry is digitizing tether-free neural interface design. Academic research groups in the United States and Switzerland are adopting subcutaneous photovoltaic energy harvesting for chronically implanted LED arrays. This architecture is digitizing behavioral neuroscience by enabling naturalistic movement paradigms previously incompatible with fiber-optic tethers.
EMA's adaptive licensing framework for advanced therapy medicinal products is compressing gene therapy-photonics combination product timelines. Pharmaceutical developers are front-loading manufacturing quality discussions with notified bodies to parallelize clinical and regulatory track preparation. European ophthalmology trials for inherited retinal dystrophies represent the most responsive segment, with sponsors pre-submission briefing packages addressing photon dose-biological response correlations.
Core facility procurement committees are consolidating vendor relationships around integrated platform providers. Discrete component sourcing from multiple photonics suppliers is yielding to single-source contracts bundling light-delivery hardware, control software, and technical support. This concentration is most visible at United States research universities where shared instrumentation grant reporting requirements favor unified service-level agreements over fragmented warranty management.
Global Optogenetics Actuators and Sensors Market Segmentation
Optogenetics platforms require precise matching between light-delivery hardware and genetically encoded actuators. Segmentation reveals how procurement committees balance technical specifications against viral vector compatibility and behavioral rig integration requirements.
Product Type:
Use-case spectrum spans tethered fiber-optic implants through fully implantable wireless arrays, with each hardware category imposing distinct surgical workflow and photonics integration constraints.
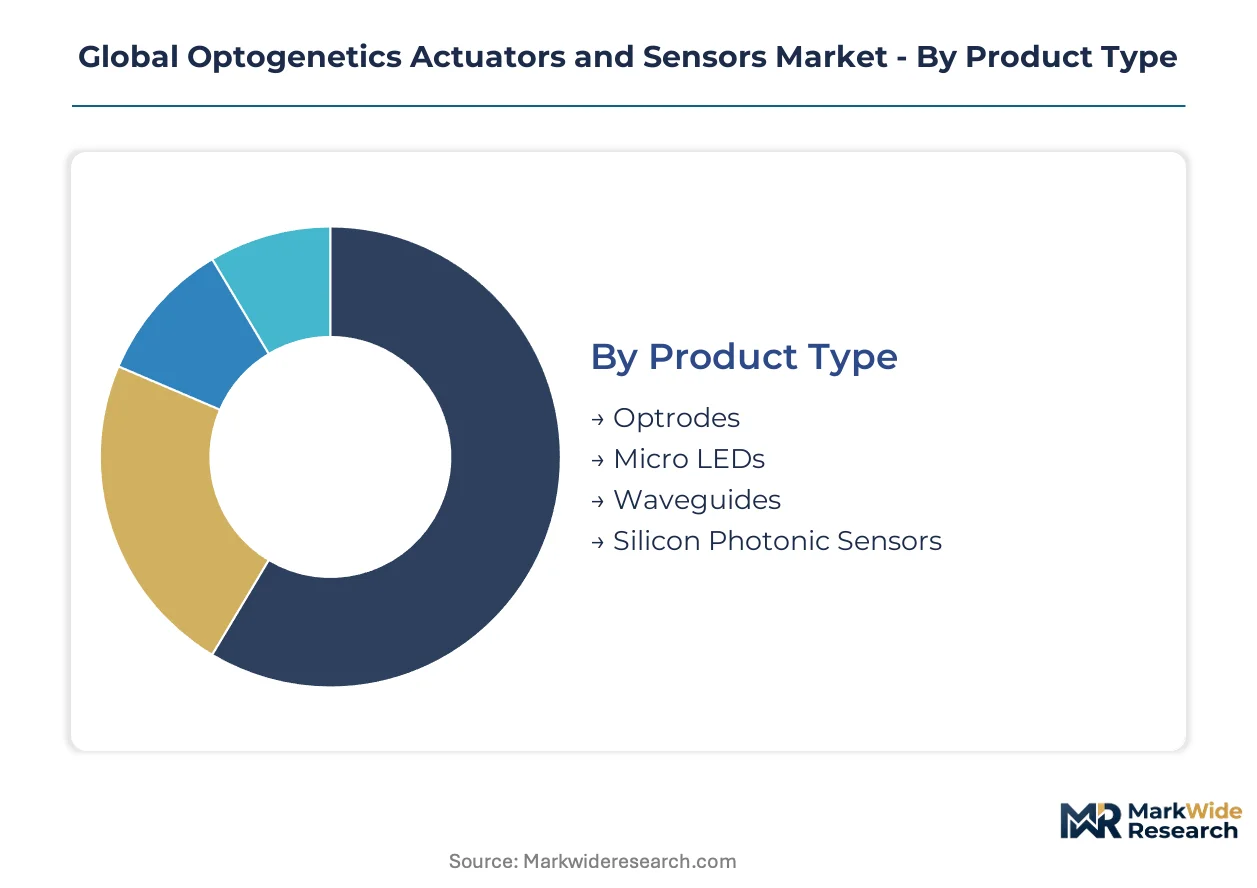
- Optrodes:These fused optical-electrical probes combine waveguide light delivery with electrophysiological recording in a single shank geometry. Demand concentrates in United States academic neuroscience departments where NIH-funded circuit-mapping initiatives require simultaneous optical stimulation and neural signal acquisition. Procurement cycles compress when bundled with institutional viral vector core services.
- Micro LEDs:Miniaturized solid-state emitters enable sub-millimeter scale implantation without external fiber tethering. German research laboratories prioritize these devices for freely moving behavioral paradigms, driven by DFG funding priorities for naturalistic movement studies. Foundry manufacturing in Taiwan and South Korea constrains supply elasticity for high-density arrays.
- Waveguides:Tapered optical fibers deliver precise illumination to deep brain structures with minimal tissue displacement.
- Silicon Photonic Sensors:Semiconductor-fabricated detector arrays enable multiplexed recording density at wafer-scale unit economics.
The dominant share belongs to Optrodes, while Micro LEDs is closing the gap fastest.
Technology:
Cost tier differentiation separates established opsin variants with mature viral packaging protocols from engineered receptor platforms commanding premium licensing fees.
- Channelrhodopsin:This blue-light-gated cation channel from Chlamydomonas reinhardtii dominates installed base volumes through standardized AAV2/5 delivery protocols. United States pharmaceutical companies deploy these actuators in high-throughput screening cascades for psychiatric drug target validation. Photocurrent reliability at 470nm wavelength supports reproducible dose-response curves.
- OptoXR:Engineered G-protein coupled receptors enable optogenetic control of intracellular signaling cascades beyond membrane depolarization. Japanese metabolic disease research programs are adopting these platforms for hepatocyte glucose regulation studies, driven by METI funding for diabetes therapeutic development. Licensing costs from Stanford and Duke University technology transfer offices filter academic access.
- Halorhodopsin:Yellow-light-activated chloride pump provides inhibitory modulation complementary to excitatory channelrhodopsins.
- Archaeorhodopsin:Proton pump variant offers alternative hyperpolarization kinetics for sustained neuronal silencing.
Channelrhodopsin retains the largest deployment footprint, though OptoXR is expanding most quickly into metabolic and immunological research domains.
Application:
Volume concentration tracks funding agency priorities, with circuit-mapping neuroscience commanding capital equipment budgets while therapeutic development drives recurring consumable demand.
- Neuroscience Research:Fundamental circuit interrogation in model organisms consumes the majority of actuator-sensor procurement volume. German Max Planck Institute core facilities standardize on integrated platforms bundling hardware, software, and viral vector logistics. EU Horizon Europe funding mechanisms require open-access data sharing that favors instrument interoperability.
- Retinal Prosthesis:Clinical translation of optogenetic vision restoration is accelerating through FDA breakthrough device pathways. Spark Therapeutics and Bionic Sight trials in the United States are establishing photon dose-biological response correlations for regulatory submission packages. Manufacturing scale-up for AAV5-Channelrhodopsin production requires ISO 13485 quality management certification.
- Cardiac Studies:Optogenetic pacing and defibrillation research in ex vivo preparations and small animal models.
- Behavioral Modulation:Closed-loop neural interfaces for psychiatric symptom management in preclinical development.
Neuroscience Research captures the dominant procurement volume, while Retinal Prosthesis is climbing the fastest toward commercial therapeutic validation.
End User:
Customer type determines procurement authority structure, with academic shared instrumentation grants favoring unified vendor relationships and pharmaceutical buyers prioritizing regulatory documentation packages.
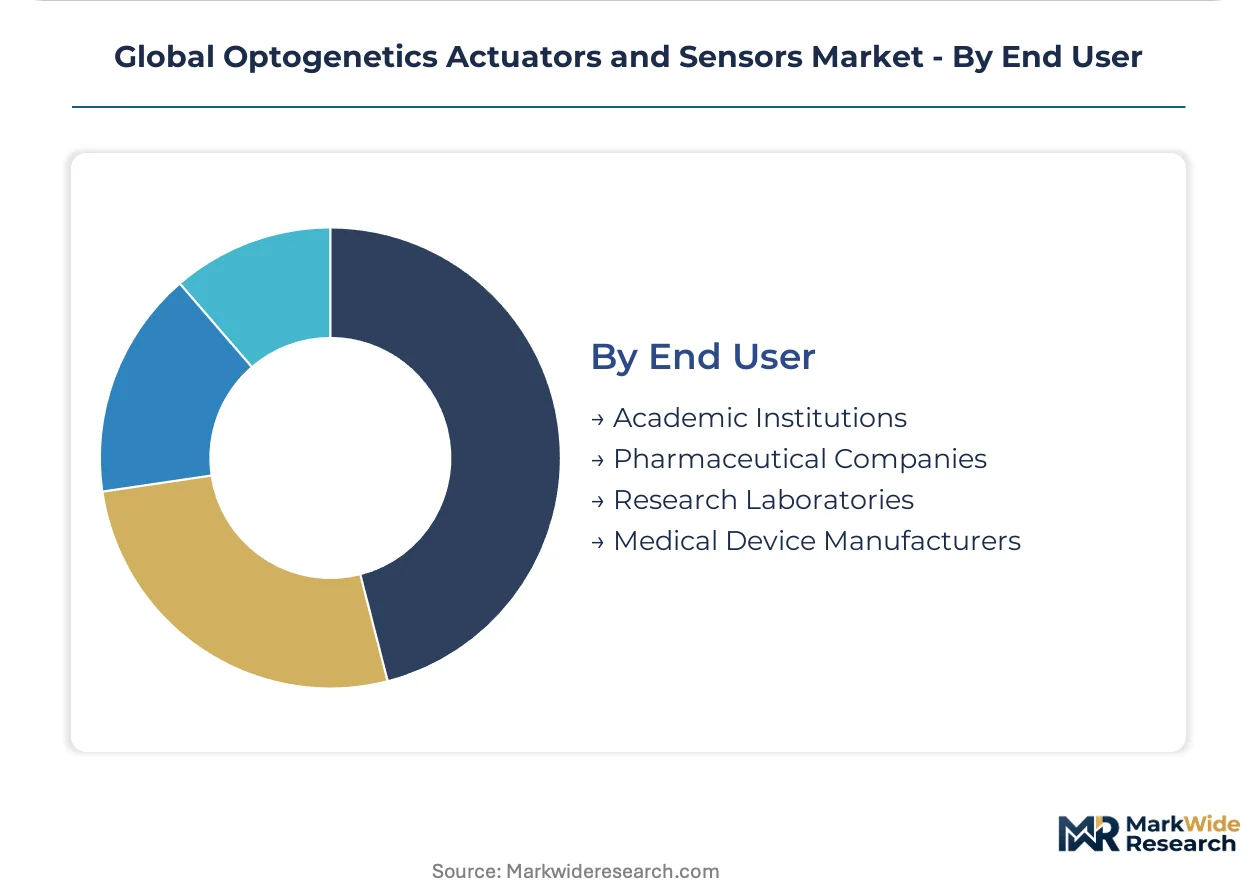
- Academic Institutions:University core facilities consolidate purchasing around platform providers offering bundled hardware, control software, and technical support agreements. United States research universities favor single-source contracts to simplify NIH shared instrumentation grant reporting requirements. Graduate student training programs drive demand for intuitive software interfaces.
- Pharmaceutical Companies:Drug developers require GMP-grade viral vectors and instrument qualification documentation for IND-enabling studies. Swiss and German pharmaceutical R&D sites are front-loading manufacturing quality discussions with EMA notified bodies to parallelize clinical and regulatory track preparation. Optogenetic target validation contracts command premium pricing for exclusive access windows.
- Research Laboratories:Independent investigator-led groups with discrete component sourcing flexibility.
- Medical Device Manufacturers:OEM suppliers integrating optogenetic subsystems into broader therapeutic platforms.
Academic Institutions maintain the largest aggregate procurement volume, though Pharmaceutical Companies are gaining share fastest as therapeutic pipelines mature toward clinical validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for optogenetics hardware varies sharply by geography. Academic buyers in Germany absorb premium pricing for integrated platforms, while United States procurement committees drive hard bargains through consolidated vendor relationships. Japanese pharmaceutical developers prioritize regulatory documentation over unit cost, creating tiered demand segmentation.
United States
NIH circuit-mapping initiatives compress procurement cycles for integrated optogenetics platforms across academic neuroscience departments. FDA breakthrough device designations for retinal implants accelerate clinical validation timelines and attract pharmaceutical R&D investment. Boston and San Diego photonics clusters anchor supply relationships with viral vector core facilities.
Germany
Max Planck Institute core facilities standardize on bundled hardware-software platforms driven by DFG funding priorities for naturalistic movement studies. EMA adaptive licensing frameworks for gene therapy-photonics combinations reduce clinical trial duration for European therapeutic developers. Munich and Heidelberg manufacturing clusters constrain supply elasticity for waveguide-coupled actuator modules.
Japan
METI funding for diabetes therapeutic development drives adoption of OptoXR platforms in metabolic disease research programs. PMDA consultation pathways for regenerative medicine products shape front-loaded manufacturing quality discussions. Tokyo-Yokohama photonics fabrication clusters support integrated actuator-sensor supply chains for domestic pharmaceutical developers.
Switzerland
Swiss pharmaceutical R&D sites command premium pricing for GMP-grade viral vectors and instrument qualification documentation. Swissmedic pre-submission briefing protocols parallelize clinical and regulatory track preparation for ophthalmology trials. Basel and Zurich clusters concentrate cross-disciplinary expertise in viral vector engineering and systems neuroscience.
United Kingdom
UK Research and Innovation funding mechanisms prioritize open-access data sharing that favors instrument interoperability across university core facilities. MHRA innovation passports for novel technology combinations streamline regulatory engagement for emerging therapeutic platforms. Cambridge and Oxford behavioral neuroscience groups adopt wireless telemetry architectures for naturalistic movement paradigms.
Global Optogenetics Actuators and Sensors Market Competitive Landscape
Capability concentration sits with specialized photonics firms; scale advantage sits with diversified life sciences conglomerates. The vendor base organizes around three strategic archetypes: laser source specialists anchoring supply relationships, vertically integrated micro-LED fabricators sustaining price positioning, and platform providers bundling hardware with control software. Dominant competitive moves include strategic partnerships with academic core facilities and technology licensing from university technology transfer offices.
Among diversified instrumentation conglomerates, Danaher Corporation and Thermo Fisher Scientific occupy positions leveraging subsidiary channel networks into optogenetic behavioral rigs. Coherent Inc. exemplifies the laser source specialist archetype, anchoring supply relationships through photonics expertise. Thorlabs, Inc. represents vertically integrated fabrication capability in waveguide-coupled modules.
| Leading Market Players |
|---|
| Bruker Corporation |
| Coherent Inc. |
| Elliot Scientific Ltd. |
| Noldus Information Technology BV |
| Merck KGaA |
| Thorlabs, Inc. |
| Danaher Corporation |
| Thermo Fisher Scientific, Inc. |
| The Jackson Laboratory |
| Others |
Supply & Pricing Matrix
Trans-Pacific air freight corridors from Taiwan and South Korea into the United States impose cost volatility that amplifies price spreads between integrated platform bundles and discrete component sourcing, compressing margins for academic buyers while reinforcing premium positioning for vendors with captive photonics fabrication.
Pricing Analysis
After-sales revenue from software licensing and protocol customization drives lifetime value more than hardware margins. A three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 13485 certification status and viral vector core access. Pricing pressure stems from DFG and NIH grant compression forcing procurement committees toward consolidated vendor relationships. Academic core facilities exhibit highest price sensitivity, while Swiss pharmaceutical developers absorb premiums for GMP-grade documentation.
Supply Chain Analysis
Single-source vulnerability for micro-LED and laser diode fabrication concentrates in Japan and Germany, with Taiwan and South Korea anchoring foundry-scale silicon photonic sensor production. Waveguide-grade optical fiber draws from specialty glass manufacturers in the United States and Germany. Tariff exposure between East Asian semiconductor hubs and North American end markets threatens cost predictability for high-density LED arrays. Distribution runs through academic core facility procurement committees and pharmaceutical GPO contracts rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NIH funding cycles and pharmaceutical R&D budget resets position this market in early-stage cyclical recovery, with circuit-mapping grant awards and breakthrough device designations serving as the primary demand pulse.
For Market Incumbents: Insulate installed base relationships by embedding control software into multi-year service agreements that raise switching costs for academic core facilities. Captive production of AAV packaging vectors in ISO 13485-certified facilities defends against emerging contract manufacturing entrants. Deepen backward integration into gallium nitride epitaxy for micro-LED fabrication to secure supply continuity against Japanese and German fabrication bottlenecks.
For New Entrants and Emerging Players: Pursue metabolic disease research programs in Japan and Switzerland where OptoXR platform penetration remains below neuroscience saturation. Target hepatocyte glucose regulation studies as the most penetrable application segment given METI funding priorities. Lead with unbundled software licensing and protocol customization services to circumvent capital equipment procurement cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to monetize non-core photonics instrumentation divisions. Long-term viability hinges on therapeutic pipeline maturation toward FDA and EMA approval rather than academic hardware replacement cycles. Monitor FDA breakthrough device designation announcements as the critical inflection signal for pharmaceutical R&D commitment scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Software Licensing Unbundling | Recurring revenue streams from control protocol subscriptions decouple vendor economics from capital equipment cycles. |
| ISO 13485 Certification Investment | Quality management certification filters vendor participation toward established medical device supply relationships. |
| Viral Vector Core Facility Partnership | Integrated logistics bundling AAV packaging with hardware procurement compresses academic buyer decision timelines. |
| EMA Pre-Submission Briefing Engagement | Front-loaded regulatory dialogue parallelizes clinical and manufacturing track preparation for European therapeutic developers. |
| Wireless Telemetry Architecture Development | Subcutaneous photovoltaic energy harvesting enables naturalistic behavioral paradigms previously incompatible with fiber-optic tethers. |
Research Methodology
Desk research of FDA 510(k) and breakthrough device filings, NIH RePORTER grant databases, and EMA adaptive licensing pathway documentation preceded structured interviews with academic core facility directors, viral vector manufacturing specialists, and pharmaceutical regulatory affairs leads. Primary fieldwork with photonics hardware procurement committees at United States research universities and German Max Planck Institutes combined with secondary validation against SEC 10-K disclosures from listed life sciences instrumentation firms. Bottom-up demand modeling across product type and application segments triangulated against top-down NIH and DFG funding allocation trends.
Assumptions held fixed across the analysis window include continued FDA breakthrough device pathway availability and stable NIH circuit-mapping budget priorities, while EMA adaptive licensing uptake and METI metabolic disease research allocations were treated as scenario variables. Segmentation dimensions spanned hardware category, opsin variant technology, therapeutic versus research application, and end-user procurement authority structure. CAGRs derived from fitted growth curves anchored to disclosed funding trajectories and pharmaceutical pipeline progression stages, with silicon photonics foundry capacity expansion and viral vector manufacturing scale-up serving as key supply-side forecast inputs.
Sensitivities concentrate around NIH funding reallocations away from circuit-mapping initiatives, FDA breakthrough device pathway modifications, and single-source fabrication disruptions in Japanese micro-LED production. Forecasts reflect documented assumptions regarding viral delivery protocol maturation and semiconductor manufacturing roadmap execution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Sensor Data Analytics Market