
 Smart Parking Sensor Market | 2026-2036
Smart Parking Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Parking Sensor Market Analysis
Project finance for smart city infrastructure is tilting competitive dynamics toward vendors capable of delivering performance-backed service contracts rather than hardware-only sales. Cleverciti Systems Corp leverages its integrated software-hardware stack to sustain recurring revenue streams across European deployments. SpotHero anchors its position through digital platform control over operator-facing demand aggregation, while Modii Inc. specializes in curb-management analytics that differentiate its sensor layer from commodity parking detection.
A smart parking sensor is an electromechanical or optical device, typically integrating ultrasonic, magnetic, infrared, or image-capture elements with wireless transceivers operating across Wi-Fi, Zigbee, LoRaWAN, or Bluetooth protocols, designed to detect vehicle presence and transmit occupancy status to centralized management platforms. Its primary commercial purpose is to eliminate search-time inefficiency, monetize parking inventory dynamically, and generate traffic-flow data for municipal planning. Ultrasonic sensors occupy the largest installed base due to proven reliability and low unit cost, though camera-based sensors are capturing premium-tier deployments where license-plate recognition and security integration justify higher expenditure. Magnetic sensors lead in off-street surface lots where embedded installation tolerates pavement disruption, while LoRaWAN connectivity dominates municipal on-street networks for its long-range, low-power profile.
The European Green Deal and F-Gas Regulation shape hardware specifications by restricting refrigerants in associated edge-computing enclosures, while GDPR imposes strict data-governance requirements on camera-based systems capturing vehicle identifiers. CE marking and EU AI Act conformity assessments increasingly determine market access for sensor platforms employing machine-vision classification. Stakeholders must monitor how evolving interoperability mandates under the EU Digital Decade program reshape procurement standards and vendor qualification criteria.
Market Dynamics
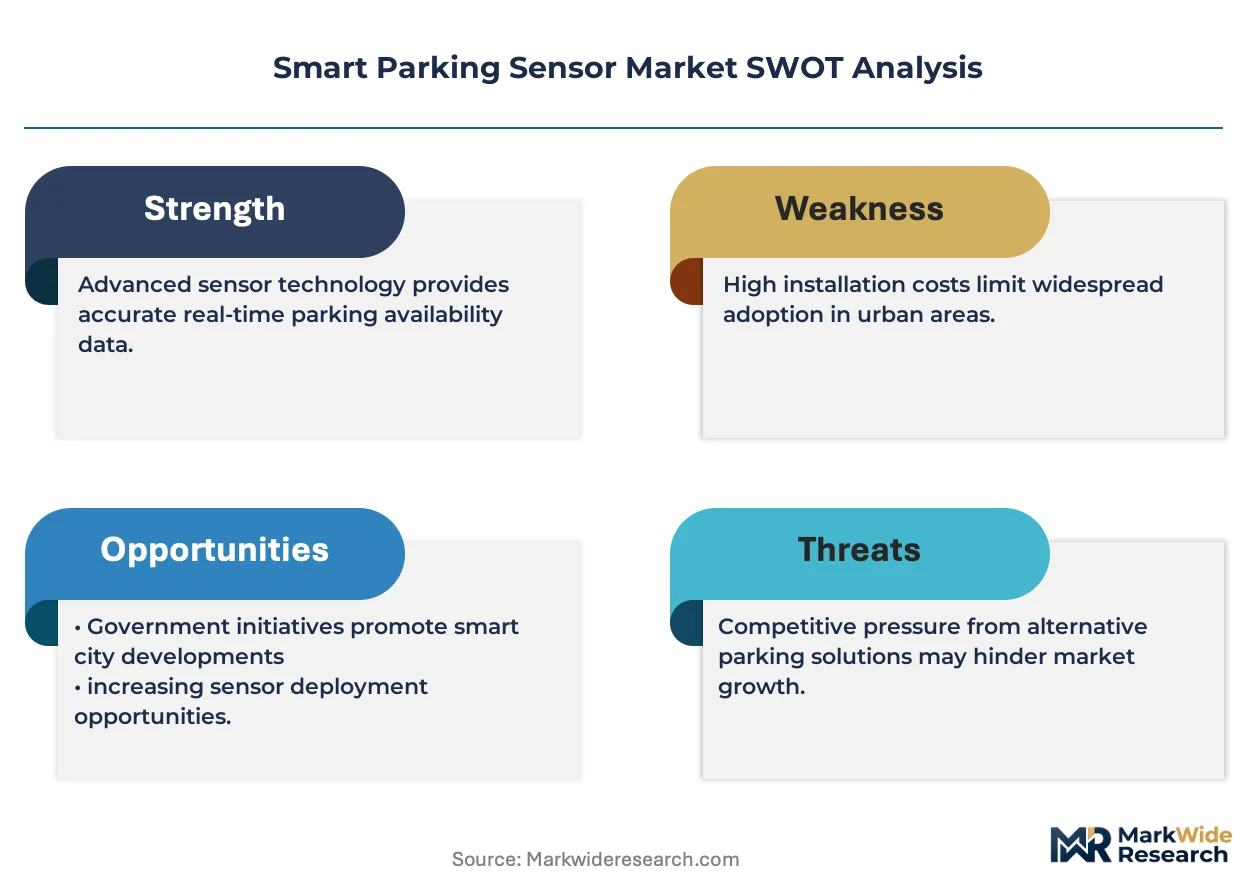
Performance-backed service contracts are displacing hardware-only sales as municipalities demand guaranteed uptime and data accuracy from smart parking deployments, compressing vendor margins while extending contract durations and technical accountability.
Growth Catalysts
- EU Green Deal mobility targets:Municipalities across Germany, France, and the Netherlands face binding emissions reduction mandates that accelerate sensor procurement for congestion management and traffic-flow optimization.
- Ultrasonic sensor reliability:Proven detection accuracy in harsh weather conditions sustains preference among transport authorities prioritizing operational continuity over feature expansion.
- Curb monetization urgency:Urban cores experiencing delivery-vehicle proliferation deploy sensors to enforce loading-zone pricing and dynamic reservation systems.
Market Restraints
- GDPR compliance costs:Camera-based systems capturing license-plate data require expensive data-governance infrastructure and legal review cycles that extend procurement timelines.
- Semiconductor supply concentration:LoRaWAN transceiver chip fabrication concentrates in East Asian foundries, exposing European deployments to logistics disruptions and tariff exposure.
- Lithium battery thermal limitations:Edge-computing enclosures in sensor housings face F-Gas Regulation restrictions on cooling refrigerants, constraining operating temperature ranges.
Strategic Opportunities
- EU Digital Decade interoperability mandates:Upcoming procurement standards will disqualify non-compliant vendors, creating first-mover advantage for platforms with open API architectures.
- EV charging-curb integration:Convergence of parking detection with charge-point reservation systems opens municipal RFPs previously siloed between transport and energy departments.
- CE marking plus EU AI Act conformity:Machine-vision classification systems achieving dual certification access premium-tier security-integrated deployments at higher contract values.
Industry Challenges
- Embedded systems firmware expertise:Municipal IT departments lack capacity to validate over-the-air update security, forcing vendors to absorb lifecycle management costs.
- Multi-protocol integration complexity:Deployments mixing Wi-Fi, Zigbee, and LoRaWAN networks require specialized network engineering talent scarce outside major metropolitan technology offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Parking Sensor Market |
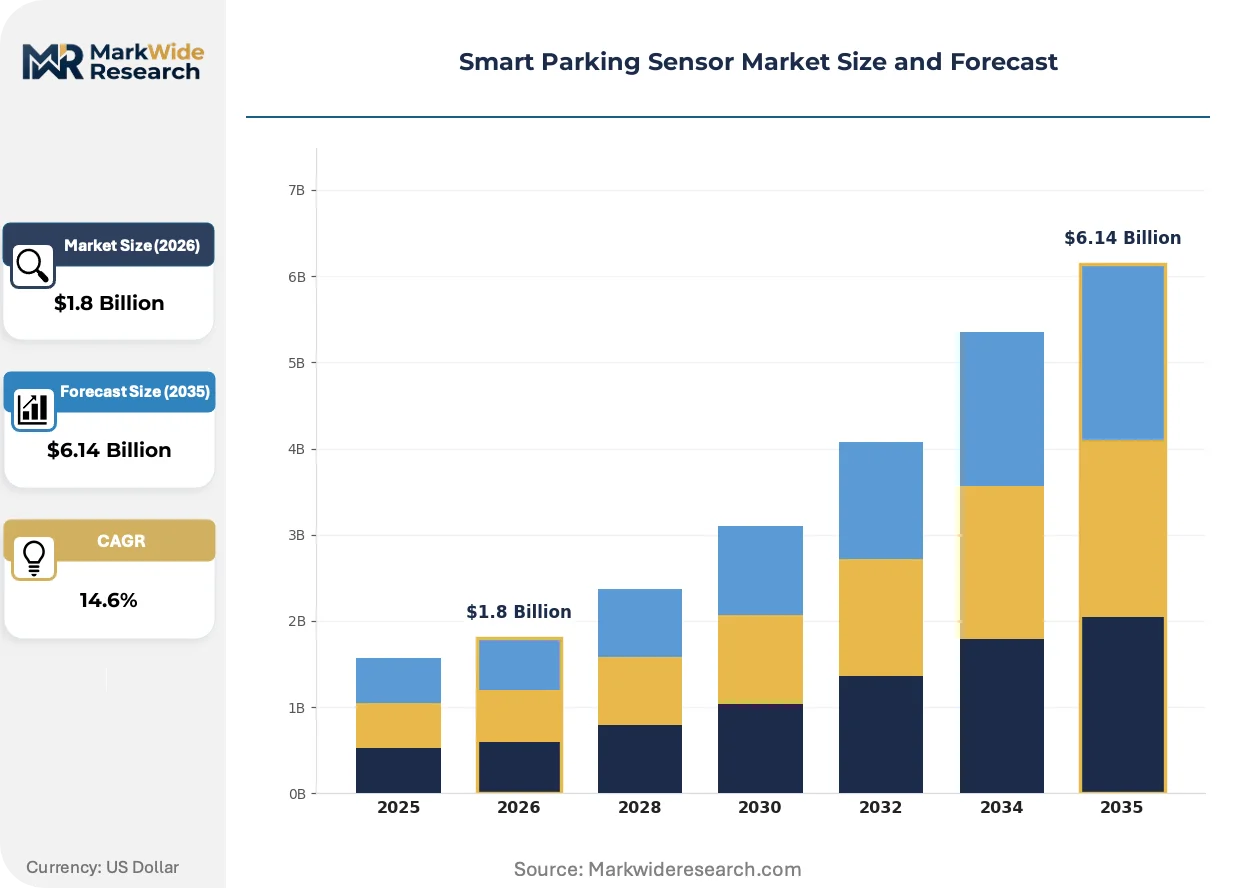
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Infrared Sensors, Magnetic Sensors, Camera-based Sensors Technology: Wi-Fi, Zigbee, LoRaWAN, Bluetooth End User: Municipalities, Commercial Parking Operators, Private Parking Lots, Smart City Developers Installation: On-street, Off-street, Multi-storey, Surface Lots |
| Companies Covered | Seyond, SpotHero, Automotus, Ensight Technologies, ProkoPark, Cleverciti Systems Corp, Modii Inc., Umojo, Park Core, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Parking Sensor Market Emerging Trajectories
Edge computing architectures are compressing data-transmission costs while enabling real-time analytics that transform parking sensors from simple occupancy detectors into multimodal traffic-intelligence nodes.
Camera-based sensors with embedded machine-vision processors are virtualizing the hardware layer by running license-plate recognition, vehicle-classification, and security-monitoring algorithms on shared silicon rather than discrete systems. Municipal buyers in premium-tier deployments adopt these consolidated platforms to reduce pole-mounted equipment counts and maintenance truck rolls. This convergence is virtualizing separate budget lines for parking, traffic enforcement, and public safety into unified infrastructure procurements.
The EU AI Act conformity assessment framework now requires documented risk-classification and bias-auditing for automated decision systems in public-space deployments. Camera-based parking sensors fall under limited-risk categorization, mandating transparency disclosures that extend vendor documentation obligations and third-party validation costs. German transport authorities have pioneered procurement clauses requiring CE marking plus algorithmic-impact assessments, establishing template requirements spreading to French and Dutch RFPs.
Outcome-based contracting is displacing capital-expenditure purchasing as transport departments transfer uptime risk and data-quality accountability to vendors. Performance metrics including detection accuracy thresholds, latency maximums, and API availability percentages now determine payment schedules and contract renewals. This shift concentrates procurement authority in cities with sufficient technical staff to define and monitor service-level agreements, visible most prominently in Amsterdam, Copenhagen, and Barcelona smart-mobility programs.
Smart Parking Sensor Market Segmentation
Segmentation in the smart parking sensor market determines procurement specifications, connectivity architecture, and service contract structures. Municipal buyers prioritize reliability metrics and integration complexity, while commercial operators emphasize total cost of ownership and scalability across distributed portfolios.
Product Type:
After-sales service intensity varies sharply across sensor modalities, with camera-based systems demanding continuous firmware validation and magnetic sensors requiring minimal lifecycle intervention.
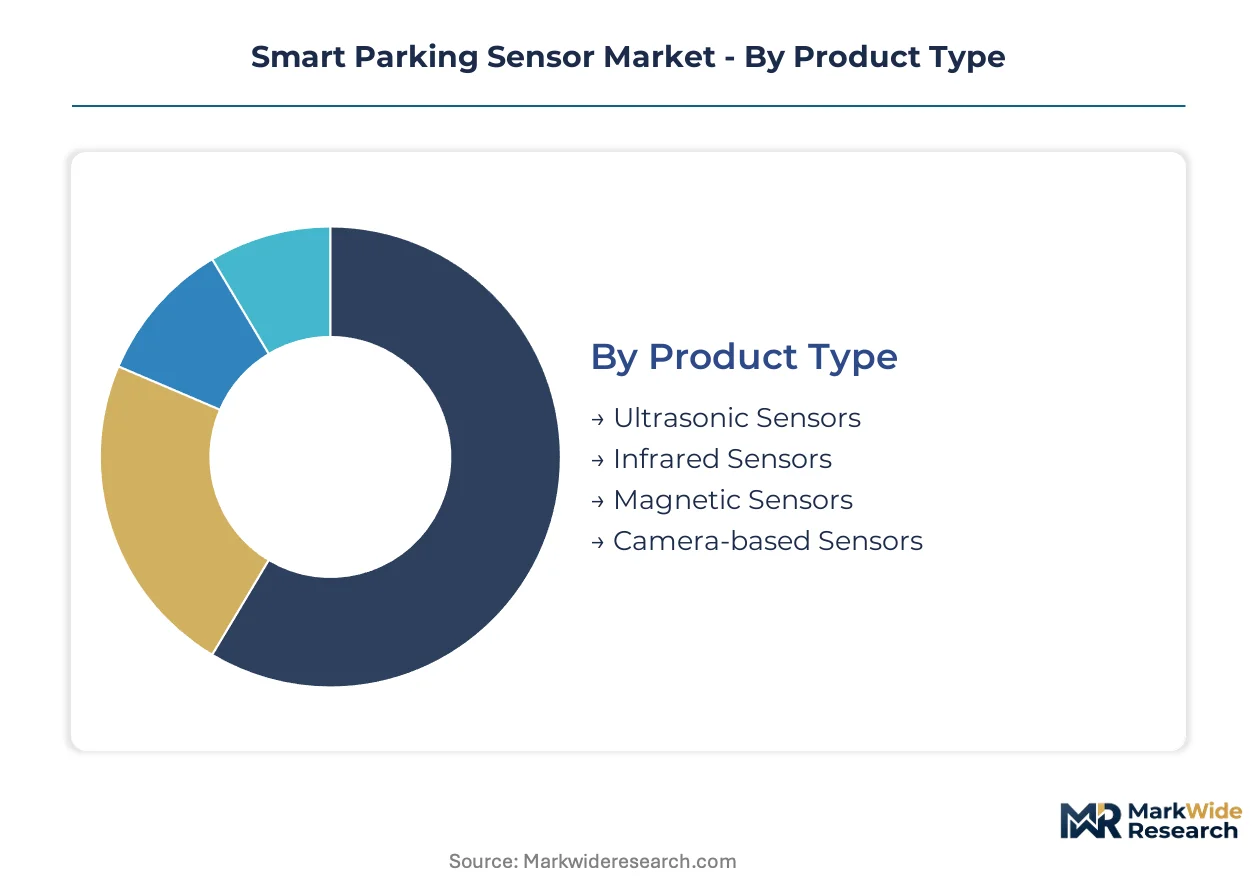
- Ultrasonic Sensors:These devices emit high-frequency acoustic pulses and measure echo return times to detect vehicle presence, achieving proven accuracy in precipitation and temperature extremes. Demand concentrates in German and Dutch municipal on-street deployments where transport authorities prioritize operational continuity over feature expansion, driven by EU Green Deal congestion management mandates.
- Camera-based Sensors:Machine-vision platforms with embedded edge processors execute license-plate recognition, vehicle classification, and security monitoring on unified silicon. Premium-tier procurement in French urban cores justifies higher expenditure through consolidated budget lines for parking enforcement and public safety integration, constrained by GDPR compliance costs for vehicle identifier capture.
- Infrared Sensors:Passive thermal detection systems sense heat signatures from vehicle engines and exhaust, suited for enclosed structures where acoustic interference complicates ultrasonic deployment.
- Magnetic Sensors:Embedded ferromagnetic detectors installed beneath pavement surface tolerate disruption in off-street surface lots, leading in installations where excavation access permits invasive construction.
Ultrasonic sensors hold the largest share; momentum sits with camera-based variants.
Technology:
Connectivity protocol selection shapes network engineering talent requirements and transceiver supply exposure.
- LoRaWAN:Long-range, low-power wide-area networking dominates municipal on-street networks across Germany, France, and the Netherlands, though semiconductor fabrication concentration in East Asian foundries creates logistics vulnerability.
- Wi-Fi:High-bandwidth local networking supports camera-based sensors requiring substantial data throughput for real-time video analytics in premium security-integrated deployments.
- Zigbee:Mesh networking protocol suits multi-storey structures where signal propagation challenges favor self-healing network topologies.
- Bluetooth:Short-range low-energy connectivity anchors consumer-facing mobile payment integrations and proximity-based reservation systems.
LoRaWAN captures the dominant installed base; Bluetooth is expanding most quickly in consumer-integrated applications.
End User:
Customer type determines contract structure, with municipalities shifting toward performance-backed service agreements and commercial operators retaining capital-purchase preferences.
- Municipalities:Public transport departments in Amsterdam, Copenhagen, and Barcelona smart-mobility programs define and monitor service-level agreements covering detection accuracy thresholds and API availability percentages.
- Commercial Parking Operators:Revenue-maximizing entities prioritize dynamic pricing infrastructure and demand aggregation platforms over hardware reliability specifications.
- Private Parking Lots:Corporate and institutional facilities emphasize integration with existing access control and building management systems.
- Smart City Developers:Master-planning consortia procure unified infrastructure spanning parking, traffic, and energy domains.
Municipalities command the largest procurement volume; smart city developers are gaining share fastest.
Installation:
Physical deployment context dictates sensor modality, connectivity architecture, and maintenance access economics.
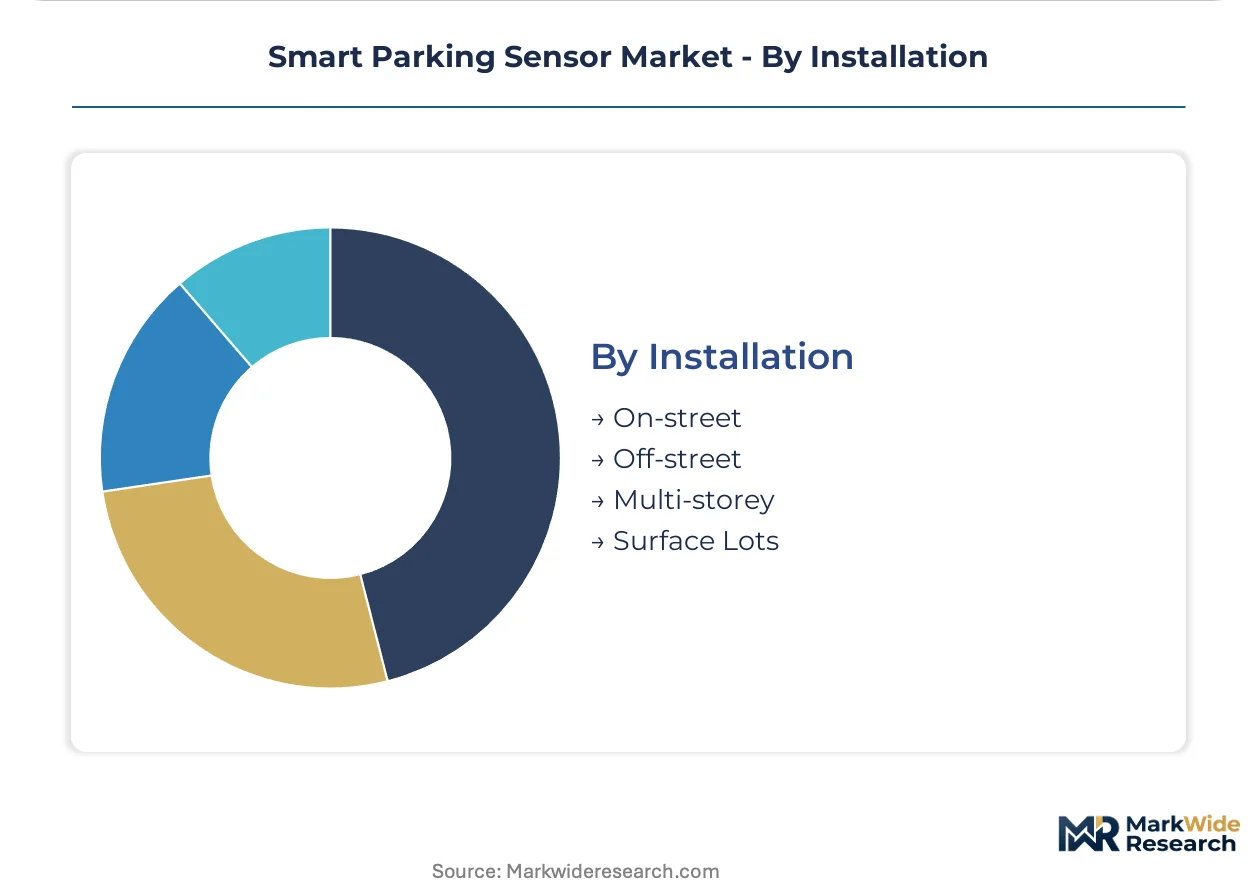
- On-street:Curb-mounted and in-pavement installations in dense urban cores face tightening emissions regulations and delivery-vehicle proliferation, driving loading-zone pricing enforcement demand.
- Off-street:Surface lots and structured facilities permit heavier equipment and power infrastructure, accommodating camera-based and edge-computing deployments.
- Multi-storey:Vertical structures with signal propagation constraints favor mesh networking and battery-powered magnetic sensors.
- Surface Lots:Expansive horizontal areas tolerate pavement disruption for embedded installations, leading magnetic sensor preference.
On-street installations hold the largest share; multi-storey deployments show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipalities extract pricing premiums for performance-backed uptime guarantees, while Dutch transport authorities negotiate sharper hardware cost compression under standardized procurement frameworks. This asymmetry reflects divergent risk-transfer appetites across adjacent regulatory environments.
Germany
Transport authorities in Berlin and Hamburg mandate CE marking plus algorithmic-impact assessments for camera-based deployments under KBA guidance. The EU AI Act conformity framework adds third-party validation costs that favor established vendors with documentation capacity. Bavarian smart-mobility clusters concentrate procurement authority in Munich and Nuremberg, where outcome-based contracting now dominates municipal RFPs.
Netherlands
Amsterdam's smart-city program defines service-level agreements covering detection accuracy thresholds and API availability percentages that spread to Rotterdam and The Hague. GDPR compliance infrastructure for license-plate recognition systems adds legal review cycles that extend procurement timelines. Randstad urban cores deploy LoRaWAN networks at scale, creating reference architectures for Belgian and Danish transport departments.
France
Paris and Lyon urban cores justify premium-tier camera-based expenditure through consolidated budget lines for parking enforcement and public safety integration. ANSM and CNIL oversight imposes strict data-governance requirements on vehicle identifier capture that constrain vendor qualification. Île-de-France municipalities pioneer curb-monetization urgency through delivery-vehicle proliferation management.
United Kingdom
London boroughs transfer uptime risk to vendors through performance-backed contracts that determine payment schedules and renewals. The Information Commissioner's Office enforces GDPR-derived transparency disclosures for automated decision systems in public-space deployments. Southeast England smart-mobility programs concentrate technical staff capacity for SLA definition and monitoring.
United States
New York and San Francisco deploy curb-management analytics under municipal congestion pricing frameworks that generate demand for real-time occupancy data. FCC spectrum allocation shapes LoRaWAN network economics across metropolitan deployments. California transport authorities integrate parking detection with EV charge-point reservation systems, opening procurement channels previously siloed between departments.
Smart Parking Sensor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying transducer modules and wireless transceivers to assembly houses. The vendor base separates into three strategic archetypes: software-hardware stacks delivering recurring revenue through service contracts, digital platforms aggregating operator-facing demand, and sensor-layer specialists differentiating through curb-management analytics. Competitive dynamics concentrate around M&A activity targeting firmware expertise and strategic partnerships securing LoRaWAN semiconductor supply.
Within the integrated-stack tier, Cleverciti Systems Corp and Modii Inc. exemplify divergent positioning—one anchoring European deployments through performance-backed service contracts, the other specializing in curb-management analytics that differentiate sensor-layer offerings from commodity detection. SpotHero occupies the platform-aggregator archetype, controlling operator-facing demand aggregation without direct hardware exposure. These three represent the structural segmentation between hardware-captive recurring revenue, software-layer platform control, and analytics-driven sensor specialization.
| Leading Market Players |
|---|
| Seyond |
| SpotHero |
| Automotus |
| Ensight Technologies |
| ProkoPark |
| Cleverciti Systems Corp |
| Modii Inc. |
| Umojo |
| Park Core |
| Others |
Supply Flow & Price Mechanics
Taiwanese semiconductor foundry capacity in Hsinchu Science Park anchors transceiver chip availability for LoRaWAN sensor deployments, with foundry allocation decisions cascading directly into procurement timelines and contract pricing power for European system integrators.
Pricing Analysis
The customization-premium spread separates configured-to-order camera-based sensor platforms with embedded machine-vision processors from standard ultrasonic detection units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE marking plus EU AI Act conformity commanding substantial uplifts. Cost compression in the standard tier is intensifying because municipal buyers consolidate procurement volumes under framework agreements. Commercial parking operators exhibit the highest price sensitivity, while smart city developers prioritize performance-backed service contracts over unit economics.
Supply Chain Analysis
Upstream feedstock for sensor housings and edge-computing enclosures draws from aluminum extrusion facilities in China, polymer compounders in Germany, and lithium cell manufacturers in South Korea. LoRaWAN transceiver fabrication hinges on East Asian foundry output, creating single-source vulnerability for European deployments. Distribution runs through specialized industrial electronics distributors serving municipal procurement channels, with direct OEM relationships gaining share in premium-tier camera-based deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart parking sensor market functions as a defensive-moat story where regulatory entrenchment through CE marking and EU AI Act conformity creates durable barriers against commodity competitors lacking documentation capacity.
For Market Incumbents: Pre-empt firmware expertise acquisition to address municipal IT capacity gaps in over-the-air update validation. Absorb lifecycle management costs before emerging platform aggregators capture service contract margins. Anchor position through backward integration into LoRaWAN semiconductor sourcing to mitigate East Asian foundry concentration risk.
For New Entrants and Emerging Players: Build out curb-management analytics specialization to differentiate from commodity occupancy detection, targeting French urban cores where delivery-vehicle proliferation drives loading-zone monetization urgency. Penetrate the multi-storey installation segment fastest through mesh networking expertise and battery-powered magnetic sensor configurations. Pursue partnership-first go-to-market positioning with smart city developers consolidating unified infrastructure procurements.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant parking detection divisions lacking software-layer integration. Five-to-ten year viability favors vendors with recurring revenue service contracts over hardware-only sales models. Monitor Amsterdam, Copenhagen, and Barcelona smart-mobility program RFP structures as inflection indicators for outcome-based contracting adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates parking enforcement and public safety budgets under unified procurement specifications. |
| Strategic Partnership | Secures LoRaWAN transceiver allocation from East Asian foundries amid semiconductor supply concentration. |
| Acquisition of Specialist Firm | Captures embedded systems firmware expertise scarce outside major metropolitan technology offices. |
| Geographic Expansion | Establishes reference architectures in Randstad urban cores for Belgian and Danish transport departments. |
| Product Launch | Introduces EV charging-curb integration to access municipal RFPs previously siloed between transport and energy departments. |
Methodological Framework
Initial hypotheses were tested against primary input from municipal transport department procurement managers, smart city program directors, sensor platform CTOs, and industrial electronics distribution executives and refined through secondary validation against EU Digital Decade policy documents, CE marking conformity assessment records, GDPR enforcement actions by national data protection authorities, and municipal RFP databases. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by sensor modality, connectivity protocol, end-user archetype, and installation context. CAGRs were derived from deployment trajectory analysis incorporating EU Green Deal mobility target compliance timelines and F-Gas Regulation hardware specification constraints. Industry-specific inputs included semiconductor foundry capacity utilization patterns and municipal IT department technical staffing ratios.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by platform aggregators would shift outcomes beyond modeled parameters. Quarterly review of municipal SLA definition sophistication and LoRaWAN transceiver spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Smart Control Socket Market