
 Virtual Sensors Market | 2026-2036
Virtual Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Sensors Market Analysis
European industrial automation vendors is broadening the supply base for virtual sensor platforms. Siemens AG leverages deep domain expertise in process industries to sustain platform leadership. Honeywell International Inc. anchors its position through embedded control systems integration. Elliptic Laboratories ASA specializes in software-defined proximity sensing for consumer electronics.
Virtual sensors are algorithmic constructs that infer physical measurements from correlated data streams rather than direct transduction, typically operating with update rates from milliseconds to seconds depending on the inference model and input data velocity. Their primary purpose is to monitor conditions in locations where hardware installation proves impractical, cost-prohibitive, or physically impossible. Integrated sensors command the largest installed base by embedding inference engines within existing control architectures, while machine learning deployments exhibit the steepest trajectory as neural network compression enables real-time edge execution. IoT platforms concentrate margin pools through recurring software licensing and cloud analytics subscriptions.
The EU AI Act imposes conformity requirements on AI-enabled monitoring systems, while GDPR mandates strict data governance for sensor-derived personal information, together elevating compliance costs for European deployments. The US FDA maintains parallel oversight for virtual sensing in connected medical devices through premarket submission pathways. Stakeholders must weigh regulatory fragmentation against standardization momentum from ISO and IEC working groups as they architect cross-border deployment strategies.
Market Dynamics
Neural network compression for edge execution is overtaking cloud-dependent inference architectures, forcing vendors to rearchitect software stacks for millisecond-latency deployments in process control environments.
Growth Catalysts
- Predictive maintenance mandates:German automotive OEMs now require virtual sensing for condition monitoring of rotating equipment, embedding algorithms directly into Siemens S7-1500 controllers.
- EU AI Act conformity pathways:The regulation's risk-classification framework creates procurement pull for CE-marked virtual sensor platforms in safety-critical industrial applications.
- Silicon carbide power electronics:Wide-bandgap semiconductors generate thermal profiles too complex for physical sensor arrays, driving algorithmic temperature inference in electric vehicle inverters.
Market Restraints
- Training data scarcity:High-fidelity physical sensor baselines required for model validation remain concentrated in German and US industrial automation corridors, limiting deployment in emerging manufacturing bases.
- GDPR-derived governance costs:Personal data classification of sensor-derived worker location and biometric inference elevates compliance overhead for European facility deployments.
- Legacy PLC protocol fragmentation:Proprietary fieldbus architectures in installed process control systems obstruct seamless virtual sensor integration without gateway hardware additions.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's emphasis on continuous process verification creates demand for virtual sensors in bioreactor parameter monitoring where probe sterilization cycles interrupt production.
- Digital twin convergence:Real-time virtual sensor outputs feeding physics-based simulation models enable closed-loop process optimization in chemical processing.
- Outcome-based performance contracts:Equipment vendors in US oil and gas now guarantee availability metrics validated through virtual sensor-derived health indices rather than physical inspection regimes.
Industry Challenges
- Multiphysics model calibration:Cross-functional teams combining domain expertise in fluid dynamics, thermodynamics, and machine learning remain scarce, elongating deployment timelines.
- FDA premarket submission complexity:Connected medical device pathways for virtual sensing in patient monitoring require clinical validation studies that compress margin structures for mid-tier vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Sensors Market |
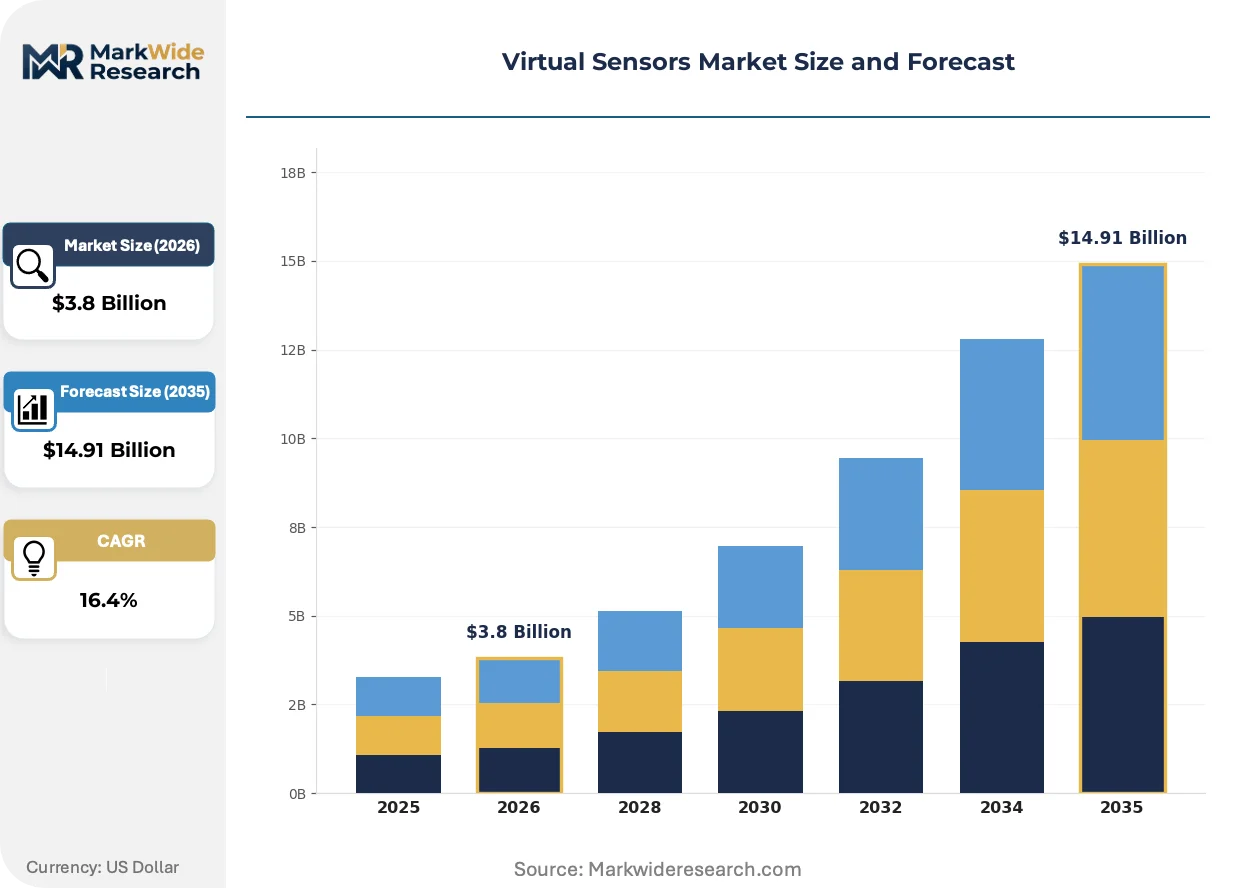
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Sensors, Integrated Sensors, Smart Sensors, Networked Sensors Technology: Machine Learning, Data Fusion, IoT Platforms, Edge Computing Application: Predictive Maintenance, Environmental Monitoring, Smart Homes, Industrial Automation End User: Manufacturing, Healthcare, Transportation, Energy |
| Companies Covered | Schneider Electric SE, General Electric Company, Siemens AG, Honeywell International Inc., Cisco Systems Inc., Rockwell Automation Inc., Emerson Electric Co., ABB Ltd, Elliptic Laboratories ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Sensors Market Emerging Trajectories
Compression algorithms and regulatory conformity frameworks are simultaneously expanding deployable use cases and elevating vendor capability requirements. Three developments warrant particular attention.
Edge-native neural network execution is overtaking cloud-reliant inference for time-critical industrial loops. Tensor quantization and pruning techniques now enable sub-10-millisecond prediction latency on ARM Cortex-M class processors. Automotive battery management systems in South Korean and German manufacturing facilities deploy these compressed models for cell-level thermal runaway prediction without dedicated sensing hardware.
The EU AI Act's high-risk system classification is redirecting vendor development resources toward conformity assessment infrastructure. Documentation requirements for training data provenance and model drift monitoring now consume substantial engineering bandwidth. Medical device and autonomous machinery segments in France and Germany face the steepest compliance cost escalation, prompting consolidation around pre-certified platform architectures.
Buyer procurement of virtual sensor capabilities now bundles algorithm licensing with physical automation hardware rather than acquiring software separately. System integrators in the US Gulf Coast petrochemical corridor package inference engines with DCS migrations, capturing margin that standalone software vendors previously extracted. This channel consolidation compresses addressable market access for pure-play algorithm developers lacking established control system partnerships.
Virtual Sensors Market Segmentation
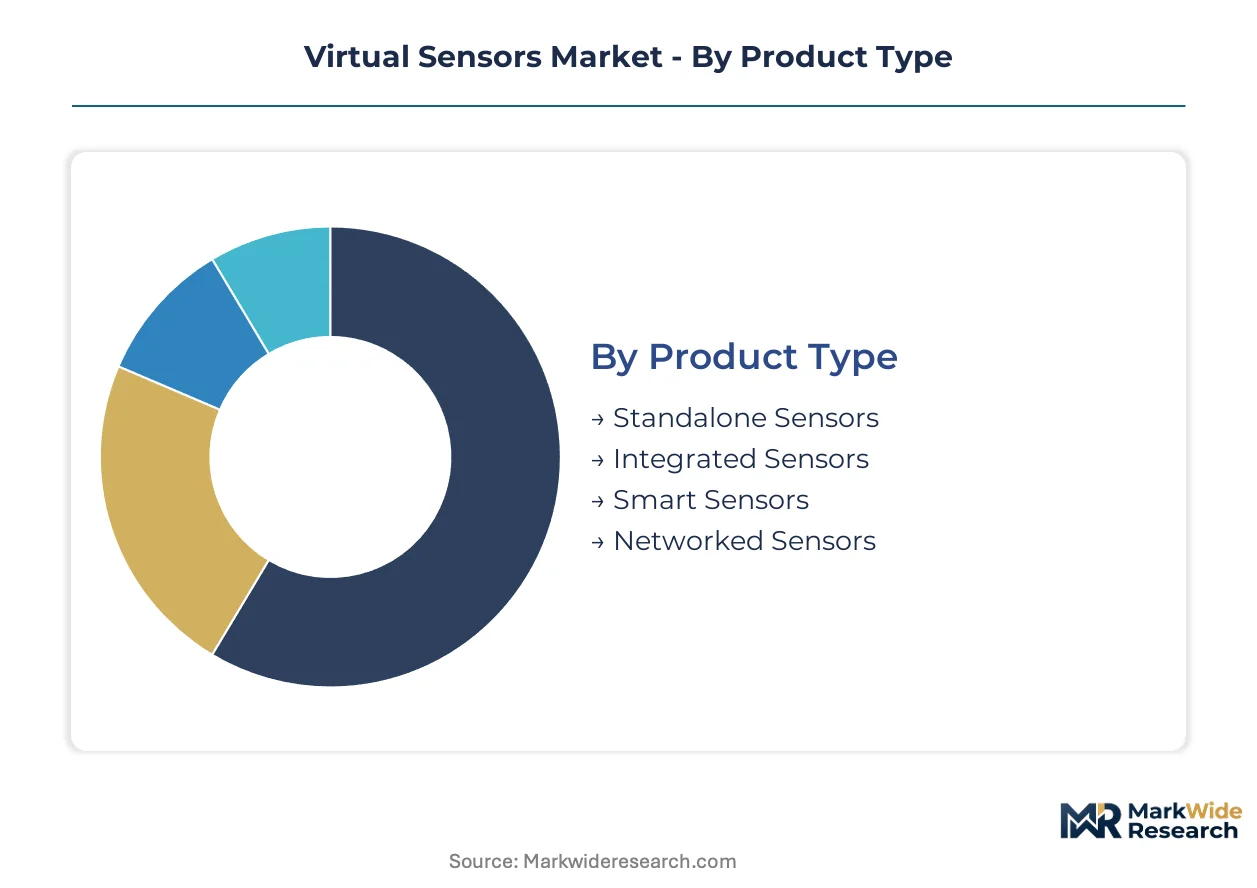
Virtual sensor architectures fragment across deployment modes, inference methodologies, and operational environments. Each segmentation axis reveals distinct margin structures, capability requirements, and buyer procurement patterns that shape vendor positioning.
Product Type:
Deployment architecture determines integration complexity and recurring revenue potential for platform vendors.
- Integrated Sensors:Inference engines embedded within existing control architectures dominate manufacturing deployments. German automotive OEMs embed these directly into Siemens S7-1500 controllers for rotating equipment monitoring, eliminating gateway hardware and reducing latency to millisecond scales.
- Standalone Sensors:Self-contained algorithmic modules operate independently of host control systems. These concentrate in legacy facility upgrades where PLC replacement proves cost-prohibitive, particularly in US Gulf Coast petrochemical installations running proprietary fieldbus protocols.
- Smart Sensors:Devices combining local inference with adaptive calibration capabilities.
- Networked Sensors:Distributed inference nodes communicating across facility-wide architectures.
Integrated sensors lead on scale; standalone configurations lead on retrofit momentum.
Technology:
Inference methodology selection hinges on latency tolerance, data sovereignty constraints, and model validation requirements.
- Machine Learning:Neural network compression enables real-time edge execution previously requiring cloud infrastructure. Tensor quantization and pruning techniques now achieve sub-10-millisecond prediction latency on ARM Cortex-M class processors, with South Korean and German automotive battery management systems deploying compressed models for cell-level thermal runaway prediction.
- IoT Platforms:Cloud-native inference architectures concentrate margin pools through recurring software licensing and analytics subscriptions. These dominate environmental monitoring applications where second-scale update rates suffice and data aggregation across distributed assets creates network effects.
- Edge Computing:Localized processing architectures address GDPR data residency mandates and connectivity interruptions.
- Data Fusion:Multimodal inference combining heterogeneous sensor streams for robustness against single-source failures.
Machine learning claims the steepest expansion trajectory; IoT platforms capture the largest recurring revenue share.
Application:
Use case specificity drives model training requirements, validation protocols, and buyer procurement authority.
- Predictive Maintenance:Condition monitoring algorithms for rotating equipment and thermal systems now carry procurement mandates from German automotive OEMs. These deployments require high-fidelity physical sensor baselines for model validation, concentrating development resources in established industrial automation corridors.
- Industrial Automation:Real-time process parameter inference in chemical processing and pharmaceutical manufacturing. CDSCO's emphasis on continuous process verification in Indian pharmaceutical manufacturing creates demand for bioreactor parameter monitoring where probe sterilization cycles interrupt production.
- Environmental Monitoring:Air quality, emissions, and climate parameter inference for regulatory compliance reporting.
- Smart Homes:Consumer-facing proximity and occupancy sensing, primarily through software-defined implementations.
Predictive maintenance dominates commercial value capture; industrial automation is gaining share fastest.
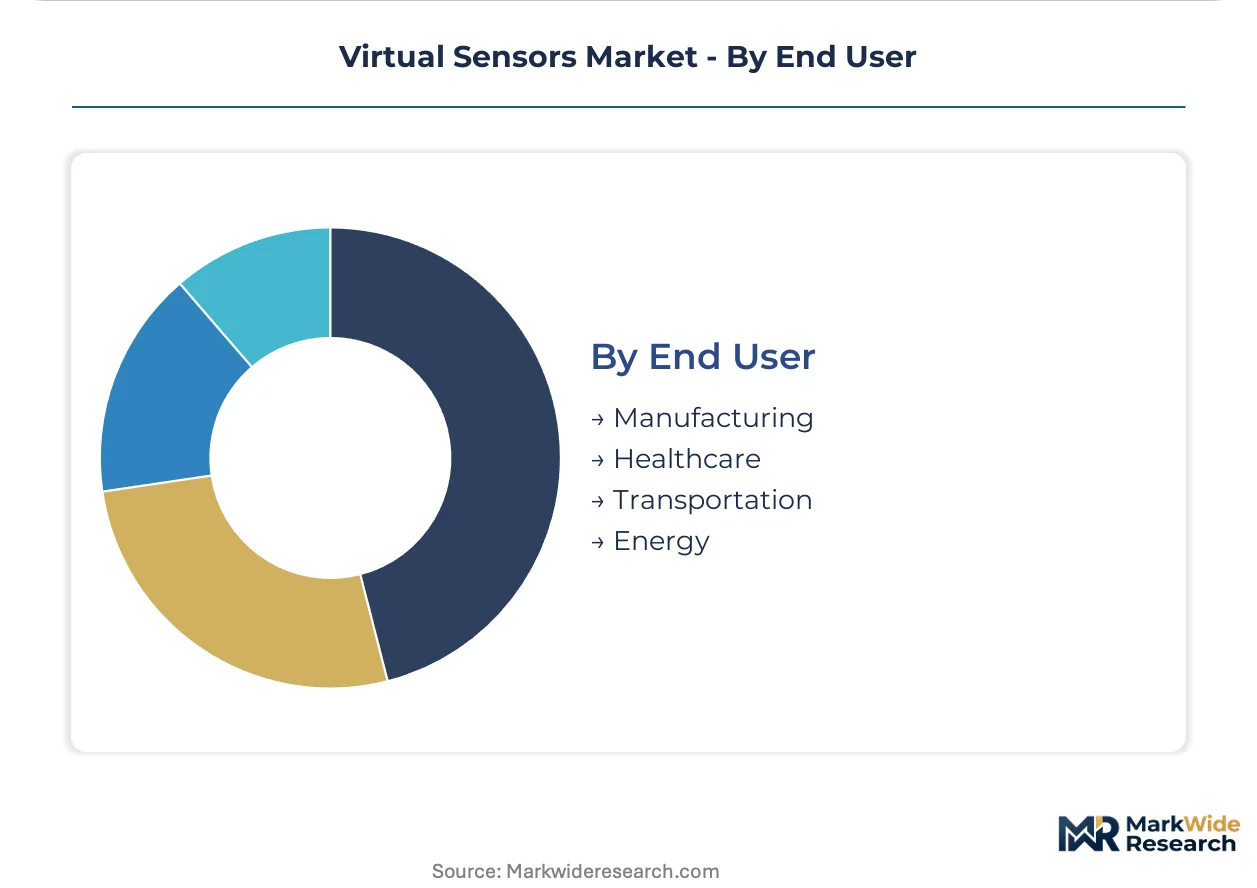
End User:
Sector-specific regulatory frameworks and operational criticality create divergent vendor qualification barriers.
- Manufacturing:Process industries and discrete automation represent the deepest installed base. EU AI Act conformity requirements for high-risk systems redirect vendor development resources toward CE-marked platforms, with medical device and autonomous machinery segments in France and Germany facing steepest compliance cost escalation.
- Energy:Power generation and grid infrastructure deployments emphasize availability guarantees. US oil and gas equipment vendors now structure outcome-based performance contracts validated through virtual sensor-derived health indices rather than physical inspection regimes.
- Healthcare:Connected medical device pathways require FDA premarket submission with clinical validation studies that compress margin structures for mid-tier vendors.
- Transportation:Automotive and aerospace applications prioritize millisecond-latency inference for safety-critical control loops.
Manufacturing leads on deployment scale; energy is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor commands deeper virtual sensor penetration than India's emerging pharmaceutical hubs, though regulatory momentum in both markets is accelerating deployment timelines.
United States
Oil and gas equipment vendors structure outcome-based performance contracts validated through virtual sensor-derived health indices. FDA premarket submission pathways govern connected medical device implementations, compressing margin structures for mid-tier vendors. The Gulf Coast petrochemical corridor packages inference engines with distributed control system migrations.
Germany
Automotive OEMs mandate virtual sensing for condition monitoring of rotating equipment, embedding algorithms directly into Siemens S7-1500 controllers. EU AI Act conformity requirements create procurement pull for CE-marked platforms in safety-critical applications. The Baden-Württemberg and Bavaria industrial clusters concentrate development resources for high-fidelity physical sensor baselines.
India
CDSCO emphasis on continuous process verification generates demand for bioreactor parameter monitoring where probe sterilization cycles interrupt production. The central drug regulator's manufacturing quality mandates align with virtual sensor deployments in active pharmaceutical ingredient facilities. Maharashtra and Gujarat pharmaceutical manufacturing corridors attract platform vendors targeting sterilization-free monitoring solutions.
South Korea
Automotive battery management systems deploy compressed neural network models for cell-level thermal runaway prediction without dedicated sensing hardware. The Ministry of Trade, Industry and Energy supports wide-bandgap semiconductor thermal profiling initiatives. Seoul Capital Area manufacturing facilities lead edge-native inference implementations for millisecond-latency process control.
France
Medical device and autonomous machinery segments face steepest EU AI Act compliance cost escalation, prompting consolidation around pre-certified platform architectures. ANSM and CNIL oversight intersects with GDPR data governance for sensor-derived worker location inference. The Île-de-France region anchors vendor development resources toward conformity assessment infrastructure.
Virtual Sensors Market Vendor Landscape
German producers anchor one tier of industrial automation integration; US specialists hold positions in embedded control systems and IoT platform architectures. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with captive control system ecosystems, pure-play algorithm developers targeting edge-native deployment, and network infrastructure providers bundling inference capabilities with connectivity hardware. Competitive moves center on strategic partnerships with system integrators and portfolio diversification into outcome-based service contracts.
Within the diversified industrial tier, Siemens AG and Honeywell International Inc. exemplify platform leadership through deep domain expertise in process industries and embedded control systems integration respectively. Elliptic Laboratories ASA occupies a specialist position in software-defined proximity sensing for consumer electronics applications. These three entities represent distinct competitive vectors: industrial automation heritage, control systems anchoring, and algorithm-centric specialization.
| Leading Market Players |
|---|
| Schneider Electric SE |
| General Electric Company |
| Siemens AG |
| Honeywell International Inc. |
| Cisco Systems Inc. |
| Rockwell Automation Inc. |
| Emerson Electric Co. |
| ABB Ltd |
| Elliptic Laboratories ASA |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up algorithm specialists now dominate the mid-tier virtual sensor licensing segment, concentrating pricing power among four consolidated platforms while compressing margins for standalone software vendors lacking embedded control system partnerships.
Pricing Analysis
Capacity additions in South Korea and Germany are reshaping price floors for edge-native inference modules. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and latency tolerance. Cost compression in the standard tier intensifies because compressed neural network models commoditize sub-10-millisecond execution. System integrators exhibit the highest price sensitivity due to bundled hardware procurement, while pharmaceutical manufacturers under CDSCO mandates accept premium tiers for sterilization-free monitoring validation.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs now mandate multi-supplier qualification for inference engines embedded in safety-critical controllers. Component supply concentrates in Germany, South Korea, and the United States for ARM Cortex-M class processors, wide-bandgap semiconductors, and high-fidelity physical sensor baselines. Manufacturing draws from silicon carbide substrates, tensor quantization libraries, and proprietary fieldbus gateway hardware. Single-source vulnerability persists in neural network compression IP held by specialist software houses. Distribution runs through system integrators packaging algorithms with DCS migrations in the US Gulf Coast petrochemical corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual sensors market functions as a stable compounder, with predictive maintenance mandates from automotive OEMs generating recurring algorithm licensing revenue across economic cycles.
For Market Incumbents: Extend platform dominance by embedding inference engines deeper into Siemens S7-1500 and Rockwell ControlLogix architectures, neutralizing standalone sensor vendors. Acquire edge-native compression specialists before they secure automotive battery management system design wins. Vertical integration into tensor quantization IP reduces dependency on external algorithm licensing. For New Entrants and Emerging Players: Mid-tier Indian pharmaceutical manufacturers under CDSCO continuous process verification mandates represent the most penetrable buyer archetype. Target sterilization-free bioreactor monitoring where probe replacement cycles create production downtime. Partner with Maharashtra and Gujarat-based system integrators already embedded in active pharmaceutical ingredient facility upgrades. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play algorithm developers lacking control system partnerships. Five-to-ten year viability hinges on FDA premarket submission capabilities for medical device pathways. Watch for EU AI Act high-risk system classification expansion beyond medical devices and autonomous machinery as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Neural Network Compression | Tensor quantization on ARM Cortex-M enables millisecond-latency automotive battery thermal prediction without dedicated hardware. |
| EU AI Act Conformity Infrastructure | CE-marked platform architectures capture procurement mandates from French and German safety-critical industrial applications. |
| Backward Integration into Control Systems | Captive DCS and PLC ecosystems lock in recurring algorithm licensing through embedded inference engine deployment. |
| Pharmaceutical Sterilization-Free Monitoring Partnerships | CDSCO-aligned validation protocols open bioreactor parameter inference contracts in Maharashtra and Gujarat corridors. |
| Outcome-Based Performance Contracting | Availability guarantees validated through virtual sensor health indices displace physical inspection regimes in US oil and gas. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement teams, system integrators, and regulatory affairs specialists anchored qualitative foundations. Secondary validation drew from FDA 510(k) filings, EU AI Act implementation guidance, CDSCO manufacturing quality circulars, and SEC 10-K disclosures from industrial automation conglomerates. Bottom-up deployment counts across German automotive facilities and Indian pharmaceutical corridors triangulated against top-down market sizing from algorithm licensing revenue pools.
Segment-level value outputs trace product type, inference methodology, application specificity, and end-user regulatory complexity across the projection horizon. CAGRs derive from neural network compression adoption curves, EU AI Act procurement pull timing, and pharmaceutical sterilization-free monitoring penetration rates. Model inputs include ARM Cortex-M processor shipment forecasts, wide-bandgap semiconductor thermal profiling deployment data, and system integrator bundle pricing disclosures.
Underlying measurement precision varies by segment; integrated sensor deployments in German manufacturing carry tighter precision than emerging Indian pharmaceutical implementations. Forecasts reflect assumptions around EU AI Act enforcement timelines, FDA premarket submission pathway stability, and silicon carbide power electronics adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Smartphone Biometric Sensors Market