
 Canada Digital Thermometer Market | 2026-2036
Canada Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Digital Thermometer Market Insights
The Canada digital thermometer market is consolidating around a widening split between clinical-grade precision instruments and mass-market consumer units. Omron Corporation leverages its decades-long presence in home health monitoring to sustain brand loyalty across Canadian pharmacy chains. Exergen Corporation specializes in non-contact infrared technology for hospital triage environments, where speed and hygiene protocols dominate purchasing criteria. Cardinal Health controls institutional procurement channels, competing on contract breadth and logistics integration with provincial health authorities.
A digital thermometer measures body temperature through electronic heat sensors, typically employing thermistors or infrared detectors with accuracy thresholds of ±0.1°C for clinical applications and ±0.2°C for consumer-grade devices, converting thermal data into digital readouts for medical diagnosis or wellness tracking. Oral and forehead units dominate volume sales through retail and online channels, though infrared and Bluetooth-enabled smart thermometers capture disproportionate margin pools as homecare users seek connected health integration. Hospitals and clinics still anchor premium-tier procurement, where non-contact technology reduces cross-contamination risk and supports throughput targets in emergency departments.
Health Canada's Medical Devices Directorate mandates ISO 13485 quality management and IEC 60601 electrical safety compliance for commercial distribution, while provincial health authorities like Ontario Health enforce additional tender specifications that filter market access. The Canadian Standards Association maintains performance benchmarks that differentiate approved clinical devices from unregulated imports sold through e-commerce platforms. Stakeholders must monitor evolving interoperability standards for Bluetooth-enabled devices as provincial electronic health record integration accelerates.
Market Dynamics
Bluetooth-enabled thermometers are compressing the traditional clinical-homecare boundary as provincial electronic health record integration accelerates across Ontario and Quebec, forcing manufacturers to recalibrate firmware development roadmaps around interoperability mandates rather than standalone accuracy metrics.
Growth Catalysts
- Health Canada Class II registration pathways:Streamlined quality management requirements under ISO 13485 are accelerating market entry for infrared non-contact devices, expanding hospital triage procurement pools beyond traditional oral thermometer suppliers.
- Aging demographics in Ontario and Quebec:Dense concentrations of Canadians aged 65-plus are sustaining institutional procurement volumes while simultaneously driving retail pharmacy demand for home-monitoring tools with large-display readability features.
- Thermistor-to-infrared sensor migration:Manufacturing cost curves for infrared detector arrays are flattening, enabling mid-tier brands to offer hospital-grade non-contact precision at consumer price points previously reserved for contact-based thermistors.
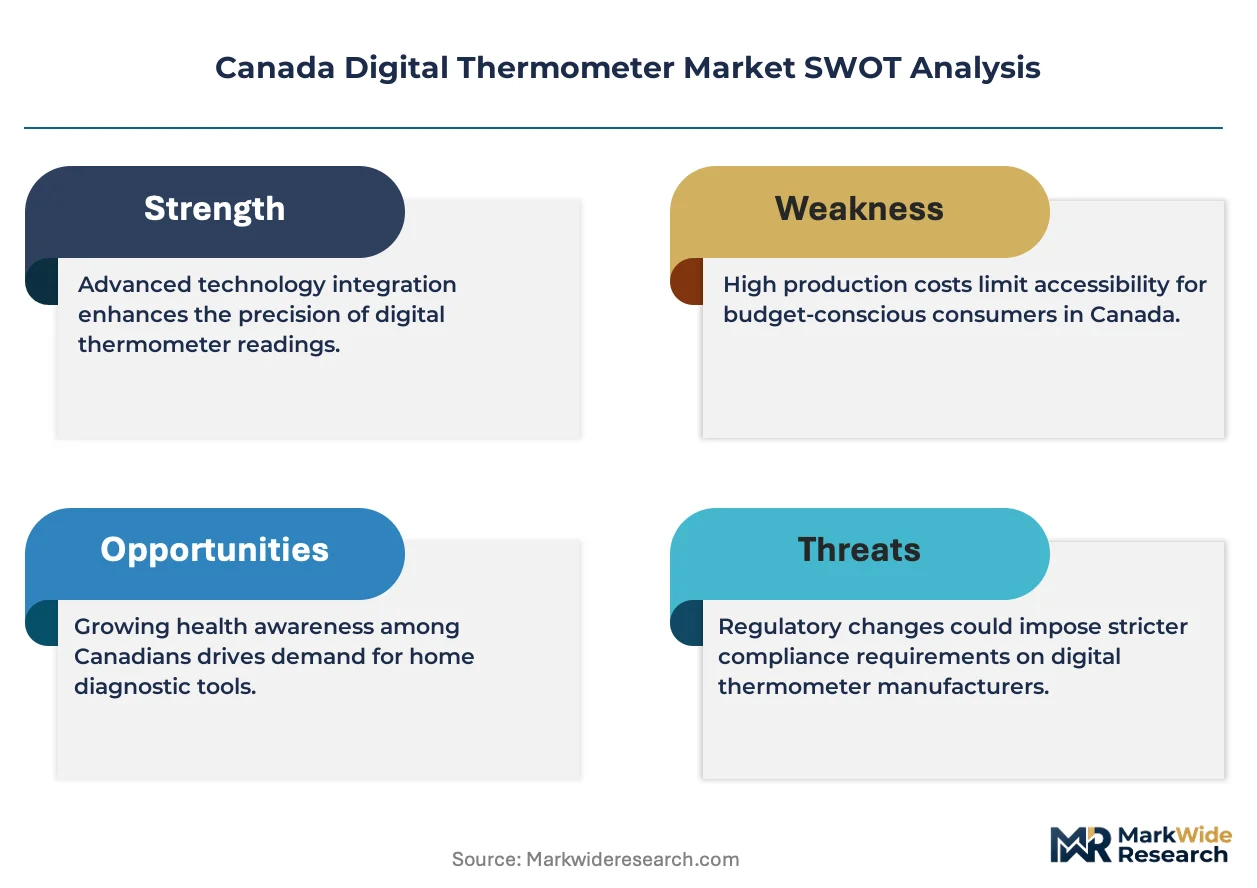
Market Restraints
- Semiconductor supply concentration:Thermistor and infrared sensor fabrication concentrates in East Asian foundries, exposing Canadian distributors to lead-time volatility that provincial tender schedules cannot accommodate.
- Health Canada electrical safety compliance:IEC 60601 testing requirements for clinical-grade devices impose six-to-nine-month certification timelines that freeze smaller manufacturers out of institutional contract cycles.
- Smartphone-based temperature estimation:Thermal camera accessories and app-based fever detection are capturing price-sensitive consumer segments that previously purchased dedicated digital thermometers.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled thermometers converging with provincial telehealth platforms create first-mover advantages for vendors achieving Ontario Health interoperability certification ahead of competitors.
- First Nations and rural health authority contracts:Underpenetrated procurement channels in northern Quebec and Indigenous communities offer volume growth outside saturated urban pharmacy retail.
- Canadian Standards Association performance benchmarking:Emerging CSA certification tiers for connected-device data security are creating premium positioning opportunities distinct from unregulated e-commerce imports.
Industry Challenges
- Firmware engineering talent scarcity:Bluetooth Low Energy stack development and Health Canada cybersecurity validation require specialized skill sets concentrated in Toronto and Vancouver, constraining product roadmap velocity for regional manufacturers.
- Legacy health record system integration:Provincial electronic medical record platforms operate on disparate data standards, forcing thermometer vendors to maintain multiple API configurations and fragmenting development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Digital Thermometer Market |
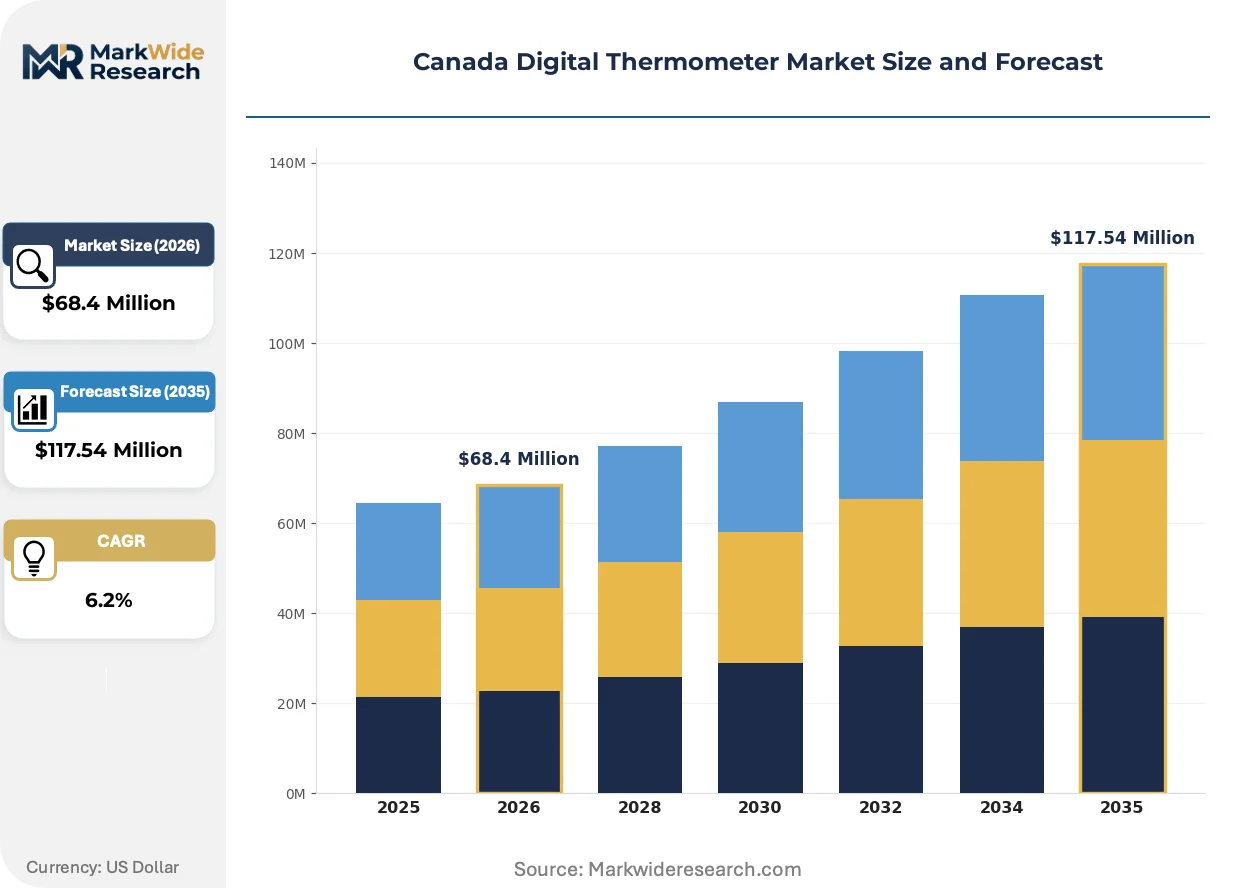
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $117.54 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Ear, Forehead, Oral End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Smart, Bluetooth, Non-Contact, Traditional Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Terumo Corporation, Omron Corporation, A&D Medical, 3M Company, Medline Industries, Exergen Corporation, Microlife Corporation, Braun GmbH, Cardinal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Digital Thermometer Market Trends and Innovations
Sensor miniaturization and connectivity protocols are redefining what constitutes a thermometer, transforming single-purpose diagnostic tools into data nodes within broader patient monitoring ecosystems.
Infrared array sensors with multi-point temperature averaging are overtaking single-spot forehead measurement in Canadian hospital emergency departments. Triage units in Toronto and Montreal are adopting these devices to reduce cross-contamination risk while maintaining throughput targets. The technology is compressing the price premium between clinical and consumer-grade non-contact units, forcing mid-market brands to differentiate on software features rather than sensor performance.
Health Canada's Medical Devices Directorate is tightening cybersecurity guidance for Bluetooth-enabled thermometers under evolving post-market surveillance frameworks. Manufacturers must now submit software bill of materials and vulnerability management protocols alongside traditional safety documentation. Class II device holders with connected features are responding by embedding over-the-air update capabilities to address emerging threats without hardware recalls.
Retail pharmacy chains are unbundling thermometer sales from after-sales calibration services, shifting warranty risk to manufacturers while capturing recurring revenue from extended protection plans. Shoppers Drug Mart and London Drugs are piloting subscription models that bundle device replacement with telehealth platform access. This restructuring is most visible in Ontario, where pharmacy consolidation has concentrated buyer power and compressed wholesale margins for standalone hardware.
Canada Digital Thermometer Market Segmentation
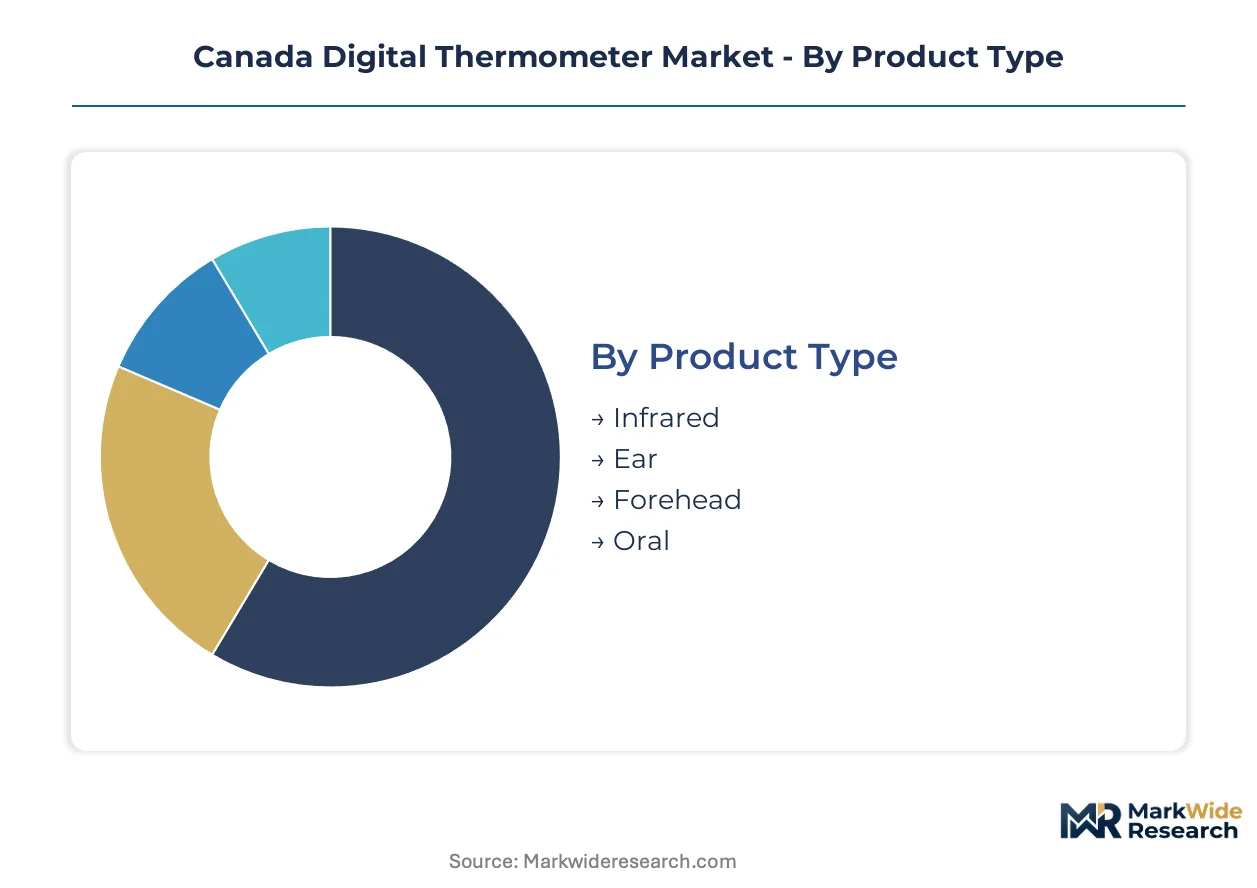
Digital thermometer purchasing in Canada fragments across clinical precision requirements, connectivity mandates from provincial health authorities, and retail accessibility preferences. Each segmentation dimension captures distinct margin structures and regulatory exposure that shape vendor positioning strategies.
Product Type:
Canadian buyers prioritize measurement speed and hygiene protocols when selecting form factors, with institutional procurement favoring non-contact technologies and homecare segments tolerating longer measurement intervals for cost savings.
- Infrared:Multi-point detector arrays capture thermal radiation from skin surfaces without physical contact, achieving ±0.1°C accuracy thresholds required by Ontario Health emergency department tenders. Quebec hospital networks are standardizing these units across triage workflows to eliminate cross-contamination vectors.
- Forehead:Single-spot infrared sensors mounted in wand or gun configurations dominate retail pharmacy volumes through Shoppers Drug Mart and London Drugs chains. Alberta Health Services bulk procurement is migrating toward forehead units with Bluetooth telemetry for remote patient monitoring integration.
- Ear:Tympanic membrane measurement via infrared probes delivers core body temperature approximation faster than oral methods, though positioning sensitivity limits adoption in pediatric homecare segments.
- Oral:Thermistor-based contact sensors with waterproof housings retain cost-sensitive pharmacy shelf presence, particularly in rural Manitoba and Saskatchewan where replacement cycles stretch beyond urban norms.
Forehead units lead on scale; infrared arrays lead on momentum.
End User:
Procurement authority concentration varies sharply across Canadian healthcare tiers, with provincial tender boards wielding price-setting power while retail consumers fragment across pharmacy and e-commerce channels.
- Hospitals:Acute care facilities in Toronto, Montreal, and Vancouver operate centralized purchasing through provincial health authorities, specifying ISO 13485-certified devices with IEC 60601 electrical safety documentation. Non-contact infrared adoption is displacing legacy oral thermometers in emergency department triage protocols.
- Homecare:Aging demographics in Ontario and Quebec are driving pharmacy retail demand for large-display, Bluetooth-enabled units that integrate with provincial telehealth platforms. Health Canada Class II registration requirements filter unregulated imports from this channel.
- Clinics:Community health centers and private physician practices balance precision requirements against capital constraints, often selecting mid-tier forehead units without enterprise connectivity features.
- Pharmacies:Consolidated retail chains are unbundling device sales from calibration services, capturing recurring revenue through extended warranty subscriptions while compressing wholesale margins for hardware vendors.
Hospitals command premium pricing; homecare is expanding most quickly.
Technology:
Firmware capabilities and interoperability certifications are displacing raw sensor accuracy as the primary vendor differentiation mechanism in connected health ecosystems.
- Smart:Embedded processors enable on-device fever algorithms, multi-user profiles, and symptom logging without smartphone dependency. Health Canada cybersecurity guidance is forcing over-the-air update architectures into new product roadmaps.
- Bluetooth:Low-energy stack implementations must achieve Ontario Health interoperability certification to access provincial electronic health record integration programs. Firmware engineering talent scarcity in Toronto and Vancouver is constraining vendor development velocity.
- Non-Contact:Infrared array measurement without skin contact eliminates consumable costs and cross-contamination risks, though ambient temperature compensation algorithms require clinical validation.
- Traditional:Standalone thermistor devices without connectivity retain price-sensitive rural market share, particularly in northern Quebec and Indigenous health authority catchments where smartphone penetration lags urban centers.
Traditional technology leads on installed base; Bluetooth-enabled units are gaining share fastest.
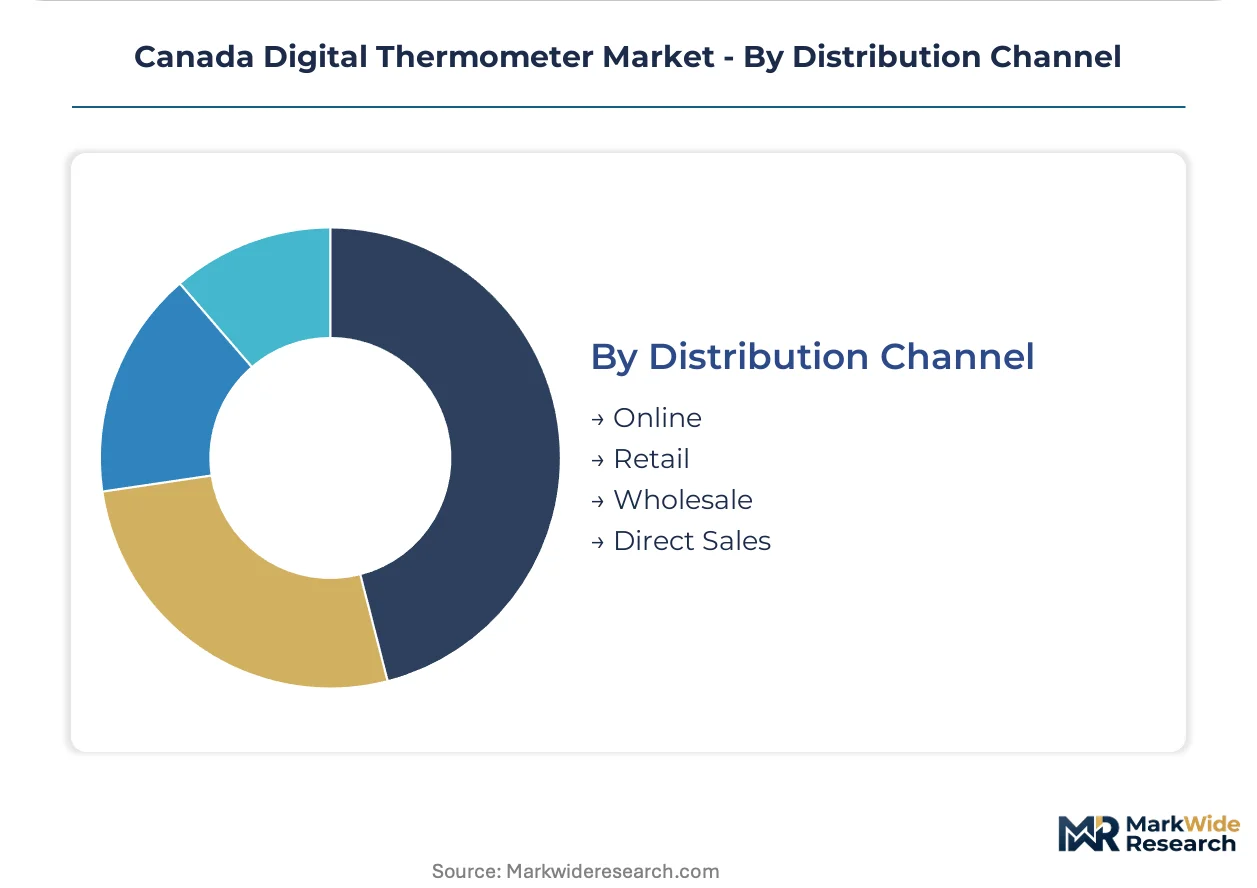
Distribution Channel:
Channel selection determines regulatory exposure, with institutional procurement requiring Health Canada Medical Devices Directorate registration while e-commerce platforms host unregulated imports.
- Retail:Pharmacy chains including Shoppers Drug Mart, London Drugs, and Jean Coutu control consumer-grade volume flows, leveraging buyer concentration to extract slotting fees and promotional support from manufacturers.
- Online:Amazon.ca and manufacturer-direct storefronts bypass retail margin stacking, though Health Canada post-market surveillance struggles to police unregistered imports sold through marketplace platforms.
- Wholesale:Medical supply distributors including Cardinal Health and Medline manage institutional procurement logistics, competing on contract breadth and provincial health authority relationship depth.
- Direct Sales:Enterprise accounts in hospital networks and provincial health authorities negotiate multi-year supply agreements with dedicated account management and calibration service bundling.
Retail channels lead on transaction volume; direct sales capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's digital thermometer demand concentrates in Ontario and Quebec, while Alberta and British Columbia sustain distinct procurement patterns shaped by provincial health authority structures and demographic profiles.
Ontario
Toronto's acute care networks and aging suburban populations drive dual-channel demand for clinical-grade infrared devices and consumer Bluetooth-enabled units. Ontario Health's interoperability mandates for electronic health record integration filter vendor access to institutional contracts. The Greater Toronto Area hosts dense pharmacy retail consolidation that compresses wholesale margins for hardware-only suppliers.
Quebec
Montreal hospital networks standardize non-contact infrared arrays across emergency department triage protocols to eliminate cross-contamination vectors. The province's Medical Devices Directorate enforcement creates regulatory friction for unregistered imports sold through e-commerce platforms. Northern Quebec health authorities remain underpenetrated, offering volume growth outside saturated urban procurement channels.
Alberta
Alberta Health Services bulk procurement is migrating toward forehead units with Bluetooth telemetry for remote patient monitoring integration. Calgary and Edmonton's dispersed suburban demographics sustain retail pharmacy demand for large-display home monitoring tools. Provincial tender specifications emphasize ISO 13485 certification pathways that favor established suppliers over emerging entrants.
British Columbia
Vancouver's firmware engineering talent scarcity constrains regional manufacturers' Bluetooth Low Energy development velocity for connected health applications. The province's telehealth platform expansion creates first-mover advantages for vendors achieving interoperability certification ahead of competitors. Victoria's aging island communities generate sustained homecare segment demand for self-monitoring precision instruments.
Atlantic Canada
New Brunswick and Nova Scotia health authorities operate decentralized procurement with longer replacement cycles for legacy thermistor devices. Rural pharmacy networks in the region tolerate extended lead times that urban distributors cannot accommodate. Indigenous health authority contracts in the Atlantic provinces offer volume growth outside competitive retail channels dominated by national chains.
Canada Digital Thermometer Market Competitive Landscape
Top-tier vendors anchor hospital and provincial health authority contracts, while mid-tier brands compete for pharmacy retail shelf space through price positioning and connectivity features. The vendor base stratifies across three strategic archetypes: multinational health technology conglomerates with decades-long Canadian presence, specialized infrared sensor developers with clinical validation focus, and consolidated medical supply distributors controlling logistics integration. Dominant competitive moves include firmware development partnerships with provincial telehealth platforms and calibration service bundling to capture recurring revenue streams.
Within the multinational conglomerate tier, Omron Corporation and Terumo Corporation exemplify established market anchors leveraging brand recognition across Canadian pharmacy chains. Exergen Corporation occupies a position among specialized developers focused on non-contact infrared technology for institutional triage environments. Cardinal Health sits within the distributor archetype, competing on contract breadth and provincial health authority relationship depth rather than proprietary device manufacturing.
| Leading Market Players |
|---|
| Terumo Corporation |
| Omron Corporation |
| A&D Medical |
| 3M Company |
| Medline Industries |
| Exergen Corporation |
| Microlife Corporation |
| Braun GmbH |
| Cardinal Health |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent scarcity in Toronto and Vancouver compresses development cost differentials between connected-device tiers, translating labor-market tightness into wider pricing spreads between Bluetooth-enabled units and standalone thermistor devices across Canadian distribution channels.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes Canadian thermometer pricing structures. Three-tier pricing separates clinical-grade infrared arrays with Health Canada Class II registration from mid-tier forehead units with Bluetooth telemetry from economy oral thermistors without connectivity. Price differentiation hinges on ISO 13485 certification tier and after-sales calibration bundling. Cost compression in the mid-tier is intensifying because retail pharmacy chains extract slotting fees while unbundling warranty services. Homecare consumers show highest price sensitivity; hospital procurement committees prioritize total cost of ownership over unit price.
Supply Chain Analysis
Warehouse-distribution layer concentration in Mississauga and Montreal hubs determines downstream fulfillment velocity for Canadian thermometer markets. Infrared detector arrays and thermistor sensors draw from Taiwan, South Korea, and China, while plastic housings and battery components feed from domestic injection molders. Single-source vulnerability concentrates in East Asian semiconductor foundries serving sensor fabrication. Distribution runs through Cardinal Health and Medline medical supply networks for institutional contracts, bypassing retail margin stacking for hospital and provincial health authority procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada digital thermometer market functions as a stable compounder, with aging demographics in Ontario and Quebec generating steady replacement demand across clinical and homecare segments.
For Market Incumbents: Anticipate smartphone-based temperature estimation apps eroding dedicated-device sales in price-sensitive consumer tiers. Defend position by deepening firmware partnerships with Ontario Health for interoperability certification, and by acquiring calibration service capabilities to capture recurring revenue streams from extended warranty subscriptions. For New Entrants and Emerging Players: Begin with underpenetrated First Nations health authority contracts in northern Quebec and Atlantic Canada, where procurement channels remain outside consolidated retail pharmacy networks. Target rural health authorities with traditional thermistor devices featuring large-display readability, leveraging longer replacement cycles that urban distributors cannot accommodate. For Investors and Strategic Acquirers: Medical supply distributors with provincial health authority relationship depth represent the most active acquirer category in this space. The long-term viability window favors vendors with Health Canada Class II registration and Bluetooth Low Energy development capabilities. Watch for Ontario Health interoperability certification announcements as inflection indicators for connected-device market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class II Registration | Unlocks institutional procurement channels and filters unregulated import competition from pharmacy retail. |
| Bluetooth Interoperability Certification | Enables integration with Ontario Health electronic health record systems and provincial telehealth platforms. |
| Calibration Service Bundling | Captures recurring revenue from extended warranty subscriptions while defending against retail margin compression. |
| Infrared Array Sensor Migration | Flattens manufacturing cost curves and enables hospital-grade precision at consumer price points. |
| First Nations Contract Penetration | Accesses volume growth outside saturated urban pharmacy channels with concentrated buyer power. |
Research Methodology
Multiple input streams — hospital procurement database analysis, provincial health authority tender documentation, and retail pharmacy channel audits — were reconciled through bottom-up and top-down triangulation. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and firmware development leads at connected-device manufacturers were cross-validated against Health Canada Medical Devices Directorate registration filings, ISO 13485 certification records, and customs import data tracking infrared sensor shipments.
Historical shipment volumes were cross-referenced against expert panel assessments of provincial telehealth integration timelines. The analytical framework modeled product type, end-user segment, technology tier, and distribution channel dimensions across the projection horizon. CAGRs were derived from regression analysis of replacement cycle patterns and demographic aging curves, with specific inputs including Ontario Health interoperability mandate schedules and Quebec hospital network standardization protocols for triage equipment.
Caveats apply where semiconductor supply disruptions, Health Canada cybersecurity guidance revisions, or provincial electronic health record system delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Sensor Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
United States Scintillator Market