
 Global Saas Spend Management Software Market | 2026-2036
Global Saas Spend Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Saas Spend Management Software Market Foresight
Enterprise-grade API integration and real-time data synchronization is reorganizing competitive dynamics across the sector. Zylo leverages deep benchmarking databases to anchor its position in subscription intelligence. Vendr competes through negotiated SaaS pricing databases that reduce procurement cycle times. Flexera differentiates by extending software asset management capabilities into cloud cost governance.
SaaS spend management software encompasses cloud-native platforms that aggregate subscription data through REST API connections, normalize vendor billing structures, and enforce procurement policies across distributed application portfolios. These systems functionally centralize shadow IT discovery, contract renewal alerts, and departmental chargeback allocation to prevent revenue leakage from redundant or orphaned licenses. Deployment via public cloud infrastructure leads adoption among organizations prioritizing elastic scaling and minimal internal infrastructure overhead, while hybrid cloud configurations capture demand from financial services and healthcare entities with data residency requirements. Solution offerings in subscription management and invoice automation represent the fastest-expanding categories as finance teams seek to replace spreadsheet-based renewal tracking.
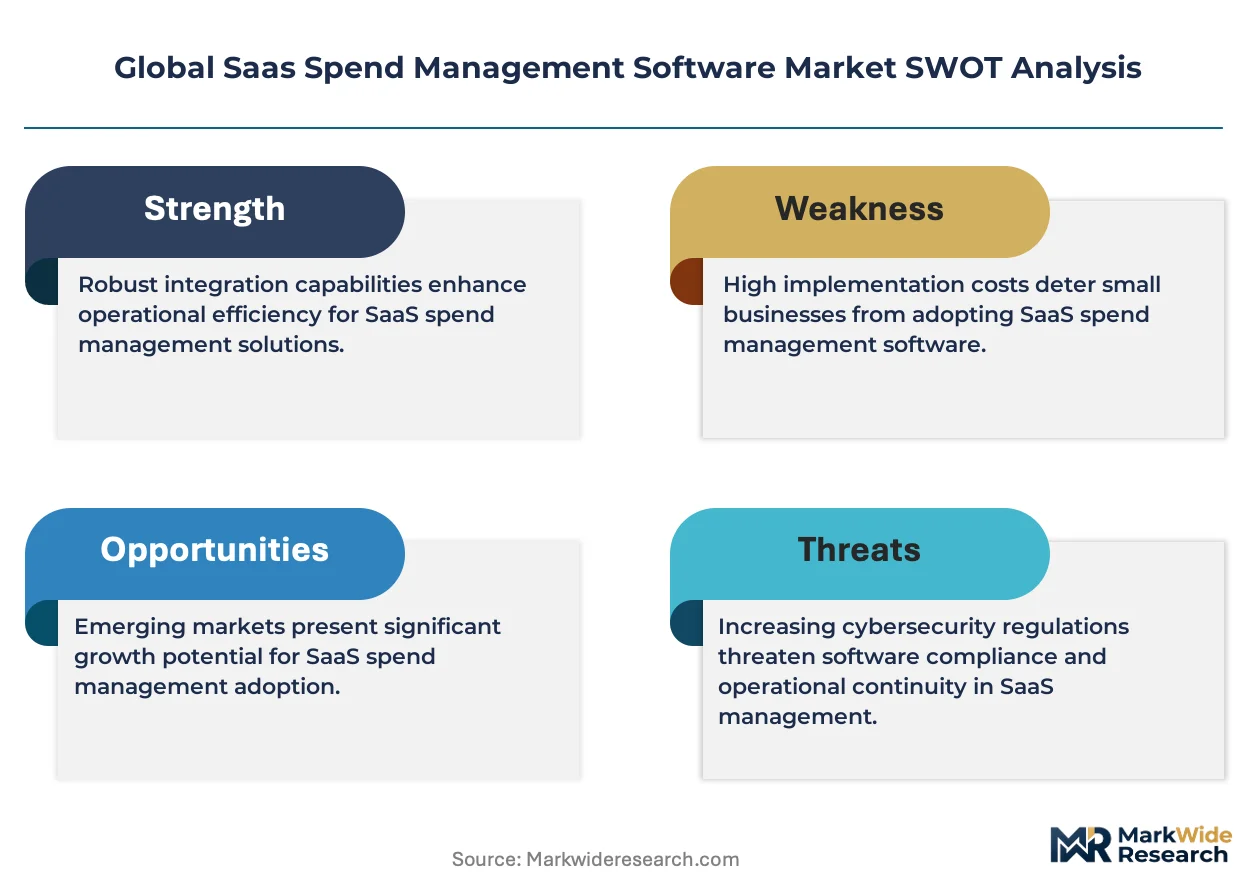
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively reshape product roadmaps by mandating auditable vendor risk documentation and automated compliance attestation workflows. FDA 21 CFR Part 11 and HIPAA standards further constrain how life sciences and healthcare organizations evaluate SaaS procurement tools, creating segmented certification requirements that filter market access. Stakeholders must weigh whether to build unified platforms spanning procurement through renewal management or maintain specialized point solutions as buyer expectations consolidate around single-pane visibility.
Market Dynamics
Enterprise procurement teams are consolidating SaaS oversight tools as shadow IT proliferation and distributed workforce expansion create unsustainable manual tracking burdens. Finance departments now mandate automated subscription discovery and renewal orchestration to prevent revenue leakage from orphaned licenses and redundant vendor contracts.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must maintain auditable vendor risk documentation and automated attestation workflows, creating mandatory procurement tool adoption across regulated industries.
- Mid-market technology firm expansion:Technology companies with 200-2,000 employees are deploying subscription oversight platforms to manage vendor sprawl without dedicated procurement staff.
- API-first architecture standardization:REST API connectivity enables real-time data synchronization between spend management platforms and ERP systems, eliminating spreadsheet-based renewal tracking.
Market Restraints
- Data residency compliance costs:Financial services and healthcare organizations face elevated infrastructure expenses for hybrid cloud configurations meeting HIPAA and FDA 21 CFR Part 11 requirements.
- Vendor consolidation risk:Concentrated demand among three dominant platform providers creates pricing power asymmetry and integration lock-in for enterprise buyers.
- Technical debt friction:Legacy ERP systems lacking modern API endpoints require expensive middleware development for spend management platform connectivity.
Strategic Opportunities
- India procurement digitization:Indian enterprises managing complex distributed workforces represent underpenetrated demand for automated SaaS governance tools.
- Healthcare vertical specialization:Life sciences organizations require purpose-built modules for clinical trial software license management and FDA-compliant vendor documentation.
- CSRD sustainability reporting convergence:EU corporate sustainability disclosure rules are creating procurement tool demand for carbon footprint tracking across cloud vendor portfolios.
Industry Challenges
- Integration architect scarcity:Shortage of professionals skilled in ERP-to-SaaS platform API mapping and data schema normalization extends deployment timelines.
- Multi-jurisdiction certification complexity:Vendors must sequentially obtain HIPAA, GDPR, SOC 2, and ISO 27001 attestations, creating 12-18 month market entry barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Saas Spend Management Software Market |
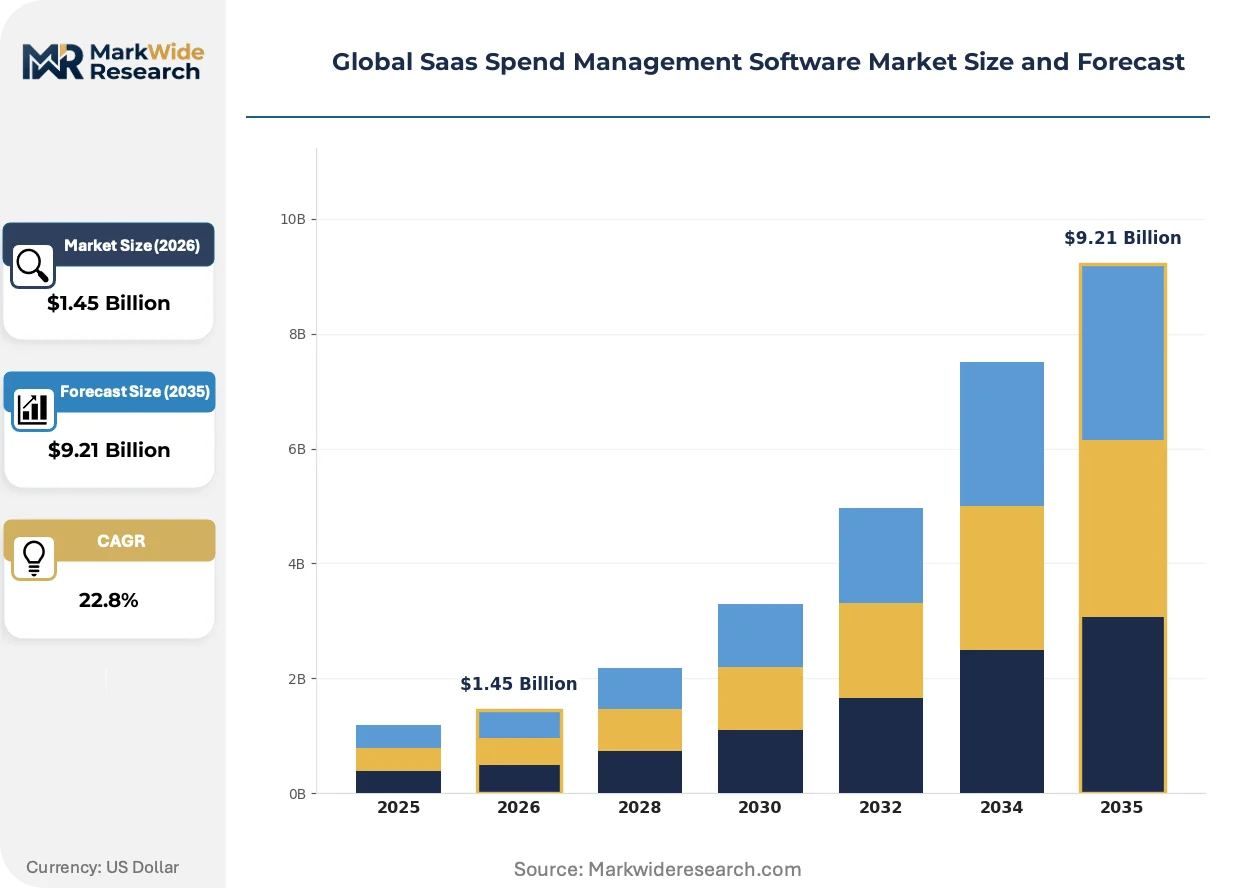
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $9.21 Billion |
| CAGR (2026 – 2036) | 22.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution Offering: Procurement Management, Expense Tracking, Subscription Management, Budget Planning, Invoice Automation Use Case: Vendor Management, Cost Optimization, Compliance Monitoring, Financial Reporting, Contract Management Customer Type: Large Enterprises, Small & Medium Businesses, Non-Profit Organizations, Government Agencies |
| Companies Covered | Zylo, CloudNuro, Binadox, BetterCloud, Spendflo, Zluri, Flexera, Intello, Vendr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Saas Spend Management Software Market Shifts & Advancements
Artificial intelligence and machine learning capabilities are embedding into core platform architectures, transforming spend management from retrospective reporting into predictive orchestration. Vendors are racing to deploy autonomous renewal negotiation agents and real-time usage optimization engines.
Agentic AI systems are displacing manual subscription renewal workflows by autonomously analyzing usage patterns, triggering vendor renegotiations, and executing contract amendments without human intervention. Mid-market finance teams are adopting these capabilities fastest, compressing procurement cycle times from weeks to hours. This automation is displacing traditional category manager roles and consolidating vendor relationship management into platform-native intelligence layers.
The EU AI Act and GDPR jointly mandate algorithmic transparency and automated decision documentation for procurement tools using machine learning. Vendors must now embed explainable AI modules that audit vendor selection rationale and flag discriminatory pricing patterns. Healthcare and financial services sectors in Germany and France face the strictest compliance timelines, accelerating demand for certified platforms with pre-built regulatory workflow templates.
Chief financial officers are unbundling SaaS procurement from traditional IT governance, creating direct relationships with spend management vendors outside centralized technology approval processes. Finance departments now own subscription budgets and vendor selection authority, displacing CIO-led procurement committees. This organizational shift is most visible in United States technology companies, where CFOs prioritize operational expenditure visibility over technical architecture standardization.
Global Saas Spend Management Software Market Segmentation
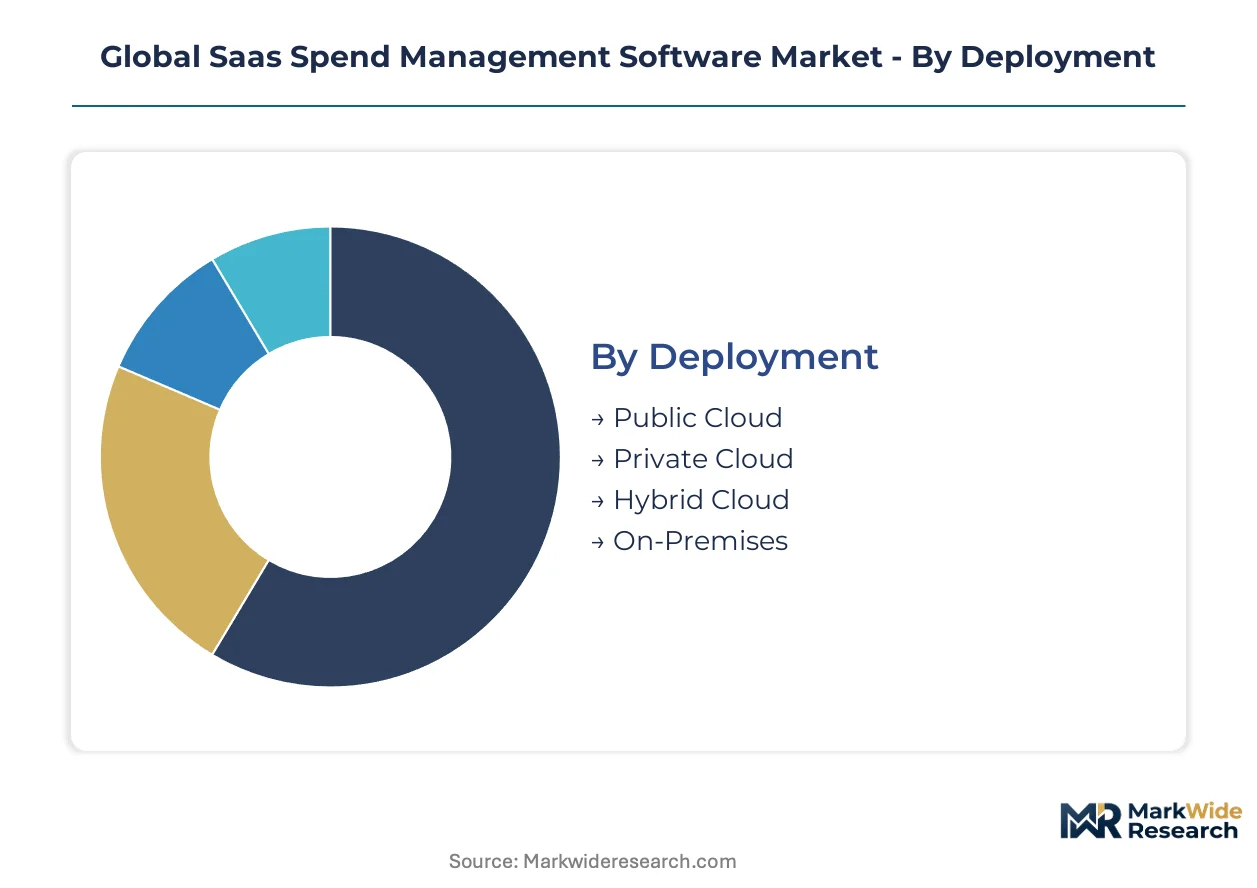
SaaS spend management software segments diverge sharply by infrastructure requirements and compliance posture. Regulatory mandates from GDPR, HIPAA, and the EU AI Act create non-negotiable deployment constraints that reshape vendor selection across every category.
Deployment:
GDPR data residency rules and FDA 21 CFR Part 11 audit trails differentiate infrastructure choices more than performance benchmarks.
- Public Cloud:Elastic scaling architectures eliminate capital expenditure for mid-market technology firms. United States software companies with distributed workforces drive concentrated demand here, prioritizing rapid API connectivity over data sovereignty controls.
- Hybrid Cloud:Split workload configurations satisfy financial services regulators in Germany and healthcare compliance officers in the United States. Sensitive contract metadata resides on-premises while analytics engines run in managed cloud environments.
- Private Cloud:Single-tenant deployments serve defense contractors and government agencies requiring air-gapped vendor risk documentation systems.
- On-Premises:Legacy ERP integration scenarios in regulated manufacturing retain fully localized subscription tracking databases.
Public cloud handles the majority of throughput; hybrid cloud is the fastest mover on share.
Solution Offering:
Finance team priorities and procurement cycle friction determine which modules command implementation budgets.
- Subscription Management:Automated discovery engines map shadow IT across distributed application portfolios. Indian enterprises managing vendor sprawl without dedicated procurement staff represent expanding demand concentration.
- Invoice Automation:Machine learning extraction normalizes disparate vendor billing formats into unified general ledger entries. Mid-market firms in the United States adopt these tools fastest to eliminate spreadsheet-based renewal tracking.
- Procurement Management:Policy enforcement workflows gate software purchases against pre-approved vendor lists.
- Expense Tracking:Real-time departmental chargeback allocation prevents revenue leakage from orphaned licenses.
- Budget Planning:Predictive forecasting modules aggregate commitment-based pricing across multi-year SaaS contracts.
Subscription management dominates current deployments; invoice automation is climbing the fastest on implementation velocity.
Use Case:
Organizational accountability shifts—particularly CFO ownership of SaaS budgets—reshape which functional outcomes drive purchasing decisions.
- Cost Optimization:Usage analytics engines identify redundant licenses and right-size tiered pricing agreements. Technology firms with 200-2,000 employees leverage these tools to compress procurement cycle times from weeks to hours.
- Compliance Monitoring:Automated attestation workflows document vendor risk for SEC cybersecurity disclosure rules and EU AI Act algorithmic transparency mandates. Healthcare organizations in France face the strictest compliance timelines here.
- Vendor Management:Centralized relationship databases consolidate contract terms, renewal dates, and pricing benchmarks.
- Financial Reporting:Standardized SaaS expenditure dashboards feed directly into ERP general ledgers.
- Contract Management:Digital repository systems track amendment history and auto-trigger renegotiation alerts.
Cost optimization commands the largest implementation base; compliance monitoring is expanding most quickly on regulatory pressure.
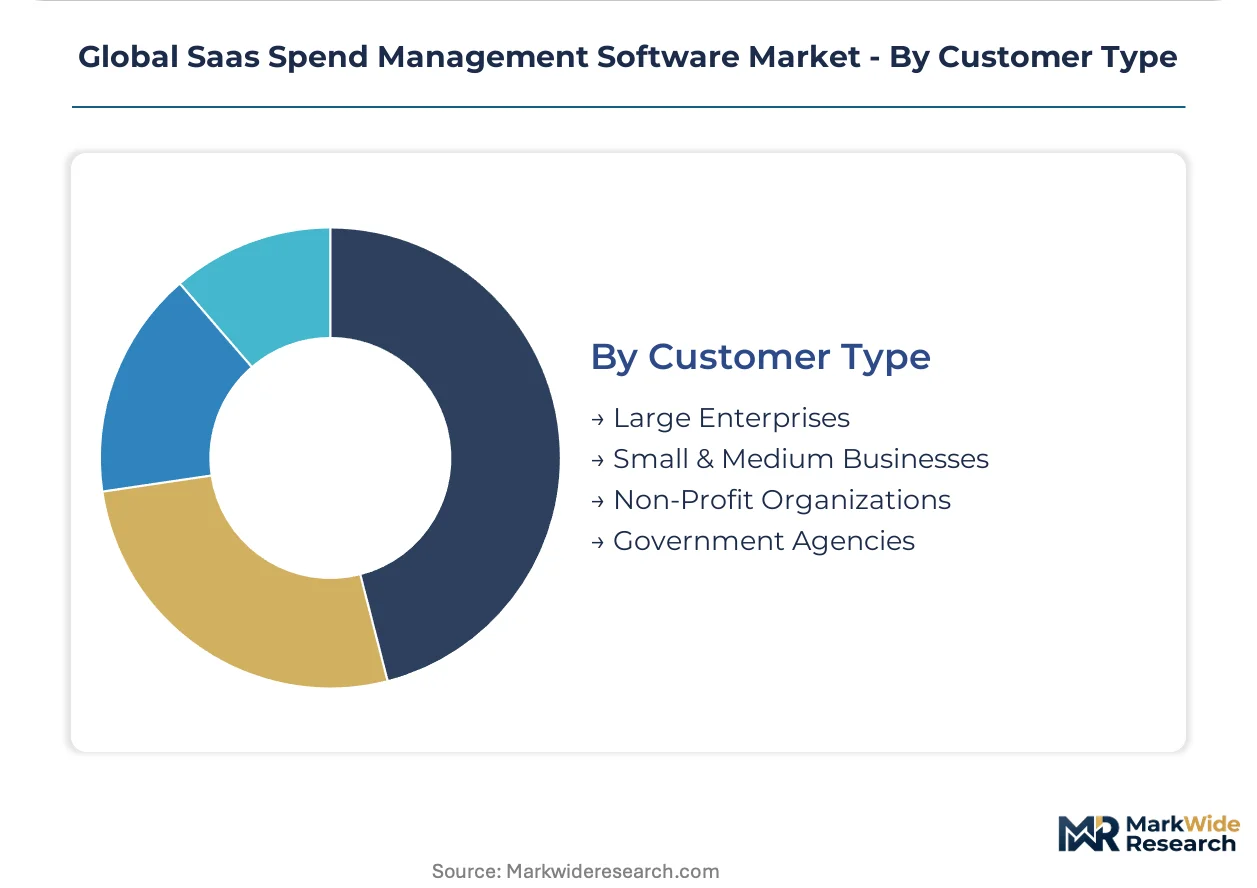
Customer Type:
Organizational scale determines whether buyers prioritize out-of-box functionality or deep customization.
- Large Enterprises:Complex multi-entity structures require federated subscription governance across hundreds of business units. German automotive manufacturers and United States pharmaceutical companies drive sophisticated feature requirements.
- Small & Medium Businesses:Pre-configured templates and rapid deployment cycles dominate selection criteria. Indian technology startups represent underpenetrated demand for automated SaaS governance without dedicated procurement staff.
- Non-Profit Organizations:Grant-funded budget cycles necessitate specialized donor reporting and restricted fund tracking modules.
- Government Agencies:FedRAMP and state-level certification requirements filter vendor eligibility for public sector procurement.
Large enterprises absorb the majority of platform revenue; small and medium businesses are gaining share fastest on mid-market digitization waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based SaaS spend management vendors export subscription intelligence platforms to enterprise buyers across Germany, India, and Japan as distributed workforce governance needs intensify worldwide.
United States
Mid-market technology firms with 200-2,000 employees drive concentrated demand for automated subscription discovery tools. SEC cybersecurity disclosure rules mandate auditable vendor risk documentation, accelerating procurement platform adoption. San Francisco Bay Area software companies deploy API-first architectures to eliminate spreadsheet-based renewal tracking across distributed application portfolios.
Germany
Automotive manufacturers and pharmaceutical companies require federated subscription governance across complex multi-entity structures. EU AI Act compliance mandates algorithmic transparency and automated decision documentation for procurement tools using machine learning. Munich and Frankfurt financial services clusters prioritize hybrid cloud configurations to satisfy GDPR data residency requirements.
India
Technology startups and enterprises managing complex distributed workforces represent underpenetrated demand for automated SaaS governance without dedicated procurement staff. RBI guidelines on vendor risk management push financial institutions toward centralized subscription oversight platforms. Bangalore and Hyderabad technology corridors lead domestic adoption of cloud-native spend management solutions.
United Kingdom
London-based financial services firms and professional services organizations consolidate SaaS oversight tools to address shadow IT proliferation. UK GDPR alignment maintains stringent data protection requirements for procurement platforms processing vendor contract metadata. The City of London and Canary Wharf financial clusters drive demand for real-time departmental chargeback allocation capabilities.
Japan
Enterprise manufacturers and trading houses seek subscription management platforms to govern multi-year SaaS contracts across Asian operations. METI digital transformation initiatives encourage procurement digitization among mid-sized enterprises. Tokyo and Osaka industrial clusters evaluate hybrid cloud deployments balancing operational efficiency with data sovereignty controls.
Global Saas Spend Management Software Market Competitive Landscape
Listed technology conglomerates compete with private venture-backed specialists across pricing intelligence and API integration depth. The vendor landscape organizes into three tiers: established software asset management incumbents extending into cloud governance, pure-play SaaS spend platforms built on benchmarking databases, and procurement automation specialists compressing vendor negotiation cycles. Dominant competitive moves include strategic acquisitions of usage analytics engines and geographic expansion through localized compliance certification.
Within the pure-play tier, Zylo and Vendr exemplify alternative approaches to subscription intelligence—one anchoring position through deep benchmarking datasets, the other through negotiated pricing databases. Flexera occupies a position spanning legacy software asset management and emerging cloud cost governance. These three companies represent the concentration of platform revenue as enterprise buyers consolidate around single-pane visibility expectations.
| Leading Market Players |
|---|
| Zylo |
| CloudNuro |
| Binadox |
| BetterCloud |
| Spendflo |
| Zluri |
| Flexera |
| Intello |
| Vendr |
| Others |
Supply & Pricing Matrix
API-first architecture standardization is displacing legacy middleware-dependent deployments, simultaneously concentrating development talent in United States technology corridors and compressing implementation pricing for mid-market buyers while elevating premium tiers for hybrid cloud configurations serving German financial services and United States healthcare entities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade federated governance platforms from mid-market subscription discovery tools and entry-level invoice automation modules. Price differentiation rests on certification depth—SOC 2, ISO 27001, and HIPAA attestations command 40-60% premiums over uncertified alternatives—and customization scope for multi-entity ERP integration. Cost compression in the standard tier is intensifying because pure-play vendors are racing to capture mid-market technology firms with pre-configured templates. Small and medium businesses exhibit highest price sensitivity, while German automotive manufacturers and United States pharmaceutical companies prioritize compliance posture over unit economics.
Supply Chain Analysis
Inbound logistics costs for specialized compliance certification services—particularly EU AI Act algorithmic transparency audits and FDA 21 CFR Part 11 validation—are creating chokepoints as accredited assessors concentrate in Germany, France, and the United States. Platform development draws from cloud infrastructure provisioning in the United States, integration engineering talent in India, and regulatory consulting capacity in Germany. Single-source vulnerability sits with concentrated API gateway providers serving the middleware layer between spend management platforms and legacy ERP systems. Distribution runs through direct enterprise sales teams for large accounts and self-service digital channels for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SaaS spend management software sits in early-cycle expansion as CFO-led procurement governance displaces traditional IT oversight, with EU AI Act compliance mandates creating non-negotiable adoption triggers across regulated European industries.
For Market Incumbents: Consolidate platform capabilities through targeted acquisition of usage analytics engines and localized compliance certification assets to defend against pure-play specialists compressing pricing in the mid-market. Deepen vertical integration into healthcare and financial services workflow modules to capture renewal revenue from German and United States enterprises facing strictest regulatory timelines. Prioritize hybrid cloud infrastructure partnerships that satisfy GDPR data residency requirements without sacrificing elastic scaling economics. For New Entrants and Emerging Players: Differentiate on India procurement digitization and healthcare vertical specialization as white-space targets with lowest incumbent saturation. Target technology startups in Bangalore and Hyderabad managing vendor sprawl without dedicated procurement staff as the most penetrable segment. Pursue channel partnerships with Indian system integrators and regional ERP resellers as the primary go-to-market angle to bypass direct sales cost structures. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward platforms with pre-built regulatory workflow templates and explainable AI modules already deployed in German and French enterprise accounts. Long-term viability favors vendors bridging procurement automation with sustainability reporting convergence for CSRD compliance. Target acquisition archetypes include specialized usage analytics engines and regional compliance certification providers. Watch for inflection signals in Indian RBI vendor risk management guideline enforcement accelerating platform adoption among domestic financial institutions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity eliminates spreadsheet-based renewal tracking for mid-market United States technology firms. |
| Geographic Expansion | Localized GDPR and EU AI Act certification opens German automotive and pharmaceutical procurement budgets. |
| Acquisition of Specialist Firm | Usage analytics engines compress procurement cycle times from weeks to hours for CFO-led finance teams. |
| Strategic Partnership | Hybrid cloud infrastructure alliances satisfy HIPAA requirements for United States healthcare compliance officers. |
| Product Launch | Agentic AI renewal negotiation modules displace traditional category manager roles in procurement organizations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at technology firms, financial services institutions, and healthcare organizations across the United States, Germany, and India; and secondary validation drawing from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and ERP vendor integration documentation. Bottom-up deployment estimates triangulated against top-down addressable market calculations.
Across the analysis window, the analytical framework modeled segmentation dimensions spanning deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from fitted growth curves applied to subscription management and invoice automation module penetration rates, with inputs including API standardization velocity, regulatory compliance deadline clustering, and mid-market technology firm formation trends.
Material uncertainties—regulatory enforcement timing variations, ERP vendor API roadmap changes, and cloud infrastructure cost volatility—sit outside the modeled envelope. Forecasts reflect documented assumptions about CFO ownership consolidation and agentic AI adoption curves. Practitioners should keep alternative scenarios live as EU AI Act implementation timelines and Indian procurement digitization waves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Autonomous Finance Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
Lendtech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Micro-Investing Platform Market
FinTech
Financial Forecasting Software Market
FinTech
Financial Consolidation Software Market
FinTech
AI Finance Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Account Checking Software Market
FinTech
Financial Audit Software Market
FinTech
North America Fintech Market
FinTech
Europe AI in Fintech Market
FinTech
Business Analytics in Fintech Market
FinTech
Fintech Lending Market
FinTech
Asia-Pacific Financial Analytics Market