
 Financial Management Software Market | 2026-2036
Financial Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Management Software Market Insights
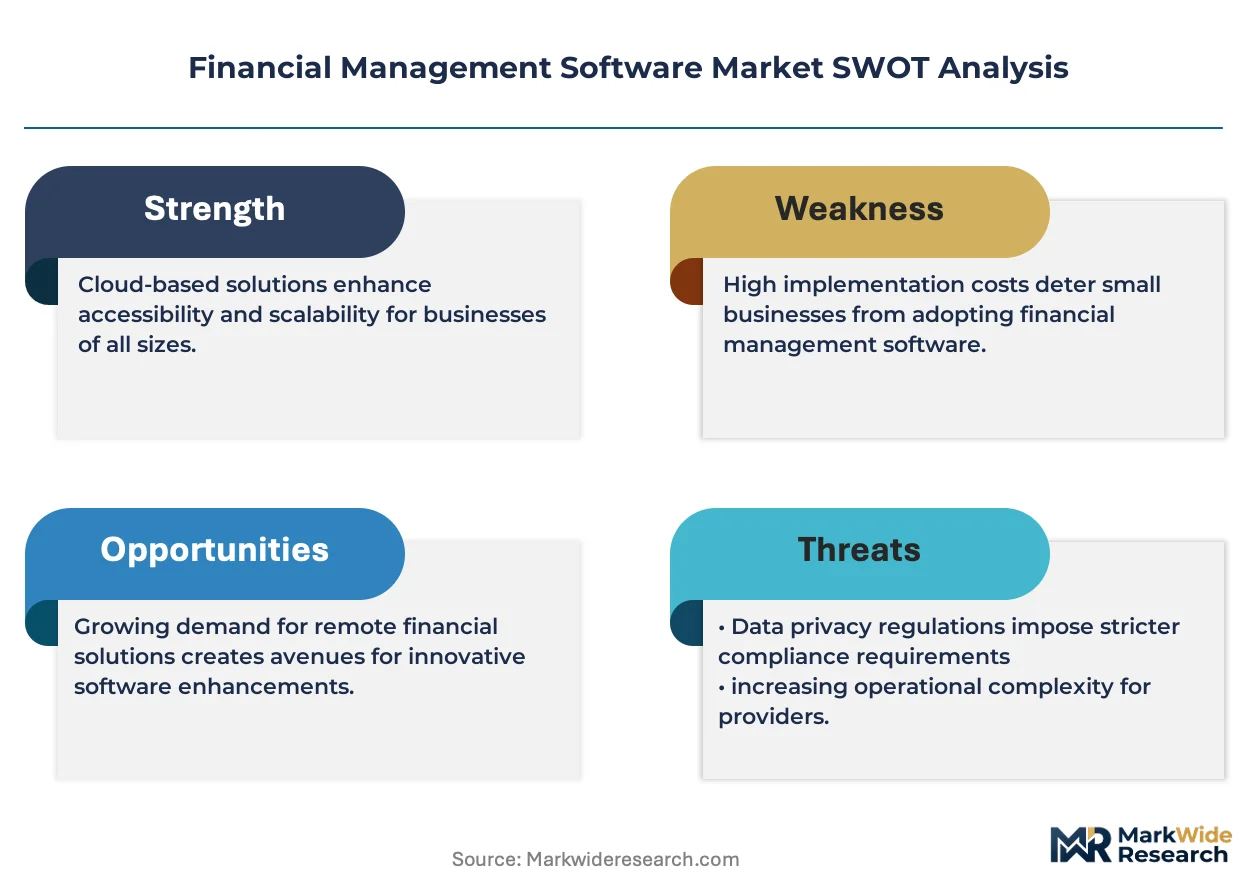
Project finance and recurring-revenue leasing structures for enterprise software procurement is narrowing the competitive field to vendors with balance-sheet depth. Oracle Corporation leverages its cloud infrastructure scale to anchor multi-year subscription contracts with Fortune 500 treasuries. SAP SE sustains R&D intensity across compliance monitoring modules that integrate with ERP core systems. Xero Limited competes through product specialization in small-business payroll and expense workflows.
Financial management software comprises modular applications for general ledger consolidation, real-time cash-flow forecasting, automated reconciliation, and regulatory reporting, typically deployed through browser-accessible dashboards or API-connected microservices. Its primary commercial purpose is to replace spreadsheet-dependent finance operations with auditable, permissioned data flows that reduce close-cycle latency. Cloud-based deployment leads solution type adoption among mid-market manufacturers and telecommunications operators seeking to avoid capital expenditure on server infrastructure. Compliance monitoring represents the fastest-expanding solution category as BFSI end users confront escalating AML and data-privacy obligations across multiple jurisdictions. Subscription pricing dominates new contracts, though enterprise agreements retain margin concentration at the top of the customer pyramid.
The SEC, GDPR, and EU AI Act collectively shape product roadmaps by mandating algorithmic transparency in credit-scoring modules and granular consent management for cross-border data transfers. HIPAA and SOX requirements in the United States further segment the vendor landscape, as only architectures with pre-certified audit controls qualify for healthcare and publicly traded end users. Stakeholders must weigh the trade-off between cloud-native agility and the compliance overhead of jurisdiction-specific data residency as procurement decisions multiply across regional subsidiaries.
Market Dynamics
Cloud-native architectures are compressing deployment timelines from quarters to weeks, forcing incumbent vendors to reengineer monolithic codebases while mid-market buyers demand consumption-based pricing that transfers infrastructure risk to suppliers.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions across Germany, France, and Italy must embed algorithmic audit trails into credit-scoring modules, creating replacement demand for legacy systems lacking native transparency controls.
- Real-time treasury workflows:Telecommunications operators and mid-market manufacturers are abandoning batch-processed ERP finance modules in favor of API-connected cash forecasting tools that reduce working capital latency.
- GDPR cross-border data restrictions:Multinational enterprises require jurisdiction-specific data residency controls, compelling software procurement that segments European operations from North American cloud instances.
Market Restraints
- Specialized compliance engineering talent:Vendors face acute scarcity of developers certified in SOX audit controls and HIPAA privacy frameworks, inflating R&D labor costs.
- Concentrated cloud infrastructure dependency:Three hyperscale providers dominate server capacity for financial workloads, creating single-point-of-failure risk and limiting vendor negotiation leverage.
- Spreadsheet persistence in small enterprises:Manual accounting workflows remain entrenched among businesses below fifty employees, delaying SaaS conversion and elongating sales cycles.
Strategic Opportunities
- Embedded finance convergence:API-first accounting platforms that integrate with vertical SaaS in construction and healthcare capture workflow data before it reaches general ledgers, locking in switching costs.
- CSRD sustainability reporting mandates:European corporates require carbon-accounting modules that feed directly into financial consolidation systems, opening green-ledger product lines.
- India's digital public infrastructure:Account aggregator frameworks and UPI transaction rails enable native-born fintech-accounting hybrids to bypass traditional ERP adoption curves.
Industry Challenges
- Legacy ERP integration complexity:Hybrid deployments connecting cloud finance modules to on-premise SAP or Oracle cores demand specialized middleware engineering that extends implementation timelines.
- Multi-jurisdiction certification backlog:Vendors must sequence SOX, HIPAA, and PCI-DSS audits across quarterly release cycles, delaying feature launches in regulated verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Management Software Market |
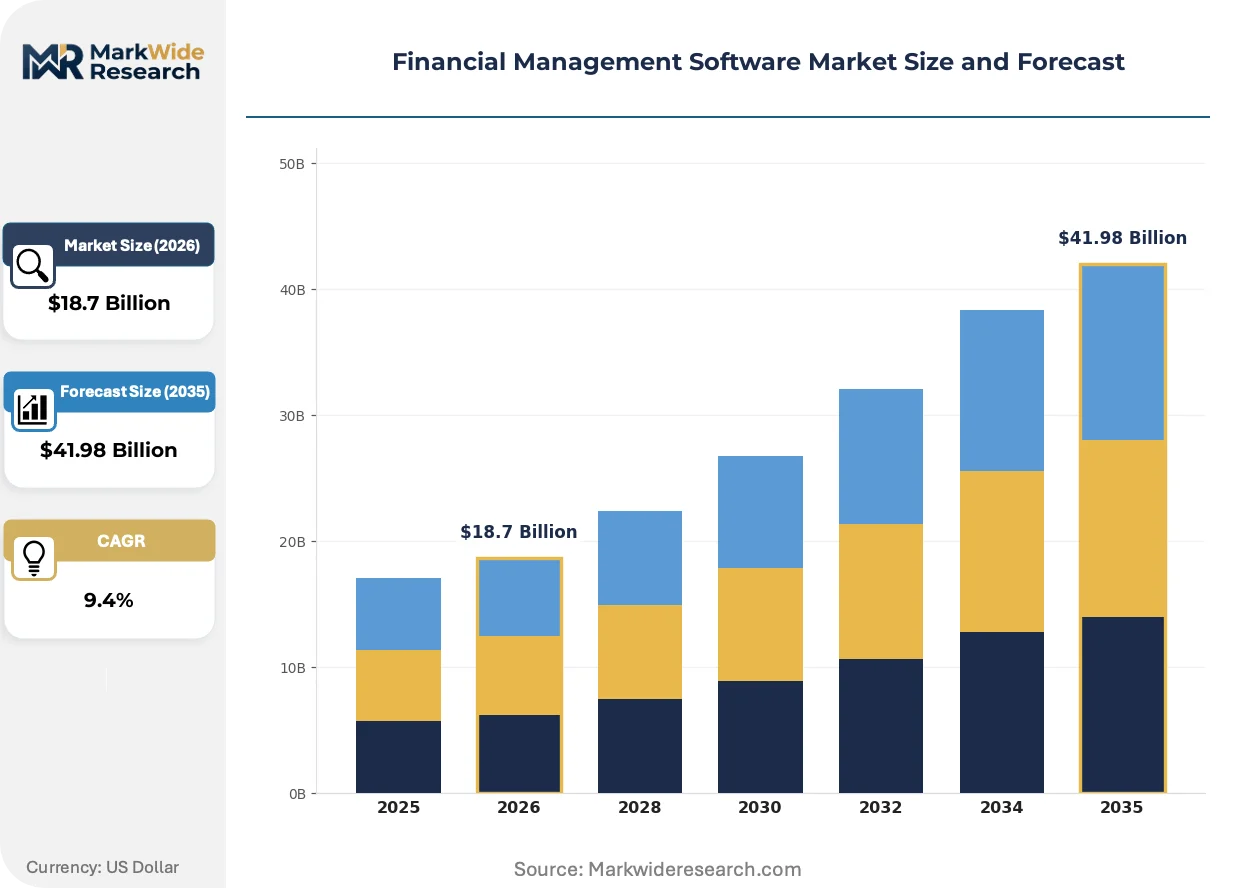
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Virtualized Solution Type: Accounting, Expense Management, Payroll Processing, Budgeting, Compliance Monitoring End User Industry: BFSI, Manufacturing, Telecommunications, Education, Non-Profit, Real Estate Pricing Model: Subscription, One-Time License, Freemium, Pay-As-You-Go, Enterprise Agreement |
| Companies Covered | Oracle Corporation, SAP SE, Intuit Inc., Microsoft Corporation, Sage Group plc, Infor Inc., Workday Inc., NetSuite, Xero Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Management Software Market Trends and Innovations
Distributed ledger and AI inference technologies are rewriting core accounting primitives, while procurement behavior shifts reward vendors who unbundle implementation from subscription fees.
Embedded machine-learning inference engines are virtualizing exception-handling in reconciliation workflows. Mid-market finance teams at real estate investment trusts and commercial lenders are deploying these tools to compress month-end close cycles from ten days to under seventy-two hours. The technology is virtualizing tier-one accounting firm labor by automating variance analysis that previously required human judgment.
The EU AI Act's risk-classification framework now mandates human-in-the-loop overrides for automated credit decisions exceeding defined thresholds. Vendors serving BFSI end users must engineer explainability dashboards that surface model coefficients to compliance officers. German and Dutch banks are responding by procuring modular compliance layers that sit between core ledgers and algorithmic scoring engines.
Buyers are unbundling implementation services from recurring subscriptions, treating deployment as capital expenditure while demanding usage-based pricing for ongoing platform access. Systems integrators and accounting firms are capturing implementation margin that vendors previously booked as professional services. This pattern is most pronounced among United States-based private equity portfolio companies undergoing rapid ERP consolidation.
Financial Management Software Market Segmentation
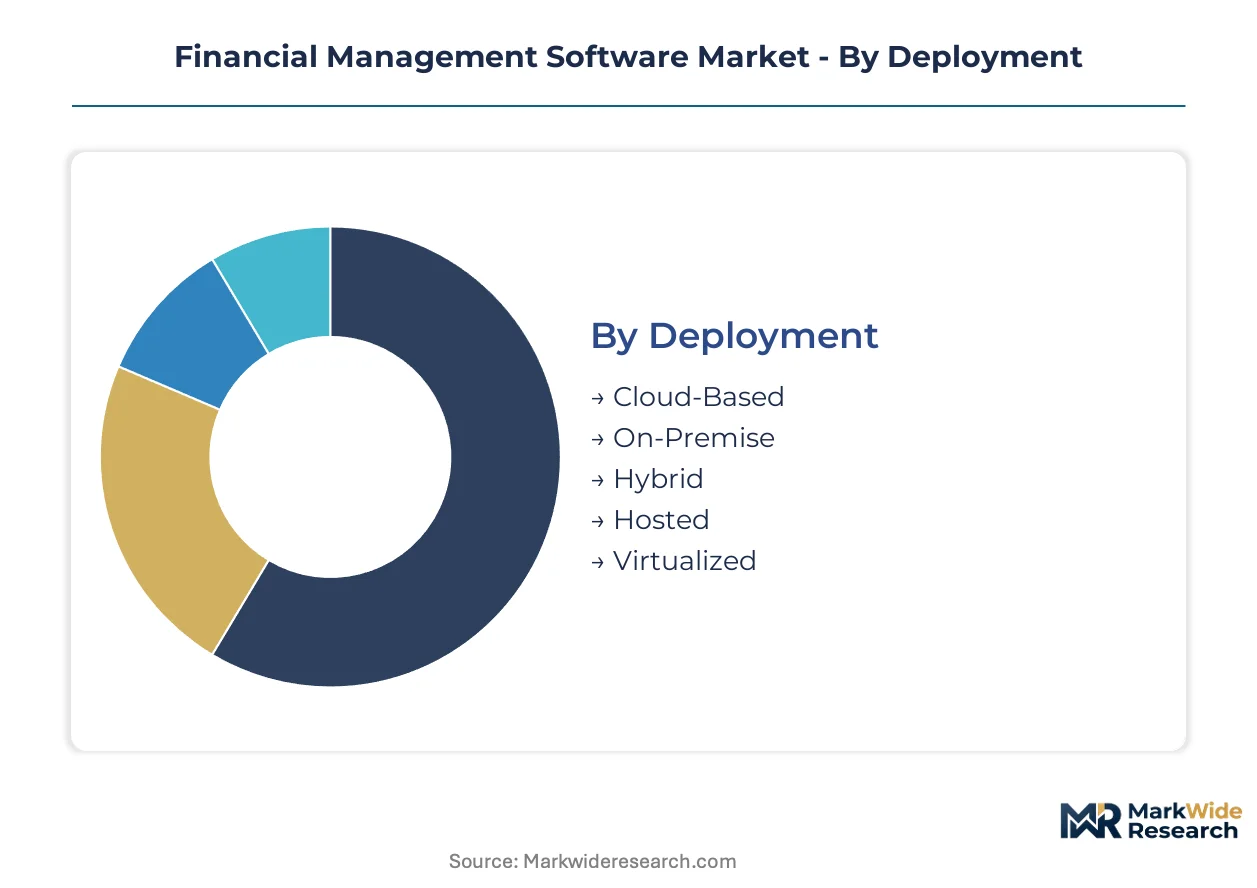
Segmentation reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and capital structure. Buyers select deployment modes and pricing constructs that align working capital constraints with compliance obligations.
Deployment:
Mature cloud architectures now dominate procurement decisions while legacy on-premise installations persist in regulated verticals requiring data sovereignty.
- Cloud-Based:Browser-accessible platforms with API-connected microservices eliminate server capital expenditure. Mid-market manufacturers in the United States and telecommunications operators in Germany prioritize these deployments to compress implementation timelines from quarters to weeks.
- On-Premise:Perpetually licensed software running on customer-managed hardware. German banks and French insurers maintain these installations to satisfy GDPR data residency mandates and EU AI Act audit trail requirements that cloud instances struggle to guarantee.
- Hybrid:Split architectures connecting cloud finance modules to on-premise transaction cores. Healthcare systems in the United States deploy hybrid stacks to isolate HIPAA-protected patient billing data while leveraging cloud analytics for operational dashboards.
- Hosted:Single-tenant software operated by vendors on dedicated infrastructure. Real estate investment trusts favor hosted deployments for treasury workstations requiring deterministic latency on cash forecasting calculations.
- Virtualized:Containerized applications orchestrated across private data centers. Japanese manufacturing conglomerates adopt virtualized stacks to maintain METI-aligned cybersecurity frameworks while achieving cloud-like elasticity.
Cloud-Based handles the majority of throughput; Hybrid is expanding most quickly as regulated enterprises seek compromise positions.
Solution Type:
Application depth correlates directly with regulatory pressure intensity across jurisdictions.
- Accounting:Core general ledger consolidation with automated reconciliation engines. Small-business payroll providers in Australia and the United Kingdom embed accounting modules as loss-leaders to capture expense workflow data upstream.
- Expense Management:Corporate card integration with real-time policy enforcement. United States-based professional services firms and consulting partnerships drive demand for mobile-first expense capture that reduces reimbursement cycle times.
- Payroll Processing:Tax withholding automation with jurisdiction-specific filing. Indian fintech-accounting hybrids leverage UPI rails and account aggregator frameworks to bypass traditional ERP adoption curves in this category.
- Budgeting:Driver-based forecasting with scenario modeling capabilities. Private equity portfolio companies undergoing rapid consolidation in the United States treat budgeting module procurement as capital expenditure separate from recurring platform subscriptions.
- Compliance Monitoring:AML screening and algorithmic audit trail generation. BFSI end users across Germany, France, and Italy confront escalating EU AI Act mandates for explainability dashboards in credit-scoring workflows.
Accounting retains the largest installed base; Compliance Monitoring is gaining share fastest as regulatory frameworks tighten.
End User Industry:
Vertical specialization determines feature prioritization and sales cycle duration.
- BFSI:Institutions requiring SOX audit controls, PCI-DSS certification, and granular consent management for cross-border transfers. United States banks and European credit unions represent the most demanding certification environment.
- Manufacturing:Mid-market producers seeking to avoid capital expenditure on server infrastructure. German and Italian manufacturers lead adoption of consumption-based pricing that transfers infrastructure risk to suppliers.
- Telecommunications:Operators abandoning batch-processed ERP finance modules for API-connected cash forecasting. Real-time treasury workflows reduce working capital latency in this capital-intensive sector.
- Education:Universities and research institutions with complex grant accounting requirements. Endowment management modules with donor-restricted fund tracking characterize procurement in this segment.
- Non-Profit:Organizations requiring fund accounting with programmatic expense allocation. Donor transparency mandates drive demand for audit-ready reporting without enterprise-grade implementation budgets.
- Real Estate:Investment trusts and property managers with recurring-revenue leasing structures. These entities procure through multi-year subscription contracts anchored by balance-sheet depth requirements.
BFSI commands premium pricing tiers; Manufacturing is climbing the fastest on volume as cloud-native deployment eliminates upfront infrastructure barriers.
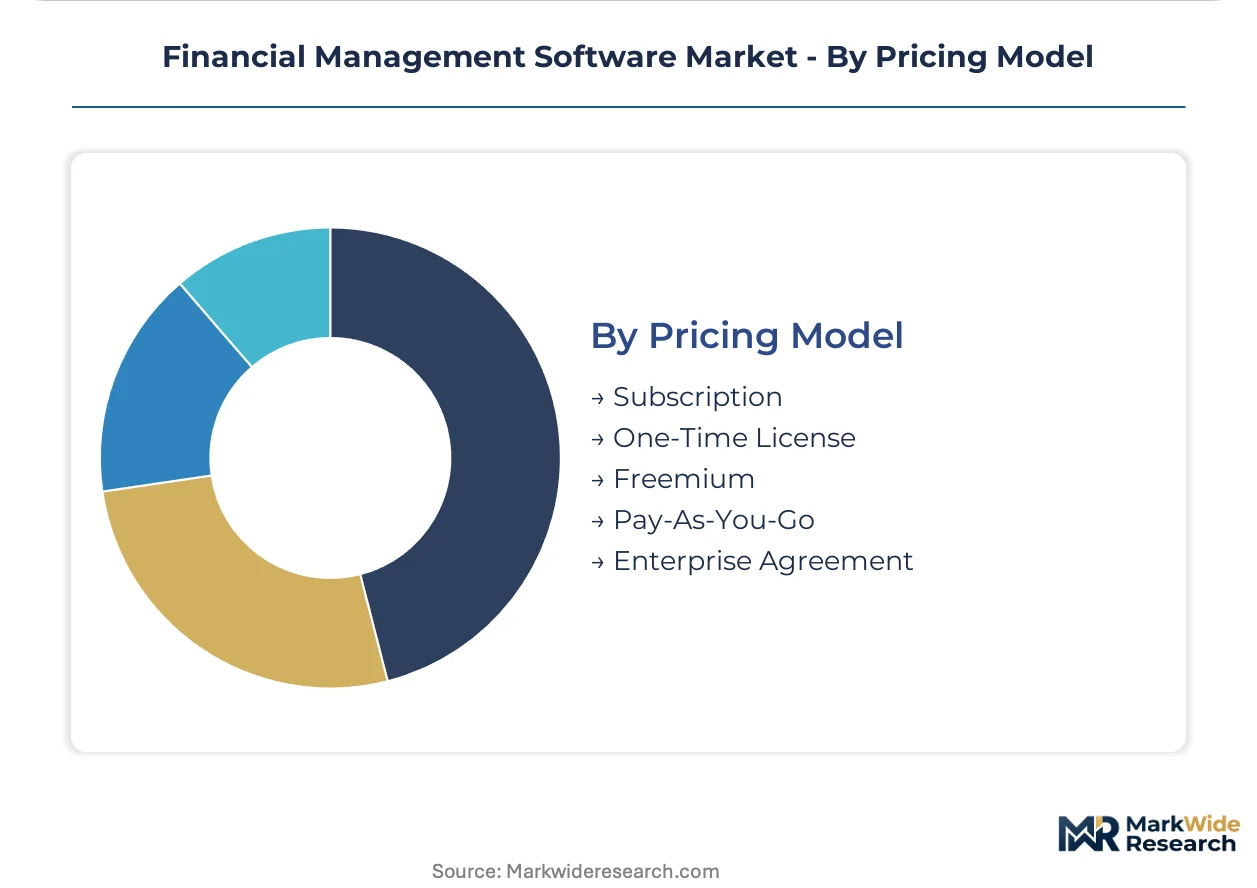
Pricing Model:
Contract structures reflect buyer sophistication and vendor balance-sheet capacity.
- Subscription:Recurring fees for platform access with embedded maintenance. Dominates new contracts among mid-market buyers seeking to operationalize software expenditure.
- One-Time License:Perpetual rights with separate maintenance agreements. Persists in on-premise installations where buyers treat software as capital assets.
- Freemium:Tiered feature access with conversion triggers at employee or transaction thresholds. Captures small enterprises below fifty employees where spreadsheet persistence delays full SaaS conversion.
- Pay-As-You-Go:Consumption-based pricing tied to transaction volume or API calls. Appeals to seasonal businesses and project-based professional services with lumpy revenue patterns.
- Enterprise Agreement:Multi-year commitments with volume discounts and dedicated support. Fortune 500 treasuries and private equity portfolio companies consolidate vendor relationships through these structures.
Subscription captures the broadest customer base; Enterprise Agreement delivers the steepest expansion trajectory in absolute contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where SaaS procurement by financial services and real estate firms outpaces other national markets. European buyers face compliance premiums driven by GDPR and EU AI Act mandates. Emerging markets compress contract values through localized fintech-accounting hybrids.
United States
Fortune 500 treasuries and private equity portfolio companies anchor demand for multi-year enterprise agreements. SEC audit controls and SOX requirements segment procurement toward vendors with pre-certified architectures. New York and San Francisco financial clusters drive adoption of real-time treasury workflows and API-connected cash forecasting tools.
Germany
Mid-market manufacturers prioritize consumption-based pricing that transfers infrastructure risk to suppliers. EU AI Act mandates for algorithmic transparency in credit-scoring modules create replacement demand for legacy systems. Frankfurt's banking cluster and Munich's industrial corridor lead procurement of compliance monitoring layers with explainability dashboards.
United Kingdom
Small-business payroll providers embed accounting modules as loss-leaders to capture expense workflow data upstream. GDPR cross-border data restrictions compel jurisdiction-specific data residency controls. London's fintech hub and Manchester's professional services cluster drive mobile-first expense capture adoption among consulting partnerships.
India
Account aggregator frameworks and UPI transaction rails enable native-born fintech-accounting hybrids to bypass traditional ERP adoption curves. RBI oversight shapes procurement toward platforms with embedded audit trails for digital payment reconciliation. Bengaluru's SaaS corridor and Mumbai's financial district concentrate demand for payroll processing automation with tax withholding compliance.
Japan
Manufacturing conglomerates adopt virtualized stacks to maintain METI-aligned cybersecurity frameworks while achieving cloud-like elasticity. HIPAA-equivalent data protection standards segment healthcare procurement toward architectures with pre-certified privacy controls. Tokyo's corporate headquarters and Osaka's industrial belt sustain demand for hybrid deployments connecting cloud modules to on-premise transaction cores.
Financial Management Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in workflow automation niches. The vendor base organizes around three strategic archetypes: hyperscale cloud infrastructure operators, ERP core system incumbents, and vertical SaaS specialists. Consolidation pressure intensifies as project finance and recurring-revenue leasing structures narrow the competitive field to vendors with balance-sheet depth. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized compliance certification.
Within the hyperscale infrastructure tier, Oracle Corporation and Microsoft Corporation exemplify platform integrators leveraging cloud scale to anchor multi-year subscription contracts. SAP SE occupies a position among ERP core incumbents sustaining R&D intensity across compliance monitoring modules. Xero Limited represents the vertical SaaS specialist archetype, competing through product specialization in small-business payroll and expense workflows.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Intuit Inc. |
| Microsoft Corporation |
| Sage Group plc |
| Infor Inc. |
| Workday Inc. |
| NetSuite |
| Xero Limited |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud infrastructure concentration in the United States anchors margin pools at the platform integrator tier, while downstream pricing pressure from mid-market buyers compresses professional services premiums into standardized subscription tiers. This structural asymmetry forces component specialists to absorb implementation risk while hyperscalers capture recurring-revenue expansion.
Pricing Analysis
Configured-to-order enterprise agreements command substantial premiums over standardized SaaS tiers, with Fortune 500 treasuries paying differential rates for dedicated support and jurisdiction-specific data residency controls. Pricing stratifies across premium compliance-certified, standard cloud-native, and economy freemium tiers based on audit trail granularity and API call volumes. Cost compression in the mid-market segment is intensifying because consumption-based pricing transfers infrastructure risk to vendors. Small enterprises below fifty employees exhibit highest price sensitivity, while BFSI institutions with SOX and PCI-DSS mandates demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration among three hyperscale providers—Amazon Web Services, Microsoft Azure, and Google Cloud Platform—holds the majority of server capacity for financial workloads. Engineering talent pools concentrate in India, Germany, and the United States, with specialized compliance developers certified in HIPAA and SOX frameworks commanding scarcity premiums. Raw material dependencies center on semiconductor fabrication, data center real estate, and fiber optic infrastructure. Single-source vulnerability runs through concentrated cloud infrastructure providers, creating systemic continuity exposure. Distribution runs through direct enterprise sales teams, systems integrators, and vertical SaaS marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Financial management software functions as a service-attach opportunity where compliance monitoring modules and implementation services expand faster than core accounting subscriptions. The recurring-revenue attach rate for audit-ready reporting layers outpaces platform growth by a material margin.
For Market Incumbents: Pre-empt displacement by cloud-native entrants through backward integration into specialized compliance engineering talent pools in Germany and India. Anchor multi-year enterprise agreements with balance-sheet depth that mid-market SaaS vendors cannot match. Fortify against API-first accounting platforms by embedding workflow data capture upstream in construction and healthcare verticals. For New Entrants and Emerging Players: Establish a beachhead in India's digital public infrastructure corridor, where account aggregator frameworks and UPI rails enable fintech-accounting hybrids to bypass traditional ERP adoption curves. Target small-business payroll and expense workflows in Australia and the United Kingdom where spreadsheet persistence delays incumbent conversion. Deploy freemium tiering with mobile-first capture to compress sales cycles below fifty-employee thresholds. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across compliance monitoring solution categories as EU AI Act mandates force algorithmic transparency investments. Long-term viability centers on vendors with pre-certified architectures spanning SOX, HIPAA, and PCI-DSS frameworks. Acquisition targets should demonstrate vertical workflow integration in healthcare or construction with switching-cost lock-in. The signal to watch is quarterly certification backlog duration across regulated verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures embed into vertical SaaS workflows before data reaches general ledgers. |
| Compliance Certification Investment | Pre-certified SOX and HIPAA controls qualify vendors for healthcare and publicly traded end users. |
| Geographic Expansion | Localized GDPR and EU AI Act certification opens German and French banking procurement channels. |
| Strategic Partnership | Systems integrators capture implementation margin that vendors previously booked as professional services. |
| Acquisition of Specialist Firm | Vertical SaaS specialists in construction and healthcare bring workflow data capture capabilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with CFOs, IT procurement officers, compliance officers at BFSI institutions, and platform engineers at hyperscale cloud providers. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory submissions under GDPR and EU AI Act frameworks, and healthcare procurement databases. Bottom-up sizing of subscription revenue pools triangulated against top-down market value estimates.
Calibration against historical adoption curves and regulatory implementation timelines anchored projections across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, end-user industry vertical, integration complexity with legacy ERP cores, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed vendor revenue ranges and disclosed customer expansion metrics. Forecast inputs incorporated EU AI Act compliance deadlines and CSRD sustainability reporting phase-ins.
Sensitivities concentrate around regulatory deadline delays, cloud infrastructure concentration events, and spreadsheet-to-SaaS conversion acceleration in small enterprises. Forecasts reflect assumptions about compliance cost pass-through rates and mid-market buyer price elasticity. Quarterly review of certification backlog durations, hyperscaler capacity expansion announcements, and vertical SaaS partnership formations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Germany Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
Finance Cloud Market
FinTech
Global Saas Spend Management Software Market
FinTech
China AI in Fintech Market
FinTech
United States Fintech Market
FinTech
Financial Audit Software Market
FinTech
Australia Fintech Market
FinTech
Europe Financial Analytics Market
FinTech
Robo Advisory Market
FinTech
Spend Management Platform Market
FinTech
Malaysia Fintech Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Financial Analytics Market
FinTech
Netherlands AI in Fintech Market
FinTech
Hand Account Software Market