
 Europe Embedded Finance Market | 2026-2036
Europe Embedded Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Embedded Finance Market Foresight
API-first infrastructure is shifting embedded finance from legacy bank partnerships toward direct platform integration. Solaris SE anchors the German-speaking market through its full banking-as-a-service license stack. Stripe leverages its payment processing dominance to extend lending and treasury products into software platforms. BBVA competes through its proprietary Open Platform, which sustains a regulated foothold across Iberia and Latin American corridors.
Embedded finance denotes the integration of banking, lending, insurance, or investment services into non-financial digital platforms via API layers, typically operating on RESTful architectures with sub-200-millisecond response thresholds for real-time transaction authorization. Its primary commercial purpose is to capture financial services margin at the point of commerce without redirecting users to standalone banking interfaces. Payment processing leads service-type revenue pools due to high transaction velocity, while lending solutions represent the fastest-expanding segment as buy-now-pay-later mechanics penetrate B2B invoicing workflows. Cloud-based deployment dominates among fintech-native providers, though hybrid architectures persist among incumbent banks navigating EBA cloud outsourcing guidelines.
PSD3, DORA, and GDPR collectively determine product architecture, data handling protocols, and third-party risk management obligations for embedded finance providers operating across EU member states. The European Banking Authority's draft technical standards on strong customer authentication directly influence checkout friction and conversion metrics for platform-integrated payments. Stakeholders must monitor whether upcoming EBA guidance on payment initiation services narrows the regulatory gap between licensed credit institutions and API-integrated non-bank distributors.
Market Dynamics
API-first banking infrastructure is compressing time-to-market for non-financial platforms seeking embedded financial services, shifting competitive advantage from regulatory licensing speed to developer experience and sub-200-millisecond response reliability.
Growth Catalysts
- PSD3 implementation:The Payment Services Directive 3 tightens open banking standards across EU member states, mandating stronger customer authentication that paradoxically accelerates API standardization and reduces integration friction for platform distributors.
- Retail checkout transformation:German and French merchants are deploying point-of-sale lending at transaction completion, capturing consumer credit demand without redirecting to standalone banking interfaces.
- Nordic open banking maturity:Sweden, Norway, and Denmark possess the highest account-to-account payment penetration in Europe, enabling real-time treasury services integration into accounting software and ERP platforms.
Market Restraints
- Cloud outsourcing constraints:The European Banking Authority's draft technical standards on ICT risk management impose data localization requirements that increase infrastructure costs for fintech-native providers operating multi-tenant architectures.
- Strong customer authentication friction:Regulatory-mandated two-factor verification at checkout introduces abandonment risk for low-consideration purchases under fifty euros, particularly affecting impulse-driven retail categories.
- Licensed credit institution competition:Incumbent banks with existing deposit-taking permissions can undercut banking-as-a-service fees through proprietary balance sheet deployment, compressing margins for API-dependent distributors.
Strategic Opportunities
- B2B invoice financing:Buy-now-pay-later mechanics are penetrating supplier payment workflows, with Netherlands-based trade credit platforms demonstrating viable unit economics for SME working capital extension.
- Embedded insurance at checkout:Travel and electronics retailers in the United Kingdom are piloting parametric warranty products triggered by transaction data rather than manual underwriting processes.
- DORA compliance services:The Digital Operational Resilience Act creates advisory and tooling demand for third-party risk management, incident reporting automation, and resilience testing for non-bank financial providers.
Industry Challenges
- API talent scarcity:Embedded finance providers compete with hyperscale technology firms for engineers proficient in financial-grade REST architecture, OAuth 2.0 implementation, and regulatory-compliant error handling.
- Cross-border licensing fragmentation:Passporting rights under EU financial services law require member-state-specific notifications and capital requirements that delay unified product rollouts by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Embedded Finance Market |
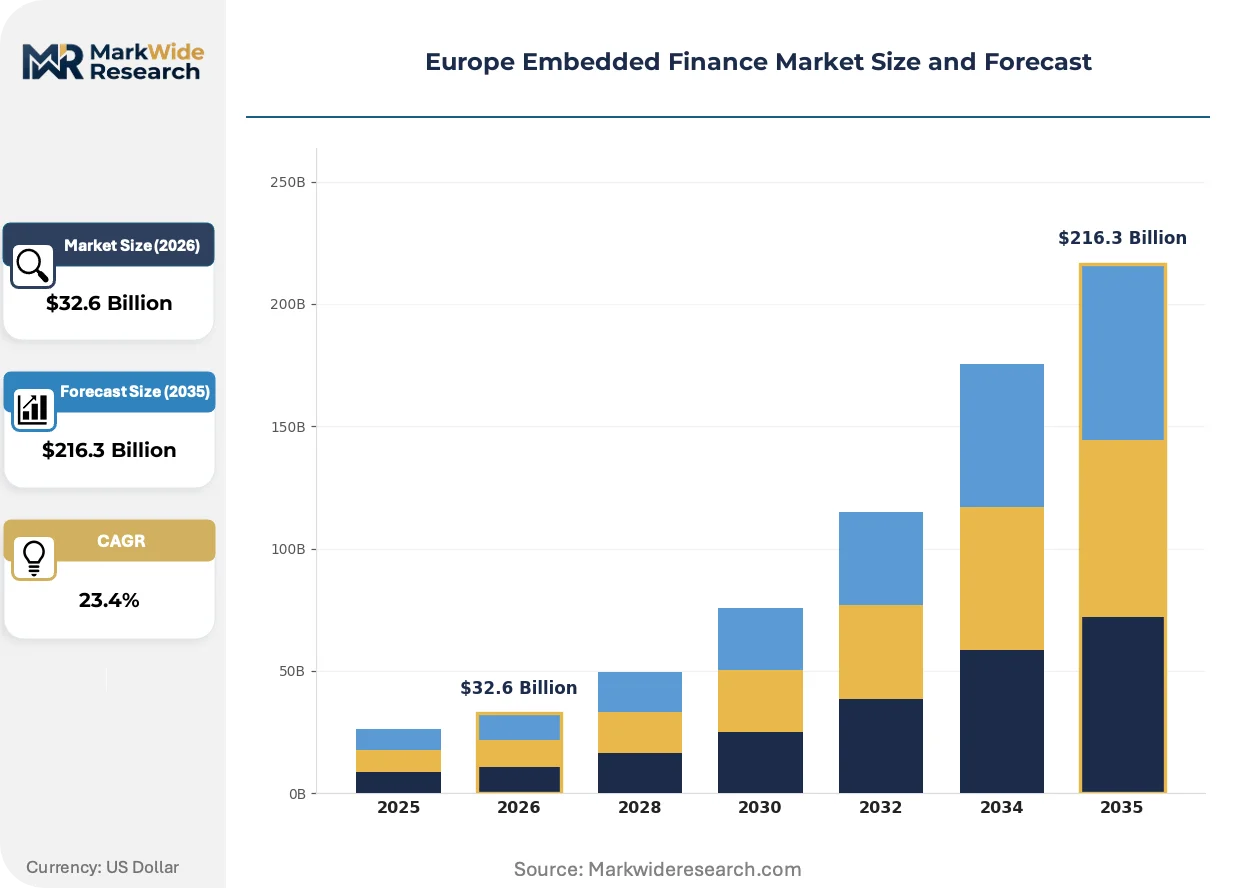
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $216.3 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Lending Solutions, Insurance, Investment Services Customer Type: SMEs, Large Enterprises, Startups, Corporates Deployment Model: Cloud-Based, On-Premise, Hybrid, Mobile Integration End User: Retailers, E-Commerce Platforms, Financial Institutions, Tech Companies |
| Companies Covered | PayPal, Marqeta, Solaris SE, Froda, Unit, BBVA, SDK.finance, Dreamix, Stripe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Embedded Finance Market Shifts & Advancements
Real-time payment infrastructure and regulatory technology convergence are redefining how financial services embed into commerce platforms, compressing the traditional bank-platform partnership cycle from years to quarters.
Modular banking-as-a-service stacks are modularizing the traditional core banking system into discrete microservices for KYC, ledger management, and payment processing. German automotive marketplaces and French property management platforms are adopting these components to launch branded financial products within ninety-day development windows. This architecture is modularizing the competitive barrier between licensed banks and technology platforms, enabling the latter to assemble regulated financial services without acquiring full banking charters.
DORA's incident reporting mandates are operationalizing resilience requirements that previously existed as supervisory guidance. The regulation compels embedded finance providers to maintain automated detection systems for operational disruptions affecting payment initiation or account information services. Fintech distributors serving United Kingdom and Irish markets are investing most heavily in compliance tooling, anticipating that the Financial Conduct Authority will mirror EBA technical standards in post-Brexit rulemaking.
Merchant procurement of financial services is consolidating around platform-native solutions that consolidate payment acceptance, working capital, and treasury management in single interfaces. Independent software vendors serving hospitality and professional services verticals are displacing standalone banking relationships by embedding lending decisions into cash flow forecasting tools. This pattern is most visible in Nordic markets, where accounting software penetration exceeds seventy percent among SMEs and real-time bank feeds enable automated credit underwriting.
Europe Embedded Finance Market Segmentation
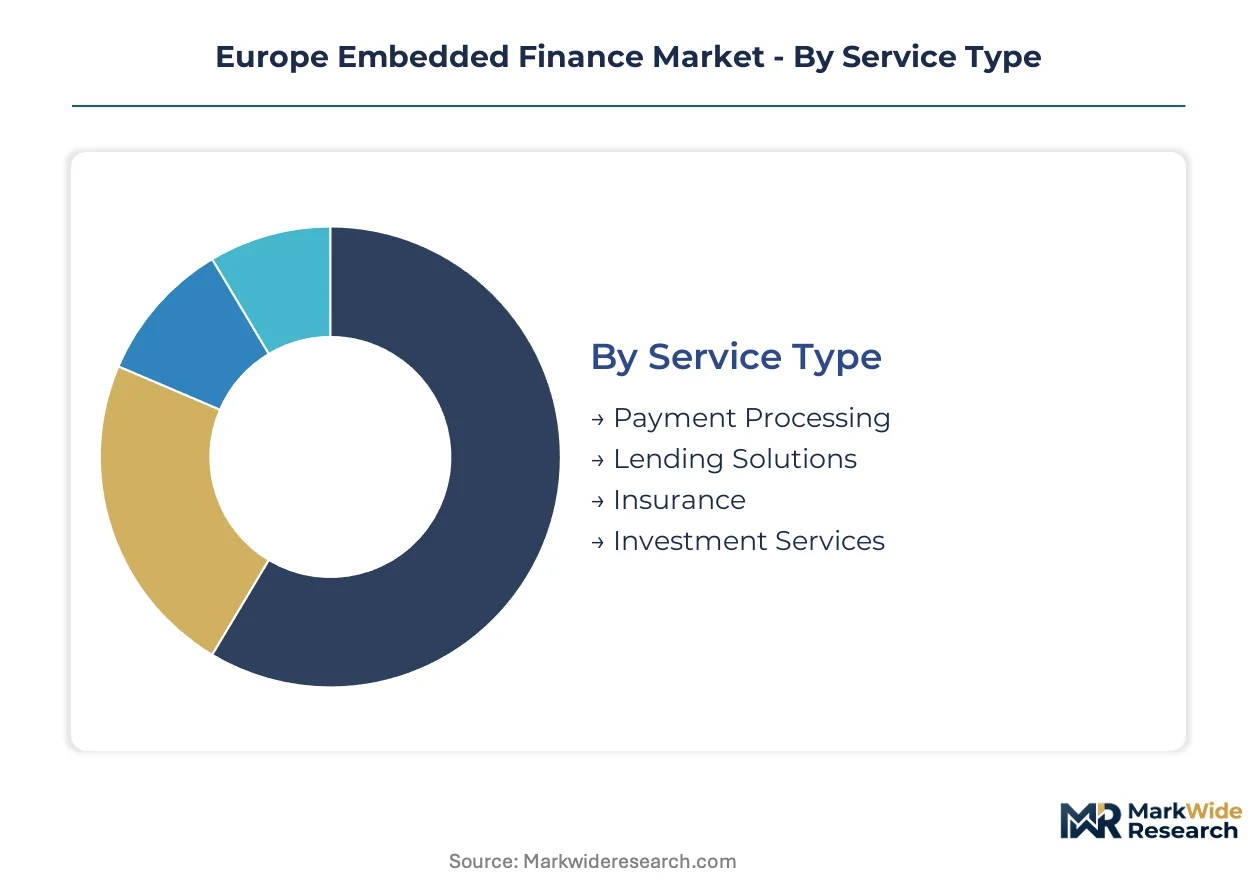
Segmentation in embedded finance reveals how API architecture choices and customer scale requirements fragment the competitive landscape. Providers must align service configurations with deployment constraints and end-user sophistication levels across European regulatory jurisdictions.
Service Type:
Standardized transaction rails dominate high-volume segments while bespoke credit algorithms capture premium pricing in specialized lending workflows.
- Payment Processing:RESTful API architectures handling authorization requests within sub-200-millisecond thresholds. German and French retailers concentrate demand here as checkout integration becomes table stakes for omnichannel commerce.
- Lending Solutions:Buy-now-pay-later mechanics and B2B invoice financing powered by real-time cash flow underwriting. Netherlands-based trade credit platforms demonstrate viable unit economics for SME working capital extension across Nordic markets.
- Insurance:Parametric warranty products triggered by transaction data rather than manual underwriting. United Kingdom travel and electronics retailers pilot these at checkout.
- Investment Services:Micro-investment roundups and fractional share purchases embedded in spending applications. Regulatory complexity limits deployment speed under MiFID II suitability requirements.
Leading the category by volume: Payment Processing. Growing fastest: Lending Solutions.
Customer Type:
Enterprise scale determines whether clients demand full banking-as-a-service stacks or modular microservices for specific financial functions.
- SMEs:Accounting software integration drives adoption, with automated credit underwriting enabled by real-time bank feeds. Nordic markets show seventy percent penetration among this cohort.
- Large Enterprises:Proprietary balance sheet deployment and captive treasury management. These clients negotiate direct licensing arrangements that compress margins for API-dependent distributors.
- Startups:Rapid time-to-market requirements favor pre-configured compliance wrappers and sandboxed testing environments.
- Corporates:Cross-border payment optimization and multi-entity cash pooling across EU member states with passporting rights.
Dominant by revenue contribution: Large Enterprises. Expanding most quickly: SMEs.
Deployment Model:
Infrastructure sovereignty concerns fragment cloud strategies between fintech-native multi-tenancy and incumbent hybrid architectures.
- Cloud-Based:Dominant among fintech-native providers leveraging containerized microservices for KYC, ledger management, and payment processing. EBA cloud outsourcing guidelines impose data localization requirements that increase costs.
- On-Premise:German automotive marketplaces and French property management platforms retain sensitive customer data within jurisdictional boundaries for GDPR compliance.
- Hybrid:Incumbent banks navigating EBA technical standards maintain core systems on-premise while API gateways operate in cloud environments.
- Mobile Integration:SDK-based deployment for native application embedding, prevalent among hospitality and professional services verticals.
Highest deployment share: Cloud-Based. Steepest expansion trajectory: Hybrid.
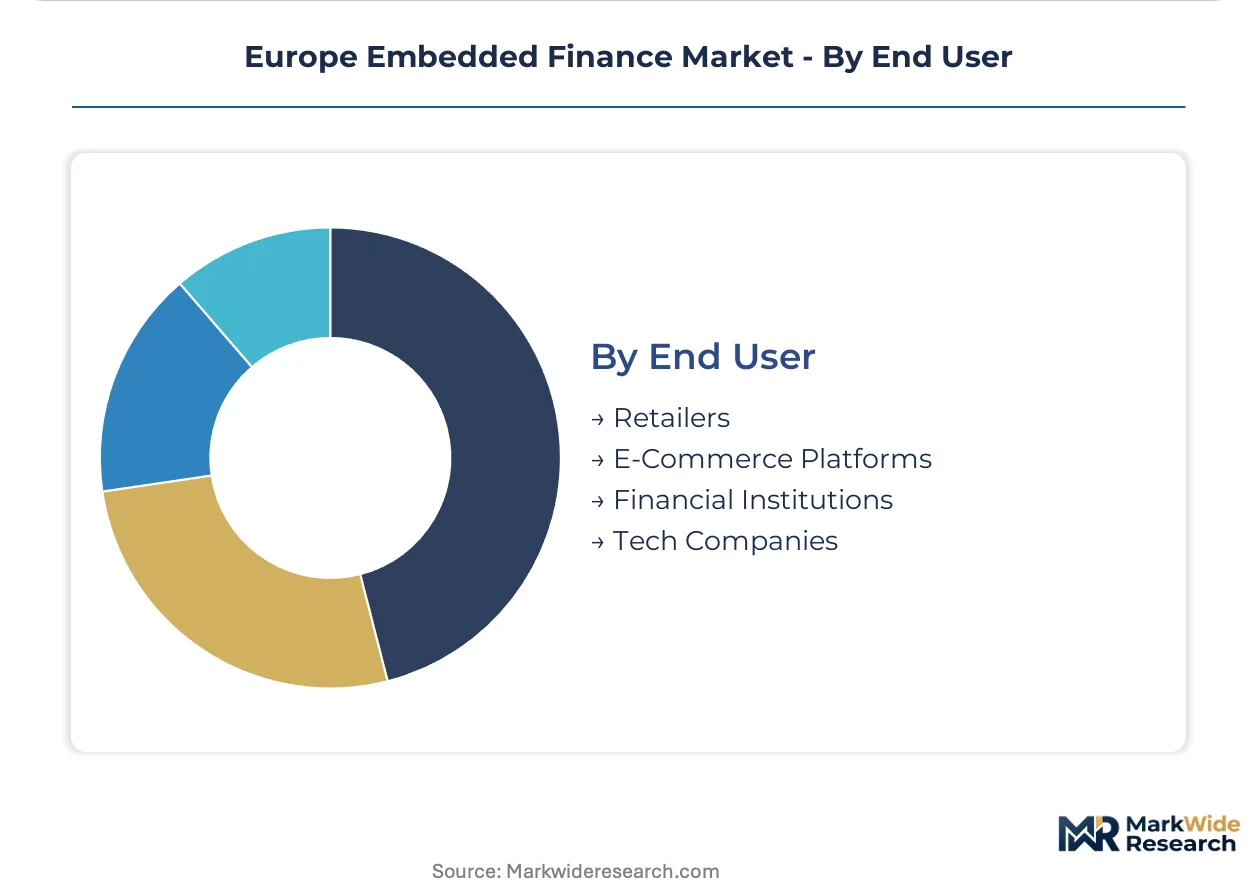
End User:
Platform business models determine whether financial services embed at the point of commerce or within operational software workflows.
- Retailers:Point-of-sale lending deployment at transaction completion without redirecting to standalone banking interfaces. German and French merchants lead adoption.
- E-Commerce Platforms:Checkout-native payment acceptance consolidated with working capital and treasury management in single interfaces.
- Financial Institutions:White-label distribution partnerships and API-based service expansion beyond traditional branch networks.
- Tech Companies:Independent software vendors displacing standalone banking relationships through cash flow forecasting tools with embedded lending decisions.
Category leader by integration volume: E-Commerce Platforms. Gaining share fastest: Tech Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United Kingdom and Nordic markets where open banking infrastructure maturity enables faster API-based financial service integration. German and French retailers anchor point-of-sale lending adoption. Regulatory divergence between EU member states fragments licensing timelines.
United Kingdom
Real-time payment rails and accounting software penetration exceeding seventy percent among SMEs drive embedded lending integration. The Financial Conduct Authority mirrors EBA technical standards in post-Brexit rulemaking, tightening third-party risk management obligations. London fintech clusters dominate B2B invoice financing platform development.
Germany
Automotive marketplaces and property management platforms deploy modular banking-as-a-service stacks within ninety-day windows. BaFin enforces EBA cloud outsourcing guidelines that increase infrastructure costs for multi-tenant architectures. Berlin and Munich anchor full banking-as-a-service license utilization.
France
Merchants accelerate point-of-sale lending deployment at transaction completion without redirecting to standalone banking interfaces. Autorité de Contrôle Prudentiel et de Résolution implements PSD3 strong customer authentication mandates. Paris fintech corridors concentrate embedded insurance pilot programs for electronics retailers.
Sweden
Account-to-account payment penetration ranks highest in Europe, enabling real-time treasury services integration into ERP platforms. The Swedish Financial Supervisory Authority enforces DORA incident reporting mandates for operational resilience. Stockholm clusters lead automated credit underwriting via real-time bank feeds.
Netherlands
Trade credit platforms demonstrate viable unit economics for SME working capital extension across supplier payment workflows. De Nederlandsche Bank supervises compliance with GDPR data handling protocols for platform-integrated financial services. Amsterdam anchors B2B buy-now-pay-later mechanics penetration.
Europe Embedded Finance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with licensed credit institutions and API-native distributors contesting margin pools. Market structure tilts toward consolidation among full-stack banking-as-a-service providers while modular microservices fragment the long tail. Two strategic archetypes dominate: incumbent banks deploying proprietary balance sheets and fintech-native platforms leveraging containerized cloud architectures. Competitive moves concentrate on M&A for regulatory licenses and strategic partnerships for API distribution reach.
Within the licensed institution tier, Solaris SE and BBVA occupy positions that exemplify divergent geographic strategies. Solaris SE anchors German-speaking markets through its full banking-as-a-service license stack. BBVA sustains a regulated foothold across Iberia and Latin American corridors through its proprietary Open Platform. Stripe sits within the payment-native expansion archetype, leveraging processing dominance to extend lending and treasury products into software platforms.
| Leading Market Players |
|---|
| PayPal |
| Marqeta |
| Solaris SE |
| Froda |
| Unit |
| BBVA |
| SDK.finance |
| Dreamix |
| Stripe |
| Others |
Supply & Pricing Matrix
API-first infrastructure standardization is compressing platform integration timelines from years to quarters while simultaneously fragmenting supplier power across modular banking-as-a-service stacks. This technological shift concentrates cost advantages with providers achieving sub-200-millisecond response reliability at scale, while smaller distributors face escalating infrastructure investments under EBA cloud outsourcing guidelines.
Pricing Analysis
Volume concentration in payment processing yields thin per-transaction margins, while lending solutions command premium pricing through real-time underwriting algorithms. Three-tier pricing structure across enterprise, mid-market, and developer tiers reflects API call volume commitments and compliance wrapper sophistication. Pricing pressure stems from incumbent banks deploying proprietary balance sheets to undercut banking-as-a-service fees. Developer-centric startups exhibit highest price sensitivity, whereas large enterprises negotiate direct licensing arrangements with limited elasticity.
Supply Chain Analysis
Reverse-logistics flows for decommissioned cloud infrastructure and obsolete API gateway hardware remain underdeveloped across European embedded finance. Core banking system components concentrate in Germany, Ireland, and the Netherlands where regulatory sandboxes and licensing authorities cluster. Raw material dependencies center on semiconductor chips for payment terminals, specialized server hardware for low-latency processing, and cryptographic security modules. Single-source vulnerability persists for financial-grade API authentication protocols. Distribution runs through direct platform integration partnerships rather than intermediary channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API engineering talent scarcity functions as the binding capacity constraint, propping pricing power for providers with proven sub-200-millisecond infrastructure and retaining pressure on margin-diluted commodity transaction processing.
For Market Incumbents: Extend modular microservice offerings into adjacent compliance and treasury functions before fintech-native platforms achieve full banking-as-a-service parity. Incumbent banks must accelerate proprietary balance sheet deployment against API-dependent distributor margin compression. Solaris SE and BBVA demonstrate viable pathways through regulatory license leverage and geographic corridor control. For New Entrants and Emerging Players: Independent software vendors serving hospitality and professional services verticals represent the most penetrable channel partner type for embedded lending integration. White-space targets concentrate in B2B invoice financing for SME supplier workflows and parametric warranty products for electronics retailers. Go-to-market execution favors sandboxed testing environments with pre-configured PSD3 compliance wrappers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-stack banking-as-a-service providers seeking regulatory license consolidation. Long-term viability favors platforms with demonstrated developer experience metrics and proven cross-border passporting execution. Monitor EBA technical standards on payment initiation services for inflection signals narrowing the regulatory gap between licensed credit institutions and API-integrated distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory License Acquisition | BaFin and ACPR approvals enable German and French market entry without passporting delays. |
| API Response Latency Optimization | Sub-200-millisecond thresholds differentiate enterprise-tier providers in competitive RFP processes. |
| DORA Compliance Tooling Development | Automated incident reporting systems capture advisory demand from non-bank financial providers. |
| Vertical Accounting Software Integration | Seventy percent Nordic SME penetration creates embedded lending distribution density. |
| Cross-Border Passporting Expansion | EU member-state notifications compress unified product rollout timelines for scalable platforms. |
Research Methodology
ECB statistical releases, EBA technical standard drafts, and national regulatory filings formed the secondary backbone for market sizing and compliance trajectory mapping. Primary interviews with banking-as-a-service platform executives, API integration specialists, regulatory affairs leads at fintech distributors, and treasury management officers at Nordic accounting software providers validated secondary findings. Bottom-up and top-down triangulation reconciled transaction volume estimates with platform revenue disclosures.
Bottom-up modeling aggregated individual platform transaction economics across service type segments, while top-down analysis calibrated aggregate market expansion against open banking infrastructure maturity indicators. Segmentation dimensions included service type, customer scale tier, deployment architecture, and end-user platform category. CAGRs derived from regression analysis against account-to-account payment penetration rates and API standardization milestones. Forecast inputs incorporated PSD3 implementation timelines and DORA compliance cost assumptions.
Caveats apply where regulatory interpretation divergences across EU member states or cloud outsourcing guideline revisions could materially shift the outlook. Practitioners should monitor EBA draft technical standards on strong customer authentication and Financial Conduct Authority post-Brexit rulemaking alignment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Supply Chain Finance Market
FinTech
Cloud AI in Fintech Market
FinTech
North America Fintech Market
FinTech
AI Finance Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Smart Advisors Market
FinTech
Decentralized Finance Technology Market
FinTech
Financial Forecasting Software Market
FinTech
Robo-Advisory Software Market
FinTech
Finance Cloud Market
FinTech
Financial App Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
Middle East AI in Fintech Market
FinTech
Smart Lending Platform Market
FinTech
Europe Fintech Cloud Market
FinTech
Latin America AI in Fintech Market