
 Autonomous Finance Market | 2026-2036
Autonomous Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Finance Market Intelligence
The EU AI Act is hardening governance requirements for algorithmic financial systems, compelling institutions to validate automated decision-making pipelines before deployment. Oracle Corporation leverages its cloud infrastructure dominance to anchor enterprise-grade autonomous finance deployments across regulated sectors. SAP SE competes through deep ERP integration that sustains workflow automation from procurement through treasury settlement. HighRadius Corporation specializes in autonomous receivables and cash application, occupying a defensible niche in order-to-cash intelligence.
Autonomous finance denotes the application of artificial intelligence, machine learning, and robotic process automation to execute financial decisions, transactions, and workflows with minimal or no human intervention, typically operating through API-connected data streams and pre-configured risk parameters. The architecture processes structured and unstructured financial data in real time, enabling continuous portfolio adjustment, fraud detection, and liquidity optimization without manual authorization loops. Algorithmic trading and AI-driven analysis represent the most mature solution categories, where execution speed and pattern recognition capabilities concentrate margin pools, while robo-advisors face margin compression as client acquisition costs escalate. Cloud-based and SaaS deployment models are expanding fastest among mid-tier institutions that lack capital for on-premises infrastructure, though hybrid architectures retain preference among banks with stringent data residency requirements.
The US Securities and Exchange Commission scrutinizes AI-generated investment recommendations under evolving fiduciary standards, while the European Banking Authority coordinates with national regulators to enforce algorithmic transparency under the EU AI Act. The Monetary Authority of Singapore and the UK's Financial Conduct Authority are converging on sandbox frameworks that permit controlled autonomous finance experimentation without full licensing burdens. Stakeholders must monitor whether fragmented supervisory approaches fragment product architectures or whether industry-led standards emerge to unify cross-border deployment protocols.
Market Dynamics
The autonomous finance market is being fundamentally restructured by algorithmic transparency mandates under the EU AI Act, which now require financial institutions to maintain auditable decision trails for every automated transaction and portfolio adjustment executed without human intervention.
Growth Catalysts
- EU AI Act Compliance Infrastructure:Financial institutions across Germany, France, and Italy are investing heavily in explainable AI frameworks to satisfy algorithmic accountability requirements, creating sustained demand for governance tooling.
- Real-time Treasury Automation:Large asset managers in the United States are deploying self-executing cash positioning systems that eliminate manual reconciliation cycles and reduce operational latency.
- Cloud-native ERP Integration:SAP and Oracle cloud architectures are enabling mid-tier banks to deploy autonomous receivables processing without capital-intensive on-premises infrastructure buildouts.
Market Restraints
- Data Residency Requirements:Stringent localization mandates in Switzerland and Singapore are forcing institutions to maintain fragmented, jurisdiction-specific infrastructure rather than unified global deployments.
- Specialized Talent Scarcity:The intersection of quantitative finance and machine learning engineering remains severely under-supplied, with fewer than 12,000 practitioners globally holding relevant dual certifications.
- Legacy System Entrenchment:Core banking platforms from the 1990s lack API-native architectures, requiring expensive middleware layers that degrade real-time performance for autonomous workflows.
Strategic Opportunities
- Sandbox Regulatory Frameworks:The Monetary Authority of Singapore and UK Financial Conduct Authority are permitting controlled autonomous finance experimentation without full licensing burdens, accelerating proof-of-concept timelines.
- Convergence of NLP and Transaction Data:Large language models processing unstructured earnings calls and regulatory filings are converging with structured market data to generate predictive liquidity signals.
- Embedded Finance Channels:Non-financial platforms—e-commerce marketplaces, supply chain networks, payroll systems—are emerging as distribution vectors for autonomous treasury and working capital products.
Industry Challenges
- Model Risk Validation Bottlenecks:Internal audit functions lack standardized frameworks for stress-testing AI-driven decision systems, creating deployment delays averaging 14-18 months.
- Cross-border Regulatory Fragmentation:Divergent supervisory approaches between the SEC, EBA, and APAC regulators are forcing product architecture duplication, inflating compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Finance Market |
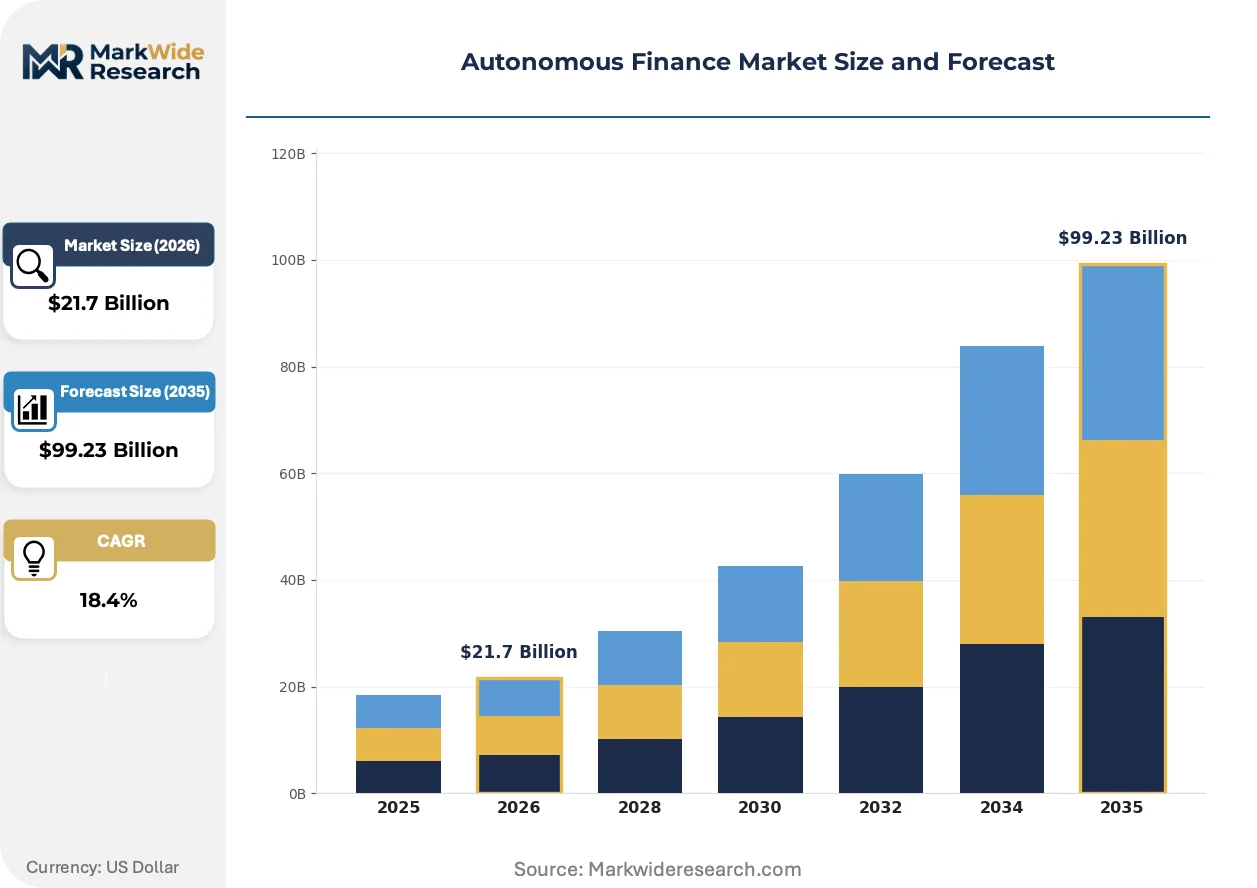
| Market Size in 2026 | $21.7 Billion |
| Market Size in 2035 | $99.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Robo-Advisors, Algorithmic Trading, Automated Portfolio Management, AI-Driven Analysis Client Type: Retail Investors, Institutional Investors, Financial Advisors, Hedge Funds Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS Service Level: Basic, Premium, Enterprise, Customized |
| Companies Covered | HighRadius Corporation, Oracle Corporation, SAP SE, Signzy Technologies Private Limited, Roots Automation, Auditoria.AI, Vic.ai, NICE Actimize, Emagia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Finance Market Strategic Shifts & Innovations
Generative AI is rewriting the interface layer between institutional investors and autonomous systems, replacing static dashboards with conversational execution interfaces that accept natural language portfolio instructions.
Reinforcement learning from human feedback is converging with traditional portfolio optimization engines to enable dynamic risk budget reallocation. Quantitative hedge funds in Connecticut and London are deploying these hybrid architectures to compress rebalancing cycles from daily to intraday frequencies. The structural consequence is a compression of alpha decay windows, forcing competitors to match execution speed or cede margin to faster actors.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for high-stakes financial decisions. Institutions must now document training data provenance, model drift monitoring protocols, and human oversight triggers before deployment. Asset managers in the Netherlands and Sweden are responding by establishing dedicated AI ethics boards with veto authority over autonomous system activations.
Institutional procurement of autonomous finance capabilities is rotating from perpetual license models toward consumption-based pricing tied to transaction volumes processed. Large pension funds in California and Ontario are leading this shift, unbundling software fees from professional services and demanding outcome-based contracts with clawback provisions for underperformance. This pattern is most pronounced in North American public sector retirement systems with fiduciary oversight requirements.
Autonomous Finance Market Segmentation
Segmentation in autonomous finance reveals divergent technology maturity and compliance burdens across client tiers. Solution architectures must reconcile real-time execution demands with explainability mandates that vary by deployment context and regulatory jurisdiction.
Solution Type:
Algorithmic trading commands premium pricing through execution velocity advantages, while robo-advisors compete on scale economics in mass-market wealth management.
- Algorithmic Trading:High-frequency execution engines process market data through co-located infrastructure, capturing microsecond arbitrage windows. Demand concentrates among quantitative hedge funds in Connecticut and London where latency differentials determine alpha generation.
- AI-Driven Analysis:Natural language processing systems parse unstructured regulatory filings and earnings transcripts to generate predictive signals. Asset managers in the Netherlands and Sweden deploy these tools to satisfy EU AI Act documentation requirements for algorithmic decision provenance.
- Automated Portfolio Management:Self-executing rebalancing systems maintain target allocations across multi-asset mandates without manual intervention triggers.
- Robo-Advisors:Automated wealth platforms face margin compression as customer acquisition costs escalate in saturated retail markets.
Mature deployment sits with algorithmic trading. Newer deployment is concentrated in AI-driven analysis.
Client Type:
Institutional investors drive infrastructure investment through fiduciary liability concerns, while retail channels prioritize accessibility over customization depth.
- Institutional Investors:Pension funds and sovereign wealth vehicles mandate auditable decision trails and human oversight protocols. Large asset managers in the United States deploy self-executing treasury systems that eliminate manual reconciliation cycles entirely.
- Hedge Funds:Quantitative strategies demand sub-millisecond execution with minimal latency variance. Funds in London and Singapore operate hybrid cloud architectures to satisfy data residency requirements while maintaining computational proximity to major exchanges.
- Financial Advisors:Hybrid advisory models leverage autonomous tools for portfolio construction while retaining human client relationships.
- Retail Investors:Mass-market platforms emphasize mobile accessibility and simplified risk profiling over sophisticated customization.
Enterprise-grade deployment dominates institutional channels. Retail-facing platforms are gaining share fastest through embedded finance distribution partnerships.
Deployment Model:
Cloud-native architectures expand among mid-tier institutions lacking capital for on-premises buildouts, though hybrid models retain preference where data sovereignty rules apply.
- Hybrid:Split architectures process sensitive data on-premises while leveraging cloud compute for non-critical analytics. Banks in Switzerland and Singapore maintain this configuration to satisfy localization mandates without sacrificing scalability.
- Cloud-Based:Fully managed environments enable rapid deployment of autonomous receivables and cash application systems. Mid-tier institutions across Germany and France adopt these models to bypass legacy system constraints.
- SaaS:Subscription pricing aligns vendor incentives with client transaction volumes, accelerating adoption among cost-constrained asset managers.
- On-Premises:Captive infrastructure persists among systemically important banks with stringent operational resilience requirements.
Established deployment sits with on-premises configurations. Cloud-based models are climbing the fastest among second-tier institutions.
Service Level:
Premium tiers capture value through dedicated support and customized risk parameters, while basic offerings compete on standardized automation at minimal cost.
- Enterprise:Bespoke implementations include dedicated model validation resources and custom API integrations. Large pension funds in California and Ontario negotiate outcome-based contracts with clawback provisions for underperformance.
- Customized:Tailored configurations address niche regulatory requirements or specialized asset class coverage. Asset managers in the United Kingdom deploy these variants to satisfy FCA sandbox reporting obligations.
- Premium:Enhanced service tiers offer priority support and expanded risk parameter flexibility for sophisticated users.
- Basic:Standardized automation packages target cost-sensitive users with limited customization requirements.
Revenue concentration sits with enterprise engagements. Premium tier expansion is steepest among mid-market asset managers upgrading from basic configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous finance capability concentrates in jurisdictions with deep capital markets and permissive regulatory experimentation, while consumption spreads through financial centers seeking operational efficiency. Production of core AI infrastructure remains anchored in technology hubs, with deployment scaling fastest where sandbox frameworks reduce compliance friction.
United States
Large asset managers in Connecticut and California drive demand for self-executing treasury systems that eliminate manual reconciliation cycles. The SEC scrutinizes AI-generated investment recommendations under evolving fiduciary standards, compelling institutions to document algorithmic decision trails. Quantitative hedge funds in the Stamford-Greenwich corridor deploy sub-millisecond execution engines to capture microsecond arbitrage windows.
Germany
Mid-tier banks across Frankfurt and Munich adopt cloud-native autonomous receivables processing to bypass legacy system constraints. The EU AI Act mandates explainable AI frameworks and auditable decision trails for high-stakes financial automation. Industrial conglomerates in Baden-Württemberg integrate autonomous cash positioning with ERP workflows from procurement through treasury settlement.
United Kingdom
Asset managers in London deploy hybrid cloud architectures to satisfy data residency requirements while maintaining proximity to major exchanges. The Financial Conduct Authority operates sandbox frameworks permitting controlled autonomous finance experimentation without full licensing burdens. Fintech clusters in the City and Canary Wharf pioneer conversational execution interfaces that accept natural language portfolio instructions.
Singapore
Hedge funds and family offices demand autonomous systems that process structured and unstructured data across Asian market hours. The Monetary Authority of Singapore coordinates sandbox frameworks with explicit algorithmic transparency requirements for cross-border deployment. Financial institutions in the Marina Bay district maintain fragmented infrastructure to satisfy stringent localization mandates without sacrificing scalability.
Netherlands
Pension funds and sovereign wealth vehicles mandate auditable decision trails with human oversight protocols for automated portfolio adjustments. The EU AI Act's risk-based classification system requires algorithmic impact assessments documenting training data provenance and model drift monitoring. Asset managers in Amsterdam establish dedicated AI ethics boards with veto authority over autonomous system activations.
Autonomous Finance Market Key Industry Players
The competitive structure tilts toward cloud-native platform providers with established enterprise relationships. Oracle Corporation and SAP SE anchor the infrastructure layer through deep ERP integration and cloud dominance, while specialized vendors occupy defensible niches in receivables automation and cash application. Three archetypes define positioning: horizontal cloud platforms, ERP-integrated suites, and point-solution specialists. Consolidation pressure intensifies as mid-tier institutions demand unified workflows rather than fragmented tooling, driving strategic partnerships between core banking vendors and AI layer providers.
Within the horizontal platform tier, Oracle Corporation exemplifies infrastructure-led positioning through cloud dominance across regulated sectors. SAP SE represents the ERP-integrated archetype, sustaining workflow automation from procurement through treasury settlement. HighRadius Corporation anchors the specialist category, occupying a defensible niche in autonomous receivables and order-to-cash intelligence. These three patterns illustrate how vendor selection criteria diverge between institutions prioritizing integration depth versus those seeking best-of-breed functional coverage.
| Leading Market Players |
|---|
| HighRadius Corporation |
| Oracle Corporation |
| SAP SE |
| Signzy Technologies Private Limited |
| Roots Automation |
| Auditoria.AI |
| Vic.ai |
| NICE Actimize |
| Emagia |
| Others |
Cost & Logistics Intelligence
Cloud-native ERP integration is compressing deployment timelines while simultaneously redistributing supplier power toward platform orchestrators with established enterprise relationships. This shift concentrates value capture among vendors controlling API infrastructure and compliance tooling, forcing mid-tier providers into margin-eroding specialization or exit.
Pricing Analysis
Margin tightening in mid-tier SaaS offerings reflects procurement standardization among large asset managers demanding outcome-based contracts with clawback provisions. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth and model validation rigor. Pricing pressure stems from cloud hyperscalers bundling autonomous finance modules into broader enterprise agreements. Retail-facing robo-advisors exhibit highest price sensitivity; institutional investors with fiduciary mandates demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for explainable AI frameworks compel financial institutions to qualify multiple governance tooling providers alongside core platform vendors. Supply concentrates in the United States for cloud infrastructure, Germany for ERP-integrated compliance systems, and Singapore for Asia-Pacific data residency solutions. Critical dependencies include GPU compute clusters, proprietary financial datasets, and regulatory sandbox access. Single-source vulnerability sits with specialized machine learning engineering talent. Distribution runs through direct enterprise sales with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous finance is consolidating around platform providers with regulatory pre-certification and enterprise ERP anchoring, as EU AI Act compliance costs force sub-scale vendors toward acquisition or exit.
For Market Incumbents: Anticipate margin compression in standardized automation modules as cloud hyperscalers bundle competing capabilities. Defensive moves require deepening vertical integration into proprietary financial datasets and securing EU AI Act pre-certification for high-risk algorithmic systems. Capacity expansion in Singapore and Switzerland addresses data residency fragmentation. For New Entrants and Emerging Players: Embedded finance distribution partnerships with non-financial platforms—e-commerce marketplaces, supply chain networks, payroll systems—offer the most penetrable route. White-space targets include autonomous working capital products for mid-market manufacturers and NLP-driven regulatory filing analysis for EU asset managers. Go-to-market positioning should emphasize sandbox pre-qualification with the Monetary Authority of Singapore or UK Financial Conduct Authority. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by cloud hyperscalers seeking compliance-ready AI tooling. Long-term viability favors vendors with established AI ethics boards, auditable decision trail architectures, and recurring revenue above sixty percent. The signal to watch is EU AI Act enforcement velocity—accelerated penalties would trigger distressed consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Establishes defensible positioning against regulatory enforcement actions in Germany and France. |
| Proprietary Dataset Acquisition | Captures differentiated training inputs for NLP models parsing unstructured regulatory filings. |
| Sandbox Framework Entry | Accelerates proof-of-concept timelines with the Monetary Authority of Singapore's controlled experimentation protocols. |
| Hybrid Cloud Architecture Deployment | Satisfies Swiss and Singapore data residency mandates without sacrificing computational scalability. |
| Outcome-Based Contract Structuring | Aligns vendor incentives with California and Ontario pension fund fiduciary oversight requirements. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with treasury technology officers, compliance leads at asset managers, ERP integration specialists, and regulatory sandbox administrators. Primary fieldwork combined quantitative demand validation with qualitative assessment of EU AI Act implementation timelines. Secondary sources included SEC enforcement actions, EBA algorithmic transparency guidelines, MAS sandbox admission records, and cloud provider capex disclosures. Bottom-up deployment estimates triangulated against top-down market sizing.
Data-stream reconciliation across solution type, client tier, deployment model, and geographic regulatory cluster generated volume and value outputs. Segmentation dimensions modeled encompass algorithmic maturity, fiduciary liability exposure, and data sovereignty requirements. CAGRs derived from fitted growth curves incorporating technology adoption S-cycles and regulatory phase-in schedules. Industry-specific forecast inputs included EU AI Act enforcement velocity projections and cloud infrastructure expansion timelines.
The model holds under stable regulatory phase-in schedules and sustained cloud migration; deviation in EU AI Act penalty severity or hyperscaler bundling aggression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Singapore Fintech Market
FinTech
Financial Forecasting Software Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Spend Management Platform Market
FinTech
Russia AI in Fintech Market
FinTech
Europe Financial Analytics Market
FinTech
Japan AI in Fintech Market
FinTech
Fintech-As-A-Service Market
FinTech
Supply Chain Finance Market
FinTech
Europe Fintech Cloud Market
FinTech
United States Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
India AI in Fintech Market
FinTech
Robo-Advisory Software Market
FinTech
Middle East AI in Fintech Market