
 Europe Financial Analytics Market | 2026-2036
Europe Financial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Financial Analytics Market Analytics
Frankfurt's fintech corridor is reconfiguring how financial institutions source analytics infrastructure across the eurozone. SAP SE leverages its embedded finance modules to anchor enterprise resource planning workflows inside major German lenders. SAS Institute competes through specialized risk quantification engines that dominate stress-testing installations. Microsoft Corporation extends its cloud analytics stack through Azure-native integrations that appeal to mid-tier banks seeking scalable deployment paths.
Europe financial analytics encompasses software platforms and services that ingest structured and unstructured financial data, apply statistical algorithms and machine-learning models, and generate predictive outputs for capital allocation, risk measurement, and regulatory reporting. These systems process real-time transaction streams, portfolio positions, and macroeconomic indicators to support decision-making under uncertainty. Reporting and forecasting solutions within the solution-type dimension carry mature margin pools, while data mining applications attract fastest-growing demand as institutions pursue alternative signal extraction. Cloud deployment models are displacing on-premises installations among investment firms, though hybrid architectures persist in banking where data-sovereignty requirements fragment infrastructure decisions.
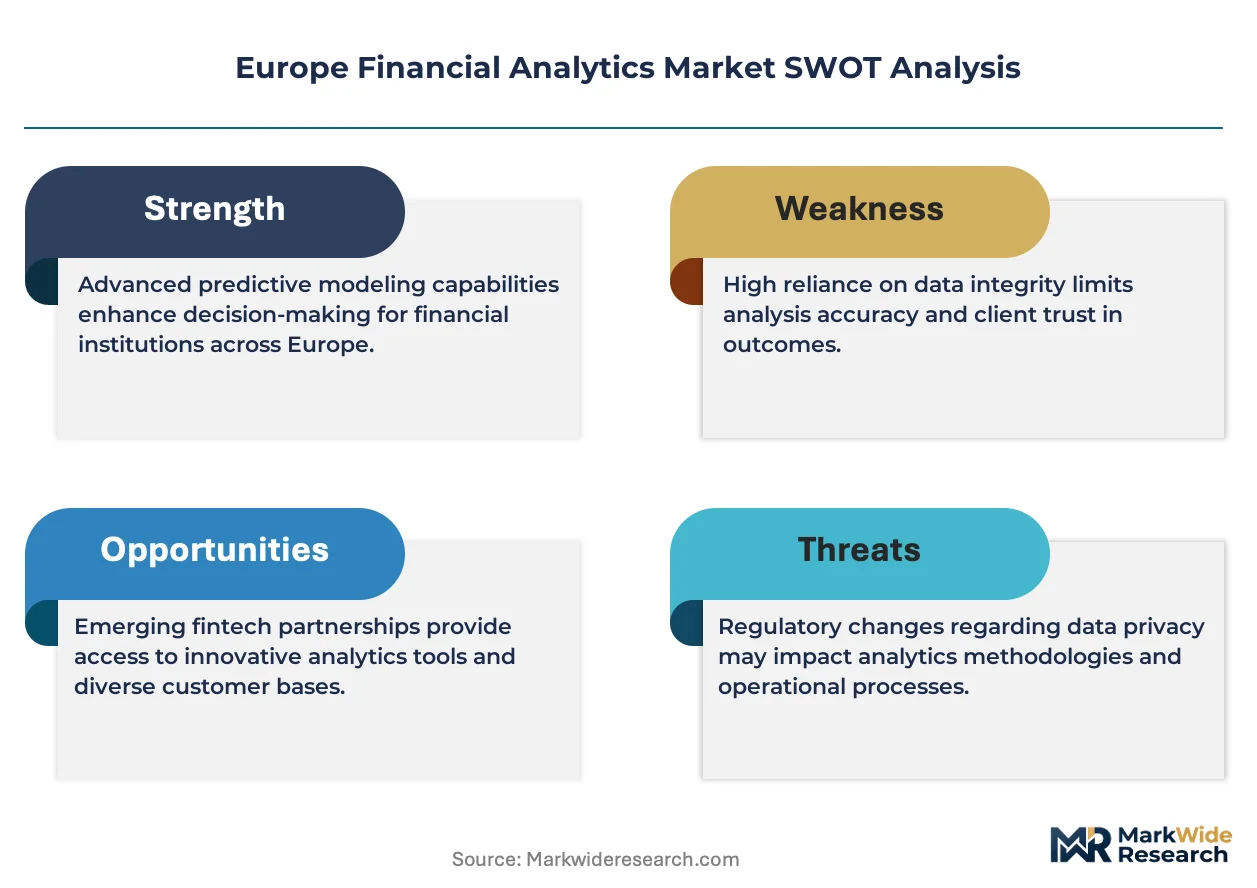
ECB stress-testing protocols, EBA reporting standards, and GDPR data-governance rules collectively shape product specifications and procurement timelines for analytics vendors serving European financial institutions. EBA's standardized templates force platform adaptations that favor vendors with dedicated regulatory engineering teams. GDPR's cross-border data-transfer constraints complicate cloud-native architectures and push clients toward regionally hosted instances. Stakeholders must weigh compliance automation depth against model explainability requirements as supervisors intensify scrutiny of algorithmic decision-making in credit and trading functions.
Market Dynamics
ECB stress-testing mandates are compressing procurement cycles for risk analytics infrastructure across eurozone banking groups, forcing vendors to reconfigure product roadmaps around regulatory compliance automation rather than discretionary feature expansion.
Growth Catalysts
- Basel III Finalization:Eurozone lenders face tightened capital reporting requirements that expand demand for regulatory compliance solutions. This regulatory pressure creates immediate procurement pull for integrated risk-quantification platforms.
- Cloud Migration:Investment firms in Germany and France are accelerating deployment of cloud-native analytics architectures. Scalability requirements and data-sovereignty constraints drive hybrid infrastructure decisions.
- Alternative Signal Extraction:Data mining applications attract fastest-growing demand as institutions pursue unstructured data processing capabilities. Machine-learning model deployment for portfolio optimization expands addressable use cases.
Market Restraints
- GDPR Cross-Border Constraints:Data-governance rules complicate cloud-native architectures and push clients toward regionally hosted instances. Fragmented infrastructure decisions increase total cost of ownership for multinational deployments.
- Specialized Talent Scarcity:Quantitative risk modeling expertise concentrates in Frankfurt, London, and Paris financial corridors. Recruitment friction delays implementation timelines for mid-tier institutions.
- Legacy System Interoperability:Core banking infrastructure at established eurozone lenders resists seamless API integration. Custom middleware development inflates deployment costs.
Strategic Opportunities
- Spain and Italy Underpenetration:Mid-tier banks in Madrid and Milan lag northern European peers in predictive analytics adoption. Localization requirements create entry barriers that favor early movers with dedicated regulatory engineering teams.
- Real-Time Transaction Processing:Streaming analytics for intraday risk monitoring represents emerging white space. Infrastructure investments by payment processors create adjacent demand for low-latency quantification tools.
- EU AI Act Alignment:Algorithmic explainability requirements intensify scrutiny of credit and trading decision systems. Vendors with embedded model-interpretability features capture premium positioning.
Industry Challenges
- Model Validation Bottlenecks:Supervisory review timelines for internal ratings-based approaches extend certification cycles. ECB scrutiny of algorithmic decision-making compresses vendor delivery windows.
- Data Sovereignty Fragmentation:National implementations of GDPR create inconsistent hosting requirements across eurozone jurisdictions. Multi-tenant cloud architectures require jurisdiction-specific instance configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Financial Analytics Market |
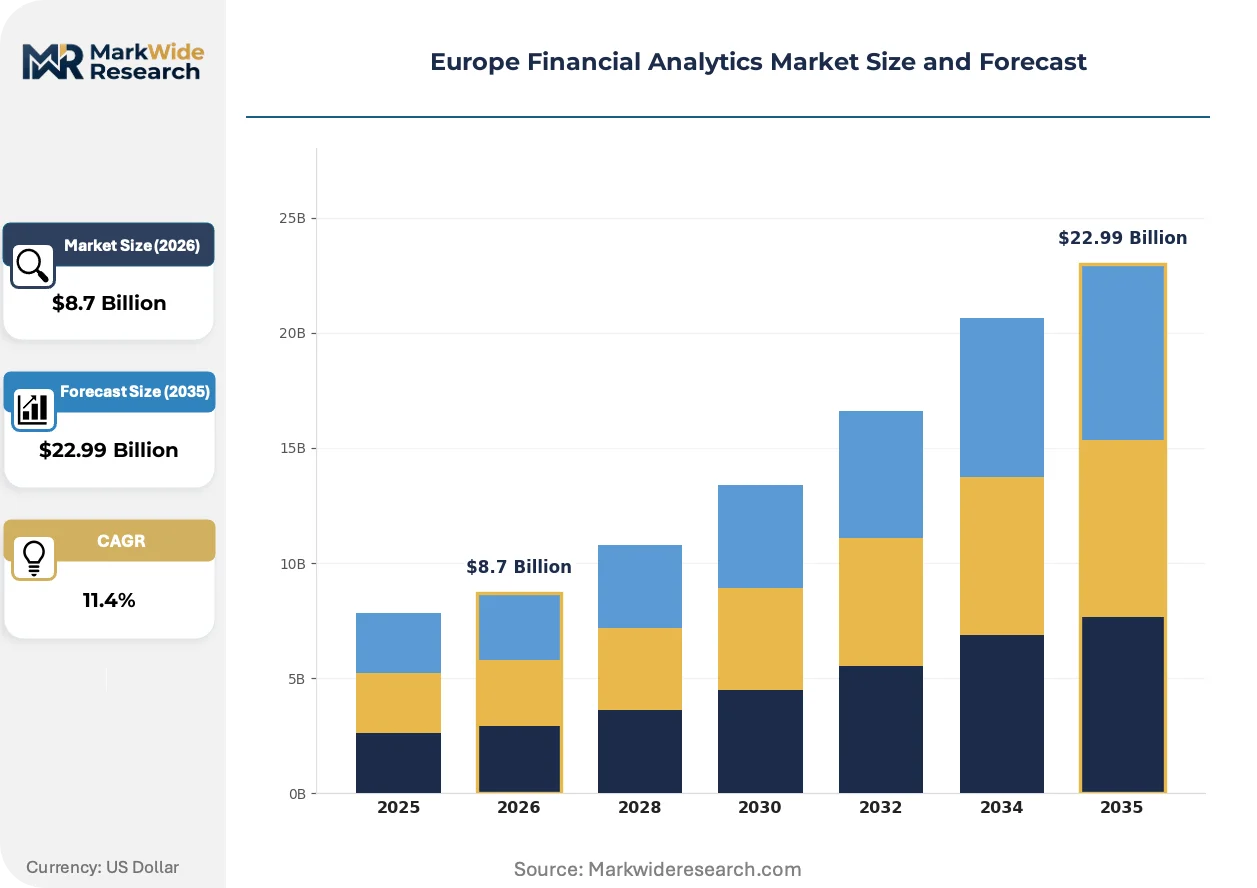
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Reporting, Budgeting, Forecasting, Data Mining User Type: Corporate Finance, Investment Analysts, Actuaries, Auditors Deployment Model: On-Premises, Cloud, Hybrid, Dedicated End User Industry: Banking, Insurance, Investment Firms, Retail |
| Companies Covered | SAP SE, IBM Corporation, Oracle Corporation, Microsoft Corporation, Tableau Software, SAS Institute, Alteryx, TIBCO Software, Finastra, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Financial Analytics Market Evolving Landscape
Generative AI capabilities are restructuring how European financial institutions approach predictive modeling and regulatory documentation, compressing traditional development cycles while introducing new governance complexities.
Natural language processing for regulatory text analysis is collapsing the manual effort required for EBA template compliance. Tier-two banks in the Netherlands and Belgium adopt these tools fastest, seeking to match stress-testing capabilities of larger competitors without proportional headcount expansion. The technology is collapsing the cost barrier that previously segmented vendor tiers by institutional size.
CSRD disclosure requirements expand non-financial reporting obligations for listed banks and insurers. Scope 3 emissions quantification and supply-chain due diligence provisions force analytics platforms to ingest sustainability data alongside traditional financial metrics. Asset managers in France face the steepest adaptation curve as domestic SRI labeling requirements predate EU harmonization.
Subscription-based platform access displaces perpetual license arrangements among asset management boutiques. Smaller firms in Zurich and Luxembourg prioritize operational expenditure predictability over capital deployment flexibility. This preference shift favors vendors with modular pricing architectures and accelerates consolidation around cloud-native stack providers.
Europe Financial Analytics Market Segmentation
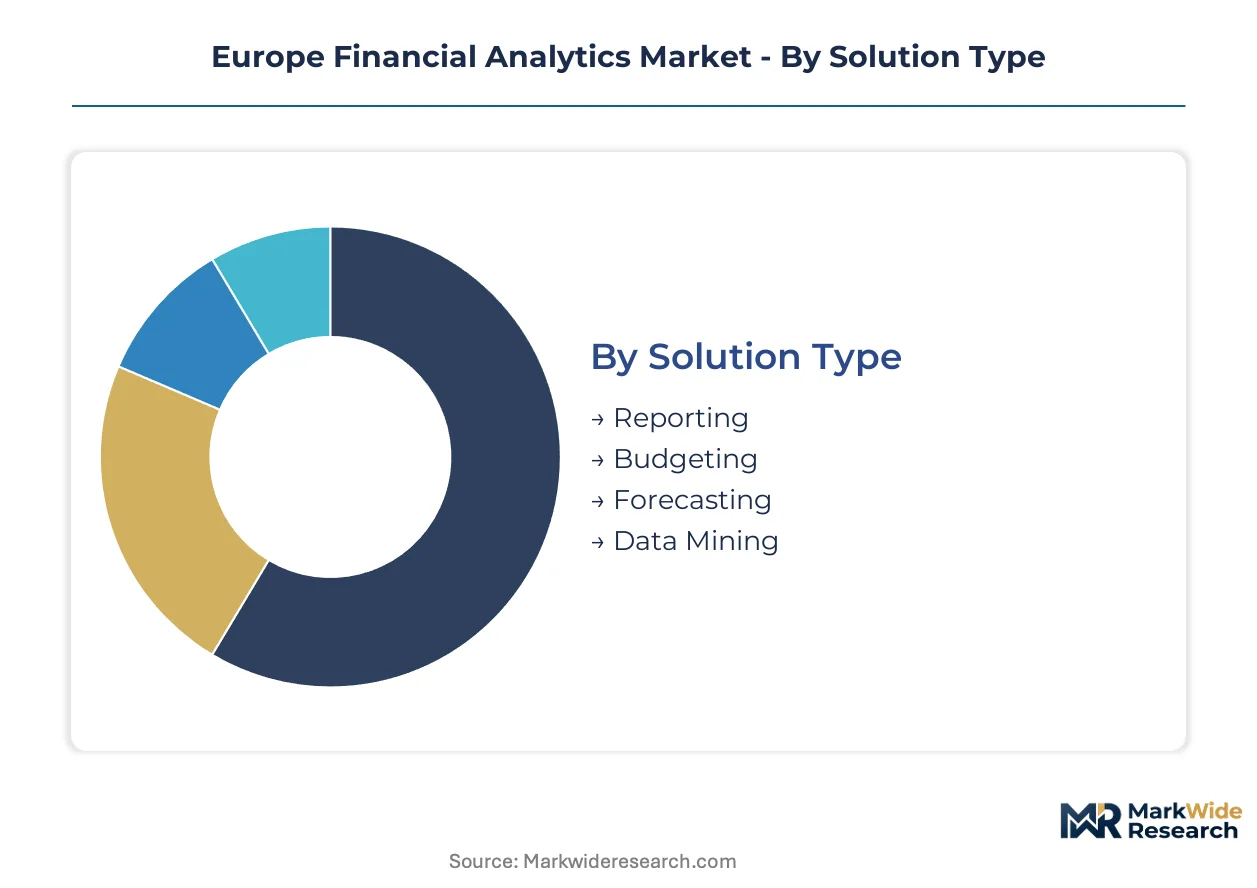
European financial institutions segment analytics procurement by regulatory workload intensity, deployment sovereignty constraints, and user sophistication levels. Solution architecture choices directly determine compliance automation depth and model explainability thresholds under ECB supervision.
Solution Type:
Reporting platforms turn over slowest with decade-long refresh cycles, while data mining tools refresh annually as algorithmic capabilities advance.
- Reporting:Standardized regulatory output generation for EBA templates and ECB stress-testing submissions. German universal banks concentrate procurement here, driven by Basel III finalization mandates that harden documentation requirements.
- Data Mining:Unstructured signal extraction from alternative data streams including satellite imagery, supply-chain telemetry, and consumer sentiment feeds. French asset managers and Dutch pension funds drive adoption, seeking alpha generation beyond traditional factor models.
- Budgeting:Capital allocation workflow automation with scenario-branching capabilities. Mid-tier Spanish lenders prioritize this segment for internal capital adequacy assessment.
- Forecasting:Predictive macroeconomic and portfolio-level simulation engines. Italian insurers favor these tools for liability-driven investment strategies.
Reporting dominates installed base. Data mining is where expansion concentrates.
User Type:
Actuarial functions command premium pricing tiers, while auditor-facing tools compete on volume and standardization.
- Corporate Finance:Treasury and FP&A teams managing liquidity, working capital, and strategic planning workflows. Demand clusters at German automotive financiers and French luxury conglomerates with complex multi-currency exposures.
- Investment Analysts:Portfolio construction and security selection professionals across buy-side institutions. Zurich-based asset managers and Luxembourg fund administrators anchor this segment's growth trajectory.
- Actuaries:Insurance liability modelers quantifying longevity, mortality, and catastrophe risks. UK-headquartered life insurers with substantial European operations drive specialized platform requirements.
- Auditors:External assurance providers and internal validation functions. EBA regulatory examination cycles compress procurement timelines for this user category.
Corporate finance commands the largest seat count. Investment analysts represent the steepest expansion trajectory.
Deployment Model:
Cloud configurations scale fastest among new entrants, while hybrid architectures capture incumbent banking groups with fragmented data-estate legacies.
- Cloud:Multi-tenant SaaS delivery with API-native integration patterns. German B2B fintechs and French investment boutiques favor this model for operational expenditure predictability and rapid time-to-value.
- Hybrid:Sensitive data remains on-premises while compute-intensive workloads shift to cloud. Dutch and Belgian banks with GDPR complexity prefer this architecture to satisfy data-sovereignty requirements without sacrificing scalability.
- On-Premises:Fully captive infrastructure with dedicated hardware stacks. Austrian and Swiss private banks maintain this deployment for client confidentiality protocols that predate cloud adoption.
- Dedicated:Single-tenant cloud instances with physical isolation guarantees. Italian and Portuguese institutions select this model to satisfy national regulator hosting mandates without full on-premises burden.
On-premises retains the deepest installed base. Hybrid deployments are gaining share fastest.
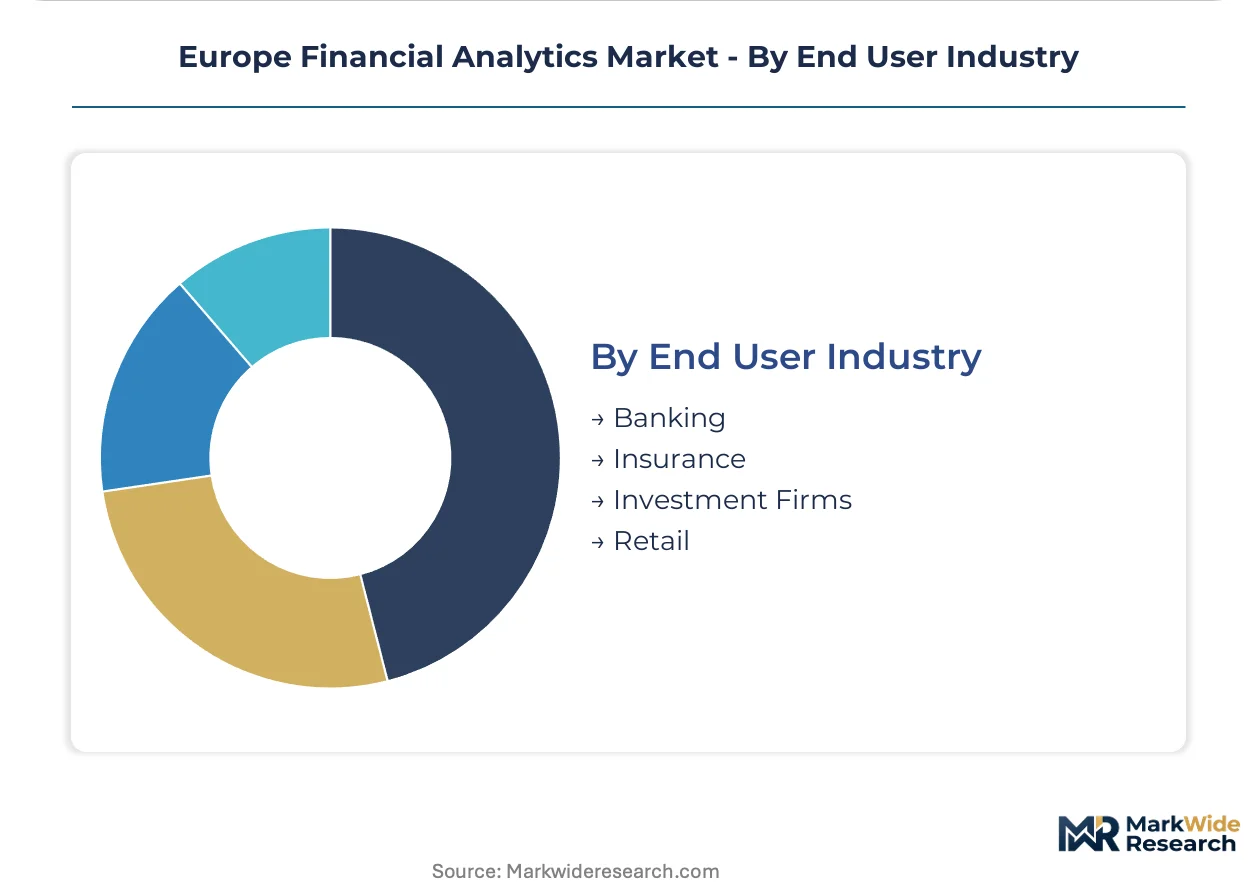
End User Industry:
Banking consumes analytics capacity by absolute spend, while investment firms demonstrate the shortest replacement cycles.
- Banking:Universal banks, savings institutions, and cooperative lenders executing ECB stress-testing and IRB model validation. German and French banking groups anchor demand with the most complex quantitative infrastructure requirements.
- Investment Firms:Asset managers, hedge funds, and private equity sponsors pursuing portfolio optimization and risk-adjusted return attribution. Luxembourg and Dublin fund domiciles concentrate procurement for UCITS and AIFM compliance.
- Insurance:Life, non-life, and reinsurance carriers quantifying reserve adequacy and solvency capital. Italian and UK insurers with substantial European operations drive specialized mortality and catastrophe modeling demand.
- Retail:Consumer-facing merchants and e-commerce platforms deploying credit risk scoring and fraud detection. Nordic retail banks with integrated payment ecosystems represent the primary addressable market.
Banking dominates absolute spend. Investment firms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECB stress-testing mandates anchor procurement intensity across the eurozone, with German banking groups deploying the most sophisticated risk-quantification infrastructure. National regulatory implementations fragment cloud adoption patterns.
Germany
Universal banks in Frankfurt and Munich drive demand for integrated regulatory reporting platforms under ECB supervision. BaFin's granular implementation of Basel III finalization hardens capital documentation requirements. The Rhine-Main fintech corridor concentrates vendor engineering resources and client procurement decisions.
France
Asset managers in Paris prioritize data mining capabilities for alternative signal extraction from unstructured sources. Autorité de Contrôle Prudentiel et de Résolution enforces SRI labeling requirements that predate EU harmonization. La Défense financial district hosts specialized quant teams developing proprietary ESG integration models.
United Kingdom
Life insurers with substantial European operations sustain demand for actuarial liability modeling despite post-Brexit regulatory divergence. Prudential Regulation Authority maintains parallel stress-testing protocols that complicate cross-border platform standardization. London's risk analytics talent pool feeds continental implementation teams through contract arrangements.
Netherlands
Pension funds in Amsterdam and Rotterdam adopt data mining tools fastest among mid-tier institutions seeking factor-model alpha. Dutch Data Protection Authority enforces GDPR cross-border constraints that push clients toward hybrid cloud architectures. The Zuidas financial district concentrates fintech partnerships focused on real-time transaction monitoring.
Italy
Mid-tier banks in Milan lag northern peers in predictive analytics adoption, creating whitespace for localized platform deployment. Bank of Italy's national hosting mandates favor dedicated single-tenant cloud instances over multi-tenant alternatives. Lombardy's insurance sector drives specialized forecasting demand for liability-driven investment strategies.
Europe Financial Analytics Market Competitive Landscape
Capability concentration sits with specialized risk-quantification vendors; scale advantage sits with cloud-native platform providers with embedded finance distribution. The market structures around three tiers: enterprise resource planning incumbents with banking module integration, dedicated analytics specialists with regulatory engineering depth, and hyperscale cloud providers with API-native architectures. Dominant competitive moves include strategic partnerships between software vendors and system integrators, plus portfolio diversification into sustainability reporting modules.
Within the enterprise software tier, SAP SE represents the embedded finance archetype through its banking module dominance. SAS Institute exemplifies the specialized risk-quantification approach with stress-testing installations across ECB-supervised institutions. Microsoft Corporation occupies the hyperscale cloud position through Azure-native analytics stacks appealing to mid-tier banks.
| Leading Market Players |
|---|
| SAP SE |
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| Tableau Software |
| SAS Institute |
| Alteryx |
| TIBCO Software |
| Finastra |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud-native analytics infrastructure across Frankfurt and London is compressing vendor margins while accelerating subscription-based pricing migration among mid-tier European banks. This utilization imbalance forces specialized risk-quantification vendors toward hybrid deployment bundles and pushes hyperscale providers into longer contract lock-ins to defend revenue per seat.
Pricing Analysis
Price spreads between Frankfurt and Milan reach 35-40% for equivalent regulatory reporting modules, reflecting localization cost premiums and national hosting mandates. The dominant structure is three-tier subscription pricing across premium, standard, and economy levels, with differentiation anchored in model explainability depth and EBA template automation grade. Pricing pressure stems from open-source machine-learning libraries commoditizing baseline predictive capabilities. Mid-tier Spanish and Italian banks exhibit highest price sensitivity, while German universal banks prioritize compliance automation depth over per-seat cost.
Supply Chain Analysis
Tariff exposure between US hyperscale cloud providers and EU data-sovereignty requirements dominates supply chain risk planning for European financial institutions. Core infrastructure concentrates in Ireland, the Netherlands, and Germany for primary cloud regions, with compute hardware sourcing from Taiwan, South Korea, and the United States. GPU and specialized AI accelerator availability rests on single-source vulnerability from NVIDIA's foundry arrangements. Distribution runs through system integrator partnerships anchored in the Rhine-Main corridor and Paris-Saclay cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe financial analytics represents a service-attach opportunity where implementation consulting and ongoing model validation subscriptions expand faster than base platform licensing. Recurring revenue from regulatory update engineering now exceeds 40% of total contract value at leading vendors.
For Market Incumbents: Harden embedded finance integration through deeper SAP banking module penetration and accelerate regulatory engineering headcount in Frankfurt. Cloud-native challengers with API-first architectures threaten incumbent pricing power. Vertical integration into specialized model-interpretability tooling anchors premium tier positioning. For New Entrants and Emerging Players: Establish a beachhead in mid-tier Italian and Spanish banking where predictive analytics penetration lags northern peers by 3-4 years. Localization partnerships with Milan and Madrid-based system integrators provide fastest regulatory credibility. Target real-time transaction monitoring as the entry wedge, where incumbent platforms exhibit latency gaps. For Investors and Strategic Acquirers: Capital is best deployed toward specialized risk-quantification vendors with ECB stress-testing certification depth and established BaFin relationships. Long-term viability hinges on regulatory engineering talent density rather than pure algorithmic sophistication. Watch ECB algorithmic decision-making scrutiny intensity as the inflection signal for explainability-tooling acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Engineering Partnership | Deepens EBA template automation capabilities and accelerates ECB certification timelines. |
| Hybrid Cloud Architecture Launch | Addresses GDPR cross-border constraints while preserving scalability for Dutch and Belgian clients. |
| Specialist Risk-Quantification Acquisition | Captures stress-testing expertise concentrated in SAS Institute and Frankfurt quant corridors. |
| Real-Time Streaming Analytics Investment | Exploits whitespace in intraday risk monitoring for payment processors and clearing infrastructure. |
| Sustainability Reporting Module Expansion | Aligns with CSRD disclosure requirements forcing Scope 3 quantification for French asset managers. |
Research Methodology
Initial hypotheses were tested against primary input from chief risk officers, regulatory affairs directors, EBA examination leads, and cloud procurement officers at major European banking groups, then refined through secondary validation against ECB stress-testing documentation, EBA standardized template releases, BaFin supervisory guidance, and vendor SEC filings. Bottom-up segment sizing triangulated against top-down macroeconomic scenario modeling.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by solution type, deployment model, user sophistication tier, and national regulatory cluster. CAGRs derived from regression analysis of historical procurement cycles against ECB mandate intensity. Forecast inputs incorporated Basel III finalization implementation timelines and cloud infrastructure capex disclosures from hyperscale providers.
Sensitivities concentrate around ECB algorithmic scrutiny escalation, GDPR enforcement divergence across national data protection authorities, and open-source model commoditization pace. Forecasts reflect documented assumptions on regulatory workload intensity and vendor consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Fintech Credit Management Blockchain Market
FinTech
Japan AI in Fintech Market
FinTech
Singapore Fintech Market
FinTech
Finance Cloud Market
FinTech
Fintech Crisis Management Market
FinTech
Wealthtech Solutions Market
FinTech
Smart Finance Connectivity Market
FinTech
Smart Lending Platform Market
FinTech
Germany AI in Fintech Market
FinTech
China Fintech Market
FinTech
China AI in Fintech Market
FinTech
MENA Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Robo-Advisory Services Market