
 Saudi Arabia Fintech Market | 2026-2036
Saudi Arabia Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Fintech Market Analytics
SME banking is reorganizing competitive priorities across the Saudi fintech landscape, pulling capital away from legacy consumer remittance plays. STC Pay leverages its telecom parentage to dominate wallet-based transactions across the kingdom. Tamara specializes in buy-now-pay-later structures for retail merchants, anchoring its position in merchant-acquired credit. Geidea competes aggressively on point-of-sale hardware penetration, extending its terminal network into secondary cities.
Fintech denotes technology-enabled financial services delivered through software platforms, APIs, and mobile interfaces that automate payments, lending, wealth management, and insurance distribution. These systems rely on real-time data pipelines, encryption protocols, and cloud-native architecture to process transactions and assess credit risk outside traditional branch infrastructure. Payment Solutions leads service-type revenue generation, reflecting heavy merchant and consumer wallet activity, while Lending Services captures expanding margin pools as alternative credit scoring displaces conventional collateral requirements. SME client-type adoption outpaces enterprise segments, driven by working-capital gaps that digital lenders address faster than incumbent banks.
The Saudi Central Bank operates the regulatory sandbox that governs fintech licensing, capital requirements, and consumer protection standards, while SAMR enforces data localization and platform competition rules. These frameworks shape product architecture by mandating domestic server placement, Shariah compliance pathways, and open-banking API standards that determine market access eligibility. Stakeholders must monitor how sandbox graduation criteria and open-banking phase rollouts reshape partnership structures between neobanks and established lenders.
Market Dynamics
Saudi Arabia's fintech sector is undergoing structural reorganization as SAMA's regulatory sandbox accelerates license approvals, compressing the traditional banking partnership timeline from years to months and forcing incumbents to acquire or ally with licensed neobanks.
Growth Catalysts
- SAMA Sandbox Framework:The central bank's graduated licensing tiers enable fintechs to test products with limited customer bases before full commercial deployment, reducing regulatory uncertainty for payment and lending startups.
- Merchant POS Modernization:Retail and hospitality operators across Riyadh and Jeddah are replacing legacy terminals with cloud-connected Android-based devices, creating hardware-software integration demand for integrated payment acceptance.
- API Standardization Mandate:Open banking protocols now require Saudi banks to expose customer-permissioned data interfaces, enabling account aggregation services and real-time credit scoring for thin-file SME borrowers.
Market Restraints
- Data Localization Infrastructure Costs:SAMA mandates domestic server placement for all licensed fintechs, requiring capital-intensive data center partnerships or owned facilities that strain early-stage balance sheets.
- Shariah Compliance Complexity:Each product structure requires separate fatwa certification from SAMA's Shariah Advisory Committee, extending product development cycles and creating interpretation inconsistency across supervised entities.
- Talent Concentration in Riyadh:Software engineering and quantitative risk talent clusters in the capital's financial district, inflating compensation costs for Jeddah-based and Eastern Province fintech operations.
Strategic Opportunities
- Eastern Province Industrial SME Banking:Manufacturing and logistics clusters around Dammam and Jubail remain underserved by digital working capital solutions, presenting white space for specialized lenders with sector-specific underwriting models.
- Embedded Finance Convergence:Integration of payment acceptance, inventory financing, and payroll services into single platforms is reshaping how Saudi retail and construction sector software vendors bundle financial products.
- Hajj and Umrah Payment Rails:Seasonal pilgrimage traffic creates concentrated demand for multi-currency digital wallets and merchant onboarding solutions in Makkah and Madinah, with regulatory support for pilgrim-focused fintech licensing.
Industry Challenges
- Legacy Core Banking Integration:Neobanks and lending platforms face extended API negotiation timelines with Saudi National Bank and Al Rajhi's aging mainframe systems, delaying product launches despite sandbox approval.
- Quantitative Risk Talent Scarcity:Alternative credit scoring model development requires machine learning engineers with Arabic-language data experience, a specialization where supply lags demand across the kingdom's technology labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Fintech Market |
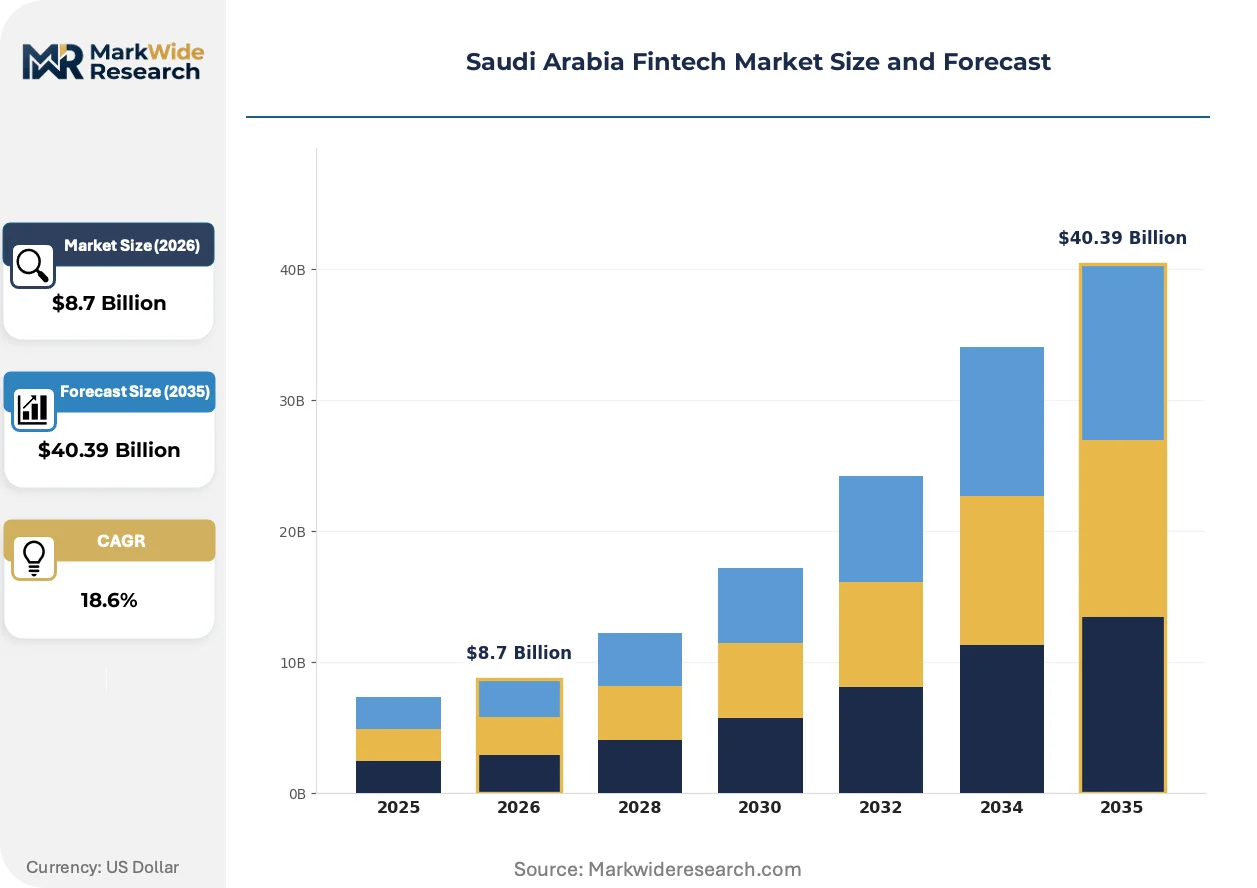
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Solutions, Wealth Management, Insurance Technology, Lending Services Client Type: Banks, SMEs, Consumers, Enterprises Technology: Blockchain, AI, Machine Learning, Mobile Platforms Offering: Applications, Platforms, APIs, Consulting Services |
| Companies Covered | STC Pay, Tamara, HyperPay, Geidea, Hala, Raqamyah, Lean Technologies, Riyad Bank Digital, Lendo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Fintech Market Evolving Landscape
Payment infrastructure across Saudi Arabia is fragmenting into specialized vertical stacks as merchants reject one-size-fits-all solutions, while regulatory pressure on data sovereignty and Shariah compliance is forcing architectural redesigns of cloud-native platforms.
Biometric authentication is miniaturizing across Saudi fintech architectures. Facial recognition and palm-vein scanning now handle transaction authorization for high-value transfers, replacing SMS one-time passwords. Retail banking apps and merchant onboarding flows deploy these modalities to reduce friction in customer verification. This technology is miniaturizing the identity layer, embedding it directly into payment hardware and mobile SDKs rather than routing through separate identity verification vendors.
SAMA's Consumer Protection Law and its 2023 amendments mandate real-time disclosure of annualized percentage rates and total cost of credit for all digital lending products. Fintechs must redesign their checkout interfaces and merchant-embedded credit flows to display standardized cost metrics before transaction completion. The buy-now-pay-later segment faces the steepest compliance burden, restructuring merchant commission disclosures and late fee calculations to meet the new transparency requirements.
Merchant acquisition patterns are fragmenting across Saudi Arabia's second-tier cities. Traditional bank-led merchant services concentrated in Riyadh and Jeddah are losing ground to independent sales organizations deploying Android terminals with integrated inventory management. Asir, Tabuk, and Hail provinces show the fastest uptake of these bundled hardware-software solutions, as regional distributors build direct relationships with family-owned retail networks outside the major metropolitan banking footprints.
Saudi Arabia Fintech Market Segmentation
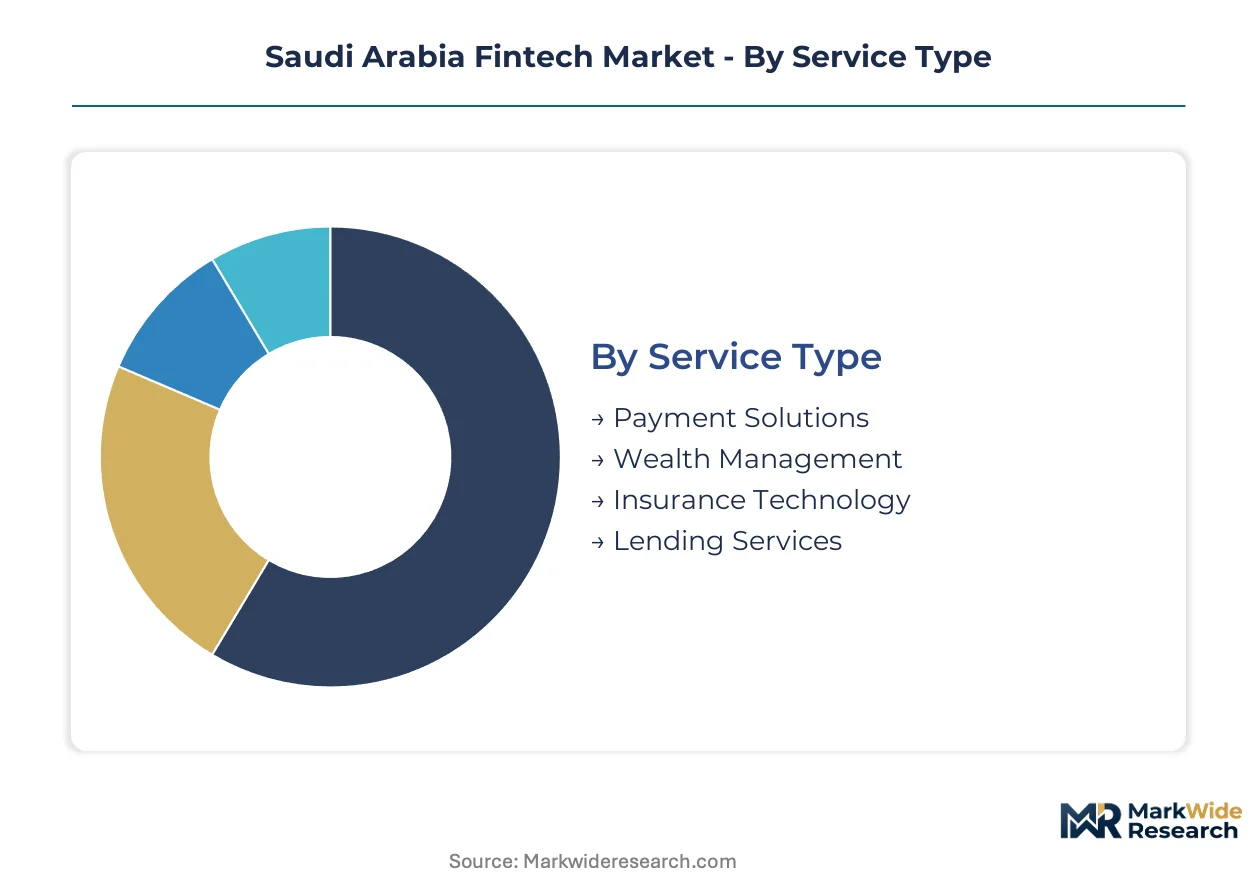
Saudi fintech revenue pools concentrate unevenly across service lines and client categories, with Payment Solutions and SME banking capturing disproportionate margin share. Technology architecture choices and regulatory compliance pathways further stratify competitive returns across the kingdom's financial districts.
Service Type:
Margin pools concentrate in transaction-heavy segments where volume scale compensates for thin per-unit economics, while lending services extract premium spreads through alternative credit scoring.
- Payment Solutions:Digital wallet infrastructure and merchant acquiring networks process high-frequency transactions across Riyadh's retail corridors. Concentrated demand clusters around government-backed wallet initiatives and POS modernization in hospitality sectors, with SAMA's open-banking APIs enabling real-time settlement rails that reduce working-capital drag for merchants.
- Lending Services:Alternative credit platforms deploy machine learning models against thin-file SME borrowers, displacing traditional collateral requirements with cash-flow-based underwriting. Dammam's industrial logistics clusters and Jubail's manufacturing corridors drive concentrated origination volumes for specialized working-capital products.
- Wealth Management:Robo-advisory platforms target affluent retail segments with Shariah-compliant portfolio construction.
- Insurance Technology:Embedded distribution models integrate takaful products into e-commerce checkout flows and automotive financing.
The dominant share belongs to Payment Solutions, while Lending Services is closing the gap fastest.
Client Type:
Application intensity varies sharply by client sophistication, with smaller enterprises showing highest platform adoption velocity due to unmet credit gaps.
- SMEs:Working-capital constraints and limited banking relationships position smaller enterprises as the most receptive client segment for digital lending and integrated payment-acceptance solutions. Eastern Province manufacturing clusters around Dammam show particular appetite for inventory financing tied to POS transaction data.
- Banks:Incumbent institutions deploy fintech partnerships and in-house digital labs to modernize legacy core systems and defend deposit franchises against neobank entrants.
- Consumers:Retail users drive wallet transaction volumes and buy-now-pay-later adoption, particularly in Riyadh and Jeddah metropolitan corridors.
- Enterprises:Large corporates utilize treasury management platforms and supply-chain financing solutions with API integration into ERP systems.
SMEs command the deepest platform engagement, while Banks are expanding their fintech procurement budgets most aggressively.
Technology:
Architecture choices determine compliance burden and scalability ceiling, with mobile-native stacks dominating customer-facing deployment.
- Mobile Platforms:Smartphone-first interfaces constitute the primary customer touchpoint across Saudi fintech, with super-app convergence bundling payments, lending, and commerce functionality. Riyadh's concentrated software engineering talent supports rapid feature iteration for retail banking applications.
- AI:Alternative credit scoring and fraud detection models process Arabic-language financial data and behavioral signals, with model development constrained by quantitative risk talent scarcity.
- Blockchain:Distributed ledger pilots focus on cross-border remittance corridors and trade finance documentation.
- Machine Learning:Predictive analytics power merchant cash-flow forecasting and dynamic pricing for embedded lending products.
Mobile Platforms anchor the installed base, though AI is expanding most quickly as lenders compete on underwriting precision.
Offering:
Delivery mode shapes partnership economics and customer acquisition cost structures across the kingdom's fintech ecosystem.
- Platforms:End-to-end software stacks integrating KYC, payments, and lending functionality enable fastest time-to-market for licensed fintechs and bank digital units. SAMA's sandbox graduation requirements favor platform completeness over point solutions.
- APIs:Modular interfaces allow banks and merchants to embed financial services into existing workflows, with open-banking mandates standardizing data exchange protocols.
- Applications:Standalone consumer and merchant apps compete for screen real estate through wallet functionality and loyalty integration.
- Consulting Services:Advisory engagements support Shariah compliance certification and regulatory sandbox navigation for early-stage entrants.
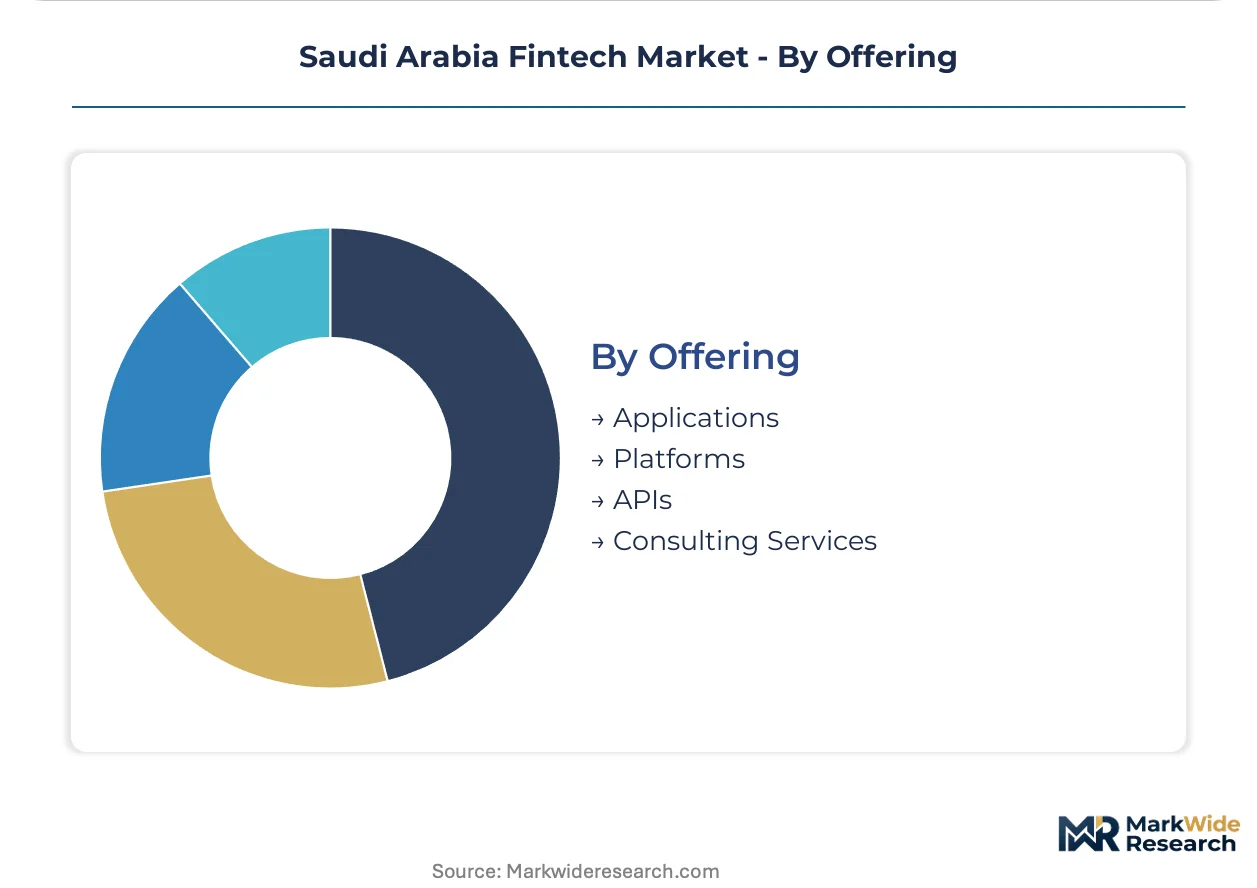
Platforms capture the largest revenue share, while APIs are gaining share fastest through embedded finance proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment concentrates in Riyadh's financial district, where SAMA's regulatory sandbox and venture capital flows cluster around government-backed fintech initiatives. Eastern Province industrial corridors and Western Region pilgrimage centers anchor secondary demand nodes, while NEOM's emerging digital infrastructure attracts experimental banking pilots.
Riyadh
Digital wallet infrastructure and merchant POS modernization drive concentrated fintech adoption across the capital's retail corridors. SAMA's open-banking API standards require domestic banks to expose customer-permissioned data interfaces, enabling real-time credit scoring. King Abdullah Financial District hosts the densest concentration of licensed neobanks and quantitative risk engineering talent.
Eastern Province
Manufacturing and logistics clusters around Dammam and Jubail generate specialized demand for inventory financing and working-capital solutions. The Saudi Central Bank's graduated licensing tiers allow fintechs to test SME lending products with limited customer bases before full deployment. Industrial software vendors in the region embed payment acceptance and payroll services into single platforms.
Western Region
Hajj and Umrah pilgrimage traffic creates seasonal demand spikes for multi-currency digital wallets and merchant onboarding solutions in Makkah and Madinah. SAMA supports pilgrim-focused fintech licensing with streamlined sandbox entry. Jeddah's commercial port infrastructure anchors cross-border payment corridor development for trade finance digitization.
NEOM Northwest
Experimental banking pilots test cloud-native core systems and biometric authentication architectures outside legacy regulatory constraints. The Saudi Central Bank permits limited-scope digital currency trials and blockchain-based settlement rails within the zone's regulatory perimeter. NEOM's data localization infrastructure attracts fintechs seeking to minimize domestic server placement costs.
Saudi Arabia Fintech Market Competitive Landscape
Concentration sits with telecom-backed wallet providers and specialized lending platforms that leverage parent infrastructure for customer acquisition. Three archetypes dominate: incumbent bank digital units defending deposit franchises, independent neobanks graduating from SAMA's sandbox, and merchant-acquired credit specialists embedding finance at point-of-sale. Competitive moves center on strategic partnerships with legacy core banking systems and vertical specialization into underserved industrial sectors.
Within the telecom-anchored tier, STC Pay leverages its parent network for wallet distribution across the kingdom. Tamara and Geidea occupy positions in merchant-facing credit and POS hardware penetration respectively, exemplifying how specialization in buy-now-pay-later structures and terminal network extension create defensible positioning against generalized banking apps.
| Leading Market Players |
|---|
| STC Pay |
| Tamara |
| HyperPay |
| Geidea |
| Hala |
| Raqamyah |
| Lean Technologies |
| Riyad Bank Digital |
| Lendo |
| Others |
Value Network & Pricing Analysis
Cloud-native core banking systems replacing legacy mainframe infrastructure simultaneously concentrate vendor relationships in Riyadh's technology corridor and compress deployment cost curves for licensed fintechs graduating from SAMA's sandbox framework.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Saudi fintech service delivery. Premium tiers bundle Shariah-certified products with dedicated API support and real-time settlement guarantees, while economy tiers strip out compliance advisory to capture price-sensitive SME merchants in secondary cities. Cost compression in standard-tier payment processing is intensifying because Android-based POS hardware commoditization erodes per-terminal software margins. Family-owned retail networks in Asir and Tabuk provinces exhibit highest price sensitivity, whereas Riyadh-based neobanks with venture backing show lowest sensitivity to subscription pricing.
Supply Chain Analysis
Saudi Arabia and the United Arab Emirates anchor data center infrastructure deployment for licensed fintechs meeting SAMA's domestic server placement mandates. Cloud computing capacity, biometric authentication hardware, and Arabic-language NLP training datasets constitute critical input dependencies. Single-source vulnerability concentrates in Riyadh's quantitative risk engineering talent pool, where machine learning specialists with Arabic financial data experience remain scarce. Distribution runs through direct enterprise sales teams for large merchant acquirers and independent sales organizations deploying Android terminals to provincial retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
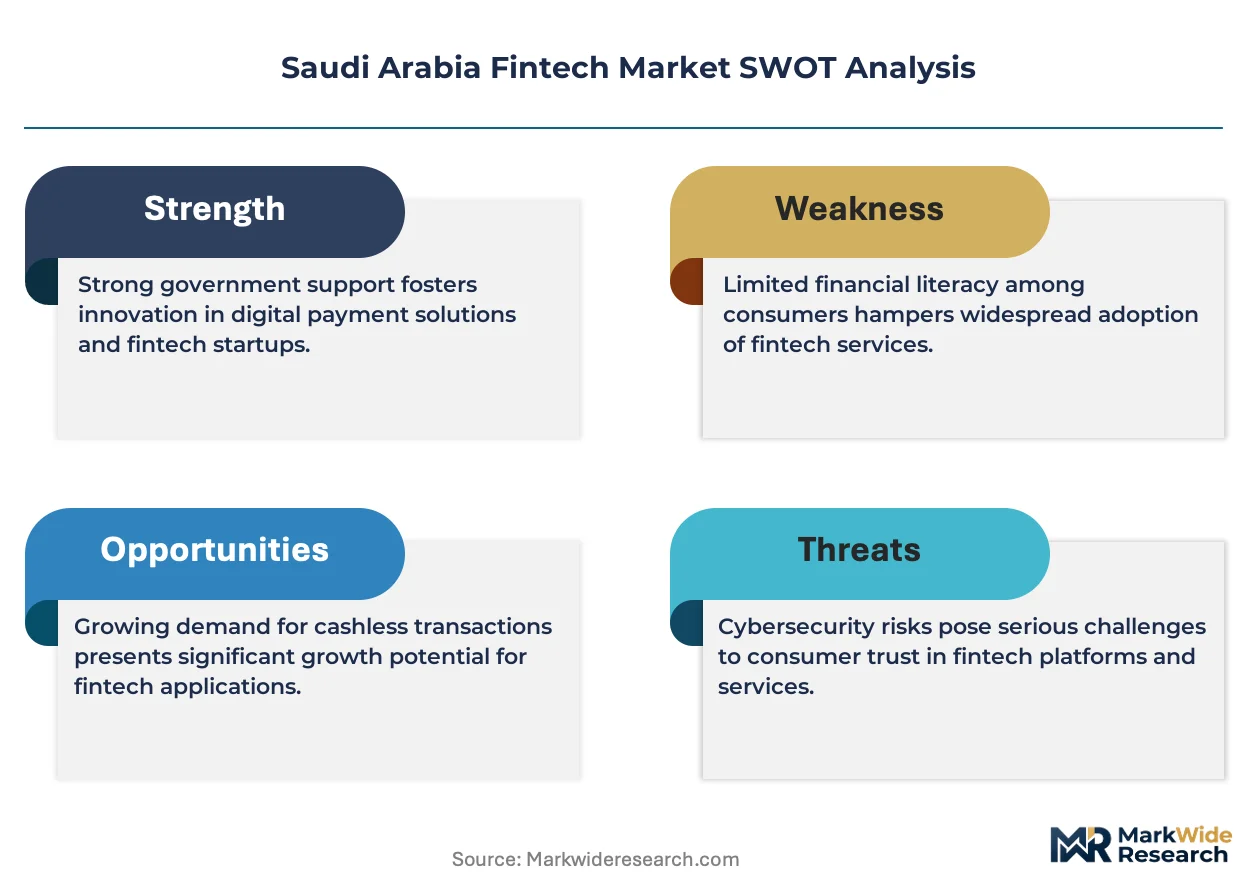
Saudi Arabia's fintech market sits in early-cycle expansion, with SME banking penetration running below regional benchmarks despite SAMA's accelerated sandbox graduation timelines.
For Market Incumbents: Fortify core deposit franchises by acquiring sandbox-graduated neobanks before venture-backed entrants scale merchant-acquired credit volumes. Al Rajhi and Saudi National Bank must modernize aging mainframe APIs to prevent partnership delays that cede working-capital lending share to specialized platforms. Priority investment in Eastern Province data localization infrastructure reduces compliance cost exposure for acquired fintech subsidiaries. For New Entrants and Emerging Players: SAMA's pilgrim-focused fintech licensing fast-track offers streamlined sandbox entry for multi-currency wallet solutions targeting Makkah and Madinah seasonal demand. White space concentrates in Dammam's manufacturing corridors, where inventory financing tied to POS transaction data remains underserved by incumbent banks. Go-to-market execution through industrial software vendor partnerships embeds payment acceptance and payroll into single platforms without direct merchant acquisition costs. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors specialized lenders with sector-specific underwriting models over generalized consumer wallet plays. Long-term viability hinges on regulatory sandbox graduation rates and open-banking API adoption velocity across Saudi National Bank's legacy systems. Signal to monitor: SAMA's relaxation of data localization requirements for NEOM-based experimental pilots, which would reshape infrastructure cost structures kingdom-wide.| Strategic Initiative | Industry Significance |
|---|---|
| SAMA Sandbox Graduation | Accelerated licensing timelines compress neobank time-to-revenue from years to months. |
| Eastern Province Expansion | Dammam manufacturing clusters generate specialized demand for inventory financing products. |
| Biometric Authentication Deployment | Facial recognition and palm-vein scanning reduce high-value transaction friction. |
| Open Banking API Integration | SAMA-mandated data interfaces enable real-time credit scoring for thin-file SME borrowers. |
| Hajj Payment Rails Development | Seasonal pilgrimage traffic creates concentrated multi-currency wallet demand in Makkah. |
Research Methodology
The analysis maps payment solutions, lending services, wealth management, and insurance technology segments, each validated through SAMA regulatory affairs officers, neobank product executives, merchant acquiring sales directors, and quantitative risk engineers. Primary interviews with Eastern Province industrial software vendors and Riyadh-based venture capital investors combined with secondary validation against SAMA sandbox disclosure filings, Saudi Central Bank open-banking protocol documentation, and customs data on POS hardware imports. Bottom-up transaction volume modeling and top-down GDP-attribution approaches triangulated market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, client category, technology architecture, and delivery mode, with regional adoption patterns further stratifying outputs. CAGRs derived from trend-line extrapolation of sandbox graduation rates, merchant POS replacement cycles, and SME credit gap closure trajectories. Forecast inputs incorporated SAMA regulatory amendment timelines and biometric authentication deployment curves.
Decision-makers should treat outputs as directional under assumptions of continued SAMA sandbox acceleration and stable data localization enforcement; material deviation in Shariah compliance interpretation consistency or legacy bank API negotiation timelines would warrant model refresh. Recalibration cycles align with material shifts in regulatory sandbox graduation criteria and open-banking phase rollouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
IoT for Finance Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
Fintech Technologies Market
FinTech
Canada AI in Fintech Market
FinTech
Generative AI in Fintech Market
FinTech
Europe Fintech Market
FinTech
India AI in Fintech Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Financial Consolidation Software Market
FinTech
IT Financial Management Tools Market
FinTech
Financial Audit Software Market
FinTech
AI in Fintech Market
FinTech
France AI in Fintech Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
MENA Fintech Market
FinTech
Smart Finance Technologies Market