
 Financial Risk Management Software Market | 2026-2036
Financial Risk Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Risk Management Software Market Analysis
Single-source vendor dependency is pivoting toward multi-source procurement as institutions diversify their risk technology stacks. Oracle Financial Services leverages its database heritage to anchor enterprise-scale deployments across Tier 1 banks. SAS Risk Management competes through advanced analytics specialization in stress-testing and model risk governance. NICE Actimize dominates financial crime and compliance segments with integrated anti-money laundering workflows.
Financial risk management software comprises modular platforms that quantify, monitor, and report exposure across credit, market, operational, and liquidity dimensions using stochastic models, Monte Carlo simulations, and real-time data feeds. These systems enable institutions to calculate value-at-risk, regulatory capital requirements, and scenario-based losses for board-level and supervisory reporting. Credit Risk solutions lead product-type revenue as banks prioritize loan portfolio surveillance under stricter provisioning rules, while Cloud-Based deployment expands fastest among mid-tier asset managers seeking elastic compute for stress-testing without fixed infrastructure commitments. API-Driven integration is capturing margin pools as open-banking mandates and embedded finance architectures demand interoperable risk engines.
The US Federal Reserve's CCAR and SR 11-7 model risk management guidance shape demand for documented, auditable risk systems among domestic banks. EBA stress-test methodologies and ECB climate risk expectations drive European procurement of scenario analytics modules. Forward-looking institutions must evaluate whether their current risk infrastructure can absorb emerging crypto-asset exposures and nature-related financial disclosures without wholesale platform replacement.
Market Dynamics
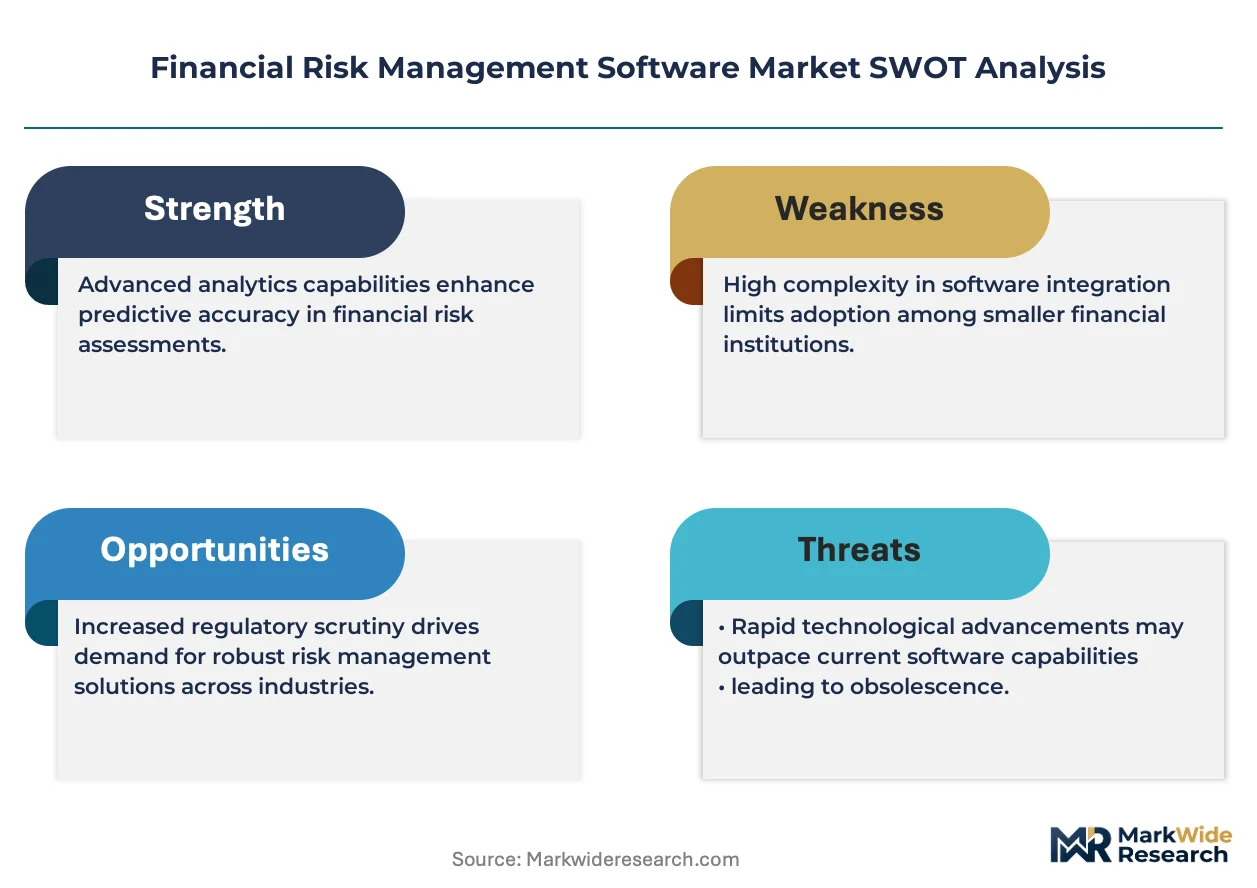
Basel III capital adequacy frameworks and IFRS 9 impairment standards are compressing implementation timelines, forcing institutions to replace legacy risk engines with modular, API-driven platforms that can absorb real-time data feeds.
Growth Catalysts
- Basel III Finalization:Tier 1 banks in the United States must upgrade capital calculation engines to meet enhanced output floor requirements, triggering wholesale procurement cycles for integrated credit and market risk modules.
- Real-time portfolio surveillance:Asset managers in Singapore are deploying streaming analytics to monitor counterparty exposures, creating demand for sub-second latency risk engines.
- Cloud elasticity:Mid-tier German insurers are adopting serverless stress-testing architectures to avoid fixed infrastructure commitments during regulatory exercise windows.
Market Restraints
- Specialized talent scarcity:Quantitative risk modelers with stochastic programming expertise command premium compensation, inflating total cost of ownership for in-house deployments.
- Vendor concentration:Core calculation engines rely on a narrow base of certified numerical libraries, creating single-point-of-failure exposure in enterprise-scale implementations.
- Data residency mandates:China's cybersecurity law requires on-shore storage of transaction records, complicating cross-border risk aggregation for multinational institutions.
Strategic Opportunities
- Crypto-asset risk engines:Swiss private banks are piloting volatility models for digital asset portfolios, opening white space for specialized pricing and collateral modules.
- Nature-related financial disclosure:The EU's Corporate Sustainability Reporting Directive mandates biodiversity impact quantification, requiring new scenario analytics for agricultural lending portfolios.
- Embedded finance integration:API-first risk engines are penetrating non-bank platforms in Brazil, enabling real-time credit decisioning for buy-now-pay-later providers.
Industry Challenges
- Model risk governance:US Federal Reserve SR 11-7 guidelines demand exhaustive documentation of algorithmic decision logic, extending deployment cycles for machine learning-based scoring systems.
- Legacy system entanglement:COBOL-based core banking platforms in Japanese megabanks resist seamless API integration, forcing expensive middleware layers for risk data extraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Risk Management Software Market |
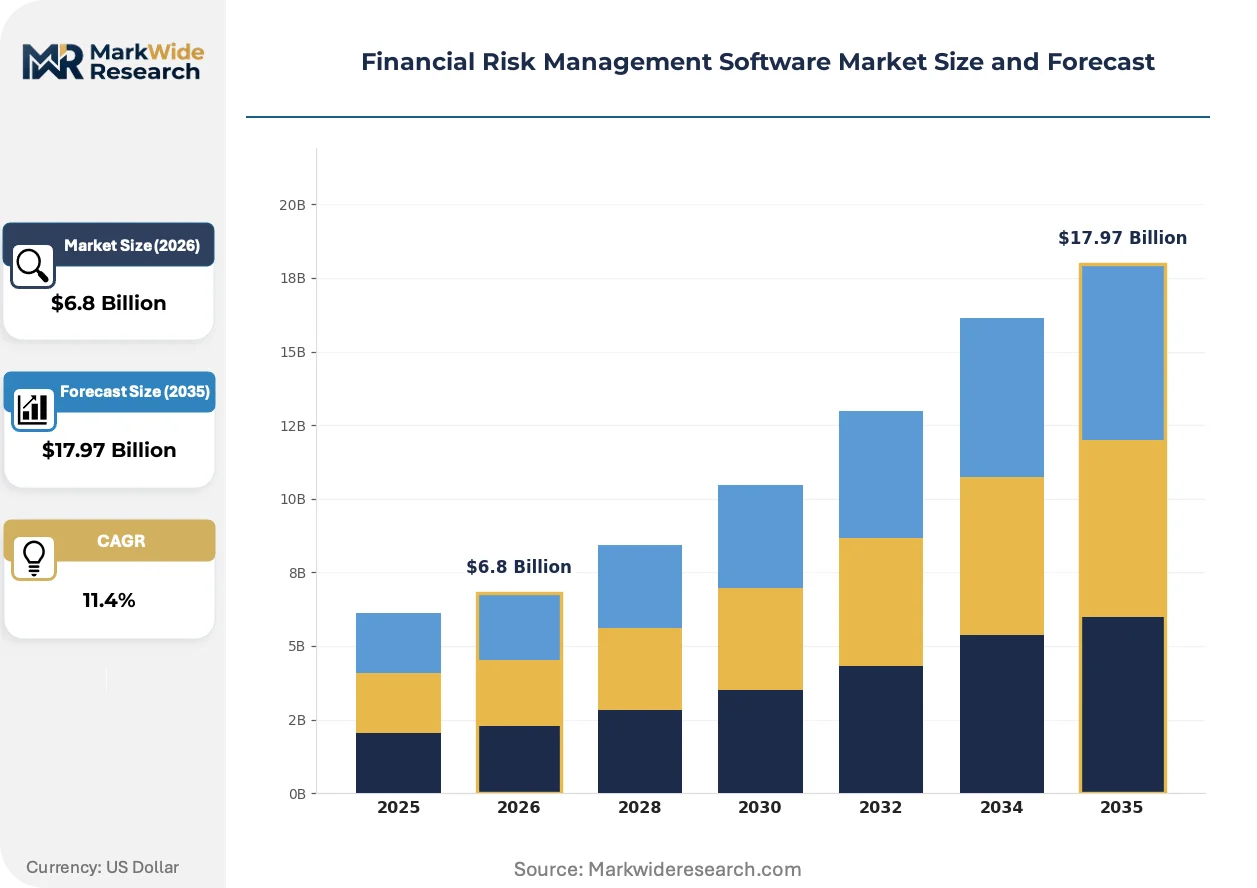
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Credit Risk, Operational Risk, Market Risk, Liquidity Risk Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based End User: Banks, Asset Managers, Insurance Companies, Hedge Funds Integration Level: Stand-Alone, Enterprise, API-Driven, Middleware |
| Companies Covered | FICO TONBELLER, Verafin, Alessa, Creditsafe, Lucinity, NICE Actimize, Oracle Financial Services, SAS Risk Management, ComplyAdvantage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Risk Management Software Market Emerging Trajectories
Distributed ledger infrastructure is decentralizing trade finance risk assessment, while climate stress-testing mandates and open-banking protocols are reshaping how risk engines consume and validate external data streams.
Blockchain-based smart contracts are decentralizing collateral management and settlement verification in trade finance. European commodity traders are piloting these systems for real-time margin calculation. This architecture is decentralizing reliance on centralized clearinghouses, compressing counterparty risk exposure windows from days to minutes.
The EU's Digital Operational Resilience Act mandates granular ICT risk reporting for financial entities. Institutions must map third-party dependencies and test recovery procedures annually. Asset servicers in Luxembourg and Ireland are prioritizing automated control monitoring to satisfy ECB supervisory expectations.
Subscription-based risk analytics are displacing perpetual license models among hedge funds. Portfolio managers in London and New York now prefer usage-priced stress-testing access over capital-intensive platform purchases. This preference shift is most pronounced among quantitative strategies with variable AUM cycles.
Financial Risk Management Software Market Segmentation
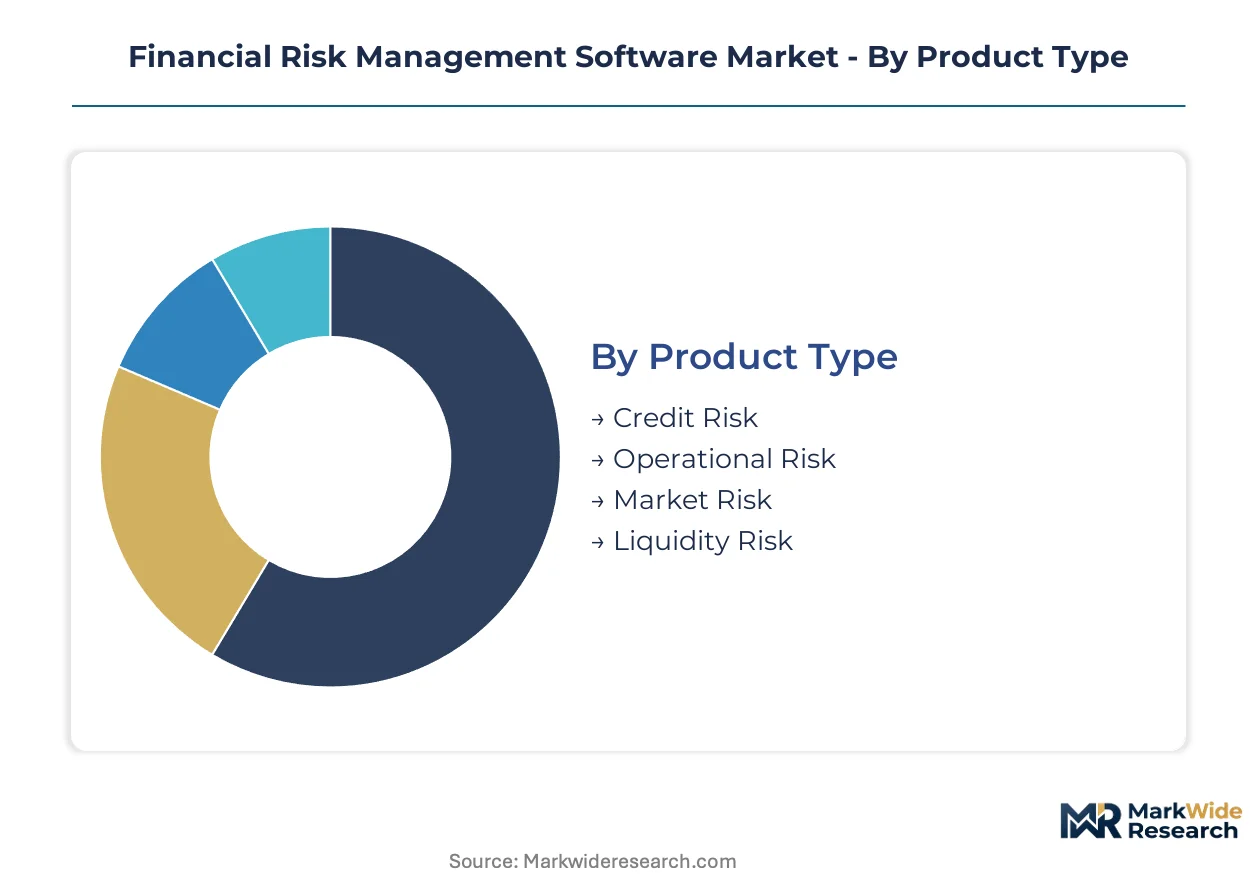
Financial risk management software segments reflect divergent infrastructure philosophies across institutions. Deployment choices separate capital-intensive incumbents from agile challengers. Product specialization maps directly to regulatory pressure points.
Product Type:
Standardized modules dominate lower-complexity use cases, while bespoke stochastic engines command premium procurement for idiosyncratic portfolios.
- Credit Risk:Stochastic models quantify loan portfolio exposure through probability-of-default calculations and loss-given-default simulations. Tier 1 banks in the United States prioritize these modules under IFRS 9 impairment standards, driving concentrated procurement for automated provisioning workflows.
- Market Risk:Value-at-risk engines consume real-time price feeds across equity, fixed income, and derivative positions. Asset managers in Singapore deploy these systems for sub-second exposure monitoring during volatile trading sessions.
- Operational Risk:Event-driven frameworks capture internal loss data and external scenario libraries for regulatory capital allocation.
- Liquidity Risk:Cash flow projection tools stress-test funding gaps under idiosyncratic and market-wide shock assumptions.
Leading the category by volume: Credit Risk. Growing fastest: Market Risk.
Deployment:
Cost tiers separate fixed-capital deployments from consumption-priced alternatives, with mid-tier institutions gravitating toward elastic architectures.
- Cloud-Based:Serverless architectures enable burst compute for regulatory stress-testing windows without perpetual infrastructure commitments. German insurers favor these deployments for EBA exercise elasticity.
- Hybrid:Sensitive calculation engines remain on-premise while reporting layers migrate to cloud instances. Swiss private banks pilot this architecture for crypto-asset portfolios requiring jurisdictional data sovereignty.
- On-Premise:Legacy core banking integrations in Japanese megabanks perpetuate captive data center strategies despite higher total cost of ownership.
- Web-Based:Browser-accessible dashboards serve distributed portfolio management teams with standardized visualization layers.
Dominant by installed base: On-Premise. Steepest expansion trajectory: Cloud-Based.
End User:
Customer type determines functional depth, with regulated deposit-taking institutions demanding exhaustive audit trails versus speed-focused trading operations.
- Banks:Comprehensive platforms integrate credit, market, and operational risk modules for consolidated regulatory reporting. US institutions align these systems with Federal Reserve CCAR documentation requirements.
- Asset Managers:Streaming analytics prioritize real-time counterparty exposure monitoring over historical loss aggregation. Singapore-based managers lead adoption of sub-second latency engines.
- Insurance Companies:Long-dated liability matching and Solvency II compliance shape specialized ALM module procurement.
- Hedge Funds:Subscription-priced stress-testing access displaces perpetual licenses among quantitative strategies with variable AUM cycles.
Largest procurement volume: Banks. Fastest technology refresh: Asset Managers.
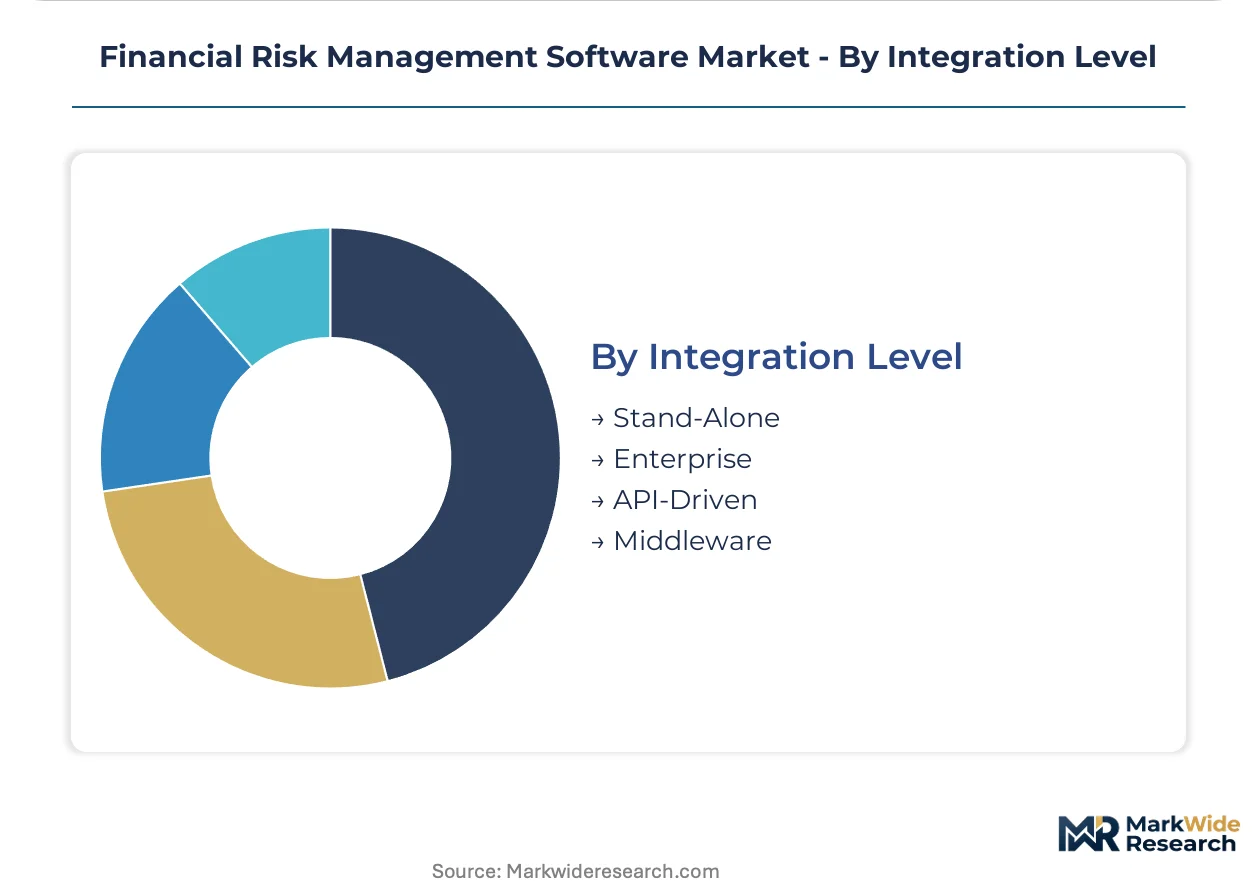
Integration Level:
Margin structures favor deeply embedded engines over surface-level reporting tools, with API monetization capturing value from open-banking mandates.
- API-Driven:Interoperable risk engines embed into third-party platforms for real-time credit decisioning. Brazilian buy-now-pay-later providers integrate these modules for instant underwriting.
- Enterprise:Unified data models span trading, treasury, and finance functions for consolidated risk aggregation. Oracle Financial Services anchors these deployments through database heritage.
- Stand-Alone:Point solutions address discrete regulatory calculations without broader platform commitment.
- Middleware:Translation layers extract risk data from COBOL-based core banking systems in legacy-dependent institutions.
Highest revenue concentration: Enterprise. Gaining share fastest: API-Driven.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center density in Northern Virginia anchors North American risk infrastructure deployment, while submarine cable landings in Singapore and Marseille concentrate real-time data aggregation for Asia-Pacific and European trading hubs respectively.
United States
Tier 1 banks in New York and Chicago drive demand for CCAR-compliant stress-testing engines. The Federal Reserve's SR 11-7 model risk management guidance mandates exhaustive documentation protocols. Dallas-Fort Worth data centers host burst-compute clusters for quarterly regulatory exercises.
Germany
Mid-tier insurers in Frankfurt and Munich prioritize serverless architectures for EBA stress-test elasticity. BaFin's DORA implementation timeline accelerates third-party risk mapping requirements. Berlin fintech clusters pilot API-first risk engines for embedded finance integration.
Singapore
Asset managers in the Marina Bay financial district deploy sub-second latency engines for counterparty exposure monitoring. MAS technology risk management guidelines enforce resilient system architecture standards. The Tanjong Pagar data hub anchors Southeast Asian risk data aggregation.
Switzerland
Private banks in Geneva and Zurich pilot crypto-asset volatility models for digital portfolios. FINMA stablecoin guidance creates compliance templates for blockchain-integrated risk engines. The Zug crypto valley cluster drives specialized pricing module development.
United Kingdom
Hedge funds in London's Square Mile prefer subscription-priced stress-testing over perpetual licenses. The Bank of England's climate biennial exploratory scenario mandates nature-related disclosure analytics. Canary Wharf technology centers host cloud-native risk platform deployments.
Financial Risk Management Software Market Vendor Landscape
Global majors compete with regional champions across deployment architecture and regulatory specialization. The vendor base stratifies between database-heritage enterprises, analytics specialists, and compliance-focused point-solution providers. Three archetypes dominate: legacy platform extenders, cloud-native challengers, and vertical-specific compliance engines. Consolidation pressures favor M&A activity around API interoperability assets, while geographic expansion targets emerging embedded finance markets.
Within the database-heritage tier, Oracle Financial Services and SAS Risk Management occupy positions anchored by enterprise-scale calculation infrastructure. NICE Actimize exemplifies the compliance-specialist archetype with concentrated presence in financial crime workflows. These three entities represent distinct strategic postures: unified data model breadth, advanced stochastic analytics depth, and integrated anti-money laundering workflow dominance respectively.
| Leading Market Players |
|---|
| FICO TONBELLER |
| Verafin |
| Alessa |
| Creditsafe |
| Lucinity |
| NICE Actimize |
| Oracle Financial Services |
| SAS Risk Management |
| ComplyAdvantage |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up risk analytics specialists anchor pricing discipline through recurring-revenue SaaS models, while supply concentration in certified numerical libraries constrains vendor switching costs. Tier 1 banks negotiate enterprise licenses against this backdrop, forcing mid-tier asset managers toward consumption-priced alternatives.
Pricing Analysis
Implementation services and model validation support are increasingly unbundled from core platform subscriptions, with Tier 1 banks paying premium rates for bespoke stochastic engine customization. Three-tier pricing structure across enterprise, professional, and standard levels separates perpetual-license incumbents from consumption-priced challengers. Pricing pressure stems from open-source alternatives encroaching on basic risk calculation modules. Hedge funds exhibit highest price sensitivity, preferring usage-priced stress-testing access over capital-intensive platform purchases.
Supply Chain Analysis
Single-source vulnerability sits with certified numerical libraries concentrated in the United States and United Kingdom, where stochastic programming expertise commands premium compensation. Core calculation engines draw from proprietary Monte Carlo simulation frameworks, open-source statistical libraries, and specialized data feed aggregators. Regulatory certification requirements create switching friction that amplifies vendor concentration risk. Distribution runs through direct enterprise sales teams for Tier 1 deployments and cloud marketplaces for mid-tier subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architectures are displacing monolithic risk engines, forcing institutions to evaluate modular replacement strategies against legacy entanglement costs.
For Market Incumbents: Anticipate margin compression from cloud-native challengers by deepening vertical integration into data feed aggregation and accelerating certification for Basel III finalization modules. Prioritize API interoperability investments to defend against disintermediation by embedded finance platforms. Consolidate around stochastic analytics depth as a differentiation lever against database-heritage competitors. For New Entrants and Emerging Players: Cloud-native deployment routes offer lowest friction entry for mid-tier German insurers seeking serverless stress-testing elasticity. Target crypto-asset volatility modeling for Swiss private banks as the most penetrable white space, where regulatory guidance remains formative. Pursue partnership-led go-to-market strategies with Brazilian buy-now-pay-later platforms for embedded finance integration. For Investors and Strategic Acquirers: MAS technology risk management guideline enforcement is the leading indicator that Singapore-based asset managers will accelerate procurement of sub-second latency engines. Position acquisitions around API interoperability assets with proven Federal Reserve SR 11-7 documentation protocols. Watch for EBA climate stress-test methodology publication as the signal triggering nature-related scenario analytics module demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables real-time credit decisioning for Brazilian embedded finance providers under open-banking mandates. |
| Acquisition of Specialist Firm | Consolidates stochastic analytics depth around crypto-asset volatility modeling for FINMA-compliant Swiss banks. |
| Strategic Partnership | Secures burst-compute capacity for EBA stress-test windows through serverless architecture providers. |
| Product Launch | Introduces nature-related financial disclosure modules aligned with EU Corporate Sustainability Reporting Directive requirements. |
| Geographic Expansion | Establishes local data residency compliance for China's cybersecurity law through on-shore hosting partnerships. |
Methodological Framework
Document review covered SEC 10-K filings, EBA stress-test methodology publications, and MAS technology risk guidelines, complemented by interviews with chief risk officers, quantitative model validation leads, cloud procurement officers, and regulatory compliance directors. Secondary sources included Federal Reserve SR 11-7 guidance documents, Basel Committee technical standards, and IFRS 9 impairment implementation reports. Bottom-up vendor revenue estimates were triangulated against top-down regulatory spending projections.
Segmentation outputs across deployment model, institution size tier, risk module type, and regional regulatory cluster were generated through the analytical framework. CAGRs were derived from regression analysis against regulatory implementation timelines and technology refresh cycles. Model inputs incorporated cloud infrastructure capex disclosures from hyperscalers and disclosed procurement values from Tier 1 bank regulatory filings.
The model holds under stable regulatory implementation schedules; deviation in Basel III finalization timelines or IFRS 9 enforcement intensity would shift deployment pacing assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
BFSI Security Market