
 United Kingdom Fintech Market | 2026-2036
United Kingdom Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Fintech Market Analytics
FCA authorization and the Consumer Duty standard is rotating the competitive landscape toward firms with proven compliance infrastructure. Revolut leverages its multi-currency infrastructure to sustain international payment volumes. Monzo anchors retail consumer acquisition through intuitive mobile-first banking interfaces. Thought Machine differentiates via cloud-native core banking technology that displaces legacy mainframe systems.
United Kingdom Fintech comprises technology-enabled financial services delivered through software platforms, API integrations, and mobile interfaces that process payments, extend credit, manage investments, and insure risks with sub-second transaction latency and bank-grade encryption. Payment Solutions dominates service type revenue as real-time rails displace card networks, while RegTech is accelerating fastest among technology segments as compliance automation replaces manual oversight. AI Advisory concentrates margin pools where algorithmic wealth management reduces human advisor costs for retail consumers.
FCA prudential rules, the UK Consumer Duty framework, and open banking standards mandated by the Competition and Markets Authority shape product design, pricing transparency, and data sharing protocols across the sector. The Bank of England's regulatory sandbox permits controlled innovation but gates market access for unproven models. Stakeholders must monitor evolving stablecoin legislation and the Treasury's digital pound consultation to calibrate infrastructure investment timelines.
Market Dynamics
FCA Consumer Duty implementation is compressing product development timelines while mandating transparent pricing disclosures across all retail-facing fintech interfaces. Open banking API standardization under Competition and Markets Authority mandates is simultaneously enabling third-party payment initiation and account aggregation services.
Growth Catalysts
- Real-time payment rails:Faster Payments Service infrastructure enables sub-second settlement for peer-to-peer transfers and merchant transactions. Neobanks leverage this capability to differentiate from legacy clearing cycles.
- Consumer Duty framework:FCA-mandated fair value assessments force incumbents to retire opaque fee structures. Compliance-ready challengers capture displaced retail deposits.
- Scotland's fintech cluster:Edinburgh and Glasgow data science talent pools support AI-driven credit underwriting and fraud detection specialization. Regional universities feed quantitative analytics pipelines.
Market Restraints
- Cloud infrastructure concentration:AWS and Azure dominance in UK financial services creates systemic operational risk. Regulatory scrutiny of critical third-party dependencies intensifies under Bank of England oversight.
- Legacy core banking lock-in:Tier-one institutions remain tethered to mainframe architectures. Migration costs and operational continuity requirements delay API-native infrastructure adoption.
- Stablecoin legislative uncertainty:Treasury consultation timelines delay institutional cryptoasset product launches. Firms defer infrastructure investment pending statutory clarity.
Strategic Opportunities
- Wealth management automation:Algorithmic portfolio construction targets mass-affluent segments previously served by human advisors. Machine learning models compress advisory cost structures below traditional percentage-based fees.
- Manchester fintech corridor:Lower operational costs relative to London attract payment processors and RegTech developers. Regional expansion diversifies geographic revenue concentration.
- Embedded finance partnerships:Non-financial platforms integrate lending and insurance through Banking-as-a-Service APIs. E-commerce and proptech verticals represent immediate addressable demand.
Industry Challenges
- Specialized compliance talent scarcity:FCA authorization experience commands premium compensation. Firms compete for limited pools of regulatory affairs professionals familiar with prudential rulebooks.
- API security architecture complexity:Open banking data sharing protocols expose attack surfaces across interconnected systems. Cybersecurity investment requirements escalate with ecosystem participant expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Fintech Market |
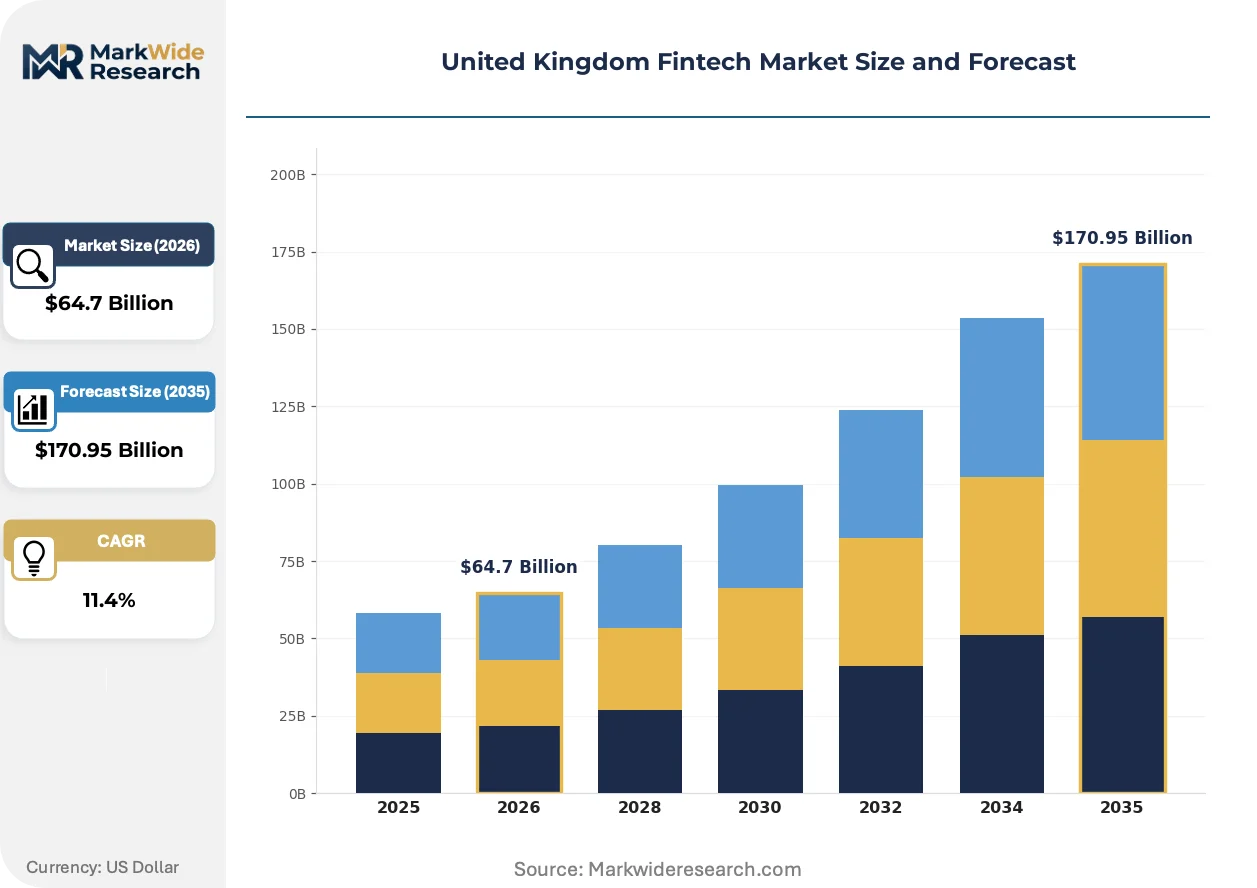
| Market Size in 2026 | $64.7 Billion |
| Market Size in 2035 | $170.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Solutions, Investment Platforms, Loan Services, Insurance Tech Client Type: Retail Consumers, Small Businesses, Enterprises, Startups Technology: Blockchain, Mobile Payments, AI Advisory, RegTech End User: Banking Institutions, E-commerce, Peer-to-Peer, Asset Managers |
| Companies Covered | Wise, Adyen, Revolut, Zilch, SumUp, Monzo, Rapyd, Thought Machine, Starling Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Fintech Market Evolving Landscape
Distributed ledger infrastructure is fragmenting settlement architectures previously dominated by centralized clearinghouses. This technological shift coincides with regulatory pressure on operational resilience and evolving consumer expectations for instant financial services.
Blockchain-based settlement systems are fragmenting correspondent banking relationships for cross-border payments. Remittance-focused fintechs adopt these rails to bypass SWIFT messaging delays and FX markups. Traditional correspondent networks compress fee structures in response to disintermediation pressure.
FCA operational resilience requirements mandate maximum tolerable downtime thresholds for critical banking services. Firms must map third-party dependencies and demonstrate recovery capabilities within four hours. Smaller neobanks invest in redundant infrastructure to meet prudential standards previously applied only to systemic institutions.
Subscription-based financial service bundling displaces transactional fee models among digitally native consumers. Neobanks package travel insurance, metal cards, and cryptocurrency access into monthly memberships. Younger demographics in London and Birmingham metropolitan areas demonstrate strongest adoption of consolidated service propositions.
United Kingdom Fintech Market Segmentation
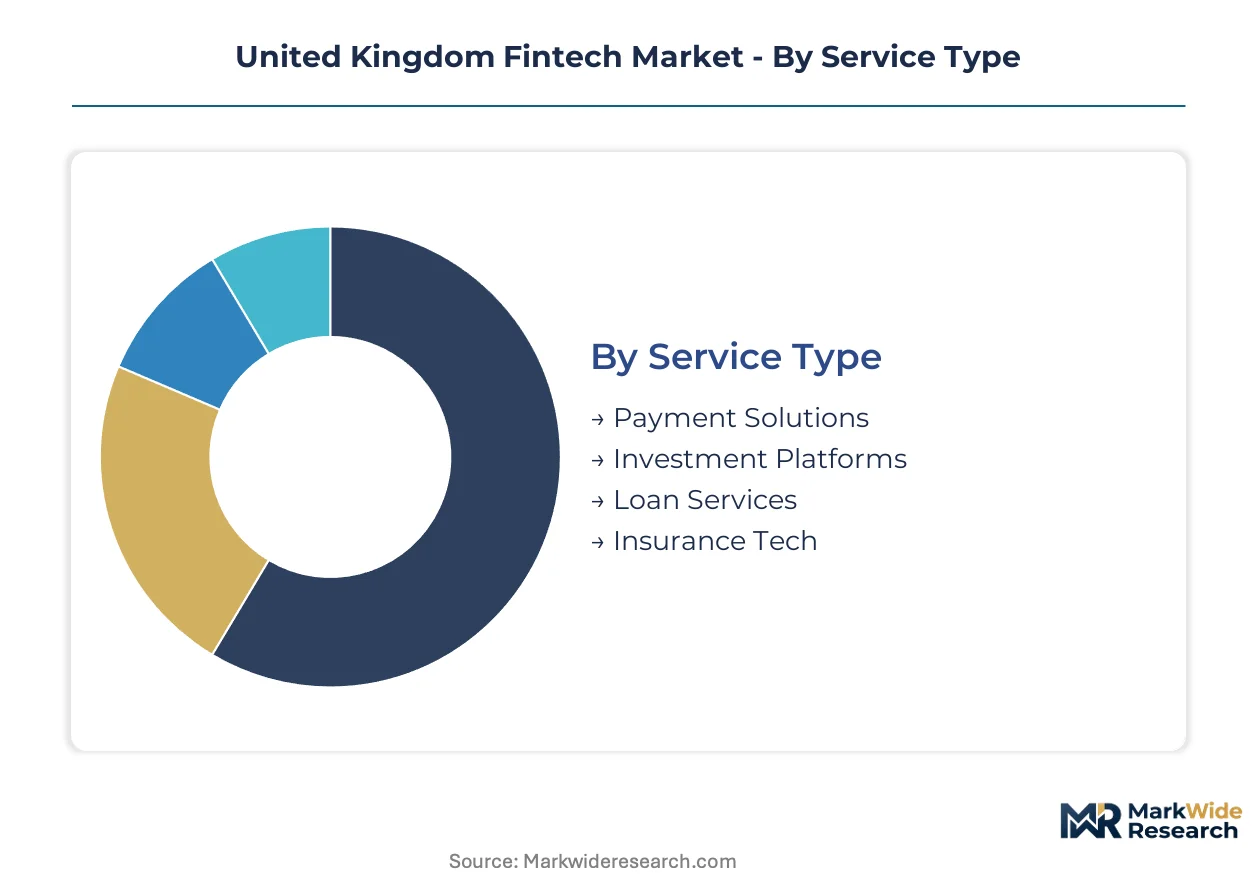
United Kingdom fintech segmentation reveals how regulatory mandates reshape competitive boundaries across service delivery models. FCA authorization tiers and Consumer Duty compliance requirements create natural stratification between established players and emerging entrants.
Service Type:
FCA prudential rules differentiate authorization pathways, with payment institutions facing lighter capital requirements than deposit-taking lenders. Consumer Duty fair value assessments apply unevenly across transactional versus advisory services.
- Payment Solutions:Real-time settlement infrastructure processes peer-to-peer transfers and merchant transactions through Faster Payments Service rails. London neobanks leverage sub-second clearing to displace legacy card network cycles and capture retail transaction volumes.
- Investment Platforms:Algorithmic portfolio construction and fractional share trading reduce minimum investment thresholds for mass-affluent consumers. Manchester and Edinburgh clusters concentrate Robo-advisory development talent drawn from regional quantitative finance programs.
- Loan Services:Open banking credit scoring via API-accessed transaction data enables alternative underwriting models for thin-file borrowers.
- Insurance Tech:Embedded distribution through Banking-as-a-Service APIs places coverage at point-of-sale across e-commerce and proptech verticals.
Payment Solutions handles the majority of throughput; RegTech-adjacent infrastructure within this category is the fastest mover on share.
Client Type:
Customer sophistication tiers dictate product complexity and regulatory scrutiny intensity. Retail-facing interfaces trigger full Consumer Duty disclosure requirements, while B2B services operate under lighter conduct standards.
- Retail Consumers:Mobile-first banking interfaces with intuitive onboarding flows dominate acquisition strategies. Birmingham and London metropolitan areas show strongest adoption of subscription-bundled service propositions combining travel insurance with cryptocurrency access.
- Small Businesses:Open banking API integration enables automated bookkeeping and cash flow forecasting. Edinburgh data science clusters support AI-driven credit underwriting specialization for SME lending.
- Enterprises:Treasury management and cross-border payment optimization require multi-currency infrastructure and FX hedging capabilities.
- Startups:Banking-as-a-Service APIs reduce time-to-market for embedded finance propositions in non-financial platforms.
Retail Consumers anchor current revenue pools; Small Businesses are expanding most quickly as open banking APIs mature.
Technology:
Technology selection determines infrastructure capital intensity and regulatory compliance automation potential. Cloud-native architectures reduce operational resilience compliance costs relative to legacy mainframe dependencies.
- Blockchain:Distributed ledger settlement fragments correspondent banking relationships for cross-border remittances. Fintechs bypass SWIFT messaging delays and FX markups through decentralized rails, pressuring traditional networks to compress fee structures.
- Mobile Payments:NFC-enabled contactless infrastructure dominates point-of-sale transaction volumes. London's merchant density supports QR-code alternative payment method experimentation.
- AI Advisory:Machine learning models compress wealth management cost structures below traditional percentage-based fees.
- RegTech:Compliance automation replaces manual oversight for FCA reporting and Consumer Duty fair value assessments.
Mobile Payments processes the highest transaction volumes; RegTech shows the steepest expansion trajectory as regulatory complexity intensifies.
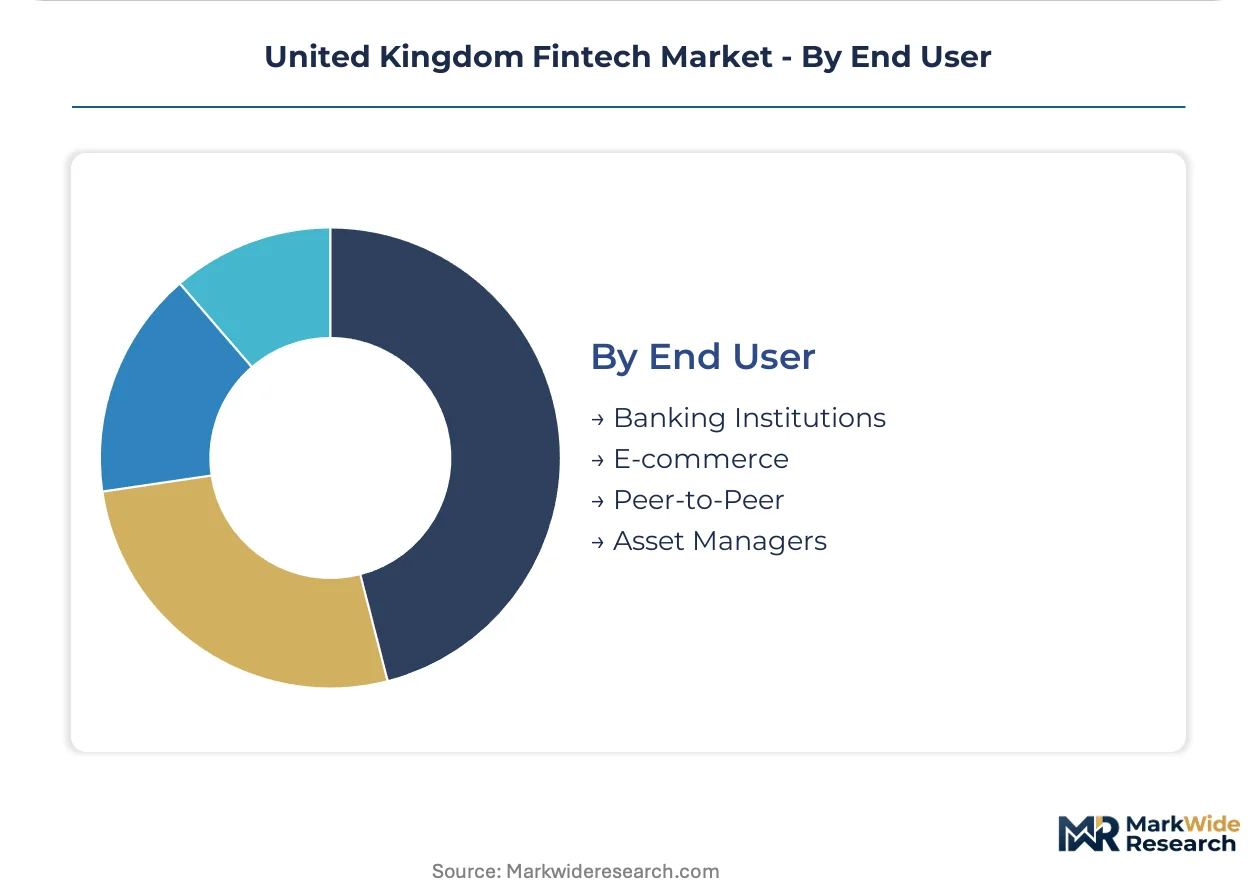
End User:
End-user concentration shapes geographic clustering and partnership strategy. Banking institutions concentrate in London's financial district, while e-commerce platforms distribute demand across Manchester and Birmingham logistics corridors.
- Banking Institutions:Core banking modernization projects displace legacy mainframe systems with cloud-native alternatives. Tier-one institutions face migration cost barriers that delay API-native infrastructure adoption despite regulatory pressure.
- E-commerce:Embedded finance integration places lending and insurance at point-of-sale. Lower operational costs in Manchester attract payment processors serving online retail verticals.
- Peer-to-Peer:Real-time settlement enables direct lending and payment splitting without intermediary institutions.
- Asset Managers:Algorithmic portfolio rebalancing and risk analytics reduce reliance on human advisor labor.
Banking Institutions anchor infrastructure investment; E-commerce is gaining share fastest through embedded finance partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK Treasury's digital pound consultation and FCA regulatory sandbox incentives are redirecting infrastructure investment toward compliance-ready clusters. Sub-regional differentiation reflects proximity to regulatory expertise, university talent pipelines, and legacy banking concentration.
London and the Southeast
Neobank headquarters and venture capital concentration drive demand for real-time payment infrastructure and AI advisory platforms. The FCA's direct oversight mandates shape product development timelines for retail-facing fintechs. The Square Mile and Canary Wharf host embedded finance partnerships between Banking-as-a-Service providers and e-commerce platforms.
Scotland
Edinburgh and Glasgow data science programs supply quantitative talent for credit underwriting and fraud detection specialization. Scottish Enterprise innovation grants support RegTech development for compliance automation. The Edinburgh financial district anchors AI-driven SME lending operations with proximity to legacy insurance expertise.
North England
Manchester's lower operational costs attract payment processors and RegTech developers seeking alternatives to London rents. The Bank of England's regional engagement programs channel sandbox participation to northern startups. The Manchester fintech corridor concentrates embedded finance integration for proptech and logistics verticals.
Midlands
Birmingham metropolitan areas show strongest adoption of subscription-bundled banking propositions among younger demographics. Regional development agencies coordinate open banking API pilots for small business cash flow forecasting. The West Midlands logistics corridor supports e-commerce payment infrastructure serving distribution networks.
Wales
Cardiff and Newport emerging tech clusters benefit from devolved administration funding for digital infrastructure. The Welsh Government's fintech strategy prioritizes cybersecurity specialization for open banking API security architecture. South Wales universities feed software engineering pipelines for cloud-native core banking development.
United Kingdom Fintech Market Competitive Landscape
Player mix skews toward neobanks and infrastructure specialists competing across authorization tiers. The competitive structure fragments between deposit-taking challengers, payment institutions, and technology vendors displacing legacy core systems. Three archetypes dominate: mobile-first retail banks, multi-currency payment platforms, and cloud-native core banking providers. Consolidation pressure operates through strategic partnerships with non-financial platforms and embedded finance API licensing.
Among UK-based challengers, Revolut, Monzo, and Starling Bank exemplify the mobile-first archetype with distinct positioning vectors. Revolut occupies the multi-currency infrastructure tier for international payment volumes. Monzo anchors intuitive consumer acquisition through interface design specialization. Starling Bank represents the SME-focused variant with open banking API integration for business cash flow services. These entities collectively demonstrate how FCA authorization experience and Consumer Duty compliance infrastructure separate viable challengers from pre-revenue entrants.
| Leading Market Players |
|---|
| Wise |
| Adyen |
| Revolut |
| Zilch |
| SumUp |
| Monzo |
| Rapyd |
| Thought Machine |
| Starling Bank |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure scale economies at AWS and Azure concentrate compute capacity in hyperscale facilities, compressing unit costs for API-native fintechs while tethering price floors to third-party dependency premiums. This concentration shapes competitive positioning between neobanks absorbing pass-through costs and legacy institutions negotiating enterprise volume discounts.
Pricing Analysis
FCA authorization tier creates the primary spread between deposit-taking challengers and payment institutions with lighter capital requirements. Three-tier pricing structure across premium subscription bundles, standard transactional fees, and economy API access separates Revolut's metal card memberships from Monzo's freemium onboarding. Pricing pressure stems from Consumer Duty-mandated fair value disclosures forcing opaque fee retirement. Small businesses show highest price sensitivity due to thin operating margins, while mass-affluent retail consumers absorb premium tiers for bundled cryptocurrency and travel insurance access.
Supply Chain Analysis
Ireland and the Netherlands anchor European cloud infrastructure serving UK fintech API workloads, with Frankfurt data centers processing cross-border payment clearing. Critical inputs include AWS Graviton compute instances, Swift messaging licenses, and FCA-compliant audit software. Single-source vulnerability concentrates in Tier-one cloud providers under Bank of England operational resilience scrutiny. Distribution runs through Banking-as-a-Service platforms embedding financial products into e-commerce and proptech verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based settlement rails threaten correspondent banking relationships, forcing incumbents to defend payment volume through infrastructure modernization before decentralized alternatives capture cross-border remittance margins.
For Market Incumbents: Consolidate API-native core banking capabilities through cloud migration partnerships displacing mainframe dependencies. Acquire RegTech automation assets to compress Consumer Duty compliance costs below challenger benchmarks. Vertical integration into embedded finance distribution channels protects transaction volumes against neobank disintermediation.
For New Entrants and Emerging Players: SME cash flow forecasting gaps in Manchester and Birmingham corridors offer immediate white-space penetration with lower customer acquisition costs than London saturation. Target open banking API integration for automated bookkeeping services underserved by legacy business banking interfaces. Partner with proptech platforms for point-of-sale lending deployment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native core banking vendors over mainframe-dependent legacy processors. Long-term viability rests on regulatory sandbox graduation rates and FCA authorization velocity. Watch Treasury stablecoin legislation timelines as inflection signal for cryptoasset infrastructure investment recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| FCA Authorization Pathway | Consumer Duty compliance infrastructure separates viable challengers from pre-revenue entrants. |
| Cloud-Native Core Migration | API-native architectures displace legacy mainframe systems under operational resilience mandates. |
| Embedded Finance Partnership | Banking-as-a-Service APIs place lending and insurance at e-commerce point-of-sale. |
| RegTech Automation Acquisition | Compliance software reduces manual oversight costs for fair value assessment reporting. |
| Regional Corridor Expansion | Manchester and Edinburgh clusters diversify geographic revenue concentration beyond London. |
Research Methodology
Desk research of FCA authorization databases, Bank of England regulatory filings, and open banking API standards documentation preceded structured interviews with neobank product executives, compliance officers at payment institutions, cloud infrastructure procurement leads, and venture capital fintech specialists. Secondary validation drew from Competition and Markets Authority market studies, Treasury consultation papers, and hyperscaler capex disclosures. Bottom-up transaction volume estimates triangulated against top-down sectoral GDP attribution.
Variance decomposition across service type, client sophistication tier, technology stack, and geographic cluster shaped the analytical framework over the projection horizon. Modeled dimensions included payment versus advisory service categories, retail versus SME versus enterprise segmentation, cloud-native versus legacy infrastructure, and London versus regional corridor concentration. CAGRs derived from historical authorization velocity and API adoption curves, with inputs from Faster Payments Service throughput trends and AI advisory platform deployment rates.
Material uncertainties — Treasury stablecoin legislation timelines, Bank of England digital pound consultation outcomes, and hyperscale cloud provider operational resilience certification delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory sandbox graduation rates and Consumer Duty implementation consistency. Recalibration cycles align with material shifts in FCA prudential rule amendments and open banking API standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Micro-Investing Platform Market
FinTech
United States Fintech Market
FinTech
Cyber Security in Fintech Market
FinTech
Robo Advisory Market
FinTech
Financial Services Cloud Market
FinTech
Europe Fintech Market
FinTech
China AI in Fintech Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Robo-Advisory Services Market
FinTech
Vietnam Fintech Market
FinTech
Financial Consolidation Software Market
FinTech
Fintech Technologies Market
FinTech
Financial Forecasting Software Market
FinTech
Financial Analytics Market
FinTech
Fintech Lending Market
FinTech
Hand Account Software Market