
 Financial Fraud Detection Software Market | 2026-2036
Financial Fraud Detection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Fraud Detection Software Market Intelligence
North American cloud infrastructure expansion is reshaping how financial institutions deploy fraud detection architectures. FIS Global leverages its core banking integration to embed transaction monitoring directly into payment rails. IBM sustains competitive positioning through Watson-powered anomaly detection across hybrid environments. SAS Institute dominates the predictive analytics segment with specialized risk-scoring engines for insurance underwriting.
Financial fraud detection software comprises algorithmic platforms that analyze transaction patterns, behavioral biometrics, and identity signals to flag anomalous activity in real time, typically processing millions of events per second through machine learning inference engines. Its primary commercial purpose is to minimize unauthorized fund transfers, synthetic identity exploitation, and money laundering while preserving legitimate customer transaction velocity. Cloud-based deployment now captures the fastest growth trajectory as latency-sensitive institutions abandon on-premises hardware refresh cycles. Machine learning functionality commands the deepest margin pools due to continuous model retraining requirements and scarce data-science talent. Rule-based systems retain residual share among smaller banks with limited IT modernization budgets.
The SEC, CFPB, and FinCEN collectively mandate suspicious activity reporting standards that force institutions toward auditable, explainable detection platforms rather than opaque black-box models. The EU AI Act adds cross-border compliance complexity for multinational banks operating hybrid US-European architectures. Stakeholders must weigh model interpretability against detection accuracy as regulatory examinations increasingly scrutinize algorithmic decision trails.
Market Dynamics
Real-time payment rails and open banking APIs are collapsing the latency window for fraud detection, forcing institutions to abandon batch processing architectures in favor of streaming inference engines that score transactions in milliseconds.
Growth Catalysts
- EU AI Act compliance mandates:European banks must deploy explainable machine learning models by 2025, triggering wholesale replacement of opaque legacy systems with auditable platforms.
- Instant payment networks:FedNow and similar real-time settlement systems in the United States, India, and Brazil eliminate the delay window that once allowed post-transaction review.
- Synthetic identity proliferation:Fraud rings exploit fragmented identity verification across credit bureaus and government databases, driving demand for behavioral biometric cross-referencing.
Market Restraints
- Data-science talent scarcity:Continuous model retraining requires specialized ML engineers, with compensation premiums exceeding 40% above standard software development roles.
- Cloud concentration risk:Three hyperscale providers dominate fraud-detection infrastructure, creating single-point-of-failure exposure for latency-sensitive transaction processing.
- Regulatory fragmentation:Divergent explainability requirements between the SEC's model risk management guidance and the EU AI Act's technical documentation standards force dual compliance architectures.
Strategic Opportunities
- Embedded finance penetration:Non-bank platforms offering lending and payments lack native fraud expertise, creating white-label detection service demand.
- Cross-border payment corridors:Remittance flows between the United States, Mexico, and the Philippines suffer from weak inter-institutional data sharing, opening consortium-based detection networks.
- Quantum-resistant cryptography:NIST's post-quantum standards will force algorithmic overhauls of encryption-dependent identity verification systems by 2030.
Industry Challenges
- Model drift management:Fraud patterns mutate faster than retraining cycles, degrading detection accuracy between scheduled updates.
- Legacy core banking integration:Decades-old COBOL-based transaction engines resist API connectivity, requiring expensive middleware layers for real-time scoring injection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Fraud Detection Software Market |
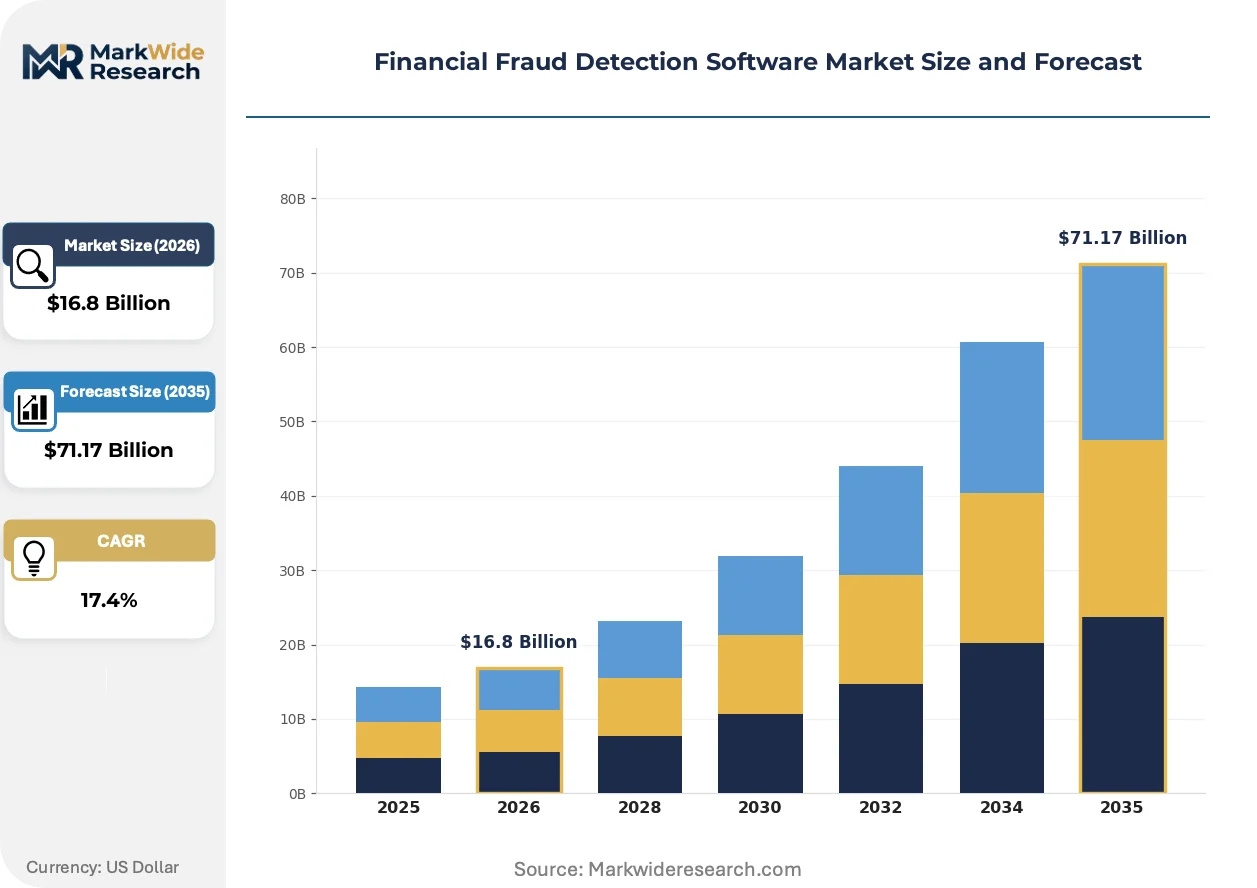
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $71.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Machine Learning, Artificial Intelligence, Rule-Based, Predictive Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Banks, Financial Institutions, Payment Processors, Insurance Companies Functionality: Transaction Monitoring, Account Takeover Protection, Identity Verification, Reporting |
| Companies Covered | Fiserv, LexisNexis Risk Solutions, FIS Global, TransUnion, IBM, SAS Institute, Fair Isaac Corporation, ACI Worldwide, Feedzai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Fraud Detection Software Market Strategic Shifts & Innovations
Detection architectures are converging on streaming data fabrics that unify transaction, behavioral, and third-party signals into single inference pipelines. This consolidation is compressing vendor stacks and elevating platform breadth over point-solution depth.
Graph neural networks are virtualizing relationship mapping across account networks, enabling detection of mule-account rings and layering schemes that evade individual transaction thresholds. Tier-one banks in the United States and United Kingdom are deploying these systems for commercial wire monitoring, with implementation timelines compressing from 18 months to 6 months as cloud-native toolkits mature. The technology is virtualizing the traditional rules-engine layer, collapsing separate case-management and detection infrastructure into unified platforms.
The EU AI Act's risk-classification framework is mandating human-in-the-loop review for high-risk automated decisions, forcing European institutions to redesign straight-through processing workflows. This regulatory friction is diverting R&D investment toward explainability tooling and away from pure accuracy optimization. Multinational banks operating hybrid US-European architectures face the steepest compliance burden, as they must maintain dual model versions or lowest-common-denominator deployments.
Buyers are consolidating vendor relationships around full-stack platforms that combine detection, case management, and regulatory reporting. Procurement teams at regional banks and credit unions are abandoning best-of-breed point solutions that require costly integration maintenance. This concentration is most visible in the United States, where mid-tier institutions face examiner pressure to demonstrate unified audit trails across previously siloed AML and fraud functions.
Financial Fraud Detection Software Market Segmentation
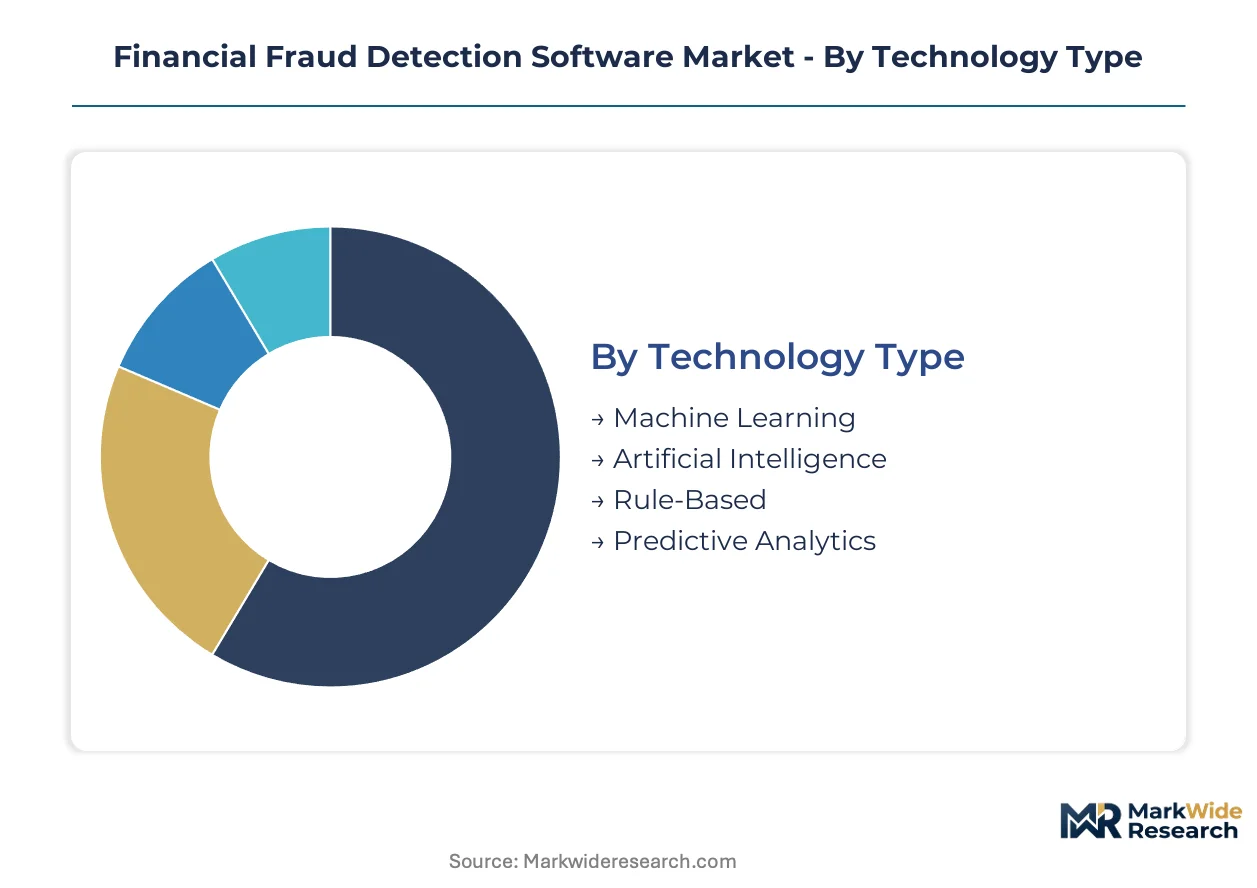
Fraud detection architectures fragment across technology maturity curves, deployment latency requirements, and regulatory compliance burdens. Each segment carries distinct refresh cycles and margin profiles that reshape vendor prioritization.
Technology Type:
Machine learning models demand the shortest retraining cycles as adversarial patterns mutate, while rule-based systems persist on decade-long refresh horizons in budget-constrained institutions.
- Machine Learning:Neural networks and ensemble methods process streaming transaction vectors through continuously updated inference engines. Tier-one banks in the United States and United Kingdom concentrate procurement here, driven by FedNow latency requirements and SEC model risk management scrutiny.
- Artificial Intelligence:Generative and agentic systems automate alert triage and synthetic identity generation for red-team testing. European institutions under EU AI Act mandates are accelerating adoption to meet explainability requirements by the compliance deadline.
- Rule-Based:Static threshold engines and Boolean logic systems dominate smaller credit unions and regional banks with limited IT modernization budgets.
- Predictive Analytics:Statistical scoring models forecast fraud probability from historical pattern libraries.
Rule-based systems anchor the volume base while machine learning gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates hyperscale cloud deployments from captive infrastructure, with hybrid architectures capturing mid-tier institutions seeking regulatory data sovereignty without full capital burden.
- Cloud-Based:Hyperscale elastic compute enables millisecond-scoring for real-time payment rails without hardware refresh cycles. Payment processors in Brazil and India favor this model to bypass capital-intensive data center builds.
- SaaS:Subscription pricing lowers entry barriers for fintech entrants and embedded finance platforms lacking native fraud expertise.
- Hybrid:Sensitive data remains on-premises while compute-intensive inference leverages cloud burst capacity. Multinational banks operating across SEC and EU AI Act jurisdictions deploy this architecture to satisfy divergent data localization mandates.
- On-Premises:Dedicated hardware installations persist where regulatory examiners demand physical audit trails.
On-premises deployments retain the largest installed base while cloud-based delivery climbs the fastest.
End User:
Customer type determines transaction velocity requirements and regulatory examination intensity, with payment processors facing the most compressed decision windows.
- Payment Processors:Real-time authorization decisions across merchant networks demand sub-50-millisecond scoring latency. Visa and Mastercard network participants in the United States are consolidating vendor stacks around unified streaming platforms.
- Banks:Commercial wire desks and retail branches require differentiated detection profiles for transaction size and customer segment.
- Financial Institutions:Credit unions and non-bank lenders prioritize cost efficiency over cutting-edge accuracy.
- Insurance Companies:Underwriting fraud and claims verification drive specialized risk-scoring engine demand.
Banks provide the deepest revenue pool while payment processors drive the steepest technology refresh cycles.
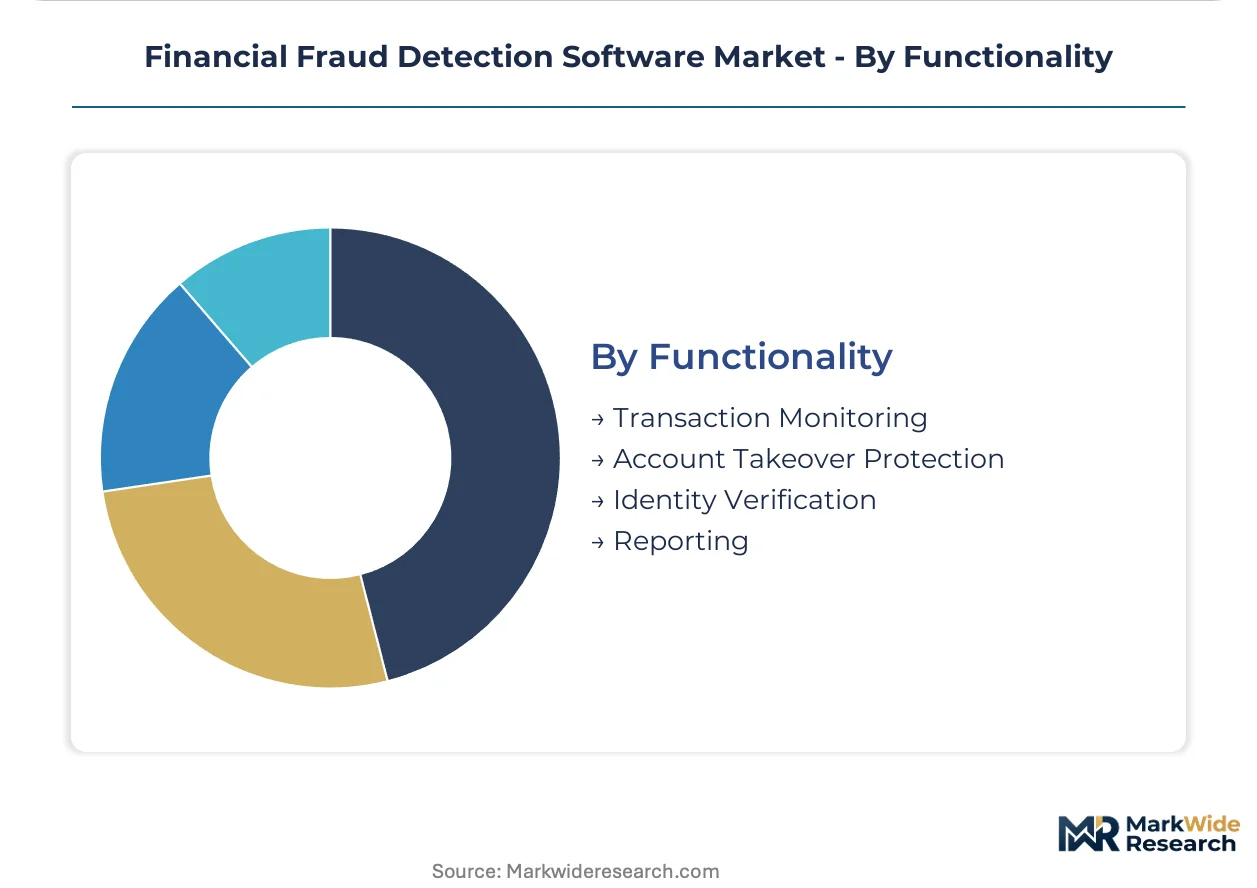
Functionality:
Application criticality varies by exposure vector, with account takeover protection commanding premium pricing due to direct fund loss exposure.
- Transaction Monitoring:Real-time scoring of payment flows against behavioral baselines and watchlist databases. FedNow participants in the United States treat this as table stakes for instant settlement participation.
- Account Takeover Protection:Device fingerprinting, behavioral biometrics, and credential stuffing detection secure authentication flows. Synthetic identity proliferation has elevated this to board-level priority at major card issuers.
- Identity Verification:Document authentication and biometric matching for onboarding workflows.
- Reporting:Suspicious Activity Report generation and regulatory filing automation for FinCEN and FinTRAC compliance.
Transaction monitoring generates the highest absolute spending while account takeover protection expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters around three regulatory jurisdictions with divergent compliance architectures. The United States, United Kingdom, and Germany host the deepest procurement pools, while India and Brazil emerge as high-velocity deployment markets for cloud-native platforms.
United States
FedNow instant settlement and SEC model risk management guidance drive real-time scoring procurement at tier-one banks. The CFPB's examination priorities force mid-tier institutions toward unified audit trails across AML and fraud functions. New York and Chicago financial centers concentrate vendor engineering talent and customer reference sites.
United Kingdom
Open banking API proliferation collapses latency windows for transaction monitoring at major card issuers. The Financial Conduct Authority's operational resilience requirements mandate sub-second failover capabilities for payment processors. London's fintech cluster anchors European headquarters decisions for North American software vendors.
Germany
Industrial Mittelstand banks seek cost-efficient SaaS alternatives to legacy core banking integrations. BaFin's guidance on IT outsourcing creates compliance complexity for cloud migration timelines. Frankfurt's concentration of European Central Bank operations drives demand for euro-denominated real-time payment monitoring.
India
UPI transaction volumes exceeding 10 billion monthly payments force domestic processors toward millisecond-scoring architectures. RBI's directive on digital payment security mandates multi-factor authentication layers for wallet providers. Mumbai and Bengaluru host indigenous fraud-tech startups competing with multinational platform vendors.
Brazil
Pix instant payment network adoption triggers wholesale replacement of batch-processing fraud systems at regional banks. Banco Central do Brasil's cybersecurity regulations impose data localization requirements for foreign software providers. São Paulo's fintech corridor concentrates implementation partnerships for cloud-based detection platforms.
Financial Fraud Detection Software Market Key Industry Players
Core banking integrators and standalone AI specialists split the market along deployment complexity lines. Consolidation pressure intensifies as procurement teams abandon point solutions for unified platforms. Two strategic archetypes dominate: incumbents with captive distribution through legacy system relationships, and cloud-native challengers with API-first architectures. Competitive moves center on vertical integration into data asset aggregation and geographic expansion through regulatory sandbox partnerships.
Within the core banking integration tier, FIS Global and Fiserv occupy positions anchored to decades-long institutional relationships. IBM and SAS Institute exemplify the hybrid-cloud archetype, serving multinational banks with divergent data sovereignty requirements across SEC and EU AI Act jurisdictions. These four entities represent the prevailing competitive tension between embedded distribution and architectural flexibility.
| Leading Market Players |
|---|
| Fiserv |
| LexisNexis Risk Solutions |
| FIS Global |
| TransUnion |
| IBM |
| SAS Institute |
| Fair Isaac Corporation |
| ACI Worldwide |
| Feedzai |
| Others |
Cost & Logistics Intelligence
Bengaluru's cloud-native engineering clusters supply inference engine capacity to payment processors worldwide, concentrating pricing power among hyperscale providers that dictate SaaS subscription benchmarks across fraud detection platforms.
Pricing Analysis
The EU AI Act dictates the pricing tier structure by mandating explainability tooling that separates premium auditable platforms from stripped-down rule-based alternatives. Pricing stratifies across enterprise-grade machine learning suites, mid-tier hybrid deployments, and economy rule-based licenses. Cost compression in the economy tier is intensifying because regional banks delay IT modernization cycles. Payment processors exhibit the lowest price sensitivity due to FedNow latency requirements, while credit unions face acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for semiconductor-dependent inference hardware. Cloud infrastructure concentrates in the United States, Ireland, and Singapore. Model training draws from proprietary transaction datasets, open-source frameworks, and behavioral biometric libraries. Single-source vulnerability persists for specialized GPU accelerators. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
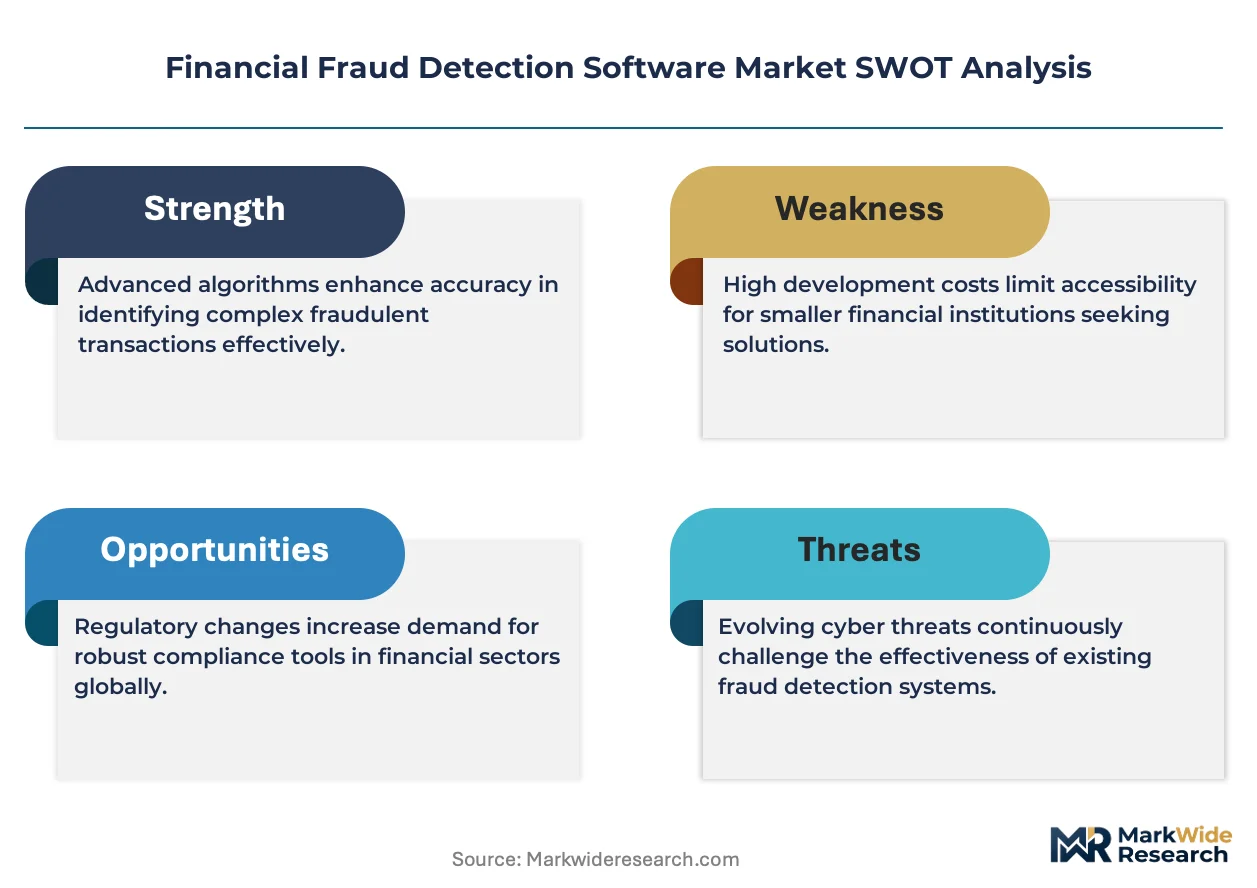
The financial fraud detection software market is accelerating through a regulatory inflection as the EU AI Act and SEC model risk guidance force wholesale replacement of opaque legacy systems with auditable platforms.
For Market Incumbents: Pre-empt cloud-native challengers by embedding transaction monitoring directly into core banking rails through API-first architectures. Invest in explainability tooling to defend against regulatory examination failures. Acquire behavioral biometric specialists to close synthetic identity detection gaps before fintech entrants capture embedded finance white space. For New Entrants and Emerging Players: Establish a beachhead in the mid-tier credit union segment where legacy system fatigue outpaces IT modernization budgets. Target white-label fraud detection services for non-bank lending platforms lacking native expertise. Lead with SaaS pricing transparency and rapid deployment timelines that contrast with incumbent implementation cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms combining detection, case management, and regulatory reporting into unified stacks. Long-term viability hinges on data network effects from cross-institutional consortium models. Monitor FedNow adoption velocity as the signal for real-time scoring infrastructure demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies detection, case management, and FinCEN reporting into single audit trails for SEC examinations. |
| Acquisition of Specialist Firm | Captures behavioral biometric IP to counter synthetic identity rings exploiting fragmented credit bureaus. |
| Strategic Partnership | Forms consortium-based detection networks across U.S.-Mexico-Philippines remittance corridors. |
| Geographic Expansion | Establishes EU AI Act-compliant engineering presence to serve BaFin-regulated Mittelstand banks. |
| Product Launch | Deploys quantum-resistant identity verification ahead of NIST post-quantum cryptography mandates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC enforcement actions, EU AI Act technical documentation, and hyperscaler infrastructure disclosures. Chief technology officers at tier-one banks, fraud operations directors at payment processors, regulatory compliance leads at multinational institutions, and integration specialists at core banking vendors provided structured input. Bottom-up transaction volume estimates triangulate against top-down IT spending allocations across the analysis window.
Forecast inputs span deployment model, organization size tier, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derive from segmented growth rate blending across machine learning, rule-based, and predictive analytics technology types. Model retraining frequency, cloud infrastructure expansion trajectories, and synthetic identity incident rates inform projection sensitivity.
Stress conditions across FedNow adoption velocity, EU AI Act enforcement intensity, and data-science talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and cloud migration pacing. Material shifts in SEC model risk management guidance or NIST post-quantum standard acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
MENA Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
Germany AI in Fintech Market
FinTech
Global Saas Spend Management Software Market
FinTech
Singapore Fintech Market
FinTech
China Fintech Market
FinTech
Robo-Advisory Services Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Financial Cloud Market
FinTech
Europe Fintech Market
FinTech
Account Checking Software Market
FinTech
Netherlands AI in Fintech Market
FinTech
Smart Finance Connectivity Market
FinTech
Saudi Arabia Fintech Market
FinTech
Financial App Market
FinTech
United Kingdom AI in Fintech Market