
 Finance Cloud Market | 2026-2036
Finance Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Finance Cloud Market Intelligence
The historical scarcity of certified cloud compliance engineers is unwinding as training programs and platform-native tools simplify deployment. Amazon Web Services leverages its vast infrastructure to support large-scale banking transformations. Microsoft positions its Azure platform with a strong focus on security and compliance for risk-averse financial institutions. Oracle specializes in enterprise-grade financial applications and database solutions migrated to its cloud infrastructure.
Finance cloud refers to a suite of cloud computing services, including IaaS and PaaS, specifically designed for the financial services industry. These platforms provide secure, scalable infrastructure for applications requiring high-transaction throughput and strict data residency controls. Across deployment models, hybrid cloud architectures are favored by established banks balancing legacy system security with public cloud agility. Among solution types, demand for AI-powered fraud detection is accelerating, driven by efficiency mandates.
Regulatory frameworks including the SEC's cybersecurity rules in the United States, the EU's GDPR, and China's data security laws dictate stringent protection and residency requirements. Adherence to standards like ISO 27001 is a prerequisite for vendors, shaping platform architecture and security protocols. Vendor selection increasingly depends on the ability to demonstrate auditable compliance and provide tools for managing complex cross-border data governance.
Market Dynamics
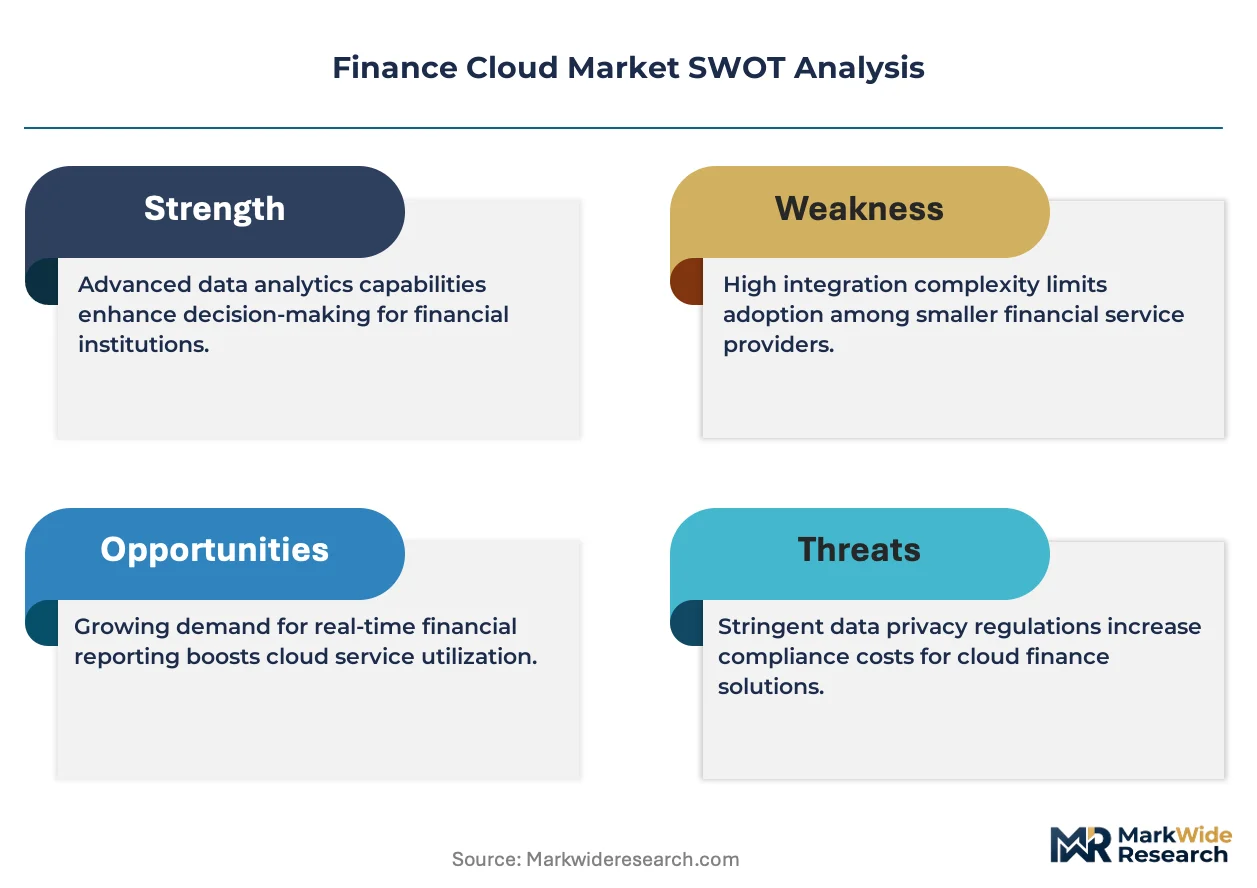
The central structural force shaping the finance cloud market is the dual pressure from regulatory mandates for data residency and the business imperative for scalable, AI-driven analytics, compelling a shift from on-premise systems to specialized cloud platforms.
Growth Catalysts
- AI-Driven Analytics:Demand from investment advisors and hedge funds for AI-powered risk management and algorithmic trading models accelerates the adoption of high-performance computing capabilities available on specialized cloud platforms.
- Regulatory Mandates:The European Union's GDPR and China's data security laws compel financial institutions to adopt cloud solutions that feature advanced, auditable data residency and governance controls.
- Fintech Proliferation:The expansion of fintech startups, particularly in payment processing and digital lending, creates a significant addressable market for scalable IaaS and PaaS solutions that lower barriers to market entry.
Market Restraints
- Data Sovereignty Costs:Strict data residency laws in jurisdictions like China and parts of the EU increase operational complexity and cost, often requiring separate, localized cloud infrastructure deployments for multinational banks.
- Legacy System Integration:The high cost and technical difficulty of migrating decades-old core banking systems, such as mainframes, to modern cloud architectures slows adoption among large, established financial institutions.
- Vendor Concentration:The market's dependence on a small number of hyperscale cloud providers creates pricing power and significant vendor lock-in risks, limiting negotiating leverage for financial services clients.
Strategic Opportunities
- Decentralized Finance Infrastructure:Providing secure and compliant cloud infrastructure for emerging Decentralized Finance (DeFi) applications and other blockchain-based financial services represents a significant new growth vector.
- Emerging Market Modernization:Supporting the digital transformation of banking sectors in underpenetrated markets across Southeast Asia and Latin America offers substantial expansion potential for cloud service providers.
- ESG Reporting Solutions:Developing specialized cloud platforms for Environmental, Social, and Governance (ESG) data aggregation, analytics, and reporting helps financial firms meet new disclosure requirements.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers with dual expertise in financial compliance frameworks and complex multi-cloud architecture management hinders project timelines for large-scale banking transformations.
- Cross-Border Audit Complexity:Demonstrating auditable compliance with conflicting or overlapping data protection regulations, such as the SEC's cybersecurity rules and the EU's GDPR, is a major operational burden for global firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finance Cloud Market |
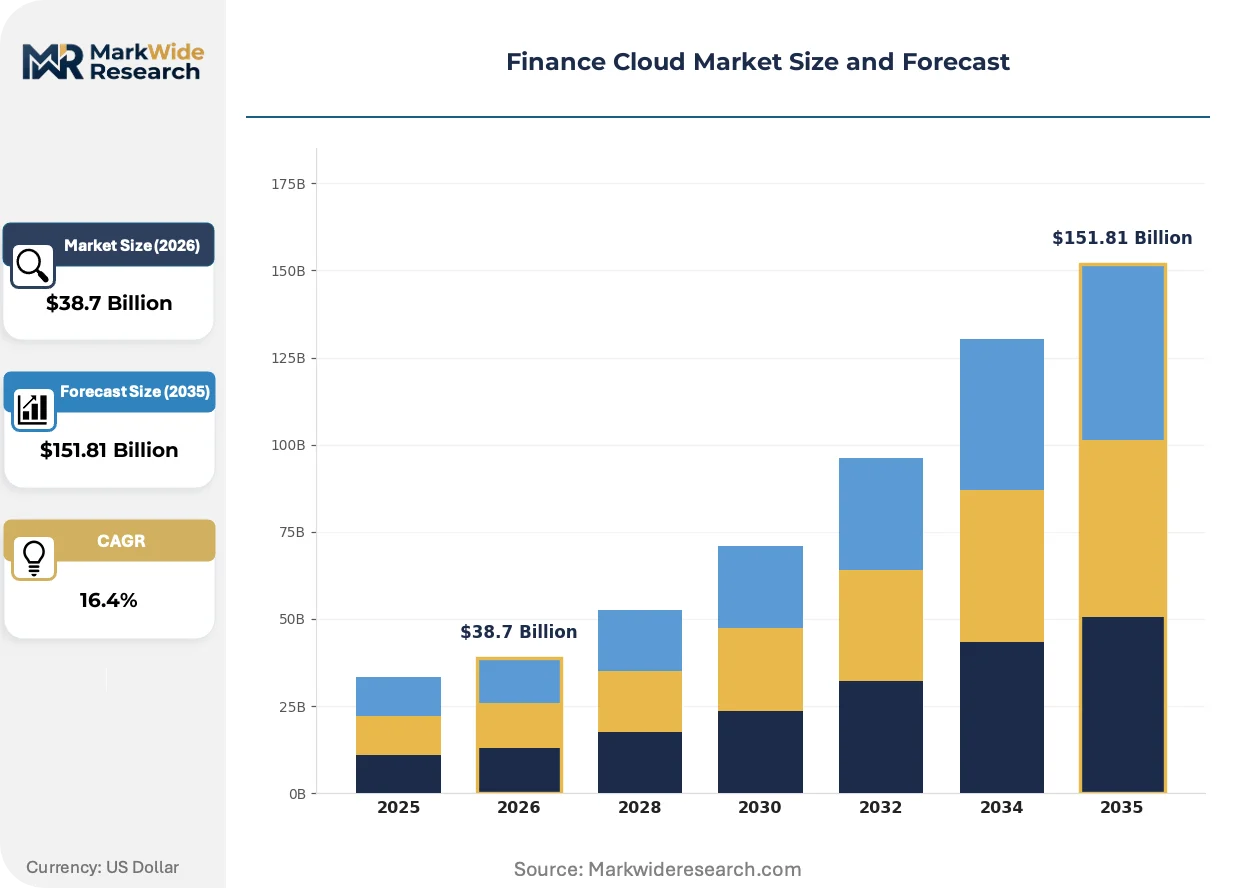
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Risk Management, Payment Processing, Loan Management, Fraud Detection, Accounting Automation End User: Banks, Insurance Firms, Investment Advisors, Credit Unions, Fintech Startups Pricing Model: Subscription, Pay-As-You-Go, Freemium, Tiered Pricing |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Oracle, Salesforce, SAP, Acumatica, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finance Cloud Market Strategic Shifts & Innovations
The market is being redefined by the convergence of enterprise-grade security and developer-centric agility. Financial institutions are moving beyond basic infrastructure migration to adopt platform-native tools for advanced analytics and automated compliance, fundamentally altering vendor selection criteria.
Containerization technologies like Kubernetes provide a standardized way to package and run applications across different computing environments. Fintech startups and innovation labs within large banks are rapidly adopting containers to accelerate development cycles and improve application portability. This architectural approach is displacing monolithic application designs, which are tied to specific on-premise hardware and are significantly slower to update or scale.
The European Union's General Data Protection Regulation (GDPR) imposes strict controls on personal data processing and requires a legal basis for cross-border transfers. This regulation forces cloud providers to build data centers within the EU and offer sophisticated data governance tools to manage residency. US-based financial firms operating in Europe are most affected, now prioritizing vendors with demonstrable GDPR compliance and local data processing capabilities.
A shift from fixed-capacity contracts to consumption-based pricing models for cloud services is gaining traction. This model disrupts traditional IT budgeting by allowing firms to pay only for the compute, storage, and network resources they actually use, replacing long-term hardware procurement cycles. The trend is most visible among investment management firms in the United States, where computational needs for algorithmic trading and risk modeling can fluctuate dramatically.
Finance Cloud Market Segmentation
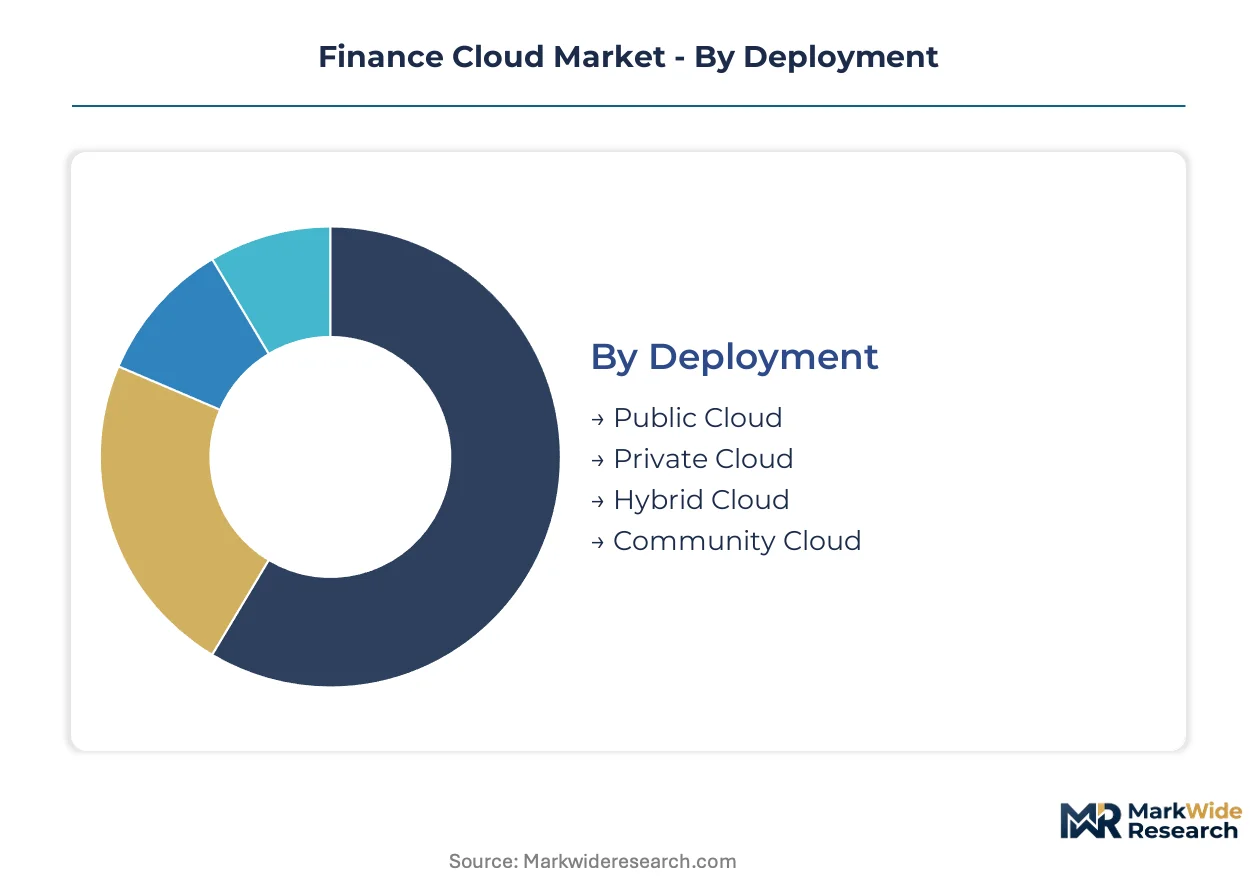
The finance cloud market segmentation provides a granular view of how diverse operational needs and strategic priorities influence technology adoption. This breakdown highlights the specific solutions, deployment models, and user segments driving innovation and investment. Understanding these distinctions is critical for providers tailoring offerings to a complex and highly regulated industry.
Deployment:
Regulatory compliance and data sovereignty requirements fundamentally differentiate deployment model preferences across the finance cloud market.
- Hybrid Cloud:This model integrates private infrastructure with public cloud services, allowing financial institutions to maintain sensitive data on-premise while leveraging public cloud for less critical workloads. Established banks in Germany and France favor Hybrid Cloud for balancing legacy system security with public cloud agility.
- Private Cloud:Dedicated cloud infrastructure, either on-premise or hosted by a third party, provides maximum control, security, and compliance for highly sensitive financial data and applications. Large investment banks in the United States utilize Private Cloud environments for their core trading platforms and proprietary algorithms.
- Public Cloud:Services delivered over the public internet by third-party providers offer scalability and cost efficiency, suitable for non-critical applications or development environments. Fintech startups often leverage Public Cloud for rapid prototyping and market entry due to its elasticity.
- Community Cloud:Shared cloud infrastructure among specific organizations with common concerns, such as regulatory compliance, offers a collaborative yet secure environment. This model serves niche financial consortia or regional banking groups for shared data analytics.
Established volume favors Hybrid Cloud deployments; emerging adoption represents the fastest-growing trajectory for Public Cloud for specific, less sensitive workloads.
Solution Type:
The functional applications within finance cloud solutions address distinct operational challenges and strategic objectives for financial institutions.
- Fraud Detection:These AI-powered solutions analyze transaction data in real-time to identify and prevent fraudulent activities, enhancing security and reducing financial losses. Banks in the United Kingdom deploy advanced Fraud Detection platforms to comply with anti-money laundering regulations and protect customer assets.
- Risk Management:Cloud-based platforms provide advanced analytical capabilities for assessing market, credit, and operational risks, crucial for compliance and strategic decision-making. Investment advisors in the United States use these tools for scenario modeling and portfolio optimization.
- Payment Processing:Cloud infrastructure supports high-volume, secure transaction processing, facilitating digital payments and international remittances for financial institutions. Modern payment gateways rely on cloud-native architectures for resilience.
- Loan Management:Solutions automate the entire loan lifecycle from application to servicing, improving efficiency and reducing processing times for lenders. Digital lending platforms leverage cloud for rapid scaling.
- Accounting Automation:Cloud platforms streamline financial reporting, general ledger management, and reconciliation processes, enhancing accuracy and reducing manual effort. Enterprise resource planning systems integrate cloud accounting modules for real-time data access.
Efficiency mandates drive demand for Fraud Detection solutions, while core banking transformation elevates Payment Processing.
End User:
Distinct operational scales and innovation priorities among financial institutions shape their specific requirements for cloud-based services.
- Banks:Large, established financial institutions migrate core operations and data analytics to the cloud, seeking scalability, cost optimization, and enhanced security. Major banks in Singapore are investing in cloud for digital transformation initiatives and customer experience improvements.
- Fintech Startups:Agile new entrants leverage cloud platforms for rapid development, deployment, and scaling of innovative financial products and services. Digital lenders in Brazil depend on cloud infrastructure to manage their dynamic customer bases and transaction volumes.
- Insurance Firms:Cloud adoption supports data-intensive tasks like actuarial modeling, claims processing, and personalized policy management for insurance providers. Insurers in Canada use cloud for disaster recovery and business continuity.
- Investment Advisors:These firms utilize cloud for high-performance computing, algorithmic trading, and advanced analytics to gain market insights and manage client portfolios. Hedge funds in Switzerland rely on cloud for complex quantitative analysis.
- Credit Unions:Smaller, member-focused financial cooperatives adopt cloud for cost-effective IT infrastructure, digital banking services, and improved member engagement. Regional credit unions in Australia use cloud for secure data storage and member portals.
Large institutions prioritize robust security, while agile startups seek rapid deployment and cost efficiency.
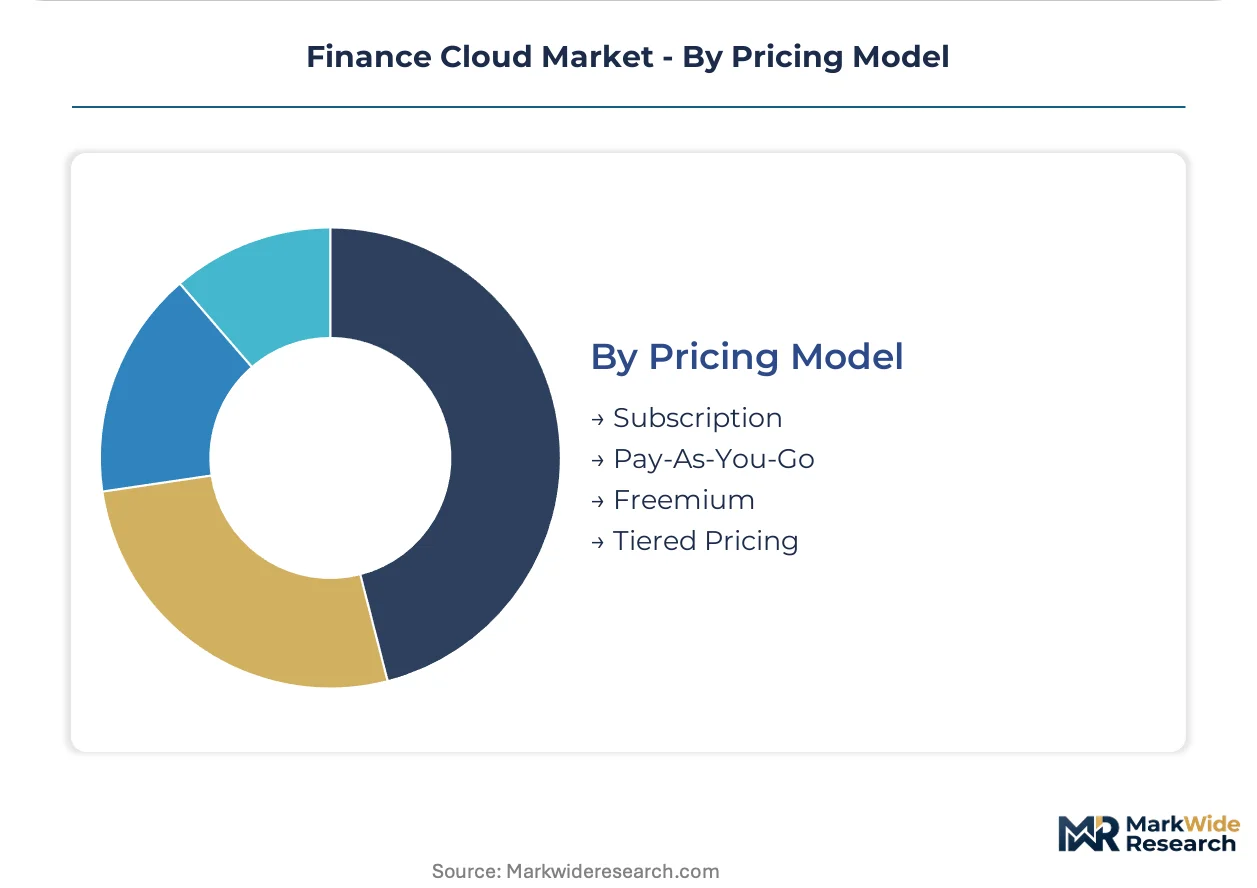
Pricing Model:
Different pricing structures reflect varying financial strategies and operational budget considerations for finance cloud consumers.
- Pay-As-You-Go:This consumption-based model charges users only for the compute, storage, and network resources actually utilized, offering high flexibility and cost efficiency. Investment management firms in the United States frequently use Pay-As-You-Go for fluctuating algorithmic trading workloads.
- Subscription:Users pay a fixed recurring fee for access to a set of cloud services and resources, providing predictable budgeting and often bundled features. Small to mid-sized banks in the Netherlands opt for Subscription models for their core banking software-as-a-service.
- Freemium:A basic version of the service is offered for free, with advanced features or higher usage tiers requiring payment, attracting new users. Some fintech platforms use Freemium models to onboard early users for their personal finance tools.
- Tiered Pricing:Services are offered in different packages or levels, each with varying features, performance, and price points, catering to diverse customer needs. Cloud providers offer Tiered Pricing for data storage, ranging from archival to high-speed access.
Predictable budgeting drives Subscription model adoption, while dynamic workloads prefer Pay-As-You-Go flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between established financial centers and emerging markets, influencing cloud adoption. Developed economies often face higher compliance costs, while developing regions prioritize scalable, cost-efficient infrastructure for rapid digital transformation. This dynamic shapes vendor strategies and localized service offerings.
United States
Investment advisors and hedge funds drive significant demand for AI-powered risk management and algorithmic trading capabilities. The SEC's cybersecurity rules compel financial institutions to enhance their cloud security postures and data protection. New York City's financial district remains a primary hub for these advanced cloud-based financial services.
United Kingdom
Banks in the United Kingdom deploy advanced fraud detection platforms to comply with anti-money laundering regulations and protect customer assets. GDPR requirements continue to influence data residency and governance controls for financial cloud providers. London's vibrant fintech ecosystem fosters rapid adoption of scalable IaaS and PaaS solutions.
Germany
Established banks in Germany favor hybrid cloud deployments to balance legacy system security with public cloud agility. The European Union's GDPR mandates stringent data protection and residency requirements for all financial data. Frankfurt's banking sector actively integrates cloud solutions for core operations and risk assessment.
Singapore
Major banks in Singapore are investing in cloud for digital transformation initiatives and customer experience improvements. The Monetary Authority of Singapore (MAS) regulations guide secure cloud adoption and data management practices within the financial sector. Singapore's central business district sees concentrated demand for cloud-native banking solutions.
China
Fintech startups and large financial institutions seek scalable IaaS and PaaS solutions for payment processing and digital lending. China's data security laws dictate strict data residency and localization requirements for cloud infrastructure. Shanghai's financial free trade zone promotes localized cloud deployments for domestic and international firms.
Finance Cloud Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the finance cloud market. The market structure is concentrated among hyperscale cloud providers, but specialized fintech solution developers contribute to fragmentation in niche areas. Strategic partnerships with fintechs and portfolio diversification into AI-driven analytics are dominant competitive moves.
Among hyperscale cloud providers, Amazon Web Services and Microsoft exemplify the broad infrastructure and platform offerings for banking transformations. These entities provide extensive computing resources and secure environments for financial operations. Oracle, with its enterprise-grade financial applications, represents the archetype of a legacy software vendor migrating specialized solutions to cloud infrastructure, focusing on database and application services.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Oracle |
| Salesforce |
| SAP |
| Acumatica |
| Cisco Systems |
| Others |
Cost & Logistics Intelligence
On-premise infrastructure's substitution by cloud services reshapes the supply geography of data centers and compute resources, directly influencing pricing economics. This shift from capital expenditure to operational expenditure alters financial institutions' budgeting approaches and vendor dependencies.
Pricing Analysis
Geographic price-spreads for finance cloud services exist, influenced by regional data residency requirements and local market competition. Pay-As-You-Go models and subscription services dominate the market, offering flexibility or predictable budgeting. Price differentiation stems from customization levels for enterprise clients and specific compliance certifications. Pricing softness reflects intense competition among hyperscale providers. Fintech startups demonstrate the highest price sensitivity, contrasting with large investment banks.
Supply Chain Analysis
Just-in-time resource provisioning characterizes the finance cloud supply chain, allowing for dynamic scaling rather than strategic stockpiling of physical infrastructure. Supply concentration centers on the United States, with significant data center infrastructure in Europe and China to meet data residency demands. The ecosystem relies on data center hardware, specialized software, and certified cloud compliance engineers. Vendor concentration among hyperscalers presents a structural risk. Distribution runs through direct sales channels and specialized channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The finance cloud market is experiencing a buyer-power shift as financial institutions consolidate their spending with a limited number of hyperscale providers. This consolidation creates dependencies, influencing long-term vendor relationships.
For Market Incumbents: Secure deep integration capabilities with legacy core banking systems to counter the agility of emerging fintech startups. Investment in platform-native compliance tools and advanced security certifications like ISO 27001 reinforces trust. Diversifying cloud deployments across multiple hyperscalers can mitigate vendor lock-in risks.
For New Entrants and Emerging Players: Anchor in specialized niches like compliant infrastructure for Decentralized Finance (DeFi) or robust ESG reporting solutions. The most penetrable segment remains underpenetrated markets across Southeast Asia and Latin America. A go-to-market angle focusing on tailored, cost-efficient cloud platforms can attract regional banks and fintechs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed fintech infrastructure providers demonstrating strong compliance capabilities. The long-term viability of finance cloud solutions remains robust, driven by ongoing digital transformation. Acquisition targets include specialized AI-powered fraud detection platforms and data governance software companies. Regulatory clarity on cross-border data transfers serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Native Compliance Tool Development | This enhances security and automates adherence to complex financial regulations like GDPR. |
| Geographic Data Center Expansion | This addresses data residency mandates in key regions, reducing cross-border audit complexity. |
| AI-Powered Risk Management Integration | This provides advanced analytics for investment advisors, optimizing portfolio performance and fraud detection. |
| Strategic Partnership with Fintech Innovators | This accelerates the adoption of scalable IaaS and PaaS solutions for payment processing and digital lending. |
| Talent Development in Cloud Compliance Engineering | This mitigates the scarcity of specialized expertise, supporting large-scale banking transformations. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and rigorous secondary validation. Senior financial institution CTOs, risk officers, compliance heads, and fintech founders provided deep market insights. Secondary sources included SEC filings, central bank reports, hyperscale cloud provider whitepapers, and regulatory guidance from the EU and China. This approach utilized both bottom-up and top-down triangulation for comprehensive data integrity.
The forecasting window extended over the projection horizon, integrating quantitative modeling with qualitative insights from market experts. Segmentation dimensions modeled included deployment architecture, solution type, end-user categories, and pricing models. Compound Annual Growth Rates were derived through a combination of regression analysis and expert consensus. Key industry-specific inputs included projected financial transaction volumes and evolving regulatory compliance costs.
Decision-makers should treat outputs as directional under base assumptions of a stable regulatory environment and sustained cloud technology advancements. Major cybersecurity breaches or abrupt shifts in data sovereignty laws pose notable forecast risks. Revision becomes warranted when new regulatory frameworks cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Latin America Fintech Market
FinTech
Global Saas Spend Management Software Market
FinTech
Autonomous Finance Market
FinTech
China Fintech Market
FinTech
Germany Fintech Market
FinTech
Financial Management Software Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Transaction Monitoring Software Market
FinTech
Japan AI in Fintech Market
FinTech
Micro-Investing Platform Market
FinTech
Decentralized Finance Technology Market
FinTech
Fintech Crisis Management Market
FinTech
Asia-Pacific Fintech Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Singapore Fintech Market
FinTech
Automotive Fintech Market