
 Asia-Pacific Financial Analytics Market | 2026-2036
Asia-Pacific Financial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Financial Analytics Market Analytics
Real-time streaming data architectures are reshaping how financial institutions process transactional intelligence across the Asia-Pacific. TIBCO Software leverages event-driven analytics to sustain low-latency decisioning for capital markets clients. SAP SE anchors enterprise resource planning integrations that dominate treasury analytics workflows in regional banking hubs. Oracle Corporation competes through database-native analytics that extend cloud infrastructure control across multi-jurisdictional deployments.
Financial analytics encompasses quantitative methods, statistical modeling, and computational algorithms applied to structured and unstructured financial data, operating through SQL-based querying, machine learning pipelines, and API-connected data lakes to generate actionable intelligence for investment, risk, and compliance functions. Cloud-based deployment leads segment expansion as institutions migrate from legacy on-premise installations to elastic compute environments managed through distributed ledger integrations and containerized microservices. Predictive analytics solutions command premium positioning within the solution architecture, while fraud detection applications absorb disproportionate R&D allocation as regulatory scrutiny intensifies across digital payment corridors.
India's RBI, Australia's APRA, and Singapore's MAS enforce divergent data localization mandates that fragment cloud architecture standards and inflate compliance tooling expenditure for cross-border operators. The EU AI Act's extraterritorial reach into Asia-Pacific financial services exports further complicates algorithmic transparency requirements for predictive models deployed in wealth management. Stakeholders must monitor evolving sandcastle frameworks from Hong Kong's FSTB and Japan's FSA to anticipate where regulatory arbitrage opportunities will open for analytics platform providers.
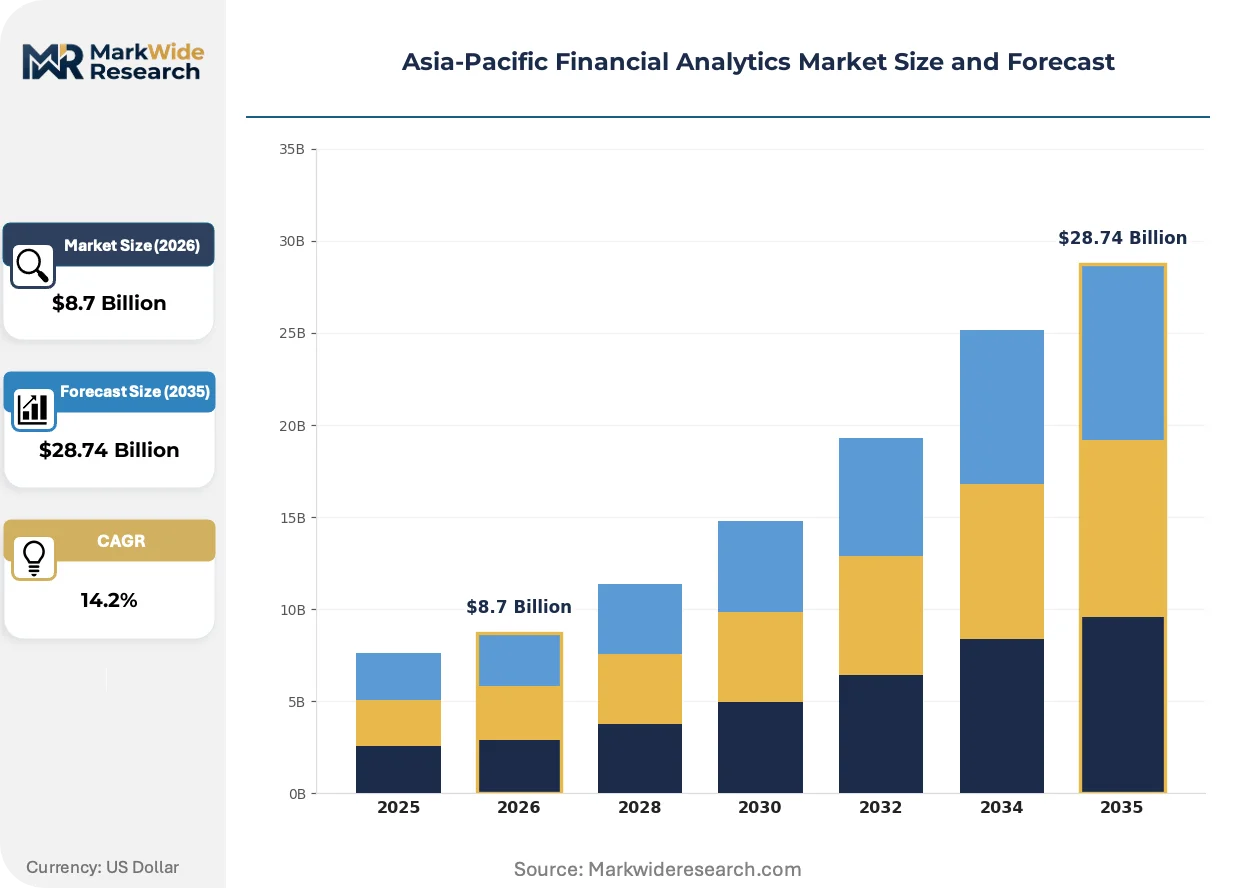
Market Dynamics
Real-time data streaming architectures are forcing a fundamental reconfiguration of how Asia-Pacific financial institutions deploy capital toward analytics infrastructure. Singapore's MAS and India's RBI are accelerating compliance mandates that privilege low-latency risk computation over batch-processed reporting.
Growth Catalysts
- Data Localization Mandates:Singapore's MAS and India's RBI require domestic data residency for transactional records. Financial institutions must deploy localized analytics clusters, expanding addressable infrastructure spend across both markets.
- Superannuation Analytics:Australia's APRA mandates granular portfolio stress-testing for superannuation funds. This institutional obligation sustains demand for predictive modeling platforms calibrated to retirement liability projections.
- Event-Driven Architectures:Capital markets firms across Hong Kong and Tokyo are replacing batch ETL pipelines with streaming data fabrics. Low-latency fraud detection and algorithmic trading execution now require sub-millisecond analytics ingestion.
Market Restraints
- Cloud Fragmentation Costs:Divergent data localization rules across India, Australia, and Singapore prevent unified multi-tenant cloud deployments. Cross-border operators must maintain redundant infrastructure stacks, inflating total cost of ownership.
- Specialized Talent Scarcity:Quantitative risk modelers with regulatory domain expertise command premium compensation in Singapore and Sydney. Regional banks face recruitment competition from global technology firms establishing APAC hubs.
- Legacy System Entrenchment:Core banking platforms running COBOL-based transaction engines resist API-native analytics integration. Mainframe dependency constrains real-time data pipeline deployment at major institutional incumbents.
Strategic Opportunities
- Vietnam's Underpenetrated Banking Sector:State Bank of Vietnam regulations are liberalizing foreign cloud provider access. Early entrants can establish analytics platform standards before domestic champions consolidate market position.
- Regulatory Sandbox Access:Hong Kong's FSTB and Japan's FSA operate supervised testing environments for AI-driven credit scoring. Approved participants gain accelerated path to production deployment with reduced compliance friction.
- ESG Disclosure Convergence:Australia's mandatory climate risk reporting and Singapore's green finance taxonomy are creating demand for sustainability-linked analytics modules. Asset managers require carbon footprint attribution tools for portfolio construction.
Industry Challenges
- Model Explainability Requirements:Singapore's MAS and India's RBI mandate interpretability documentation for algorithmic credit decisions. Engineering teams must retrofit black-box machine learning pipelines with SHAP-value or LIME-based transparency layers.
- Cross-Border Data Governance:Australia's Privacy Act and India's Digital Personal Data Protection Act impose conflicting consent frameworks. Regional wealth managers face operational complexity when unifying client analytics across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Financial Analytics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, Managed Services End User: BFSI, Retail, Telecommunications, Healthcare Solution: Dashboarding, Reporting, Predictive Analytics, Risk Management Application: Cash Flow Analysis, Fraud Detection, Financial Planning, Investment Analysis |
| Companies Covered | TIBCO Software, SAP SE, Oracle Corporation, Microsoft Corporation, IBM Corporation, Teradata Corporation, Tableau Software, QlikTech International AB, Alteryx, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Financial Analytics Market Evolving Landscape
Generative AI capabilities are penetrating risk modeling workflows across Asia-Pacific banking institutions. Natural language interfaces for querying structured financial data are compressing analyst training cycles.
Graph neural networks for anti-money laundering detection is hybridizing supervised learning with network topology analysis. Major transaction banks in Singapore and Hong Kong are piloting these systems for correspondent banking surveillance. The technology is hybridizing rule-based threshold alerts with relationship-pattern inference, reducing false-positive rates while maintaining regulatory defensibility.
Singapore's MAS has issued specific guidance on responsible AI use in financial services, including mandatory fairness testing for credit allocation algorithms. The framework requires documented bias audits before production deployment of predictive models. Wealth management platforms serving high-net-worth clients across Southeast Asia are restructuring model governance committees to satisfy these procedural obligations.
Subscription-based analytics procurement is displacing perpetual license arrangements at regional insurance conglomerates. Chief data officers in Sydney and Mumbai now favor consumption-priced cloud warehouses over capital-intensive on-premise deployments. This shift is most visible among mid-tier general insurers modernizing actuarial reserving capabilities.
Asia-Pacific Financial Analytics Market Segmentation
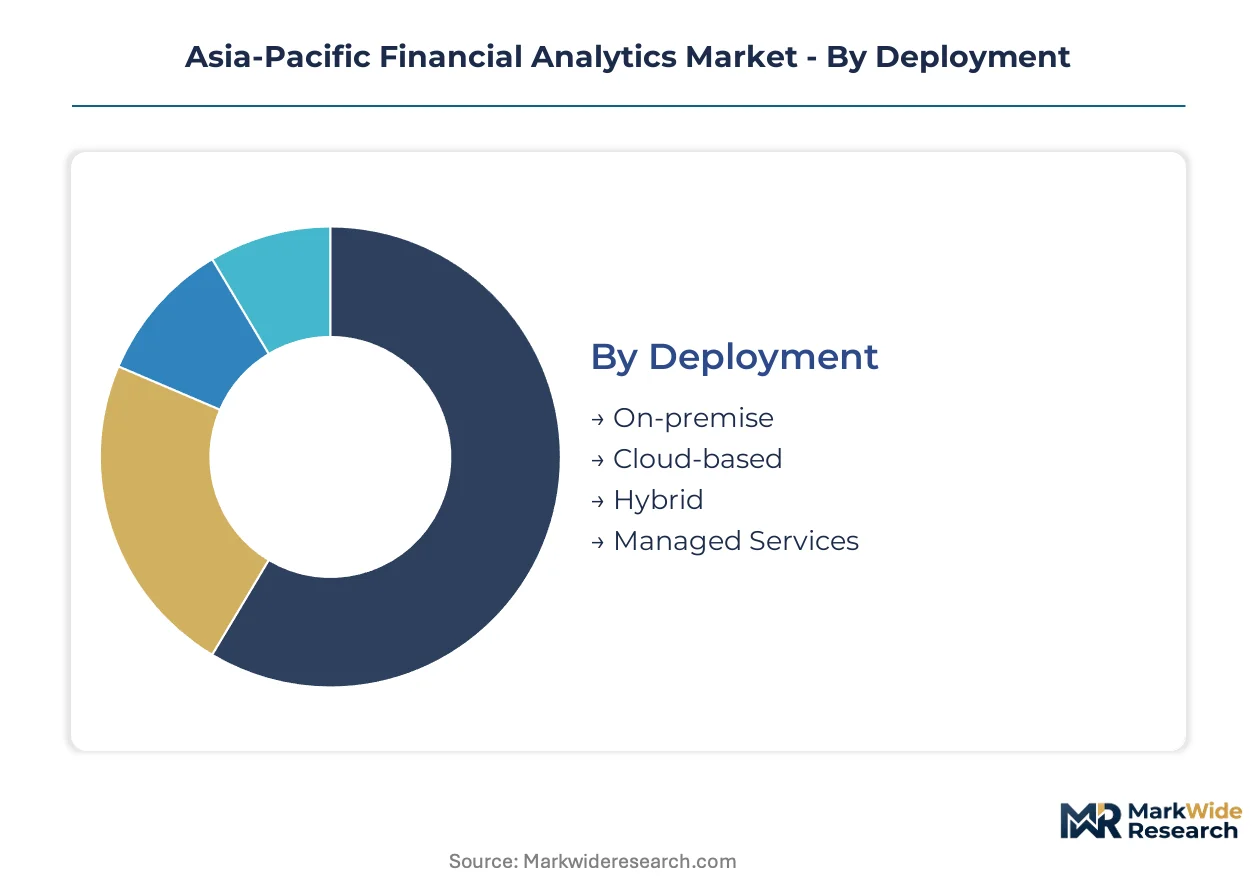
Financial analytics deployment patterns across Asia-Pacific reflect divergent regulatory maturity and infrastructure legacy. Institutions calibrate architecture choices against data sovereignty mandates from Singapore's MAS, India's RBI, and Australia's APRA.
Deployment:
Cost tier determines how institutions balance capital expenditure against operational flexibility across regulatory jurisdictions.
- Cloud-based:Elastic compute environments enable real-time scaling for transaction volumes during market volatility. Singapore's wealth managers and Australia's superannuation funds prioritize this model to satisfy MAS and APRA data residency rules without maintaining physical infrastructure.
- On-premise:Dedicated hardware installations retain full data custody within institutional firewalls. India's largest public sector banks favor this architecture to comply with RBI's strictest localization mandates for core banking transaction records.
- Hybrid:Workload-splitting between private data centers and public cloud partitions sensitive from general processing. Regional insurers use this approach for actuarial modeling that touches both regulated reserves and exploratory analytics.
- Managed Services:Third-party operators assume infrastructure maintenance and compliance documentation burdens. Mid-tier banks in Vietnam and the Philippines contract these arrangements to bypass internal capability gaps.
On-premise systems command the established base. The steepest expansion runs through cloud-based deployment.
End User:
Application intensity varies sharply across customer type, with regulatory pressure and transaction complexity driving differential analytics investment.
- BFSI:Banking, financial services, and insurance institutions deploy the most sophisticated risk engines. Capital adequacy calculations, stress-testing protocols, and anti-money laundering surveillance consume the majority of regional analytics infrastructure spend.
- Retail:Consumer-facing merchants leverage transaction pattern analysis for inventory financing and customer lifetime value scoring. Point-of-sale data feeds into working capital optimization tools.
- Telecommunications:Mobile network operators apply churn prediction and revenue assurance algorithms to prepaid subscriber bases. Payment platform integration creates financial data streams requiring dedicated analytics.
- Healthcare:Hospital networks and pharmaceutical distributors use cost accounting and claims analytics to manage reimbursement complexity. Regulatory pricing transparency mandates accelerate adoption.
BFSI anchors current revenue concentration. Retail exhibits the most rapid adoption trajectory among non-financial verticals.
Solution:
Functional maturity separates visualization tools from algorithmic engines in procurement priorities across the region.
- Predictive Analytics:Machine learning pipelines forecast credit defaults, market movements, and operational losses. Singapore's private banks and Australia's pension funds invest heavily here for liability-driven investment strategies.
- Risk Management:Integrated platforms quantify market, credit, and operational risk exposures against regulatory capital requirements. Basel III implementation deadlines sustain demand across ASEAN banking systems.
- Dashboarding:Real-time visualization layers aggregate KPIs for executive decision support. Regional insurance conglomerates modernize legacy reporting through these interfaces.
- Reporting:Structured output generation satisfies periodic regulatory submission obligations. Automated XBRL formatting reduces compliance labor for listed entities.
Reporting solutions retain the largest installed base. Predictive analytics demonstrates the steepest capability investment curve.
Application:
Volume concentration aligns with where transaction intensity and regulatory scrutiny intersect most acutely.
- Fraud Detection:Real-time pattern recognition intercepts payment anomalies before settlement completion. India's UPI transaction surge and Southeast Asia's digital wallet expansion drive continuous model refinement.
- Investment Analysis:Portfolio construction tools optimize asset allocation across multi-asset mandates. Australia's superannuation sector and Singapore's family offices deploy these for retirement liability matching.
- Cash Flow Analysis:Liquidity forecasting models project working capital requirements across supply chain cycles. Corporate treasuries in manufacturing-heavy economies rely on these for FX exposure management.
- Financial Planning:Integrated budgeting and scenario modeling supports strategic resource allocation. Mid-market enterprises adopt cloud-native versions as legacy ERP modules reach end-of-life.
Fraud detection holds the deepest incumbent penetration. Investment analysis is climbing fastest as wealth management digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports financial analytics services and platform expertise to Australian superannuation funds and Indian banking conglomerates, establishing the city-state as the primary trade-flow corridor for risk modeling capabilities across the region.
Singapore
Wealth management digitization and family office proliferation drive analytics infrastructure investment. MAS mandates fairness testing and interpretability documentation for AI-driven credit allocation algorithms. Raffles Place and Marina Bay financial districts host concentrated deployments of real-time risk engines serving Southeast Asian capital markets.
India
Digital payment volume surge through UPI and expanding private banking networks necessitate fraud detection modernization. RBI enforces strict data localization for core banking transaction records and enhanced governance frameworks. Mumbai's Bandra-Kurla Complex and Bangalore's Electronic City anchor domestic analytics development centers for regional banks.
Australia
APRA-mandated granular portfolio stress-testing for superannuation funds sustains demand for predictive liability modeling. Mandatory climate risk reporting creates specialized ESG analytics procurement. Sydney's Barangaroo financial precinct and Melbourne's Docklands concentrate retirement fund technology infrastructure.
Japan
Correspondent banking surveillance requirements and aging demographic liability management drive graph neural network pilots for AML detection. FSA operates supervised sandbox environments for AI credit scoring approval. Tokyo's Otemachi district and Osaka's Umeda financial cluster host major institutional analytics deployments.
Vietnam
State Bank of Vietnam liberalization of foreign cloud provider access opens underpenetrated banking sector modernization. Rapid digital wallet expansion generates transaction data volumes requiring real-time processing. Ho Chi Minh City's District 1 financial district and Hanoi's Cau Giay district attract early analytics platform standard-setting entrants.
Asia-Pacific Financial Analytics Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers. Enterprise software conglomerates with database-native architectures anchor the premium segment, while specialized analytics vendors occupy mid-market positioning. Cloud-native challengers are disrupting perpetual license arrangements with consumption-priced alternatives. Competitive dynamics center on strategic partnerships with regional system integrators and accelerated regulatory sandbox certifications for AI-driven credit scoring modules.
Within the enterprise infrastructure tier, Oracle Corporation and SAP SE exemplify database-anchored platform providers competing through cloud infrastructure control and ERP integration dominance. TIBCO Software occupies a position representing event-driven architecture specialization for capital markets latency requirements. These three entities collectively illustrate how vendor positioning stratifies between generalized enterprise stacks and purpose-built streaming analytics engines.
| Leading Market Players |
|---|
| TIBCO Software |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Teradata Corporation |
| Tableau Software |
| QlikTech International AB |
| Alteryx |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud compute infrastructure across Singapore and Sydney data centers is compressing margins for analytics platform providers while forcing incumbents to bundle professional services with core software subscriptions. This utilization imbalance privileges buyers with multi-year commitment leverage and pressures mid-tier vendors toward managed service transitions.
Pricing Analysis
Legacy perpetual-license pricing for on-premise risk engines sits at substantial discount to cloud-native subscription tiers, while next-generation generative AI-augmented analytics commands premium positioning. The dominant model is consumption-priced SaaS with three-tier pricing structure across premium, standard, and economy levels differentiated by data volume thresholds and model complexity. Price differentiation rests on regulatory certification depth—MAS sandbox approval and RBI data localization compliance carry material premiums. Pricing pressure stems from hyperscaler entry into financial services verticals with subsidized compute bundles. Tier-two regional banks exhibit highest price sensitivity; Singapore family offices and Australian superannuation funds demonstrate lowest.
Supply Chain Analysis
Export control regimes limiting advanced GPU and quantum-analytics technology flows to Chinese financial institutions are fragmenting vendor access across the Asia-Pacific. Supply concentrates in United States cloud infrastructure providers, Indian software development centers, and Singapore-based system integrators. Raw material dependencies include specialized semiconductor hardware, proprietary risk model libraries, and regulatory compliance documentation frameworks. Supply chain risk centers on single-source vulnerability for low-latency streaming data fabrics essential to Tokyo and Hong Kong capital markets. Distribution runs through regional system integrators with MAS and APRA certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific financial analytics sector is experiencing high-growth disruption as generative AI penetrates risk modeling workflows and MAS fairness-testing mandates restructure procurement criteria.
For Market Incumbents: Entrench through backward integration into specialized GPU infrastructure for low-latency streaming analytics, securing captive supply of compute resources amid hyperscaler competition. Acquire regulatory sandbox certifications from Japan's FSA and Hong Kong's FSTB before next-generation entrants achieve production deployment rights. Deepen vertical integration into model explainability tooling to satisfy RBI and MAS interpretability mandates. For New Entrants and Emerging Players: Pursue Vietnam's underpenetrated banking sector where State Bank of Vietnam liberalization has opened cloud provider access ahead of domestic champion consolidation. Target mid-tier general insurers in Sydney and Mumbai modernizing actuarial reserving through consumption-priced cloud warehouses. Execute through partnership with regional system integrators holding existing APRA and MAS compliance credentials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among event-driven architecture specialists serving capital markets latency requirements. Long-term viability favors vendors with demonstrated regulatory sandbox track records across multiple Asia-Pacific jurisdictions. Acquisition target archetype: cloud-native challengers with MAS-approved AI credit scoring modules. Watch for inflection when India's RBI expands data localization mandates beyond core banking records into wealth management analytics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Certification | Accelerated production deployment with reduced compliance friction from MAS and FSA accelerates revenue recognition timelines. |
| GPU Infrastructure Backward Integration | Captive compute supply insulates margin pressure from hyperscaler subsidized bundling in Singapore and Sydney. |
| Model Explainability Tooling Development | SHAP-value and LIME-based transparency layers satisfy RBI and MAS algorithmic credit decision mandates. |
| Vietnam Market Entry Partnership | Early cloud provider standard-setting before State Bank of Vietnam domestic champion consolidation locks out foreign platforms. |
| ESG Analytics Module Expansion | Australia's mandatory climate risk reporting and Singapore's green finance taxonomy create specialized procurement demand. |
Research Methodology
Two parallel data streams informed the analysis: structured intelligence drawn from MAS regulatory filings, RBI circulars, APRA prudential standards, and hyperscaler financial services vertical disclosures; and unstructured insights from primary interviews with chief data officers at Singapore private banks, quantitative risk heads at Australian superannuation funds, platform engineers at Indian digital payment networks, and regulatory technology leads at Japanese transaction banks. Secondary validation incorporated SEC 10-K software segment disclosures, vendor earnings call transcripts, and cloud infrastructure capex reports. Bottom-up deployment model sizing triangulated against top-down financial services IT spending benchmarks.
Forecast inputs span deployment architecture, end-user vertical, solution functional maturity, and application intensity across the analysis window. Segmentation dimensions modeled include cloud-based versus on-premise versus hybrid infrastructure, BFSI versus retail versus telecommunications end-use, predictive analytics versus risk management versus dashboarding solution types, and fraud detection versus investment analysis application focus. CAGRs derive from regression analysis against historical financial services software adoption curves, adjusted for regulatory mandate acceleration effects and cloud migration velocity differentials by jurisdiction.
Macroeconomic conditions sit as an overlay; deviation in regional interest rate trajectories, currency volatility affecting cross-border data transfer economics, or sovereign debt stress impacting financial institution IT budgets would shift the trajectory. Forecasts reflect documented assumptions regarding MAS and RBI regulatory timeline adherence. Material shifts in AI governance frameworks or data localization mandate scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Robo Advisory Market
FinTech
Saudi Arabia Fintech Market
FinTech
United States Fintech Market
FinTech
Asia-Pacific Fintech Market
FinTech
Supply Chain Finance Market
FinTech
Spain AI in Fintech Market
FinTech
China AI in Fintech Market
FinTech
Financial Technology Fintech Market
FinTech
Malaysia Fintech Market
FinTech
Stock Trading App Market
FinTech
Singapore AI in Fintech Market
FinTech
Finance Cloud Market
FinTech
Generative AI in Fintech Market
FinTech
Canada AI in Fintech Market
FinTech
Global Saas Spend Management Software Market
FinTech
North America Fintech Market