
 China Fintech Market | 2026-2036
China Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
China Fintech Market Analysis
SAMR's antitrust enforcement is repositioning platform economics across China's fintech sector. Ant Group leverages its Alipay ecosystem to sustain dominance in mobile payment infrastructure. Tencent Holdings anchors consumer engagement through WeChat Pay's embedded finance architecture. JD Technology competes in supply-chain financing by controlling merchant data pipelines across its e-commerce network.
China fintech denotes the application of digital technologies to deliver financial services through software platforms, mobile applications, and algorithmic systems, encompassing blockchain settlement protocols, AI-driven credit scoring models, and real-time big data analytics engines that process transaction volumes exceeding conventional banking thresholds. Payment Processing leads service type revenue pools due to ubiquitous QR-code infrastructure, while Wealth Management captures expanding margin pools as mass-affluent households shift savings from property to fund distribution platforms. Lending Solutions specializes in micro-credit origination for underbanked consumers, and Insurance Tech occupies nascent but accelerating growth trajectories through embedded distribution in e-commerce checkout flows.
NMPA licensing requirements and PBoC's digital yuan framework are reshaping capital reserve mandates for third-party payment providers, while MIIT data localization rules constrain cross-border cloud architecture for fintech platforms. Stakeholders must monitor how SAMR's ongoing platform governance reviews redefine permissible scope for financial product cross-selling within super-app environments.
Market Dynamics
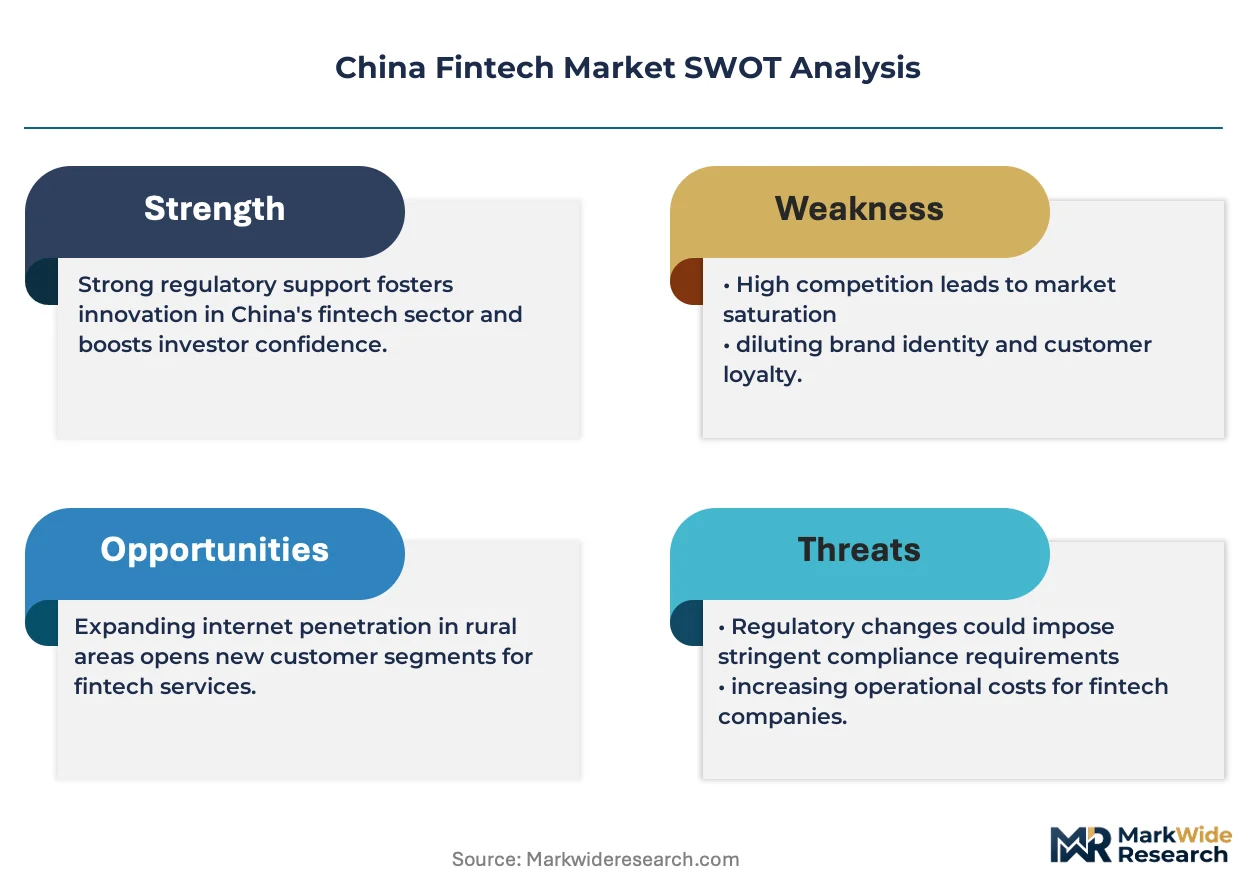
China's fintech sector is undergoing structural compression as SAMR's antitrust enforcement dismantles super-app data monopolies while PBoC's digital yuan infrastructure rewrites payment settlement economics.
Growth Catalysts
- NMPA Licensing Framework:Capital adequacy mandates for non-bank payment processors are filtering out undercapitalized competitors, concentrating transaction flows among compliant platforms in tier-two cities.
- Blockchain Settlement Protocols:Distributed ledger infrastructure is reducing cross-border remittance friction for SME import-export networks operating through Shenzhen and Guangzhou port corridors.
- Mass-Affluent Wealth Migration:Household savings rotation from property to fund distribution platforms is expanding fee-based revenue pools for algorithmic portfolio management services.
Market Restraints
- MIIT Data Localization:Cross-border cloud architecture restrictions are forcing fintech platforms to duplicate infrastructure domestically, raising fixed cost thresholds for foreign-invested entrants.
- Concentrated Credit Scoring Inputs:Alternative data access depends on e-commerce and social platform partnerships controlled by two dominant ecosystem operators.
- Digital Yuan Disintermediation:PBoC's central bank digital currency enables direct liability holding, compressing interchange fee extraction opportunities for third-party wallets.
Strategic Opportunities
- Supply-Chain Financing Integration:Merchant data pipelines from industrial e-commerce networks enable working capital products for underbanked manufacturers in Zhejiang and Jiangsu provinces.
- Embedded Insurance Distribution:Micro-premium products triggered at e-commerce checkout flows remain underdeveloped relative to payment and wealth verticals.
- Dual Carbon Goal Alignment:Green finance taxonomies under MEE guidance create regulatory tailwind for carbon-accounting fintech tools serving corporate treasury functions.
Industry Challenges
- Algorithmic Audit Talent Scarcity:PBoC's model explainability requirements for AI-driven credit scoring outpace domestic supply of compliance engineers with statistical validation expertise.
- Legacy Core Integration:Rural commercial bank partnerships require API bridging to COBOL-based core banking systems, extending implementation timelines for digital lending products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Fintech Market |
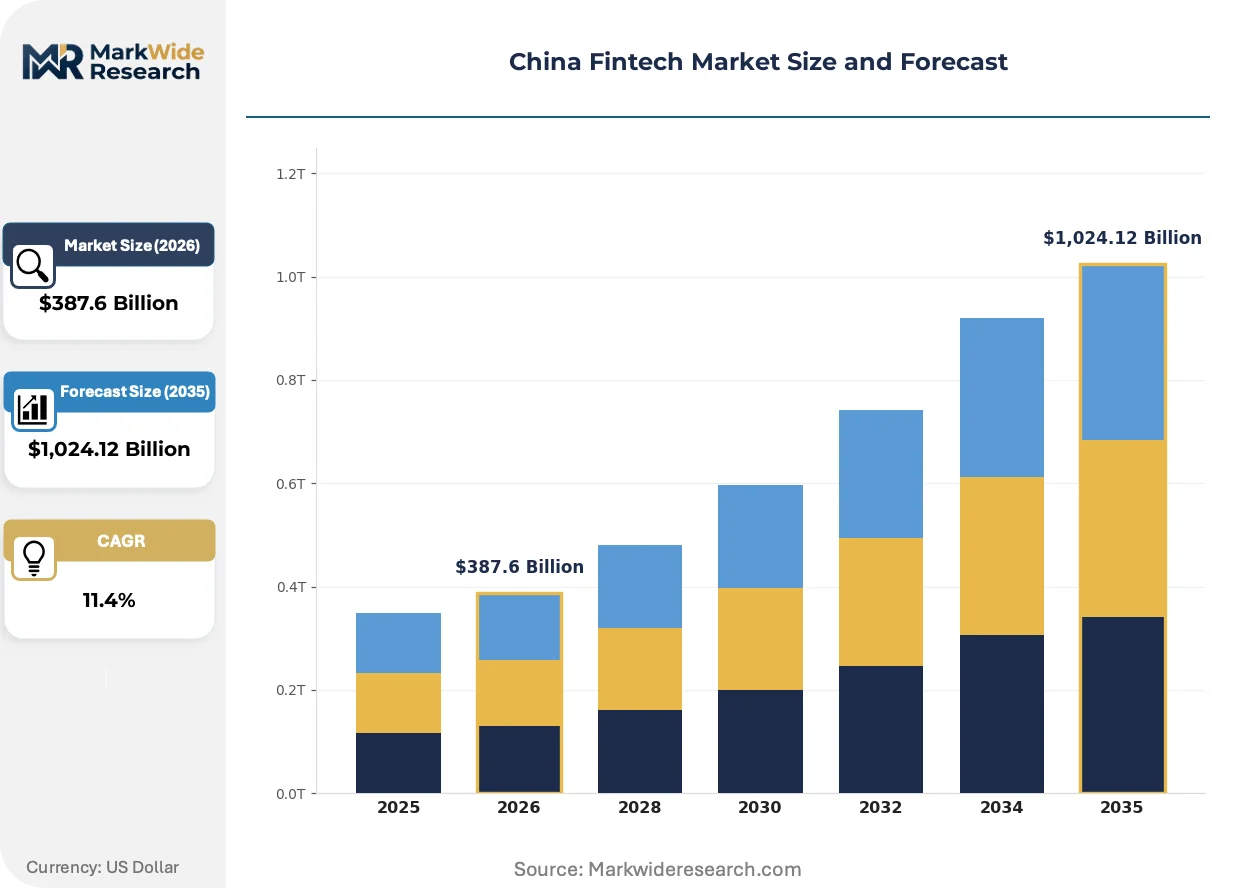
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Wealth Management, Lending Solutions, Insurance Tech Client Type: Consumers, Small Businesses, Enterprises, Financial Institutions Technology: Blockchain, AI, Mobile Payments, Big Data Analytics Delivery Model: On-Demand, Subscription, Freemium, Transaction-Based |
| Companies Covered | Lufax Holding Ltd., Alibaba Group Holding Ltd., Ant Group, Ping An Insurance, China Construction Bank Corporation, Tencent Holdings, JD Technology, China Merchants Bank Co., Ltd., WeBank Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Fintech Market Emerging Trajectories
Technological convergence and regulatory architecture are compressing legacy business models while opening white space for specialized infrastructure providers.
Federated learning architectures for credit scoring are unifying multi-source data analysis without centralizing sensitive personal information. Regional joint-stock banks are piloting these systems to compete with super-app incumbents in consumer lending origination. The technology is unifying previously siloed data cooperatives into shared inference networks that preserve privacy compliance under MIIT guidelines.
SAMR's platform governance reviews are mandating firewalls between payment, credit, and wealth functions within super-app environments. This industrial consequence fragments cross-selling economics that previously subsidized user acquisition costs. Wealth management segments are responding by building standalone app experiences with direct fund house relationships rather than embedded marketplace models.
QR-code payment infrastructure saturation in tier-one cities is rotating merchant acquisition investment toward inland provinces. Payment service providers are deploying agent networks and simplified onboarding flows to capture township-level retail density. This geographic demand rotation favors hardware-light software solutions over proprietary terminal deployments that dominated coastal market entry strategies.
China Fintech Market Segmentation
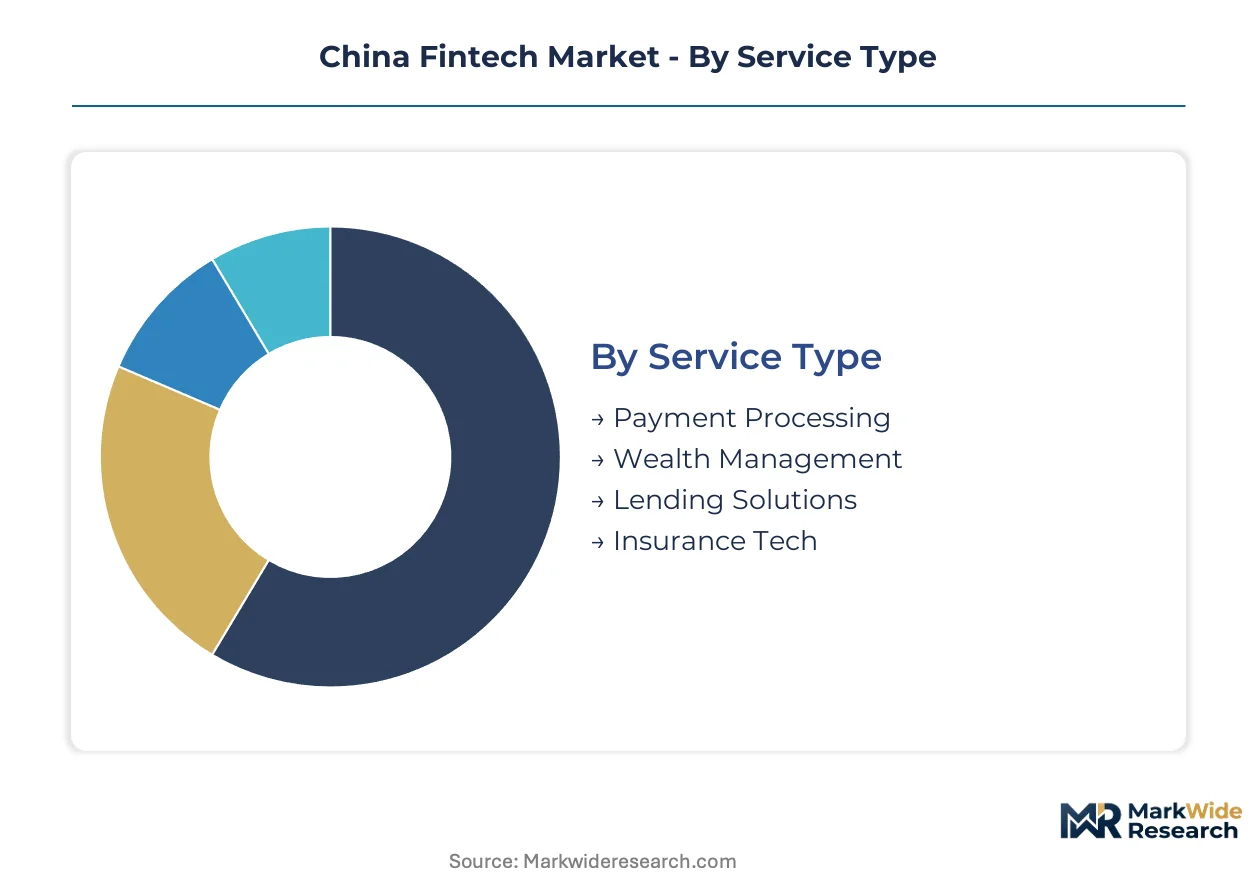
Segmentation in China's fintech sector reveals how regulatory licensing and technology architecture create divergent margin structures across service categories. NMPA capital adequacy requirements and MIIT data localization rules impose tiered compliance burdens that reshape competitive positioning within each segment cluster.
Service Type:
Payment Processing carries the heaviest NMPA licensing burden with capital reserve mandates that filter undercapitalized competitors, while Wealth Management faces SAMR firewall requirements separating it from payment ecosystems.
- Payment Processing:QR-code infrastructure processing transaction volumes exceeding conventional banking thresholds through real-time settlement rails. Demand concentrates in tier-two cities as merchant acquisition rotates inland from saturated coastal markets, constrained by PBoC digital yuan disintermediation of interchange fees.
- Wealth Management:Algorithmic portfolio management services distributing fund products to mass-affluent households rotating savings from property. Shanghai and Shenzhen anchor fee-based revenue pools as standalone app experiences replace embedded marketplace models under SAMR governance mandates.
- Lending Solutions:Micro-credit origination for underbanked consumers using alternative data partnerships.
- Insurance Tech:Embedded micro-premium distribution triggered at e-commerce checkout flows.
Payment Processing sits at the top of the volume ranking, with Wealth Management climbing the fastest.
Client Type:
Cost tier differentiation separates mass-market consumer platforms with thin margins from enterprise clients bearing integration complexity premiums.
- Consumers:Mobile-first financial service adoption through super-app ecosystems with standardized UX patterns.
- Small Businesses:Working capital products leveraging merchant data pipelines from industrial e-commerce networks in Zhejiang and Jiangsu provinces.
- Enterprises:Treasury management and cross-border settlement services requiring API bridging to legacy core banking systems.
- Financial Institutions:White-label infrastructure partnerships where regional joint-stock banks pilot federated learning architectures for credit scoring.
Consumers generate the highest transaction velocity, with Small Businesses expanding most quickly as supply-chain financing deepens.
Technology:
Application maturity varies sharply, with Mobile Payments reaching infrastructure saturation while Blockchain settlement protocols remain in pilot phases across Shenzhen and Guangzhou corridors.
- Blockchain:Distributed ledger infrastructure reducing cross-border remittance friction for SME import-export networks. Regulatory clarity under PBoC guidance remains incomplete, constraining enterprise deployment timelines.
- AI:Credit scoring models facing PBoC explainability requirements that outpace domestic compliance engineering talent supply.
- Mobile Payments:Ubiquitous QR-code infrastructure with hardware-light software solutions dominating inland merchant acquisition.
- Big Data Analytics:Real-time transaction processing engines handling volumes beyond conventional banking thresholds.
Mobile Payments commands installed base dominance, with Blockchain gaining share fastest through trade finance pilots.
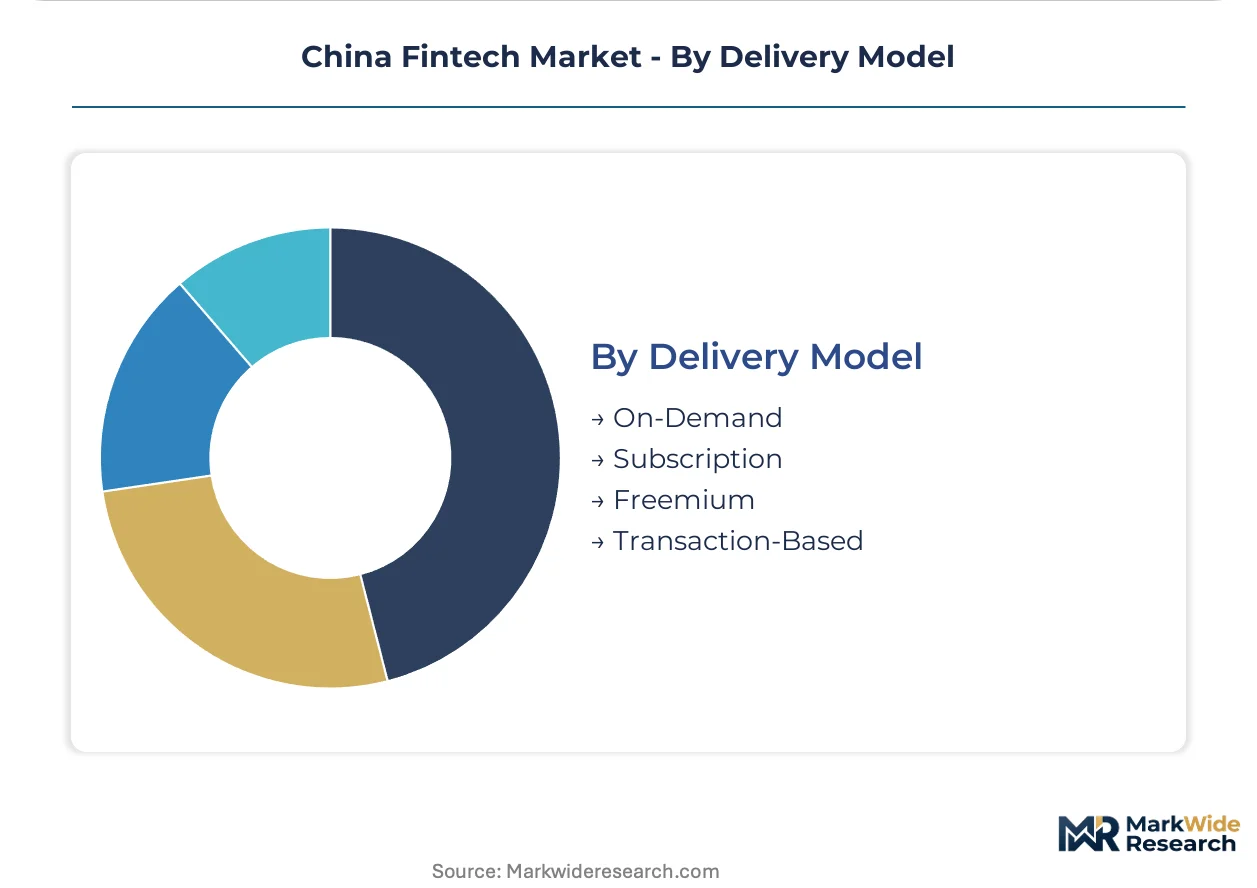
Delivery Model:
Margin structure separates transaction-scaled revenue from subscription predictability, with Freemium models facing SAMR scrutiny on cross-subsidization practices.
- On-Demand:Instant service activation for credit and insurance products with usage-based pricing.
- Subscription:Recurring revenue from portfolio management and treasury analytics tools serving corporate clients.
- Freemium:User acquisition through free payment services with monetization via credit and wealth cross-sell, now fragmented by SAMR firewall mandates.
- Transaction-Based:Interchange and distribution fees under compression from digital yuan direct liability holding.
Transaction-Based delivery captures current revenue concentration, with Subscription models showing the steepest expansion trajectory as enterprise clients seek predictable tooling costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fintech sector traces its commercial scaling to Alipay's 2004 launch and subsequent super-app consolidation, with regulatory architecture now dispersing activity across provincial innovation clusters.
Guangdong Province
Shenzhen anchors payment infrastructure R&D while Guangzhou corridor pilots blockchain settlement for SME trade finance. PBoC's digital yuan trials in the Pearl River Delta compress third-party wallet interchange economics. The Shenzhen-Hong Kong tech zone concentrates merchant acquisition hardware manufacturing and cross-border remittance protocol development.
Zhejiang Province
Hangzhou's e-commerce data pipelines feed supply-chain financing products for underbanked manufacturers in Ningbo and Wenzhou industrial clusters. SAMR's antitrust enforcement has fragmented Alipay's embedded finance architecture here. The province's joint-stock banks pilot federated learning credit scoring to compete with platform incumbents.
Jiangsu Province
Nanjing and Suzhou host white-label infrastructure partnerships where regional banks deploy algorithmic portfolio tools. MIIT data localization rules force domestic cloud duplication for fintech platforms serving Yangtze River Delta enterprises. The Nanjing Jiangbei New Area tests carbon-accounting fintech tools under MEE green finance guidance.
Beijing Municipality
The capital concentrates regulatory technology development and PBoC policy implementation for digital yuan infrastructure. Zhongguancun software parks house compliance engineering talent scarce elsewhere. Beijing-Tianjin-Hebei integration moves wealth management product distribution toward standalone app experiences under SAMR firewall mandates.
Sichuan-Chongqing
Chengdu and Chongqing drive inland merchant acquisition as QR-code saturation rotates from coastal markets. NMPA licensing requirements filter undercapitalized payment processors in these western hubs. The twin-city economic circle tests rural commercial bank API bridging for digital lending products.
China Fintech Market Vendor Landscape
The competitive structure tilts toward ecosystem operators with captive data pipelines. Two platform conglomerates anchor payment and credit origination through super-app environments, while specialized lenders and bank-affiliated fintech units compete on regulatory compliance and niche verticals. Strategic moves concentrate on firewall-compliant product unbundling and federated learning partnerships with regional banks.
Within the ecosystem operator tier, Ant Group and Tencent Holdings occupy positions defined by payment infrastructure scale and social graph data access. JD Technology represents the industrial e-commerce archetype with merchant data pipelines for supply-chain financing. Lufax Holding Ltd. exemplifies the wealth management specialist model with algorithmic distribution to mass-affluent households. Bank-affiliated players including China Construction Bank Corporation and China Merchants Bank Co., Ltd. leverage core banking relationships for white-label infrastructure deployment.
| Leading Market Players |
|---|
| Lufax Holding Ltd. |
| Alibaba Group Holding Ltd. |
| Ant Group |
| Ping An Insurance |
| China Construction Bank Corporation |
| Tencent Holdings |
| JD Technology |
| China Merchants Bank Co., Ltd. |
| WeBank Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Mass-affluent investors in Shanghai and Shenzhen anchor fee-based revenue pools for wealth management platforms, locking in subscription pricing models that reward algorithmic portfolio sophistication over transaction volume. This buyer concentration compresses margins for payment processors serving price-sensitive township merchants while elevating premium capture for standalone fund distribution apps.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates fintech service delivery. Premium tiers attach to algorithmic wealth management with direct fund house relationships, while economy tiers cover basic QR-code payment processing. Price differentiation rests on data infrastructure depth and SAMR compliance certification levels. Cost compression in payment processing is intensifying because PBoC digital yuan infrastructure disintermediates third-party wallet interchange economics. Small business lending platforms exhibit highest price sensitivity due to thin merchant margins in inland provinces.
Supply Chain Analysis
Compliance engineering talent scarcity in Zhongguancun software parks constrains platform scaling velocity for AI-driven credit scoring models. Cloud infrastructure sourcing concentrates in domestic data centers under MIIT localization mandates, with hardware components drawn from Shenzhen manufacturing corridors. API bridging modules for legacy COBOL core banking systems represent critical path dependencies. Supply chain risk centers on single-source vulnerability for federated learning architecture providers serving regional joint-stock banks. Distribution runs through super-app ecosystems and standalone mobile applications with direct carrier billing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China fintech operates as a late-cycle quality story where household savings rotation from property to fund distribution platforms elevates demand for algorithmic portfolio management with transparent fee structures.
For Market Incumbents: Deepen federated learning partnerships with Zhejiang and Jiangsu joint-stock banks to counter super-app data firewall fragmentation. Invest in compliance engineering talent pipelines at Nanjing and Beijing tech clusters to address PBoC model explainability requirements. Lock in merchant data pipeline exclusivity with industrial e-commerce networks before JD Technology consolidates supply-chain financing verticals. For New Entrants and Emerging Players: Begin with embedded insurance distribution at e-commerce checkout flows, the least penetrated vertical relative to payments and wealth management. Target Sichuan-Chongqing twin-city economic circle for rural commercial bank API bridging solutions where legacy core integration delays incumbent deployment. Lead with carbon-accounting fintech tools under MEE green finance guidance to capture regulatory tailwind. For Investors and Strategic Acquirers: Regional joint-stock banks with white-label infrastructure partnerships are the most active acquirer in this space, consolidating algorithmic credit scoring capabilities. Five-to-ten year viability favors federated learning specialists with MIIT-compliant privacy architectures over payment processors facing digital yuan disintermediation. Monitor SAMR platform governance review outcomes as inflection indicator for permissible cross-selling scope within super-app environments.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Enables regional banks to compete with Ant Group credit scoring without centralizing sensitive data under MIIT guidelines. |
| Standalone App Unbundling | Wealth management platforms build direct fund house relationships as SAMR firewalls fragment embedded marketplace economics. |
| Inland Merchant Acquisition | Agent networks capture township-level retail density as QR-code saturation rotates from coastal tier-one cities. |
| Green Finance Tool Development | Carbon-accounting fintech aligns with MEE dual carbon guidance to serve corporate treasury functions in Jiangsu. |
| Compliance Engineering Scale-Up | PBoC model explainability mandates outpace domestic talent supply, creating scarcity premium for validated AI credit systems. |
Methodological Framework
Multiple input streams — primary interviews with payment platform executives, wealth management product leads, and regional bank CTOs; secondary validation against NMPA licensing databases, PBoC digital yuan trial disclosures, and SAMR antitrust enforcement records; plus customs data on merchant acquisition hardware — were reconciled through bottom-up transaction volume modeling and top-down sectoral GDP attribution.
Historical transaction flow patterns were cross-referenced against panel input from fintech infrastructure providers across the projection horizon. Segmentation dimensions modeled include service type, client tier, technology application maturity, and delivery model economics. CAGRs were derived from trend extrapolation of QR-code penetration curves and fund distribution platform AUM trajectories, incorporating MIIT data localization cost impacts and digital yuan adoption scenarios as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt SAMR platform dissolution orders, PBoC digital yuan mandatory conversion timelines, and geopolitical restrictions on cloud architecture sourcing. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and household savings rotation velocity. Material deviation in NMPA capital adequacy enforcement intensity or federated learning standardization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Cyber Security in Fintech Market
FinTech
Netherlands AI in Fintech Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
Canada AI in Fintech Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
IoT for Finance Market
FinTech
Generative AI in Fintech Market
FinTech
AI in Fintech Market
FinTech
North America AI in Fintech Market
FinTech
Finance Cloud Market
FinTech
Vietnam Fintech Market
FinTech
Smart Financial Solutions Market
FinTech
Financial Cloud Market
FinTech
Smart Lending Platform Market
FinTech
Fintech Lending Market
FinTech
Business Analytics in Fintech Market