
 Metallised Polyester Films Market | 2026-2036
Metallised Polyester Films Market Size, Share, and Industry Trends Forecast 2026-2036
Metallised Polyester Films Market Intelligence
The performance gap between high-specification films for sensitive electronics and commodity-grade films for decorative applications is broadening. This divergence separates films requiring advanced physical vapor deposition and stringent quality control from those prioritizing cost-competitiveness. Toray Industries specializes in high-barrier films with superior gas and moisture protection for demanding applications. Uflex Ltd. leverages its large-scale production capabilities to serve diverse segments within the flexible packaging industry. Meanwhile, Cosmo Films differentiates through its focus on specialty films for complex labeling and packaging needs.
Metallised polyester film is a polymer sheet, specifically polyethylene terephthalate (PET), coated with a thin, reflective layer of metal, most commonly aluminum. The metal is applied using a physical vapor deposition (PVD) process under vacuum, which creates a barrier against light, oxygen, and moisture. Its primary commercial purpose is to protect perishable goods in packaging and to provide thermal insulation. Packaging applications dominate market volume, particularly for the food & beverage end-user segment. The insulation segment, however, represents the fastest-growing application, driven by building energy efficiency standards.
Market access is governed by compliance with food contact material regulations, including standards set by the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). Material composition is further scrutinized under chemical safety frameworks like the EU's REACH regulation and national standards such as those from the Bureau of Indian Standards (BIS). Future material selection will hinge on balancing barrier performance with recyclability to meet evolving circular economy directives.
Market Dynamics
The market's central force is its division between high-barrier performance needs and circular economy mandates for recyclability. This tension drives material innovation and defines the competitive separation between specialty and commodity-grade film producers.
Growth Catalysts
- Processed Food Sector Expansion:Growth of the food processing industry in India and other South Asian nations is elevating demand for cost-effective, high-barrier packaging to extend shelf life and reduce food waste.
- Regulatory Push for Recyclability:European Union directives on packaging waste are incentivizing the development of monomaterial-ready films with thinner metallic layers, which improve compatibility with existing recycling infrastructure.
- Material Science Advancements:Innovations in deposition technology are enabling the creation of ultra-high barrier films that provide superior protection against oxygen and moisture for sensitive electronics and pharmaceuticals.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of polyethylene terephthalate (PET) resin, the primary raw material, directly impact production costs and create margin uncertainty for film manufacturers.
- Threat from Transparent Barriers:In certain food and beverage applications, metallised films face competition from transparent barrier materials like EVOH and SiOx coatings, which allow for product visibility.
- Recycling Infrastructure Challenges:The metallic layer, while functional, complicates sorting and processing in many municipal recycling facilities, creating a structural barrier to achieving circular economy goals without specialized streams.
Strategic Opportunities
- Electric Vehicle Applications:The growing electric vehicle market presents an opportunity for high-performance films to be used as thermal insulation and electromagnetic shielding for battery packs and power electronics.
- Geographic Market Development:Film producers can target underpenetrated markets in Africa, where rising disposable incomes and a growing middle class are creating new demand for packaged consumer goods.
- Smart Packaging Integration:Metallised films can be functionalized by incorporating printed electronics, such as RFID antennas, to enable advanced supply chain tracking and authentication for high-value goods.
Industry Challenges
- Complex Regulatory Compliance:Manufacturers face significant operational hurdles in navigating the fragmented and continuously evolving food contact material regulations across jurisdictions like the U.S. (FDA) and EU (EFSA).
- High Capital Investment:The production of high-specification films requires substantial capital expenditure for advanced vacuum deposition chambers, cleanroom environments, and stringent quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallised Polyester Films Market |
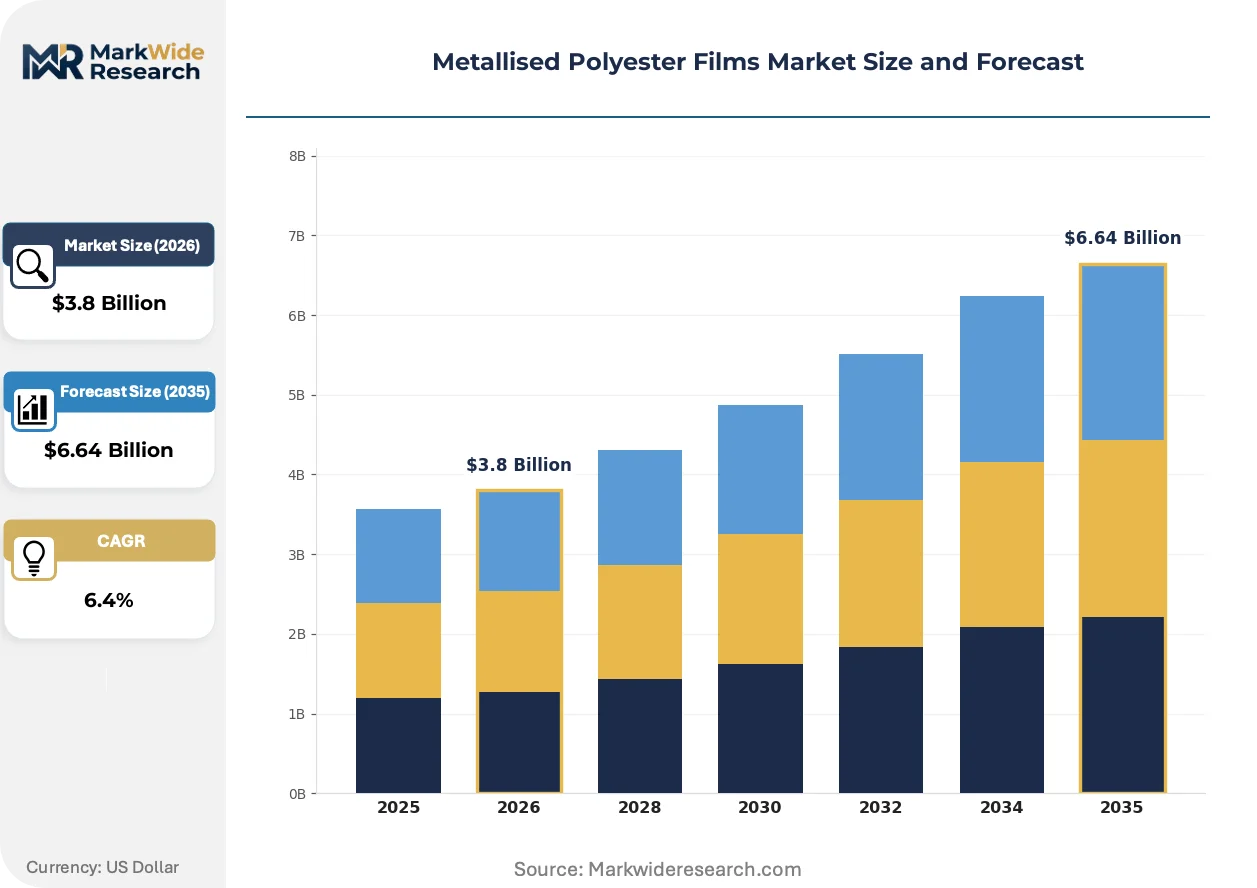
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Clear, Colored Application: Packaging, Labels, Decorative, Insulation End User: Food & Beverage, Electronics, Textile, Automotive Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Coating, Printing |
| Companies Covered | Uflex Ltd., Polyplex, Cosmo Films, Sumilon Group, Emperial Films LLP, Toray Industries, DUNMORE, Flex Films, Jindal Poly Films Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallised Polyester Films Market Strategic Shifts & Innovations
Material science innovation and sustainability mandates are the primary forces shaping market evolution. These pressures compel producers to develop films that offer enhanced barrier properties while meeting new standards for end-of-life management.
Advanced deposition techniques are improving film performance. Technologies such as Atomic Layer Deposition (ALD) allow for the creation of exceptionally thin, uniform, and flexible barrier layers. The medical device and flexible electronics sectors are key early adopters seeking superior protection in miniaturized formats. ALD technology for barrier creation is converging with traditional physical vapor deposition (PVD), enabling hybrid films with enhanced performance characteristics.
The European Union's REACH regulation imposes strict controls on chemicals used within manufacturing supply chains. This framework forces film producers to provide extensive documentation and find substitutes for certain substances used in primers or surface treatments. Film converters exporting to the EU are actively reformulating products to ensure compliance, which affects the global supply chain for specialty additives and coatings.
A shift from bulk price purchasing to a total cost of ownership model is gaining traction. This model, which factors in waste disposal fees and potential recycling credits, disrupts traditional volume-based contracts. It is most visible among large consumer packaged goods companies in Europe, responding to pressures from the Corporate Sustainability Reporting Directive (CSRD).
Metallised Polyester Films Market Segmentation
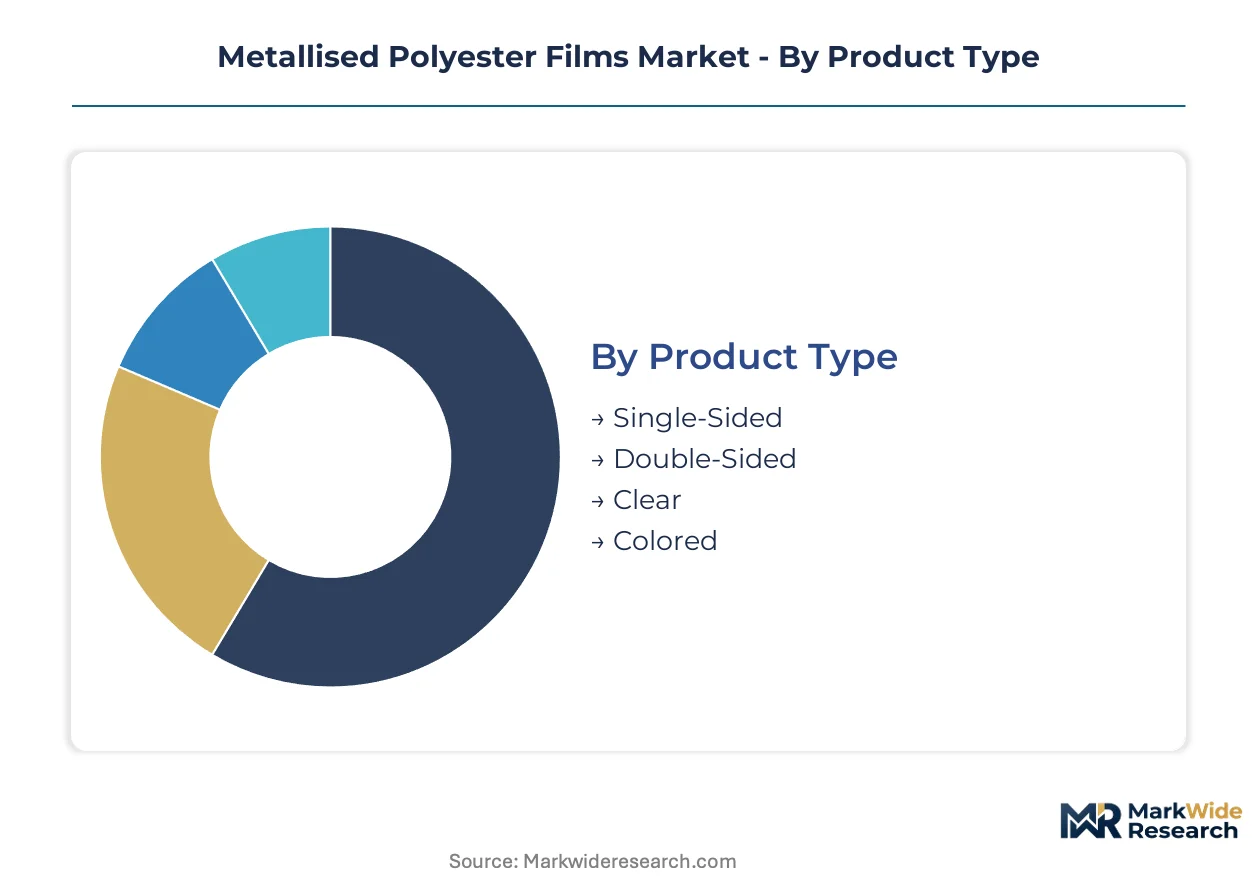
The metallised polyester films market differentiates across diverse product types, applications, end-users, and manufacturing technologies. Understanding these segmentations provides clarity on specific performance requirements and market demand drivers. This granular view helps producers align their product offerings with evolving industry needs and regulatory mandates.
Product Type:
Product type segmentation reflects varying barrier performance and aesthetic demands, with specific configurations often requiring distinct food contact material certifications, such as those from the U.S. Food and Drug Administration (FDA) or European Food Safety Authority (EFSA).
- Single-Sided:This film features a metallic layer on one surface of the PET substrate, providing a primary barrier against light, oxygen, and moisture. Demand concentrates in the flexible packaging sector for snacks and confectionery, driven by the need for extended shelf life in ambient conditions.
- Double-Sided:Both surfaces of the polyester film are metallised, offering enhanced barrier properties and often superior thermal reflectivity for demanding applications. The electric vehicle market uses these films for battery pack insulation, where robust thermal management is critical for safety and performance.
- Clear:These films use specialized transparent barrier coatings or ultra-thin metallic layers that allow product visibility while offering some barrier protection. Consumer preference for visible products in packaging drives adoption in premium food segments.
- Colored:Pigmented metallised films provide aesthetic appeal and brand differentiation, often used in decorative applications or high-end product packaging. These films cater to specific marketing requirements for visual impact.
Single-Sided films sit at the top of the volume ranking, with Clear films climbing the fastest due to evolving consumer preferences.
Application:
Applications for metallised polyester films span a wide cost spectrum, from high-volume, cost-sensitive packaging solutions to specialized, performance-critical insulation systems. This differentiation influences material specifications and production processes.
- Packaging:This segment uses metallised PET films for flexible packaging, providing essential barrier properties for perishable goods against light, moisture, and oxygen. The food & beverage industry dominates this application, seeking cost-effective solutions to prolong product freshness and reduce food waste.
- Labels:Metallised films provide a premium aesthetic for product labels, enhancing brand visibility. Beverage and cosmetic brands employ these labels to attract consumers.
- Decorative:Films in this category are primarily used for aesthetic purposes, such as gift wrap, balloons, and textile embellishments, where visual impact is the main driver. These applications prioritize appearance over high barrier performance.
- Insulation:High-performance metallised films offer thermal reflectivity and barrier properties critical for insulation in construction, aerospace, and electric vehicle battery packs. This application prioritizes advanced material science for energy efficiency and critical system protection, representing a steep expansion trajectory.
Packaging applications command the largest market share, while insulation applications are gaining share most quickly.
End User:
The end-user landscape for metallised polyester films comprises diverse customer types, ranging from large-scale consumer packaged goods corporations to highly specialized electronics manufacturers. Each requires tailored product specifications and supply chain considerations.
- Food & Beverage:This segment utilizes metallised films extensively for packaging snacks, confectionery, and processed foods, requiring robust moisture and oxygen barriers. Large consumer goods companies in India and other South Asian nations drive significant volume, focusing on shelf life extension and cost efficiency for mass-market products.
- Electronics:High-specification metallised films provide electromagnetic shielding and thermal management for sensitive electronic components, circuit boards, and displays. Manufacturers of smartphones and advanced computing devices demand ultra-high barrier films with stringent quality control for miniaturized formats.
- Textile:Metallised films are incorporated into textiles for decorative effects, thermal lining, or specialized protective apparel. Fashion brands use these films for aesthetic appeal or functional properties.
- Automotive:This sector employs metallised films for thermal insulation and interior decorative elements. Electric vehicle manufacturers integrate these films for enhanced battery performance.
The Food & Beverage sector remains the dominant end-user, with the Automotive industry demonstrating accelerated adoption.
Technology:
Manufacturing technologies for metallised polyester films exhibit varying degrees of supply concentration, with specialized equipment and expertise defining market access. Advanced deposition techniques require significant capital investment and technical know-how.
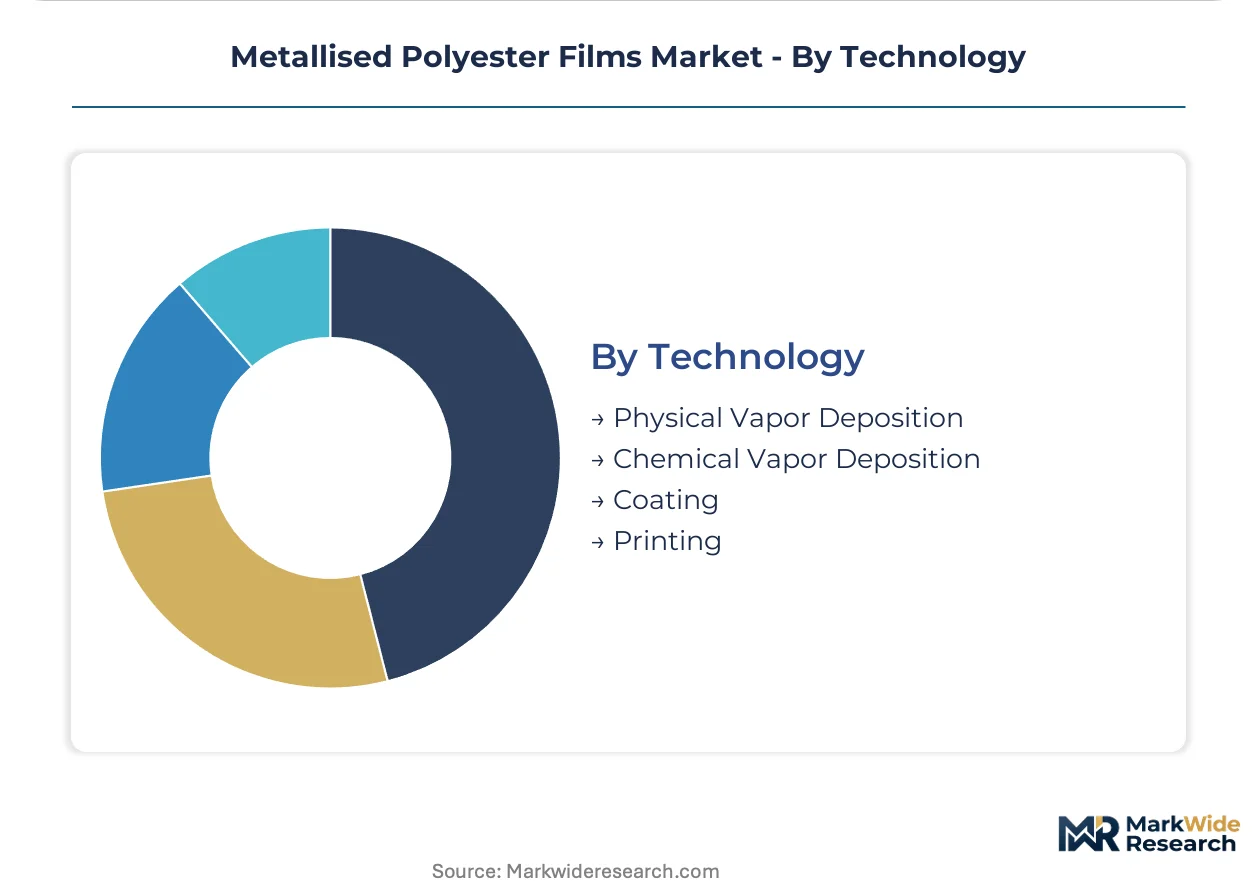
- Physical Vapor Deposition:PVD involves vaporizing metal, typically aluminum, in a vacuum chamber and condensing it onto the PET film surface, creating a thin, uniform metallic layer. This established technology forms the backbone of metallised film production for high-barrier packaging and thermal insulation.
- Chemical Vapor Deposition:CVD processes involve chemical reactions of gaseous precursors on the film surface to deposit thin films, offering precise control over material composition and structure. This technology is gaining traction for specialty barrier layers in medical devices and flexible electronics, where atomic-level precision is critical.
- Coating:This technology applies liquid barrier material onto the film surface, forming a protective layer. Coating methods enhance barrier properties or add functional characteristics.
- Printing:Printing technologies apply metallic inks or patterns onto films for aesthetic or functional purposes. This method is used for decorative films and smart packaging applications.
Physical Vapor Deposition continues to be the most prevalent manufacturing technology, while Chemical Vapor Deposition showcases significant technological advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's demand for metallised polyester films primarily stems from its expanding processed food sector, contrasting with Germany's market, which increasingly prioritizes films compliant with circular economy mandates. Each region presents distinct drivers and regulatory landscapes shaping film adoption. These regional dynamics influence material specifications and production strategies for global film manufacturers.
India
The processed food sector's growth in India drives significant demand for cost-effective, high-barrier packaging films to extend shelf life. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for packaging materials, influencing local production. Mumbai and Delhi-NCR feature concentrations of consumer goods manufacturers, elevating packaging material procurement.
Germany
Germany's market for metallised films is shaped by stringent circular economy mandates and a focus on monomaterial-ready solutions. The European Union's REACH regulation governs chemical substances in film production, requiring continuous material innovation. Industrial clusters in Bavaria and North Rhine-Westphalia lead in specialty film manufacturing for high-performance applications.
United States
Packaging applications, particularly for food and beverage products, represent a major demand driver in the United States. The U.S. Food and Drug Administration (FDA) establishes comprehensive food contact material regulations, ensuring product safety. California and Texas are emerging hubs for electric vehicle battery manufacturing, increasing demand for thermal insulation films.
China
China's vast consumer goods market fuels substantial demand for metallised films across diverse packaging segments. National GB standards dictate material safety and performance requirements for flexible packaging. The Yangtze River Delta region, including Shanghai, concentrates major packaging converters and film producers.
Japan
Japan's market emphasizes high-specification films for sensitive electronics and advanced packaging solutions. The Ministry of Economy, Trade and Industry (METI) supports research into advanced material science and sustainable manufacturing practices. Tokyo and Osaka remain centers for innovation in flexible electronics and specialty film development.
Metallised Polyester Films Market Key Industry Players
Top-tier vendors anchor high-specification film production, while mid-tier players focus on cost-competitive commodity grades for mass-market applications. The market exhibits archetypes including global material science innovators and large-scale flexible packaging converters. Competitive moves center on technology licensing and strategic capacity expansion to meet evolving industry demands.
Global material science innovators, such as Toray Industries, focus on ultra-high barrier films for demanding applications in electronics and medical devices. Large-scale flexible packaging converters like Uflex Ltd. leverage extensive production capabilities to serve diverse consumer goods segments, particularly in emerging markets. Meanwhile, Cosmo Films exemplifies companies specializing in niche film solutions for complex labeling and packaging needs, differentiating through specialty product portfolios.
| Leading Market Players |
|---|
| Uflex Ltd. |
| Polyplex |
| Cosmo Films |
| Sumilon Group |
| Emperial Films LLP |
| Toray Industries |
| DUNMORE |
| Flex Films |
| Jindal Poly Films Limited |
| Others |
Cost & Logistics Intelligence
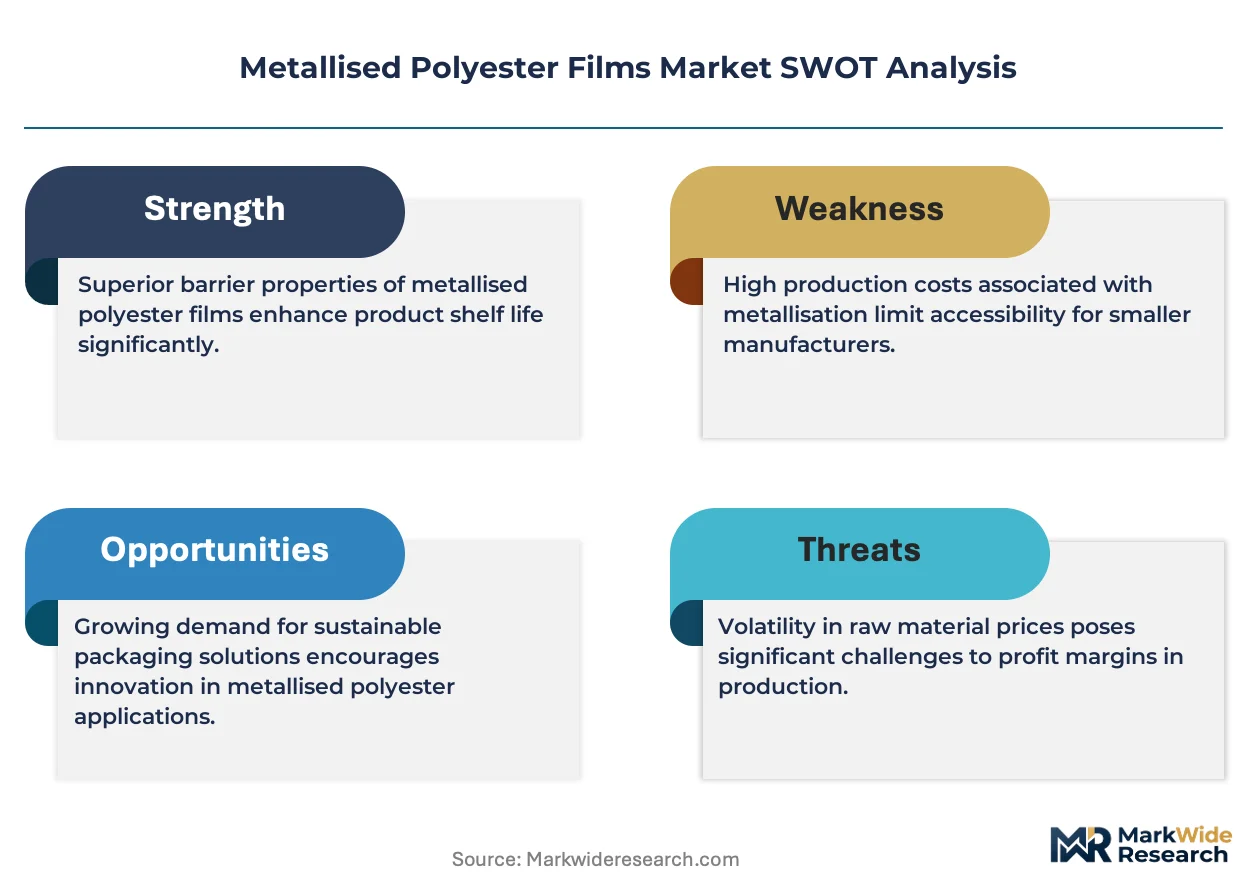
European Union's circular economy mandates are compelling film producers to develop monomaterial-ready solutions, which in turn influences manufacturing processes and shifts pricing structures towards value-based models. This demand-side pressure necessitates investment in material science, affecting overall market costs.
Pricing Analysis
Capacity additions in India are reshaping price floors for commodity-grade metallised films, intensifying competition among suppliers. Contract-based long-term offtake agreements dominate for bulk volumes, while specialty films command value-based pricing. Price differentiation stems from superior barrier performance and specific FDA or EFSA food contact material certifications. Input cost volatility, particularly for PET resin, creates margin uncertainty, making food & beverage packaging highly price-sensitive compared to electronics applications.
Supply Chain Analysis
Workforce availability in China and India supports large-scale production of metallised polyester films, anchoring global supply. The supply chain relies heavily on polyethylene terephthalate (PET) resin and aluminum as primary raw materials. Commodity price volatility for these inputs represents a structural risk to manufacturer margins. Distribution runs through direct sales channels for large flexible packaging converters and specialized distributors for smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metallised polyester films market functions as a stable compounder, driven by the sustained demand for enhanced shelf-life and protection of perishable goods. Material innovation further supports consistent expansion across diverse applications.
For Market Incumbents: Cement existing market leadership by investing in advanced material science for ultra-high barrier films, targeting sensitive electronics applications. Develop monomaterial-ready film solutions to address evolving EU packaging waste directives, mitigating the threat from transparent barrier materials. Expand strategic capacity in high-growth regions like South Asia to capture local demand. Prioritize stringent quality control and certifications to maintain premium pricing.
For New Entrants and Emerging Players: Capture niche segments by specializing in high-performance films for electric vehicle battery insulation, particularly in the United States. Focus on advanced thermal management properties and electromagnetic shielding as a key differentiator. A go-to-market strategy centered on technology licensing for specialized deposition techniques can accelerate market penetration. Target underpenetrated markets in Africa for consumer goods packaging.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialty film producers possessing proprietary barrier technologies and strong intellectual property in deposition techniques. Long-term viability is supported by the films' essential protective functions across critical industries over a 5-10 year window. Target acquisition archetypes include mid-cap firms with advanced Chemical Vapor Deposition (CVD) capabilities for medical devices. The signal to watch is the increasing integration of printed electronics into metallised films for smart packaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses demand in South Asia's processed food sector. |
| R&D in Monomaterial Films | Ensures compliance with EU circular economy mandates. |
| Technology Licensing | Accelerates adoption of advanced barrier coatings for electronics. |
| Geographic Market Entry | Penetrates under-served African consumer goods markets. |
| Smart Packaging Integration | Enables advanced supply chain tracking for high-value goods. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data foundation. Primary research included discussions with R&D directors, procurement leads, packaging engineers, and regulatory compliance officers across key geographies. Secondary data sources comprised FDA and EFSA regulations, Bureau of Indian Standards (BIS) documents, trade association reports, and company financial filings. This approach utilized both bottom-up market sizing and top-down validation for comprehensive analysis.
Historical performance across comparable periods anchored the forecast framework, providing a baseline for future projections over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, manufacturing technology, and regional regulatory frameworks. Compound annual growth rates were derived from regression analysis, integrating industry-specific forecast inputs. Key inputs included polyethylene terephthalate (PET) resin price trends and electric vehicle production forecasts.
Raw material price shocks, new regulatory mandates, and disruptive barrier technologies are the dominant revision risks for metallised polyester films forecasts. These projections reflect assumptions regarding market stability and technological evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Gutta-Percha Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
India Collagen Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Alginate Films Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Solar Backsheet Films Market