
 Nonwoven Filter Media Market | 2026-2036
Nonwoven Filter Media Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Filter Media Market Analysis
Modular filter cartridge systems is shifting procurement patterns across industrial buyers who now specify interchangeable media layers rather than fixed-configuration units. Toray Industries leverages its polymer science depth to supply customized meltblown grades for these stackable designs. Freudenberg anchors European aftermarket service networks with rapid-turn replacement programs. Kimberly-Clark competes in healthcare OEM channels through bonded cellulose formats optimized for gamma-sterilizable modules.
Nonwoven filter media consists of randomly oriented synthetic or natural fibers bonded through mechanical, thermal, or chemical means to create porous sheets with defined micron ratings, typically manufactured via meltblowing, spunbonding, or needle punching to achieve target permeability and dirt-holding capacity for separating particulates from fluid or air streams. Polypropylene dominates liquid filtration for its chemical inertness in process streams, while spunlace formats command premium positioning in healthcare where fiber shedding must approach zero. Air filtration applications lead absolute volume as urban air quality mandates multiply across industrial zones.
EPA National Ambient Air Quality Standards and EU F-Gas Regulation together tighten performance thresholds for HVAC and industrial emissions control, compelling media upgrades that nonwoven suppliers must certify. ISO 16890 for air filter testing and EN 1822 for HEPA/ULPA classification create technical barriers that filter media producers navigate through accredited laboratory partnerships. Stakeholders should track how REACH chemical restrictions on perfluorinated treatments redirect R&D toward silicone and bio-based repellent chemistries.
Market Dynamics
Modular filter cartridge architectures are restructuring procurement specifications across industrial buyers, forcing media suppliers to engineer interchangeable layer stacks rather than fixed-configuration units. This shift compresses replacement cycles and rewards suppliers with rapid-turn manufacturing capabilities.
Growth Catalysts
- EPA PM2.5 NAAQS tightening:The United States ambient air standard revisions mandate HVAC retrofit cycles across commercial building stock, pulling nonwoven media upgrades through certified filter OEM channels.
- Spunlace zero-shedding formats:Healthcare sterilization protocols in Germany's Rhineland hospital clusters specify bonded cellulose structures for gamma-irradiable surgical modules.
- Cologne-Düsseldorf industrial filtration concentration:Germany's process equipment manufacturers cluster demands high-volume meltblown supply for liquid filtration in chemical process streams.
Market Restraints
- Polypropylene resin price volatility:Propylene feedstock fluctuations transmit directly into liquid filtration media cost structures, compressing margins for commodity-grade producers.
- Perfluorinated chemistry REACH restrictions:ECHA regulatory pressure on PFAS treatments forces R&D redirection toward silicone and bio-based repellent alternatives with unproven scale economics.
- Meltblown capacity geographic concentration:Asian polymer fiber production clusters control upstream supply of fine-fiber grades, exposing European and North American converters to freight and tariff exposure.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO regulatory alignment with EU GMP standards creates demand for validated HEPA/ULPA media in sterile API production facilities.
- Electrospun nanofiber convergence:Layering sub-micron electrospun mats onto spunbond substrates enables next-generation HVAC efficiency without pressure-drop penalties.
- EU F-Gas Regulation phase-down:Refrigerant containment mandates drive membrane media adoption in HVAC system leak detection and recovery equipment.
Industry Challenges
- ISO 16890 and EN 1822 certification timelines:Accredited laboratory partnerships require 12-18 month validation cycles, delaying product launches for new media formulations.
- Electrospinning scale-up capex intensity:Commercial nanofiber production lines demand specialized voltage-controlled deposition equipment with limited second-hand market liquidity.
- Legacy HVAC system integration friction:Retrofit media must conform to dimensional standards established decades prior, constraining innovation in pleat geometry and frame attachment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Filter Media Market |
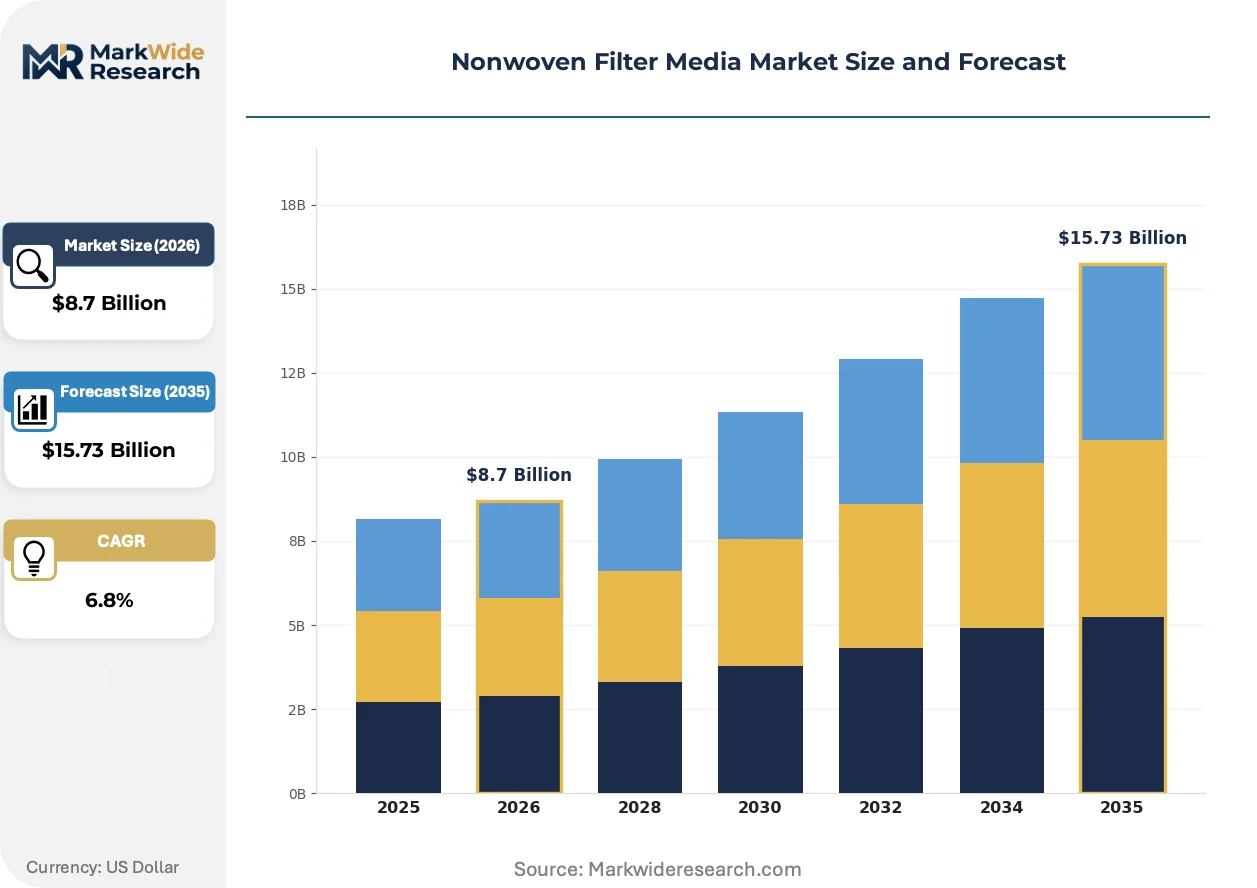
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
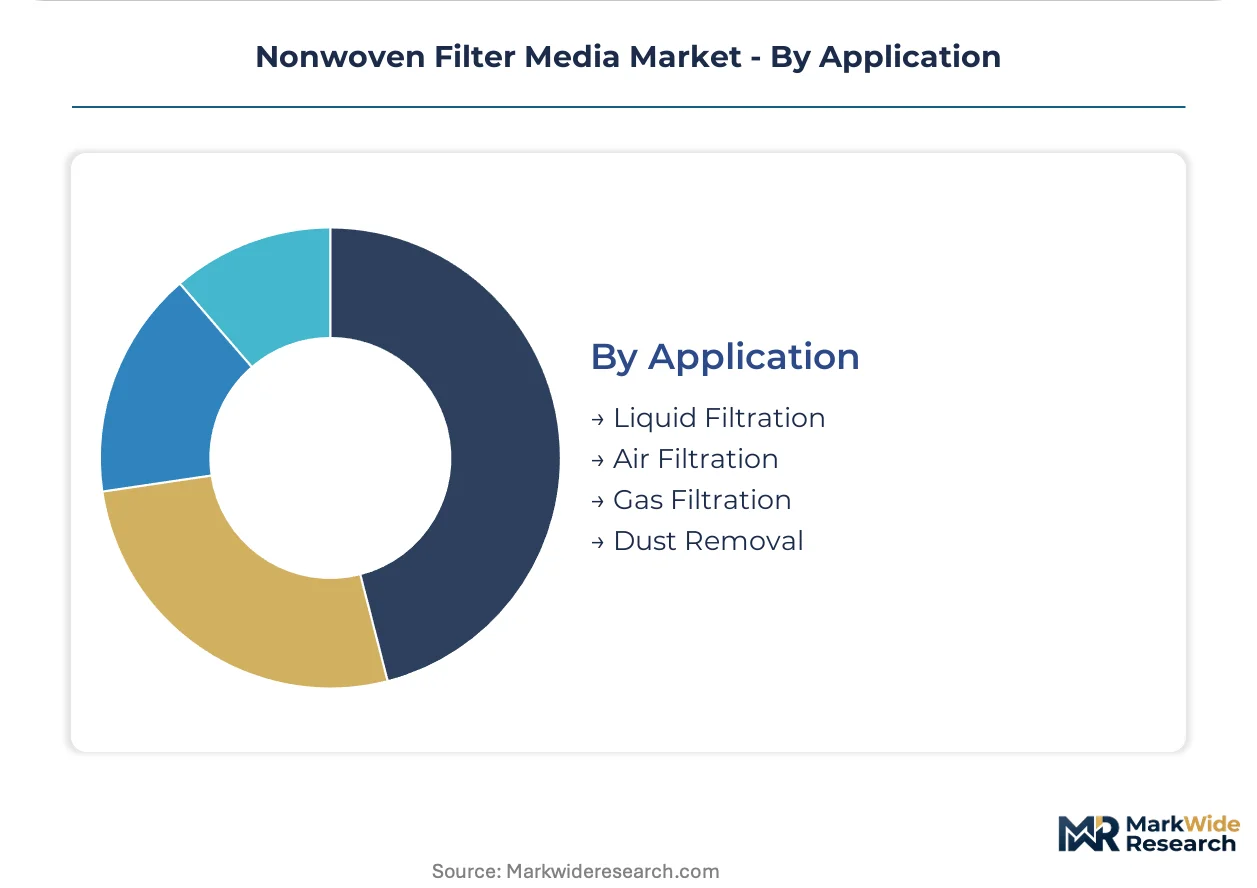
| Segmentation | Product Type: Polyester, Polypropylene, Cellulose, Spunlace Technology: Needle Punching, Thermal Bonding, Chemical Bonding, Airlaid End User: Automotive, Healthcare, HVAC, Oil & Gas Application: Liquid Filtration, Air Filtration, Gas Filtration, Dust Removal |
| Companies Covered | Ahlstrom, Toray Industries, BASF, DuPont, Berry Global, Freudenberg, Kimberly-Clark, Hollingsworth & Vose, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Filter Media Market Emerging Trajectories
Active material science breakthroughs and regulatory threshold tightening are compressing product lifecycles while opening premium positioning for certified performance tiers. Suppliers now compete on validation speed and accredited testing partnerships rather than commodity throughput alone.
Bicomponent spunbond-meltblown-spunbond (SMS) laminates are decentralizing filter manufacturing by enabling regional converters to source standard base webs and apply proprietary functional layers locally. Hospital procurement groups in France and the United States are qualifying these distributed supply models for pandemic resilience. The technology is decentralizing what had been concentrated premium media production into mid-scale regional operations.
EU F-Gas Regulation refrigerant phase-down mandates are forcing HVAC OEMs to redesign systems for lower-GWP alternatives with different pressure and compatibility profiles. Filter media must now certify chemical resistance to hydrofluoroolefins and natural refrigerants previously outside test protocols. German and Italian HVAC manufacturers are accelerating media validation programs to maintain CE marking compliance.
Industrial buyers are consolidating filter procurement through integrated facility management contracts that specify performance outcomes rather than product SKUs. Equipment service providers like those operating in Japan's automotive manufacturing belt are unbundling media supply from original equipment agreements. This pattern is most visible in German automotive paint finishing operations where Tier-1 suppliers now source filtration-as-a-service.
Nonwoven Filter Media Market Segmentation
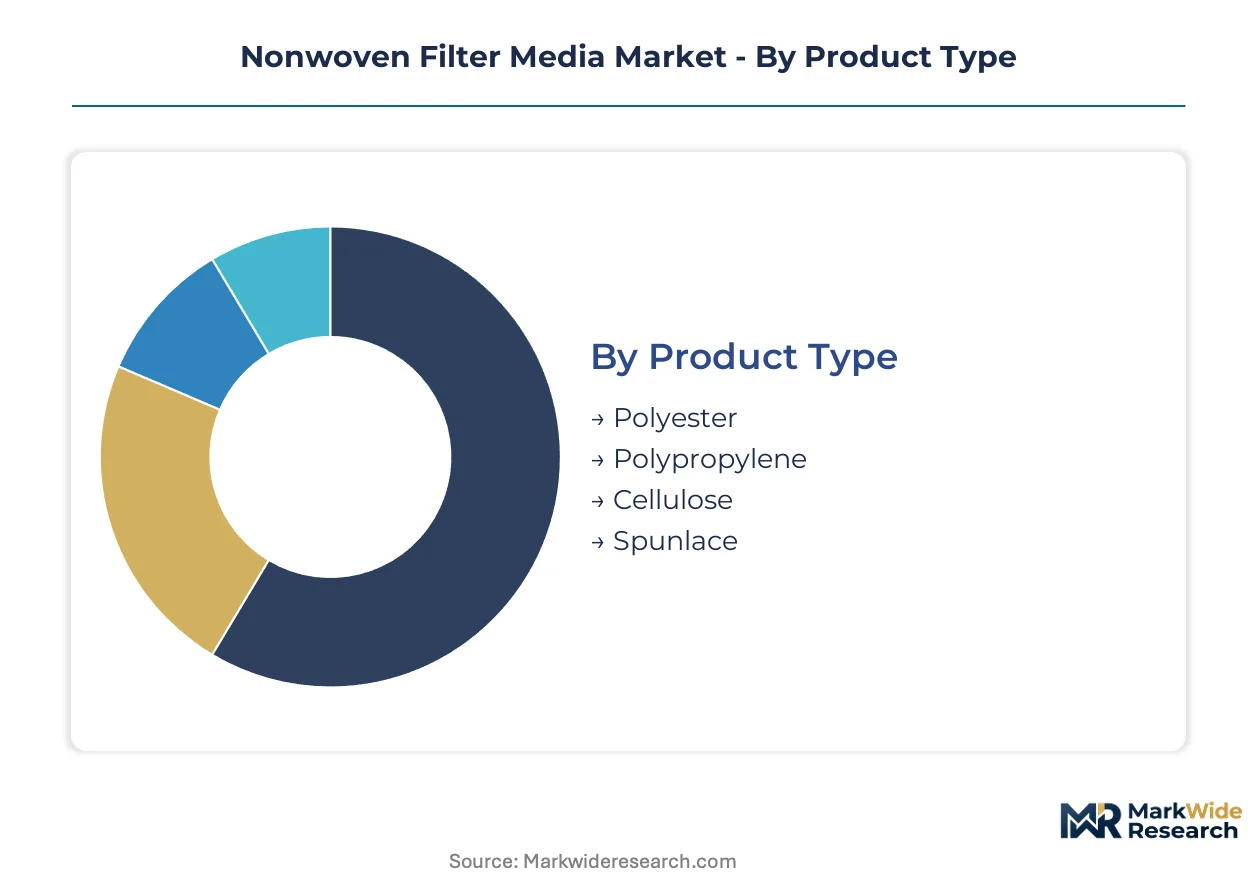
Nonwoven filter media segmentation reveals how material chemistry, bonding architecture, and end-use severity dictate specification tiers. Buyers select media based on fluid compatibility, temperature exposure, and regulatory compliance requirements rather than commodity pricing alone.
Product Type:
Polymer selection determines chemical resistance profiles and thermal stability ceilings across process environments.
- Polypropylene:Olefin-based matrices deliver hydrophobic surfaces and broad chemical inertness for aggressive liquid streams. Demand concentrates in Germany's chemical processing corridor around Cologne, where CDSCO-aligned pharmaceutical exporters specify validated polypropylene grades for sterile API filtration.
- Polyester:Thermoplastic polyester fibers offer dimensional stability under cyclic temperature loading in automotive engine compartments. BMW and Volkswagen paint finishing operations in Bavaria specify polyester spunbond substrates for overspray capture systems.
- Cellulose:Natural fiber webs bond through hydrogen interlocking for biodegradable disposal pathways.
- Spunlace:Hydroentangled structures achieve near-zero fiber shedding for gamma-sterilizable surgical drapes.
Mature deployment sits with polypropylene. Newer deployment is concentrated in spunlace formats for infection control protocols.
Technology:
Bonding mechanism selection trades off permeability, mechanical strength, and production throughput economics.
- Meltblowing:Extruded microfibers create fine-fiber matrices with sub-micron capture efficiency for HEPA-grade air filtration. EPA PM2.5 NAAQS retrofit mandates in United States commercial buildings pull meltblown supply through certified HVAC OEM channels.
- Needle Punching:Mechanical fiber interlocking produces high-loft structures with depth-loading capacity for heavy-dust industrial environments. Mining and cement operations in India's Rajasthan belt specify needle-punched felts for baghouse collectors.
- Thermal Bonding:Calender-activated polymer fusion yields consistent pore structures for liquid clarification.
- Chemical Bonding:Latex or resin binders enhance wet strength for aqueous process streams.
Volume leadership belongs to needle punching. Value capture is climbing fastest in meltblowing for fine-fiber specifications.
End User:
End-use severity dictates certification depth and replacement cycle frequency across buyer categories.
- Healthcare:Sterilizable media for surgical suites and pharmaceutical manufacturing demands EN 1822 HEPA/ULPA validation and zero-shedding fiber commitment. Germany's Rhineland hospital procurement clusters specify bonded cellulose structures for gamma-irradiable modules.
- HVAC:Commercial and residential air handling systems require ISO 16890-tested media with pressure-drop efficiency tradeoffs. United States EPA ambient air standard revisions mandate retrofit cycles across existing building stock.
- Automotive:Cabin air and engine intake filtration balance cost targets with OEM warranty requirements.
- Oil & Gas:Downstream process streams demand chemical compatibility for hydrocarbon separation.
Specification intensity peaks in healthcare. Procurement volume expansion is steepest in HVAC retrofit mandates.
Application:
Fluid phase determines pore architecture, surface treatments, and structural reinforcement requirements.
- Air Filtration:Pleated depth media with electrostatic enhancement capture particulate loads in HVAC and industrial emissions control. EU F-Gas Regulation refrigerant phase-down forces HVAC OEM redesigns for lower-GWP compatibility profiles.
- Liquid Filtration:Graded-density meltblown cartridges separate solids from process streams in chemical and pharmaceutical production. India's CDSCO regulatory alignment with EU GMP standards creates demand for validated media in sterile API facilities.
- Gas Filtration:Membrane and adsorptive layers remove contaminants from compressed air and process gas streams.
- Dust Removal:Surface-loading media with pulse-clean compatibility serve baghouse collectors in minerals processing.
Installed base concentration rests with air filtration. Growth trajectory is sharpest in liquid filtration for pharmaceutical process validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and India's pharmaceutical corridors concentrate meltblown capacity near downstream filter converters. Tax incentives for advanced materials production in these zones accelerate regional supply chain integration.
United States
EPA PM2.5 NAAQS revisions mandate HVAC retrofit cycles across commercial building stock in Texas and California. The Inflation Reduction Act's building efficiency credits accelerate media replacement timelines. Dallas-Fort Worth metroplex clusters filter OEM distribution centers serving southwestern industrial zones.
Germany
Cologne-Düsseldorf industrial filtration concentration demands high-volume meltblown supply for chemical process streams. EU F-Gas Regulation refrigerant phase-down forces HVAC OEM redesigns for lower-GWP compatibility. Bavarian automotive paint finishing operations specify polyester spunbond substrates for overspray capture systems.
China
Yangtze River Delta special economic zones concentrate meltblown and spunbond base web production for regional converter networks. NMPA alignment with ISO 16890 testing protocols accelerates domestic certification capacity. Zhejiang province polymer fiber clusters supply fine-fiber grades to HVAC manufacturers in Shanghai-Suzhou corridor.
India
CDSCO regulatory alignment with EU GMP standards creates demand for validated HEPA/ULPA media in sterile API production. Maharashtra and Gujarat pharmaceutical manufacturing corridors upgrade cleanroom filtration infrastructure. Hyderabad-Visakhapatnam industrial belt attracts meltblown investment serving domestic HVAC retrofit demand.
Japan
METI energy efficiency standards for commercial buildings accelerate HVAC media replacement cycles in Tokyo-Osaka corridor. JIS standards alignment with EN 1822 creates dual-certification pathways for export-oriented producers. Chubu region automotive manufacturing belt demands cabin air filtration media with OEM warranty compliance.
Nonwoven Filter Media Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The market structure consolidates around polymer science depth on one vector and rapid-turn manufacturing scale on another. Three archetypes dominate: integrated polymer producers with captive meltblown capacity, regional converter networks sourcing base webs, and healthcare-certified specialists with accredited laboratory partnerships. M&A activity concentrates on electrospinning technology access and geographic footprint expansion into pharmaceutical manufacturing corridors.
Among diversified chemical conglomerates, BASF and DuPont occupy positions defined by polymer science depth and backward integration into propylene feedstock streams. Toray Industries exemplifies the integrated fiber producer archetype with captive meltblown capacity serving stackable filter designs. Freudenberg anchors the European aftermarket service tier through rapid-turn replacement programs. These three represent distinct competitive vectors: feedstock control, manufacturing integration, and service network density.
| Leading Market Players |
|---|
| Ahlstrom |
| Toray Industries |
| BASF |
| DuPont |
| Berry Global |
| Freudenberg |
| Kimberly-Clark |
| Hollingsworth & Vose |
| Johns Manville |
| Others |
Supply Flow & Price Mechanics
REACH chemical restrictions on perfluorinated treatments gate qualified supply and premium-tier pricing access, forcing converters to source silicone and bio-based repellent alternatives through certified polymer channels. Buyers seeking EN 1822 HEPA/ULPA validation face extended certification timelines that compress margin structures across European supply chains.
Pricing Analysis
Margin tightening in standard-grade meltblown reflects propylene feedstock volatility transmitting directly into liquid filtration media cost structures. Three-tier pricing structure across premium, standard, and economy levels separates EN 1822-certified HEPA grades from ISO 16890-tested commercial HVAC tiers and commodity needle-punched industrial felts. Cost-down pressure on economy tiers accelerates because Asian polymer fiber production clusters expose European and North American converters to freight and tariff exposure. Healthcare OEM procurement groups exhibit lowest price sensitivity due to gamma-sterilizable module specifications, while industrial baghouse operators in mining and cement show highest sensitivity to per-unit media costs.
Supply Chain Analysis
Skilled technician availability in Germany's Cologne-Düsseldorf corridor and China's Yangtze River Delta special economic zones constrains meltblown capacity expansion timelines. Polypropylene resin, spunbond base webs, and electrospun nanofiber deposition equipment draw from concentrated Asian manufacturing clusters. Single-source vulnerability in fine-fiber grade supply exposes downstream converters to disruption. Distribution runs through regional OEM filter assemblers who apply proprietary functional layers to standard base webs sourced from integrated polymer producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nonwoven Filter Media Market functions as a cost-of-compliance story where EPA PM2.5 NAAQS tightening and EU F-Gas Regulation phase-down create barrier-to-entry moats for accredited laboratory partnerships and certified media producers.
For Market Incumbents: Cement rapid-turn replacement program density in Germany's Rhineland hospital clusters to lock out Freudenberg's aftermarket service network expansion. Deepen captive meltblown capacity in chemical process corridors to defend against Toray Industries' polymer science depth in stackable filter designs. Prioritize ISO 16890 and EN 1822 certification pipeline velocity to maintain premium positioning as validation timelines compress competitive windows. For New Entrants and Emerging Players: Direct-to-filter-OEM digital procurement platforms offer lowest-friction entry into India's CDSCO-aligned pharmaceutical manufacturing corridors where validated HEPA/ULPA media demand outstrips domestic supply. Target electrospun nanofiber layering capabilities for HVAC efficiency upgrades without pressure-drop penalties. White-space concentration sits with sterile API filtration in Maharashtra and Gujarat where European GMP validation creates specification premiums. For Investors and Strategic Acquirers: CDSCO regulatory alignment completion with EU GMP standards is the leading indicator that India's pharmaceutical filtration infrastructure investment cycle has reached deployable scale. Long-term viability favors integrated producers with backward polymer integration and accredited testing partnerships. Acquisition target archetype: regional converter networks with hospital procurement group relationships and pandemic resilience qualifications. Watch for electrospinning technology scale-up capex intensity creating distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Laboratory Partnership | EN 1822 HEPA/ULPA validation compresses 12-18 month certification timelines for new media formulations. |
| Backward Integration into Polymer Feedstock | BASF and DuPont anchor margin control through captive propylene supply for meltblown production. |
| Electrospun Nanofiber Layering Scale-Up | Sub-micron mat deposition enables next-generation HVAC efficiency without pressure-drop penalties. |
| Rapid-Turn Replacement Program Expansion | Freudenberg's European aftermarket density locks in hospital procurement group loyalty. |
| Regional Converter Network Acquisition | SMS laminate sourcing models decentralize premium media production into mid-scale operations. |
Methodological Framework
Multi-period observation of EPA PM2.5 NAAQS implementation timelines, EU F-Gas Regulation phase-down milestones, and REACH PFAS restriction progress anchored the trend analysis, supplemented by interviews with meltblown production plant managers, HVAC OEM procurement leads, hospital sterilization protocol directors, pharmaceutical cleanroom engineers, and aftermarket filter service heads. Secondary validation drew from EPA regulatory filings, ECHA restriction proposals, ISO 16890 test protocol documentation, EN 1822 classification standards, and customs trade data on polypropylene fiber imports. Bottom-up segment sizing triangulated against top-down macro filter demand indicators.
Input-output matrix modeling linked polymer resin supply volumes to downstream media production capacity across meltblowing, spunbonding, spunlace, and needle punching technologies. Segmentation dimensions included polymer chemistry, bonding architecture, end-use severity, and application fluid phase. CAGRs derived from regression analysis against retrofit cycle frequencies, regulatory compliance deadlines, and pharmaceutical manufacturing expansion pipelines. Forecast inputs incorporated HVAC system stock age profiles and CDSCO GMP alignment progress.
The model holds under stable propylene feedstock pricing and continued regulatory enforcement timelines; deviation in REACH restriction acceleration or Asian polymer export policy shifts would revise capacity utilization assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global High Temperature Filters Market
Filters
Europe Activated Carbon Market
Filters
Global Industrial Filters Market
Filters
Filter Coatings Market
Filters
Global Hollow Fiber Filtration Market
Filters
Diatomaceous Filter Aid Market
Filters
Filters and Particle Monitoring Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
GCC Industrial Air Filtration Market
Filters
Global Laboratory Filtration Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Filtering Centrifuges Market
Filters
Activated Carbon Filter Market
Filters
String Wound Filter Materials Market
Filters
Anti-Microbial Filter Market
Filters
Nonwoven Air Conditioning Filter Market