
 Bitumen Membrane Sheets Market | 2026-2036
Bitumen Membrane Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Bitumen Membrane Sheets Market Analysis
Capital-intensity divergence between integrated polymer producers and regional converters is rotating competitive advantage toward firms with captive bitumen modification capacity. Sika AG leverages its global chemicals infrastructure to sustain formulation consistency across climates. Soprema Group anchors its position through vertically controlled bitumen sourcing and European manufacturing density. GAF Materials LLC competes on residential channel control and contractor loyalty programs in North America.
Bitumen membrane sheets are composite waterproofing materials manufactured from oxidized or modified bitumen saturated onto reinforcement carriers such as polyester or fiberglass, with thicknesses typically ranging from 3mm to 5mm depending on performance grade. These sheets function as primary moisture barriers in roofing and below-grade applications, with service life contingent on polymer modification type and installation integrity. SBS membrane systems command premium positioning in cold-climate specifications due to elastomeric flexibility retention, while self-adhesive formats are gaining traction in occupied building retrofits where torch-applied methods face fire safety restrictions. Standard performance grades still occupy volume leadership in emerging markets where first-cost sensitivity dominates procurement.
REACH compliance in Europe, EPA stormwater management requirements in the United States, and BIS certification mandates in India collectively elevate product testing burdens and filter non-compliant suppliers from specification shortlists. Fire-resistant performance tiers face escalating scrutiny under EU CPR classifications and local building codes, reshaping R&D allocation toward intumescent and mineral-coated variants. Stakeholders must monitor how evolving extended producer responsibility frameworks for construction materials alter membrane recovery economics and brand positioning.
Market Dynamics
Europe's EPD mandates and tightening energy codes are redirecting specification behavior toward certified membrane systems, concentrating demand among suppliers with verified environmental product declarations and polymer modification capabilities.
Growth Catalysts
- Commercial waterproofing specifications:Developers prioritize long-term building performance in flat-roof commercial stock, elevating demand for SBS-modified systems with documented service life.
- REACH compliance:European chemical registration requirements filter non-compliant suppliers from specification shortlists, consolidating procurement toward certified manufacturers.
- Renovation rates in Germany:Elevated commercial building renovation activity sustains replacement demand for high-performance membrane systems in occupied structures.
Market Restraints
- Bitumen feedstock volatility:Crude oil price fluctuations transmit directly to modified bitumen costs, compressing converter margins during supply shocks.
- Torch-applied method restrictions:Fire safety regulations in occupied building retrofits limit traditional installation techniques, forcing costly method switches.
- Polymer supply concentration:SBS and APP modifier production concentrates among integrated petrochemical producers, creating input dependency for regional converters.
Strategic Opportunities
- Self-adhesive format expansion:Cold-applied installation systems penetrate occupied retrofit segments where flame restrictions apply.
- Intumescent coating development:EU CPR fire-resistance classifications redirect R&D allocation toward mineral-coated and fire-retardant variants.
- Extended producer responsibility frameworks:Construction material recovery mandates in European jurisdictions create membrane recycling infrastructure opportunities.
Industry Challenges
- Certified installer scarcity:Quality-sensitive applications require trained applicators for torch and self-adhesive systems, constraining project throughput.
- Multi-jurisdiction compliance:Manufacturers must maintain parallel testing protocols for EPA stormwater, BIS certification, and REACH requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitumen Membrane Sheets Market |
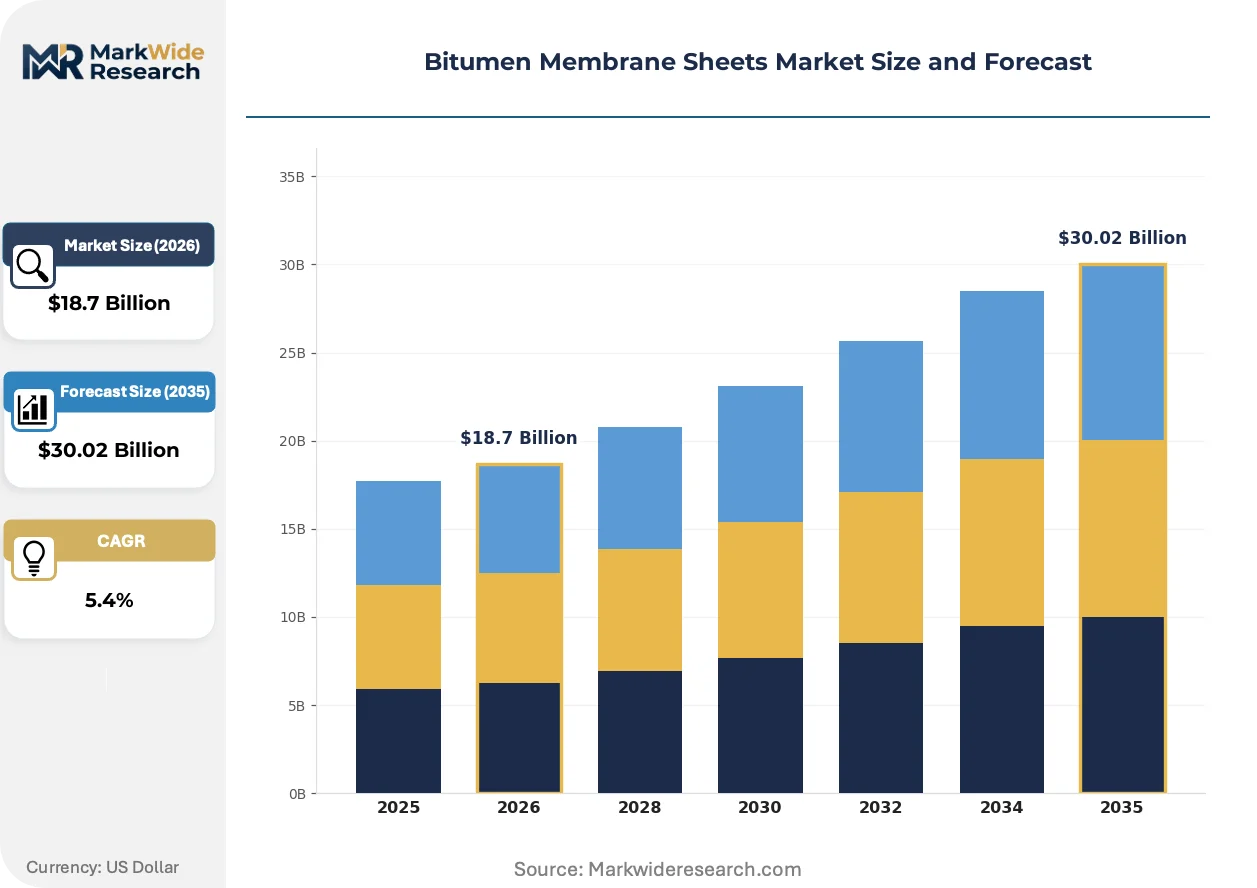
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, APP Membrane, SBS Membrane, Torch-On Installation Method: Cold Application, Hot Application, Mechanically Fastened, Ballasted End User: Residential, Commercial, Industrial, Infrastructure Performance Level: Standard, High-Performance, Fire-Resistant, Acoustic |
| Companies Covered | Sika AG, Soprema Group, GAF Materials LLC, Johns Manville, BMI Group, BASF SE, IKO Group, TotalEnergies, Fosroc International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitumen Membrane Sheets Market Emerging Trajectories
Membrane technology is diverging along climate-specific performance lines, with polymer chemistry and application methods adapting to regulatory fire-safety constraints and cold-climate flexibility requirements.
SBS elastomeric modification is fragmenting cold-climate specifications from standard-grade products. High-latitude commercial roofing contractors specify SBS-modified sheets for retained flexibility at sub-zero temperatures. The technology is fragmenting procurement tiers, separating premium elastomeric systems from oxidized bitumen volumes in specification databases.
REACH chemical registration and EU CPR fire-performance classifications are tightening product testing burdens. Manufacturers must document polymer content and fire-reaction properties for market access. Cold-climate commercial segments and German renovation contractors face the steepest compliance costs, accelerating consolidation toward integrated producers with in-house testing laboratories.
Buyer specification behavior is pivoting toward environmental product declarations and embodied carbon documentation. Architects and commercial developers now require EPD-verified membrane systems for green building certifications. This shift concentrates procurement among suppliers with third-party verified supply chains, most visible in German and Nordic commercial construction markets.
Bitumen Membrane Sheets Market Segmentation
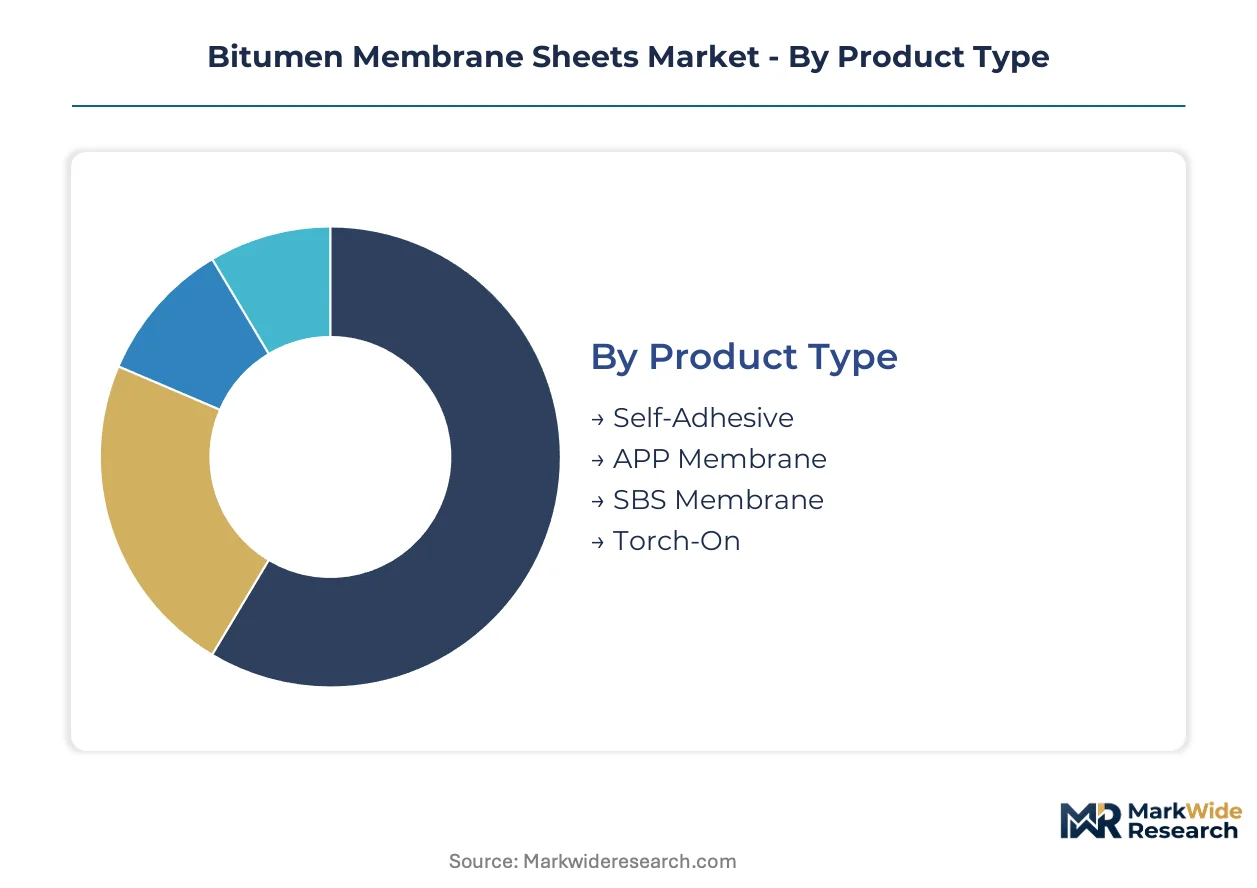
Segmentation in bitumen membrane sheets reveals how polymer chemistry, installation constraints, and regulatory fire-safety requirements partition demand across distinct procurement tiers. Specification behavior diverges sharply between cold-climate elastomeric systems and standard-grade oxidized products.
Product Type:
Domestic production concentrates SBS and APP modified systems in Germany and France, while self-adhesive formats increasingly serve export markets facing torch-application restrictions.
- SBS Membrane:Styrene-butadiene-styrene elastomeric modification delivers retained flexibility at sub-zero temperatures. German commercial roofing contractors specify these systems for flat-roof stock in renovation projects, with demand reinforced by REACH compliance documentation requirements.
- Self-Adhesive:Cold-applied installation eliminates flame hazards in occupied building retrofits. French and UK specification databases show accelerating uptake where fire safety regulations restrict torch methods.
- APP Membrane:Atactic polypropylene modification suits high-temperature climates with superior UV resistance. Italian and Spanish roofing markets favor APP for solar-exposed commercial envelopes.
- Torch-On:Traditional oxidized bitumen sheets applied with open flame dominate emerging market volume where labor costs favor established methods. Indian and Middle Eastern contractors specify torch-on for greenfield commercial construction.
SBS membrane holds the largest share; momentum sits with self-adhesive formats.
Installation Method:
Cost stratification separates premium mechanical fastening from economy ballasted systems, with application labor intensity driving total installed cost differentials.
- Cold Application:Self-adhesive and liquid-applied systems penetrate occupied retrofit segments where flame restrictions apply. German renovation contractors specify cold methods for healthcare and educational facilities.
- Hot Application:Torch-applied modified bitumen retains cost advantages in new construction with unoccupied work zones. Polish and Czech commercial developers specify hot application for logistics and manufacturing envelopes.
- Mechanically Fastened:Wind-uplift resistance specifications drive adoption in exposed high-altitude roofing. Alpine region contractors in Switzerland and Austria specify mechanical attachment for structural security.
- Ballasted:Gravel or paver-ballasted systems minimize membrane puncture risk in high-traffic rooftop applications. French commercial property managers favor ballasted installation for accessible roof terraces.
Cold application commands premium pricing; ballasted systems represent the value tier with steepest expansion trajectory in cost-sensitive segments.
End User:
Customer-type concentration shows commercial building envelopes generating specification intensity, while residential volume depends on distributor channel relationships.
- Commercial:Flat-roof office and retail stock drives SBS-modified system specifications with documented service life requirements. German property developers prioritize long-term building performance in renovation procurement.
- Infrastructure:Bridge deck and tunnel waterproofing demands high-performance membrane systems with accelerated curing characteristics. Austrian and Swiss transportation authorities specify certified systems for public works durability.
- Industrial:Manufacturing and warehousing envelopes favor standard-grade products where chemical resistance takes priority over aesthetic finish. Eastern European industrial zones specify economy-tier membranes for large-footprint structures.
- Residential:Single-family and multi-family roofing depends on contractor loyalty programs and distributor availability. Italian residential builders specify torch-on systems for cost-competitive pitched roof applications.
Commercial segment holds the largest share; infrastructure is climbing the fastest with public investment in transportation waterproofing.
Performance Level:
Margin structure separates certified high-performance tiers from commodity standard grades, with fire-resistant variants capturing regulatory premium pricing.
- Fire-Resistant:Intumescent and mineral-coated variants satisfy EU CPR classifications for high-occupancy structures. French and UK architects specify fire-rated membranes for residential high-rises and healthcare facilities.
- High-Performance:Enhanced polymer content and reinforcement density deliver extended service life for critical building envelopes. German commercial developers specify high-performance grades for green building certification compliance.
- Acoustic:Damping-layer membranes address airborne and impact sound transmission in multi-occupancy buildings. Swiss and Austrian residential construction specifies acoustic membranes for party wall and floor assemblies.
- Standard:Oxidized bitumen base grades serve cost-sensitive applications with shorter design life expectations. Emerging European markets specify standard performance for temporary structures and agricultural buildings.
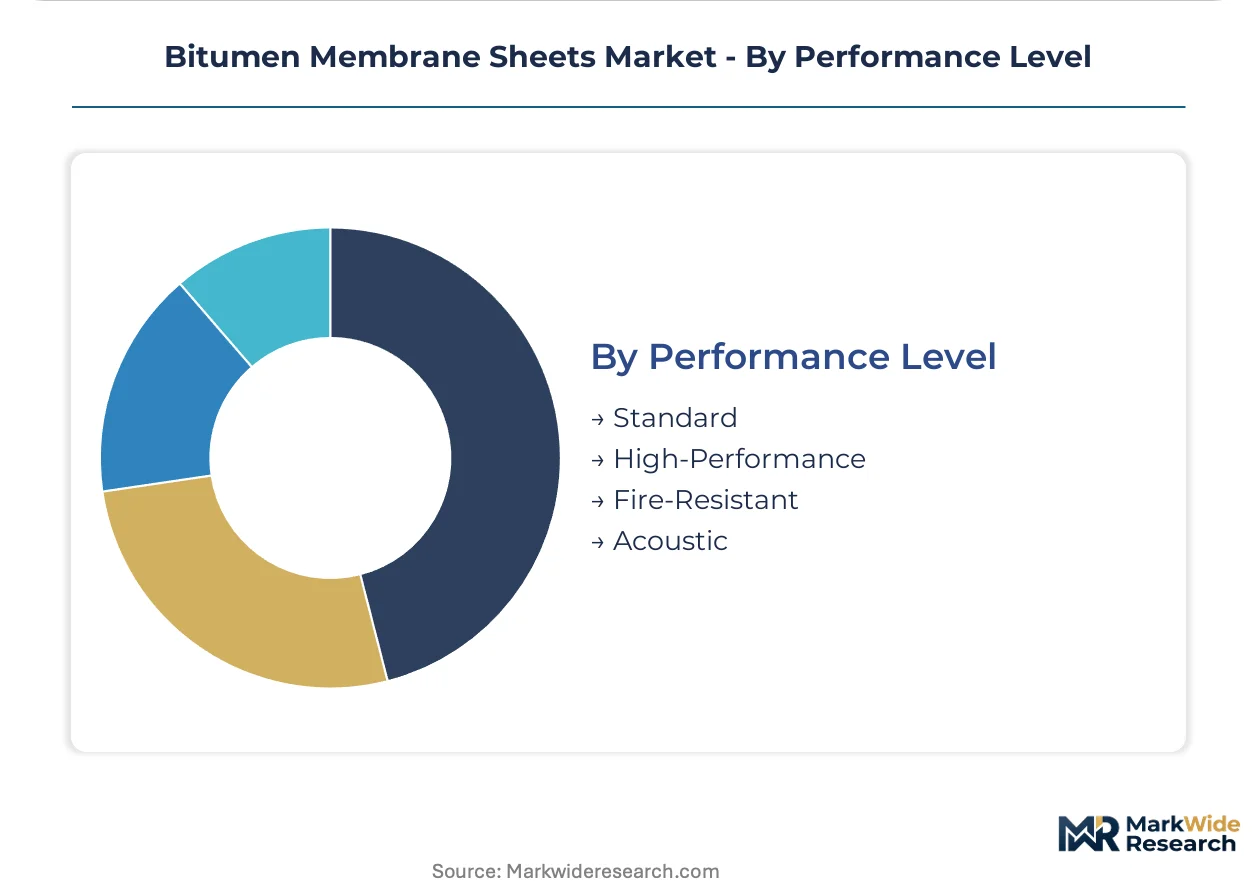
Fire-resistant tier holds the largest share; acoustic membranes are gaining share fastest with multi-family construction intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes bitumen membrane sheets primarily for commercial roof renovation, while India deploys identical materials for new greenfield construction with torch-on methods, revealing a fundamental demand-mix divergence between mature replacement markets and emerging build-out economies.
Germany
Commercial flat-roof renovation sustains SBS-modified membrane demand across aging office and retail stock. REACH compliance documentation and EPD certification requirements filter procurement toward verified suppliers. The Rhine-Ruhr corridor concentrates specification activity, with Dortmund and Düsseldorf contractors driving high-performance system adoption in occupied building retrofits.
United States
Residential channel volume and commercial re-roofing generate dual demand streams for modified bitumen systems. EPA stormwater management regulations elevate certified membrane specifications for impervious surface controls. The Southeast construction corridor from Atlanta to Charlotte shows accelerating uptake of self-adhesive formats where fire codes restrict torch application.
India
Greenfield commercial and infrastructure construction consumes standard-grade torch-on membranes at volume scale. BIS certification mandates for construction materials filter non-compliant imports from specification shortlists. The Delhi-Mumbai Industrial Corridor anchors demand concentration, with Gujarat and Maharashtra contractors specifying economy-tier products for logistics parks and manufacturing envelopes.
France
Multi-family residential and healthcare facility waterproofing drives cold-applied membrane specifications. EU CPR fire-performance classifications redirect procurement toward mineral-coated and intumescent variants. The Île-de-France region around Paris exhibits strongest demand intensity, with specification databases showing accelerating self-adhesive format uptake in occupied retrofits.
China
Urban renewal and transportation infrastructure expansion sustain modified bitumen consumption at industrial scale. GB standards for construction waterproofing mandate product testing protocols that filter regional suppliers. The Yangtze River Delta manufacturing cluster around Shanghai anchors production gravity, with Jiangsu and Zhejiang provinces driving specification volume for commercial envelopes.
Bitumen Membrane Sheets Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in bitumen membrane manufacturing. Integrated polymer producers with captive bitumen modification capacity command formulation consistency advantages across climate zones. Regional converters without upstream chemical assets face margin compression during feedstock volatility. Two strategic archetypes dominate: vertically controlled European manufacturers with in-house testing laboratories, and North American residential-channel specialists with contractor loyalty infrastructure. Competitive moves concentrate on backward integration into polymer supply and geographic expansion through distribution partnerships.
Among integrated European manufacturers, Sika AG and Soprema Group exemplify the vertically controlled archetype with captive modification capabilities. GAF Materials LLC anchors the North American residential-channel position. These three entities represent distinct competitive vectors: Sika AG leverages global chemicals infrastructure, Soprema Group maintains European manufacturing density, and GAF Materials LLC competes through contractor program structures. The specialist tier beneath them includes regional converters and building materials conglomerates with waterproofing divisions, each occupying positions defined by geographic coverage and installation-method specialization.
| Leading Market Players |
|---|
| Sika AG |
| Soprema Group |
| GAF Materials LLC |
| Johns Manville |
| BMI Group |
| BASF SE |
| IKO Group |
| TotalEnergies |
| Fosroc International Ltd. |
| Others |
Supply Flow & Price Mechanics
Self-adhesive membrane substitution for torch-applied systems is redrawing supply geography toward cold-climate European manufacturing while compressing pricing premiums previously commanded by flame-installation expertise. This format shift simultaneously elevates polymer modification costs and reduces contractor labor arbitrage, tightening margin structures for regional converters without captive chemical assets.
Pricing Analysis
After-sales service contracts and certified installer training programs capture lifetime value beyond membrane unit sales. Three-tier pricing structure across premium SBS-modified, standard APP, and economy oxidized bitumen levels stratifies procurement databases. Price differentiation rests on REACH documentation depth and fire-resistance certification tier. Cost compression in standard-grade segments is intensifying because Indian and Middle Eastern contractors prioritize first-cost procurement. Residential distributors exhibit highest price sensitivity; German commercial developers prioritize performance documentation over unit economics.
Supply Chain Analysis
Germany and France anchor SBS-modified membrane production for European renovation demand, while China feeds standard-grade volumes for Asian infrastructure build-out. Bitumen feedstock draws from regional refinery outputs, with SBS and APP modifiers sourcing from integrated petrochemical producers in South Korea and Germany. Single-source vulnerability concentrates in styrene-butadiene-styrene elastomer supply during crude price volatility. Distribution runs through specification-influenced contractor networks in commercial segments and distributor-led retail channels in residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against liquid-applied polyurethane and TPO single-ply membranes in commercial roofing specifications. Thermoplastic membrane encroachment demands formulation innovation and installation-method diversification to preserve specification share.
For Market Incumbents: Secure captive bitumen modification capacity to insulate margin structures from polymer feedstock volatility. Integrate in-house testing laboratories to accelerate REACH compliance documentation and filter regional competitors from German specification shortlists. Cold-applied format expansion represents the critical defensive lever against torch-method restrictions in occupied retrofits.
For New Entrants and Emerging Players: Lead with acoustic membrane specialization for Swiss and Austrian multi-family construction, where party-wall sound damping commands specification premiums absent from standard waterproofing procurement. Target infrastructure waterproofing segments in India and China where BIS and GB certification barriers filter fewer competitors than European EPD requirements. Partner with regional EPC contractors to bypass established specification databases.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European building materials conglomerates holding waterproofing divisions without captive polymer supply. Five-to-ten year viability hinges on backward integration completion and green certification portfolio depth. Monitor EU extended producer responsibility implementation timelines as inflection indicators for membrane recycling infrastructure valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Modification | Sika AG and Soprema Group sustain formulation consistency across climate zones through captive SBS production. |
| Cold-Applied Format Expansion | Self-adhesive membrane development penetrates French and UK occupied retrofits where EU fire codes restrict torch methods. |
| Fire-Resistance Certification Investment | Mineral-coated and intumescent variants capture EU CPR-driven premium pricing in high-occupancy structures. |
| EPD Verification and Carbon Documentation | Third-party environmental declarations secure German and Nordic green building specification access. |
| Extended Producer Responsibility Infrastructure | Membrane recovery and recycling capabilities align with evolving EU construction material circularity mandates. |
Methodological Framework
Desk research of customs trade data, ECHA REACH registration databases, and national construction statistics preceded structured interviews with waterproofing contractors, commercial property developers, and polymer procurement leads. Primary fieldwork with German roofing applicators and French specification consultants validated secondary demand estimates. SEC filings from integrated chemical producers and EU construction output indices furnished top-down market sizing. Bottom-up triangulation against regional bitumen consumption figures and membrane trade flows anchored volume estimates.
Variance decomposition across polymer chemistry, installation method, and end-use segments structured the analytical framework over the projection horizon. Modeled dimensions included SBS versus APP modification type, torch versus cold application format, and commercial versus infrastructure end-use intensity. CAGRs derived from segment-level growth rate blending weighted by current procurement volume. Forecast inputs incorporated REACH compliance cost trajectories and German renovation rate assumptions without year-specific anchoring.
Forecasts assume regulatory continuity in EU REACH and CPR regimes; material policy shifts would require re-modeling. Bitumen feedstock price volatility and polymer supply concentration represent primary forecast revision risks. Recalibration cycles align with material shifts in EPD mandate adoption and extended producer responsibility implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market