
 Activated Carbon Filter Market | 2026-2036
Activated Carbon Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Carbon Filter Market Intelligence
The activated carbon filter industry is restructuring around a widening split between pharmaceutical-grade specifications and bulk industrial commodity supply. CPL Activated Carbons leverages its vertical integration into coconut shell sourcing to sustain margin control in premium tiers. Donau Carbon GmbH anchors European demand through specialized chemical filtration systems for German automotive coating lines.
Activated carbon filters employ porous carbonaceous media with surface areas exceeding 500 square meters per gram to adsorb contaminants from fluids and gases. Steam-activation and chemical-activation processes determine pore size distribution, which governs suitability for chlorine removal, VOC capture, or mercury abatement in flue gas treatment. Water filters lead product type revenue due to municipal infrastructure replacement cycles, while hybrid systems represent the fastest-expanding technology segment as operators seek multi-contaminant compliance. Medical applications command premium pricing through stringent USP purification standards, whereas industrial end-use generates volume through food processing and mining effluent mandates.
The EPA enforces Maximum Contaminant Level Goals for disinfection byproducts that directly expand granular activated carbon replacement schedules in US municipal plants. REACH registration requirements in Europe constrain import chemistry profiles, favoring ECHA-compliant domestic manufacturers. Stakeholders must monitor evolving PFAS regulatory thresholds, as proposed EPA limits on per- and polyfluoroalkyl substances would force accelerated carbon changeout frequencies across utilities nationwide.
Market Dynamics
The activated carbon filter market is restructuring around tightening EPA and ECHA contaminant thresholds that force accelerated replacement cycles in municipal water infrastructure. Coconut shell supply concentration in Southeast Asian sourcing regions creates margin pressure for steam-activated carbon producers.
Growth Catalysts
- EPA Stage 2 Disinfectants Rule:Maximum Contaminant Level Goals for trihalomethanes and haloacetic acids mandate granular activated carbon upgrades across US municipal treatment plants, compressing replacement schedules from five-year to three-year intervals.
- Indian industrial corridor expansion:Food processing effluent mandates in Gujarat and Maharashtra drive powdered activated carbon demand for COD reduction in dairy and textile discharge streams.
- Hybrid filtration systems:Multi-contaminant compliance requirements push water utilities toward combined GAC-UV-nanofiltration architectures that outperform single-technology approaches.
Market Restraints
- Coconut shell charcoal volatility:Philippine and Indonesian supply disruptions from typhoon damage and export restrictions create raw material cost swings that steam-activation producers cannot fully hedge.
- Bituminous coal alternative limitations:Mercury and heavy metal trace content in coal-based activated carbon disqualifies it from pharmaceutical USP grade applications, constraining supply alternatives.
- REACH registration barriers:ECHA chemical substance inventory requirements block non-compliant Asian imports from European industrial filtration tenders, protecting domestic manufacturers but limiting buyer choice.
Strategic Opportunities
- Vietnam municipal infrastructure:Ho Chi Minh City and Hanoi water utility expansion programs lack established carbon filter supplier relationships, creating first-mover positioning for ECHA-compliant exporters.
- PFAS remediation tailwind:Proposed EPA limits on per- and polyfluoroalkyl substances would force utilities into activated carbon changeout frequencies double current baselines.
- Reactivation services:Spent carbon thermal reactivation in mobile kilns is displacing virgin carbon purchases among mining and petrochemical operators seeking Scope 3 emissions reductions.
Industry Challenges
- Pore size engineering talent:Chemical activation specialists who can tune micropore-mesopore distributions for specific contaminant targets command premiums that mid-scale producers struggle to match.
- USP certification timelines:FDA pharmaceutical-grade validation for new carbon sources requires eighteen-month stability studies that delay market entry for novel biomass feedstocks.
- Legacy infrastructure integration:Fixed-bed GAC contactors in decades-old US treatment plants cannot accommodate higher-density modern carbons without hydraulic capacity derating.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Carbon Filter Market |
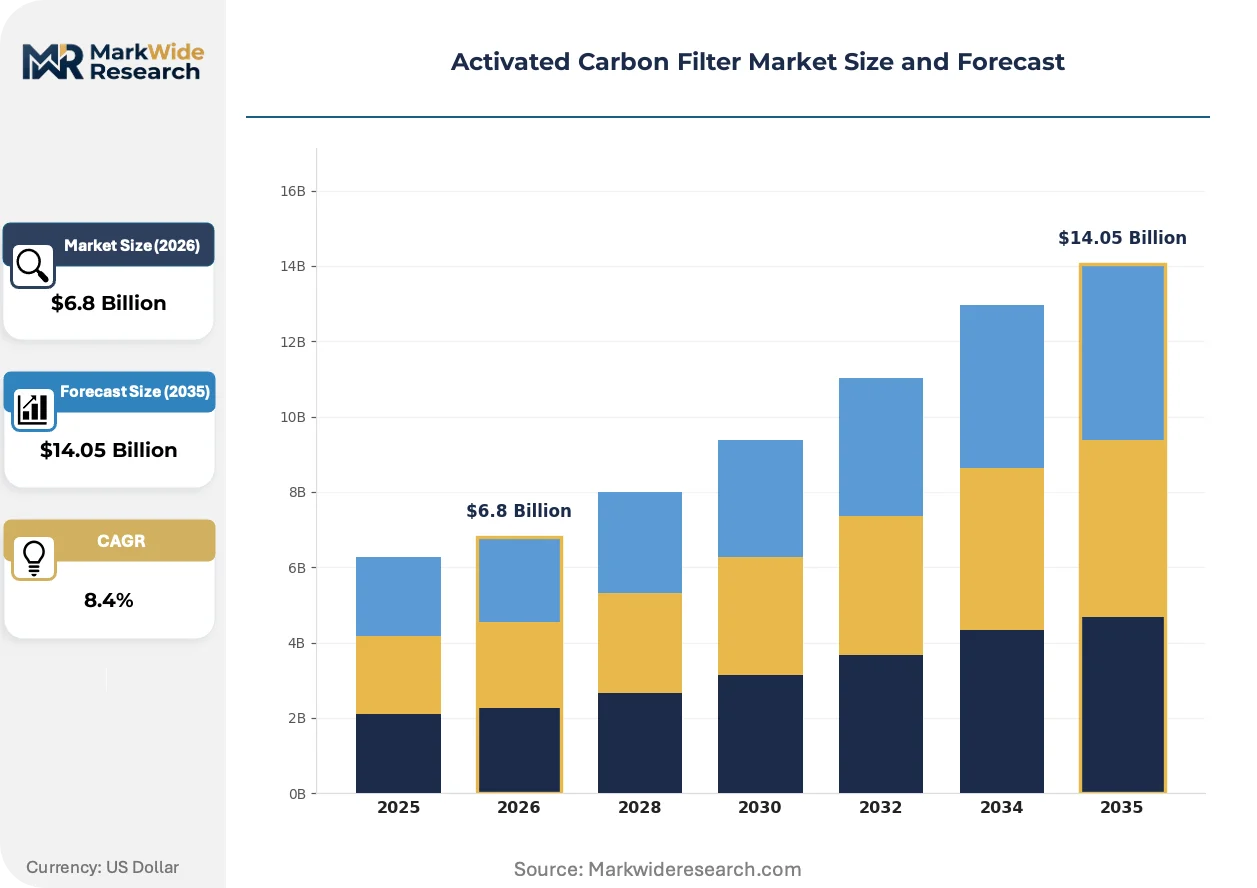
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filters, Water Filters, Gas Filters, Chemical Filters Application: Industrial, Residential, Commercial, Medical End User: Utilities, Healthcare, Food Processing, Mining Technology: Physical Adsorption, Chemical Adsorption, Biological Filtration, Hybrid Systems |
| Companies Covered | CPL Activated Carbons, Donau Carbon GmbH, Calgon Carbon Corporation, Pall Corporation, Carbon Activated Corporation, Jacobi Carbons, Haycarb PLC, 3M Company, Cabot Norit Activated Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Carbon Filter Market Strategic Shifts & Innovations
Activated carbon filtration is pivoting from commodity media supply toward engineered contaminant-specific solutions. Technology convergence and regulatory precision are compressing product lifecycles while opening premium positioning for validated performance tiers.
Biomass-derived activated carbons from agricultural residues such as rice husks and pistachio shells are rewriting feedstock economics for industrial-grade applications. European automotive coating lines are piloting these alternatives to coconut shell media for VOC capture, with reactivation yields approaching 85% of virgin performance. This substitution is compressing the premium attached to traditional sourcing while creating new regional supply nodes.
REACH authorization requirements for persistent organic pollutants are tightening import chemistry documentation for carbon filter media entering EU industrial markets. German automotive and chemical manufacturers now require full substance inventory disclosure from suppliers, disqualifying producers lacking ECHA-registered supply chains. Water treatment OEMs serving these sectors are consolidating vendor panels to three approved sources per geography.
Performance-based service contracts are displacing equipment-and-media sales in large municipal accounts. French and UK water utilities now contract for guaranteed contaminant removal outcomes rather than specifying carbon volumes, transferring technical risk to filtration service providers. This model concentrates procurement among vertically integrated operators capable of real-time performance monitoring and rapid media changeout logistics.
Activated Carbon Filter Market Segmentation
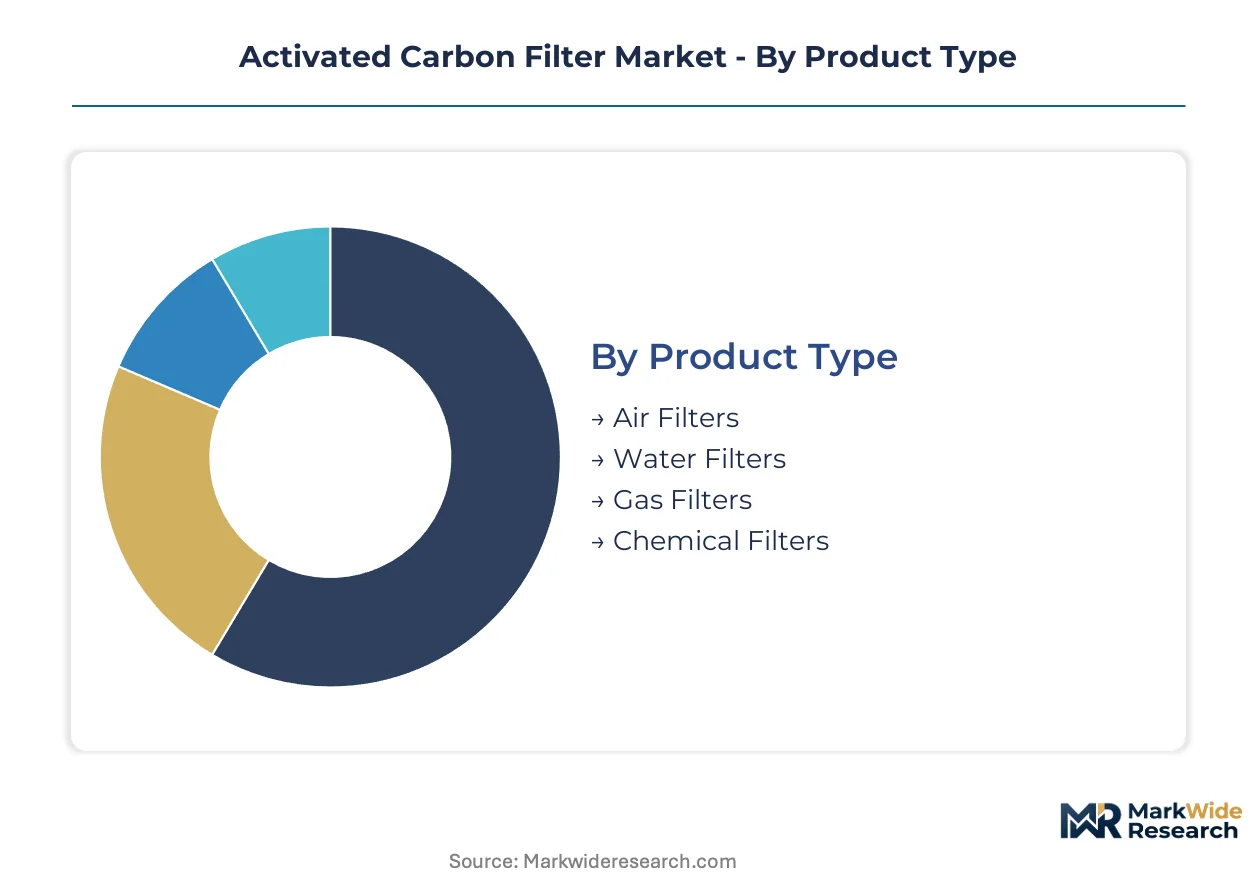
Activated carbon filter procurement diverges sharply across end-use contexts. Capital allocation, replacement cadence, and regulatory scrutiny vary by segment, creating distinct margin architectures for suppliers.
Product Type:
Capital intensity peaks in gas treatment systems requiring integrated pressure vessels and continuous monitoring infrastructure.
- Water Filters:Granular and powdered activated carbon configurations dominate municipal infrastructure replacement cycles. Demand concentrates in US municipal plants facing EPA Stage 2 Disinfectants Rule compliance deadlines.
- Air Filters:Fixed-bed and pleated configurations capture VOCs and odors in industrial ventilation. German automotive coating lines drive specification tightening for low-pressure-drop media.
- Gas Filters:Mercury abatement in flue gas treatment requires specialized impregnated carbons with sulfur or halogen surface modifications.
- Chemical Filters:Acid gas and corrosive vapor removal in semiconductor and pharmaceutical cleanrooms demands ultra-low ash content below 1%.
Most installed capacity flows through Water Filters. Expansion is steepest in Hybrid Systems (covered under Technology).
Application:
Customer procurement sophistication separates segments, with medical and industrial buyers employing divergent vendor qualification protocols.
- Industrial:Food processing effluent mandates in Gujarat and Maharashtra, plus mining discharge regulations across Australia and Canada, generate volume demand for powdered activated carbon in COD reduction.
- Medical:USP-grade validation requirements for pharmaceutical purification and dialysate preparation command 3-5x pricing premiums over industrial grades.
- Residential:Point-of-use and point-of-entry systems for chlorine and VOC removal in North American and European households compete on replacement cartridge economics.
- Commercial:Hospitality and office building HVAC integration focuses on odor control and IAQ certification compliance.
Industrial applications absorb the highest absolute carbon volumes. Medical commands the steepest price escalation per kilogram.
End User:
Contract structure complexity increases with scale, from spot purchases in mining to decade-long service agreements in utilities.
- Utilities:Municipal water treatment plants in Vietnam, Thailand, and the Philippines are expanding GAC contactor infrastructure without established supplier relationships.
- Healthcare:Hospital dialysis centers and pharmaceutical manufacturers require FDA-validated carbon sources with eighteen-month stability documentation.
- Food Processing:Dairy and beverage producers in India's industrial corridors deploy powdered activated carbon for decolorization and taste/odor control.
- Mining:Gold recovery operations and effluent treatment in Australia and South Africa favor thermal reactivation services over virgin carbon purchases.
Utilities represent the largest addressable contract value. Mining is gaining share fastest through reactivation service adoption.
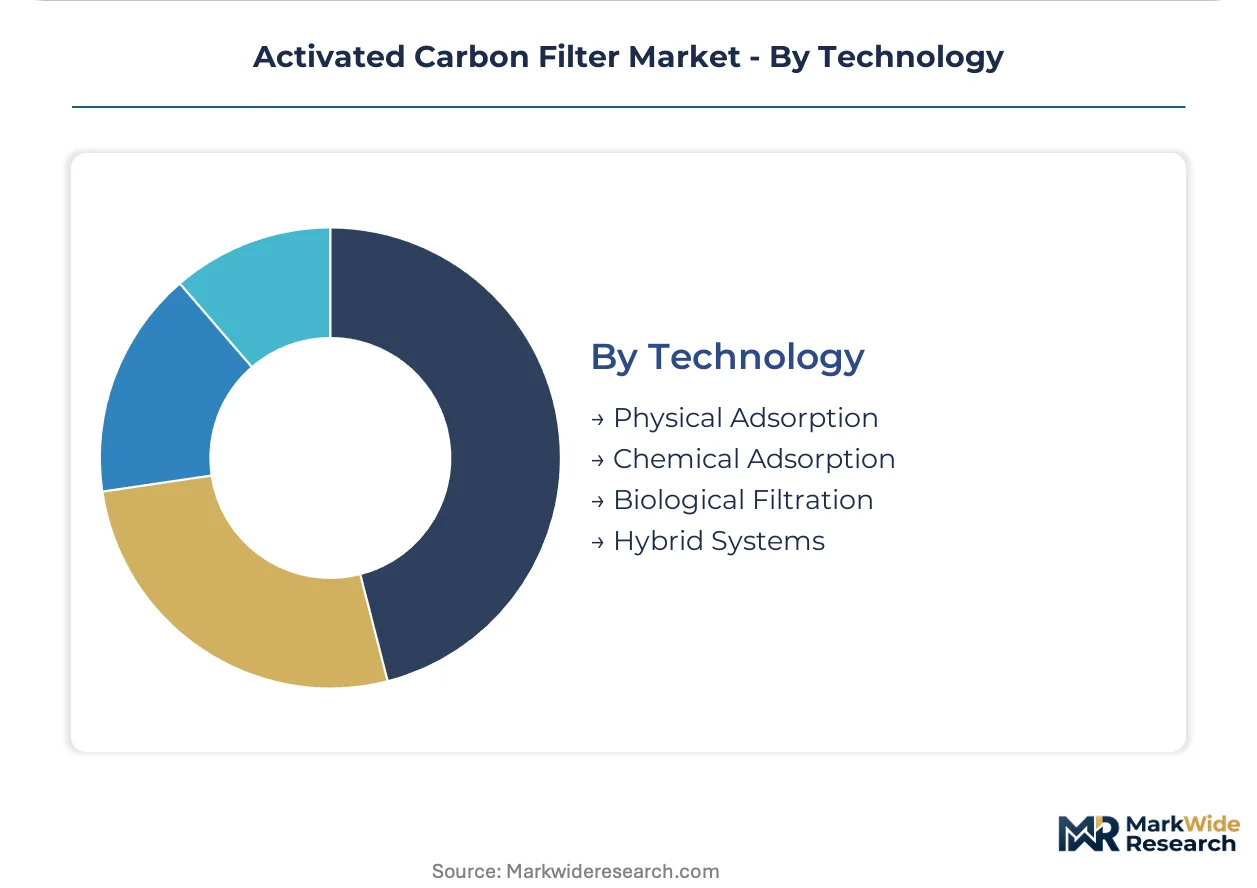
Technology:
Engineering talent scarcity concentrates in chemical activation specialists who tune pore distributions for specific contaminant targets.
- Physical Adsorption:Steam-activated coconut shell and bituminous coal carbons rely on van der Waals forces for chlorine, VOC, and odor removal. Philippine and Indonesian supply disruptions create raw material volatility.
- Chemical Adsorption:Impregnation with potassium iodide, sulfur, or metal oxides enables chemisorption of mercury, arsine, and acid gases. REACH authorization requirements constrain import chemistry profiles into Europe.
- Biological Filtration:Biologically active carbon supports microbial colonization for ammonia and nitrate reduction in advanced wastewater treatment.
- Hybrid Systems:Combined GAC-UV-nanofiltration architectures address multi-contaminant compliance including emerging PFAS concerns.
Physical Adsorption retains the largest installed base. Hybrid Systems are climbing the fastest as utilities confront simultaneous contaminant challenges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical activation specialists cluster in Germany's industrial belt and Japan's Kansai region, anchoring premium carbon engineering capabilities. Steam-activation production concentrates in Philippine and Indonesian coconut processing zones, creating geographic specialization between high-value and commodity supply tiers.
United States
EPA Stage 2 Disinfectants Rule compliance deadlines compress granular activated carbon replacement cycles across municipal plants. The Safe Drinking Water Act amendments drive infrastructure spending toward multi-contaminant filtration architectures. Ohio River Valley utilities face accelerated changeout schedules as trihalomethane monitoring intensifies.
Germany
Automotive coating lines in Baden-Württemberg specify low-pressure-drop media for VOC capture, tightening supplier qualification protocols. ECHA REACH authorization requirements block non-compliant carbon imports from Asian sources. Bavarian chemical manufacturers consolidate vendor panels to three approved suppliers per geography.
China
Dual carbon goals and MEE effluent standards expand powdered activated carbon demand in Yangtze River Delta textile clusters. Provincial environmental bureaus mandate COD reduction in Zhejiang and Jiangsu discharge streams. Shanghai municipal utilities pilot hybrid GAC-UV systems for emerging contaminant removal.
India
FSSAI food processing effluent mandates activate powdered carbon procurement in Gujarat and Maharashtra dairy corridors. Central Pollution Control Board discharge regulations tighten across industrial clusters. Chennai and Bengaluru water utilities expand filtration infrastructure without established supplier relationships.
Vietnam
Ho Chi Minh City and Hanoi municipal expansion programs lack incumbent carbon filter vendor relationships, creating first-mover positioning. Ministry of Construction water quality standards align with WHO guidelines for urban treatment plants. Mekong Delta industrial zones deploy activated carbon for textile and seafood processing effluent.
Activated Carbon Filter Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the activated carbon filter market. The vendor base splits between vertically integrated coconut shell processors and specialized chemical impregnation houses. Three archetypes dominate: steam-activation commodity suppliers, chemical activation premium specialists, and reactivation service operators. Consolidation targets capacity expansion in Southeast Asian sourcing regions, while technology licensing agreements spread impregnation expertise beyond traditional European centers.
Within the premium chemical activation tier, CPL Activated Carbons and Donau Carbon GmbH exemplify European engineering specialization. Haycarb PLC occupies a position representing Southeast Asian coconut shell sourcing integration. These three anchors illustrate the geographic and technological bifurcation shaping procurement decisions across municipal, industrial, and pharmaceutical end-use contexts.
| Leading Market Players |
|---|
| CPL Activated Carbons |
| Donau Carbon GmbH |
| Calgon Carbon Corporation |
| Pall Corporation |
| Carbon Activated Corporation |
| Jacobi Carbons |
| Haycarb PLC |
| 3M Company |
| Cabot Norit Activated Carbon |
| Others |
Cost & Logistics Intelligence
Coconut shell charcoal feedstock costs cascade through steam-activated carbon pricing tiers, compressing margins for Philippine-dependent producers while rewarding chemical-activation specialists with impregnation capabilities. Buyers in German automotive coating lines absorb premium markups for low-pressure-drop media, whereas Indian dairy processors negotiate powdered carbon contracts on commodity terms.
Pricing Analysis
Bundled service contracts now outpace unbundled equipment-and-media sales in French and UK municipal utilities, transferring technical risk to filtration providers. Three-tier pricing structure across premium, standard, and economy levels separates USP-grade pharmaceutical validation from industrial COD reduction grades. Cost compression in steam-activated tiers intensifies because Philippine typhoon damage disrupts coconut shell supply. Mining operators exhibit highest price sensitivity through thermal reactivation adoption, while pharmaceutical manufacturers accept 3-5x premiums for FDA-validated sources.
Supply Chain Analysis
Container freight rates from Philippine and Indonesian processing zones to European industrial ports amplify landed costs for coconut shell carbon shipments. Steam-activation capacity draws from Philippine, Indonesian, and Sri Lankan coastal processing clusters. Raw material inputs hinge on coconut shell charcoal, bituminous coal, and emerging rice husk biomass alternatives. Single-source vulnerability concentrates in Southeast Asian typhoon corridors. Distribution runs through authorized vendor panels that German automotive OEMs have consolidated to three approved suppliers per geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in reactivation services and hybrid system integration, where performance-based contracts capture value from Scope 3 emissions reductions and multi-contaminant compliance.
For Market Incumbents: Deepen backward integration into coconut shell sourcing to hedge Philippine supply volatility, while expanding chemical-activation capacity for mercury abatement and acid gas applications. Biomass-derived feedstock alternatives threaten traditional premium positioning; defend through USP certification timelines that delay competitor entry. Prioritize mobile thermal reactivation kiln networks to capture mining and petrochemical service contracts. For New Entrants and Emerging Players: E-procurement platforms serving Vietnam's Ho Chi Minh City and Hanoi water utilities bypass established distributor relationships. White-space concentrates in ECHA-compliant carbon exports to Southeast Asian municipal expansion programs lacking incumbent suppliers. Target hybrid GAC-UV-nanofiltration system integration as the fastest-climbing technology segment. Lead with performance-based service contracts rather than equipment sales to transfer technical risk and secure recurring revenue. For Investors and Strategic Acquirers: Consolidation pressure builds where chemical-activation engineering talent concentrates in Germany's industrial belt and Japan's Kansai region. Long-term viability favors vertically integrated operators with captive coconut shell supply and reactivation service capabilities. Watch EPA PFAS regulatory finalization as the inflection signal that would double activated carbon changeout frequencies across US utilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Shell Sourcing | CPL Activated Carbons controls Philippine supply volatility through captive plantation networks. |
| Mobile Thermal Reactivation Service Expansion | Mining operators in Australia and South Africa displace virgin carbon purchases with on-site kiln processing. |
| Hybrid Filtration System Integration | Shanghai municipal utilities pilot GAC-UV-nanofiltration architectures for emerging contaminant removal. |
| USP Pharmaceutical Grade Certification Investment | Eighteen-month FDA stability studies delay competitor entry and sustain 3-5x pricing premiums. |
| ECHA REACH Compliance Program | German automotive OEMs block non-compliant Asian imports through substance inventory disclosure mandates. |
Research Approach
Direct dialogue with municipal water utility procurement managers, chemical-activation R&D directors, coconut shell processing plant operators, and reactivation service technicians grounded the qualitative foundation. Secondary validation drew from EPA enforcement databases, ECHA substance inventory registrations, USP-NF monograph updates, and Philippine Bureau of Customs export records. Bottom-up and top-down triangulation reconciled granular utility contract values with aggregate regional infrastructure spending estimates.
Bottom-up modeling segmented the analysis window by product type, application, end user, and technology tier, with cross-validation against regional regulatory compliance deadlines. CAGRs emerged from replacement cycle compression factors, infrastructure expansion pipelines, and technology substitution rates. Forecast inputs incorporated EPA Stage 2 Disinfectants Rule implementation timelines and PFAS regulatory proposal trajectories.
The model assumes a particular technology adoption path; alternative pathways for biomass-derived activated carbon would alter the outlook if reactivation yields sustain above 80% of virgin performance. Forecasts reflect assumptions about regulatory enforcement intensity and raw material supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Filter Paper Market
Filters
Liquid Filter Bags Market
Filters
Coolant Filtration Skids Market
Filters
High Purity Chemical Filters Market
Filters
Industrial Air Filtration Market
Filters
Filters and Particle Monitoring Market
Filters
Drum Filters Market
Filters
Activated Carbon Market
Filters
Global Filter Press Market
Filters
String Wound Filter Materials Market
Filters
Filter Bag Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Global Baghouse Filters Market
Filters
United States Activated Carbon Market
Filters
Compact Filters Market
Filters
Global Lamella Clarifier Market