
 Filter Coatings Market | 2026-2036
Filter Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Filter Coatings Market Intelligence
The bundling of hydrophobic and anti-reflective coatings into single-application solutions is rebalancing buyer preferences toward suppliers offering integrated performance. This shift favors large-scale producers with deep material science expertise. HOYA Corporation leverages its extensive portfolio in optical applications to meet this demand. Meanwhile, Schott AG specializes in high-performance glass-based coatings for industrial and aerospace end-users.
Filter coatings are ultra-thin layers of material applied to a substrate to selectively transmit, reflect, or absorb light at specific wavelengths. These coatings are often deposited using physical vapor deposition processes to achieve precise optical properties. Anti-reflective coatings dominate the market by volume, driven by widespread use in electronics and optical devices. The automotive end-user segment represents the fastest-growing area, fueled by the integration of advanced driver-assistance systems.
Regulations like the EU's RoHS directive restrict the use of hazardous substances in electronic equipment, influencing material selection for coatings. In the United States, FDA guidelines for medical optical devices impose stringent quality and biocompatibility standards on associated coatings. Future competitive advantage will hinge on developing coatings that meet both performance benchmarks and evolving environmental compliance mandates.
Market Dynamics
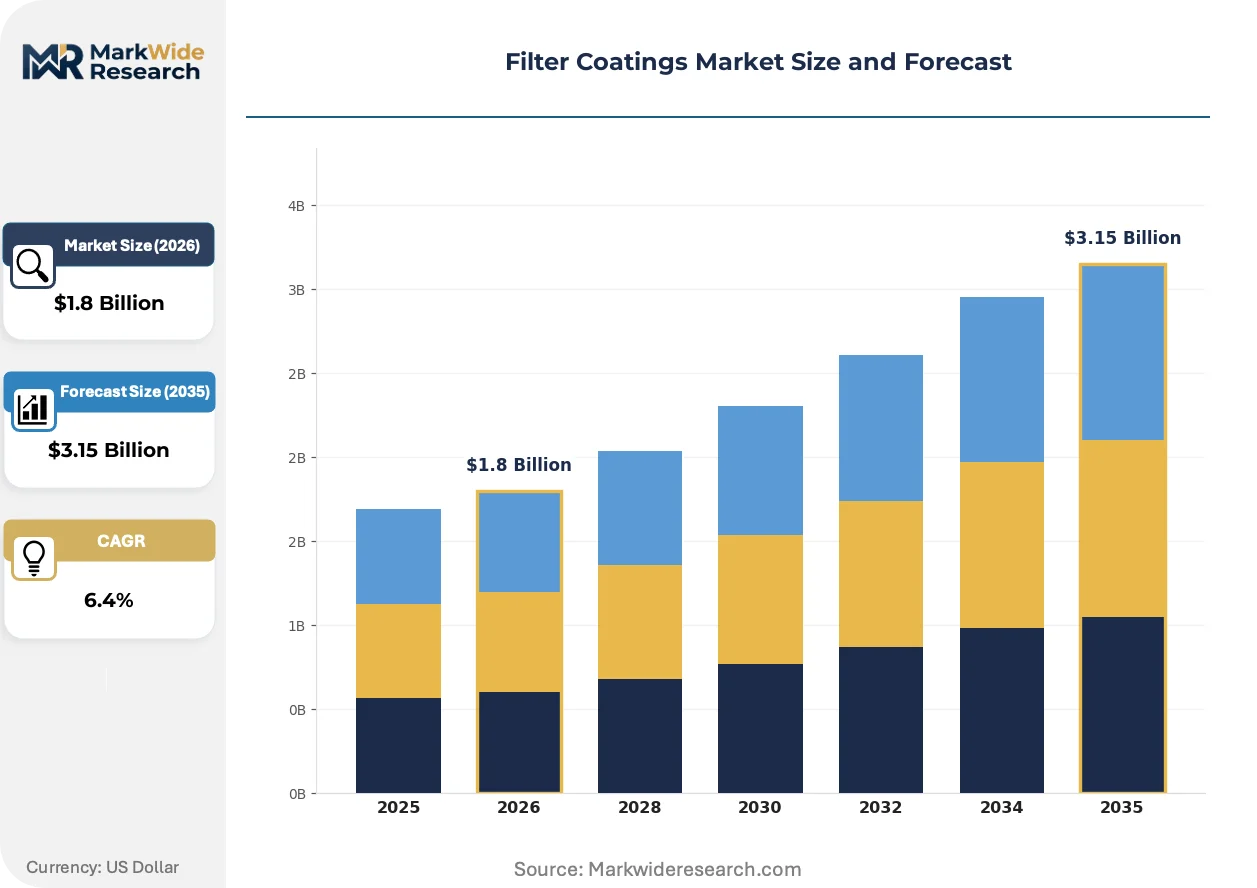
The central dynamic shaping the filter coatings market is the tension between escalating performance requirements from advanced optical systems and intensifying regulatory pressure on material composition. This forces innovation toward multi-functional coatings that meet both advanced technical specifications and stringent environmental compliance mandates like the EU's REACH framework.
Growth Catalysts
- Automotive Sensor Proliferation:Demand for LiDAR, camera, and infrared sensors in advanced driver-assistance systems (ADAS) creates a direct pull for anti-reflective, hydrophobic, and bandpass filter coatings to ensure sensor reliability in all weather conditions.
- Medical Device Standards:Stringent US FDA guidelines for optical components in diagnostic and surgical equipment mandate biocompatible and durable coatings, driving adoption of high-grade materials for endoscopes, imaging systems, and lab instruments.
- Manufacturing Concentration:The deepening of production capabilities within specialized industrial clusters in China provides economies of scale and supply chain efficiencies, lowering costs for mass-market consumer electronics and optical device applications.
Market Restraints
- Raw Material Volatility:The price and supply of specific rare earth oxides and metals, such as tantalum and niobium, used in high-refractive-index coatings are subject to geopolitical factors, creating input cost instability for manufacturers.
- Deposition Process Complexity:Achieving uniform, defect-free coatings across large or complexly shaped substrates remains a significant technical hurdle, leading to yield losses and higher production costs, especially for multi-layer stacks.
- Substitution from Advanced Polymers:The development of high-clarity polymers with integrated optical properties presents a long-term substitution threat, potentially replacing coated glass or plastic substrates in less demanding, cost-sensitive applications.
Strategic Opportunities
- Augmented and Virtual Reality Optics:The emerging market for AR and VR headsets creates a new frontier for specialized coatings that manage light, reduce glare, and enable see-through display functionalities on complex waveguide optics.
- Coatings for Agritech Sensors:Development of filter coatings for multispectral imaging sensors used in precision agriculture can optimize crop monitoring by isolating specific light wavelengths relevant to plant health and soil conditions.
- Expansion in India's Industrial Sector:India's growing manufacturing base for electronics, automotive components, and medical devices presents an underpenetrated market for domestic and international coating suppliers to establish local finishing capabilities.
Industry Challenges
- Deposition Technology Expertise:A persistent shortage of skilled engineers and technicians proficient in operating and maintaining complex physical vapor deposition (PVD) and chemical vapor deposition (CVD) equipment hampers production scalability.
- High Capital Investment:The acquisition and installation of state-of-the-art vacuum deposition chambers, metrology tools, and Class 100 cleanroom facilities require significant upfront capital, creating high barriers to entry for new players.
- Certification and Qualification Cycles:Lengthy and costly qualification processes for coatings in aerospace and defense applications, governed by strict military specifications, delay the introduction of new materials and slow revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filter Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Anti-Reflective, Hydrophobic, Oleophobic, Photocatalytic End User: Automotive, Aerospace, Electronics, Industrial Application: Water Treatment, Air Purification, Photovoltaics, Optical Devices Material: Silica, Titanium Dioxide, Polyurethane, Glass |
| Companies Covered | ZEISS Group, Essilor International, HOYA Corporation, Schott AG, AGC Inc., Inrad Optics, Newport Corporation, Abrisa Technologies, Denton Vacuum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filter Coatings Market Strategic Shifts & Innovations
Material science innovation is focused on developing coatings that deliver enhanced optical performance while complying with global substance-of-concern regulations. This dual pursuit is pushing development away from traditional materials toward more sustainable and multifunctional alternatives that can be applied using environmentally cleaner deposition processes.
Atomic layer deposition (ALD) provides a method for applying ultra-thin, highly conformal coatings with angstrom-level precision. Semiconductor fabricators and manufacturers of high-end optical components are adopting ALD for its superior uniformity and control over film thickness. This technology's precision is electrifying the development of next-generation micro-optics and complex sensors, enabling new device functionalities and smaller form factors.
China's Ministry of Ecology and Environment (MEE) is enforcing stricter controls on volatile organic compound (VOC) emissions from industrial manufacturing. This action compels filter coating applicators to shift from solvent-based processes to environmentally benign technologies like physical vapor deposition. The consumer electronics and automotive supply chains are most impacted, prioritizing vendors who can demonstrate compliance with these new environmental standards.
Buyers in regulated industries are increasingly qualifying the entire coated optical component as a system rather than procuring substrates and coatings separately. This behavior disrupts the traditional model of using specialized, small-scale coating job shops, favoring integrated suppliers who can manage the substrate, coating, and final metrology. This trend is most visible in the North American medical device and European aerospace sectors.
Filter Coatings Market Segmentation
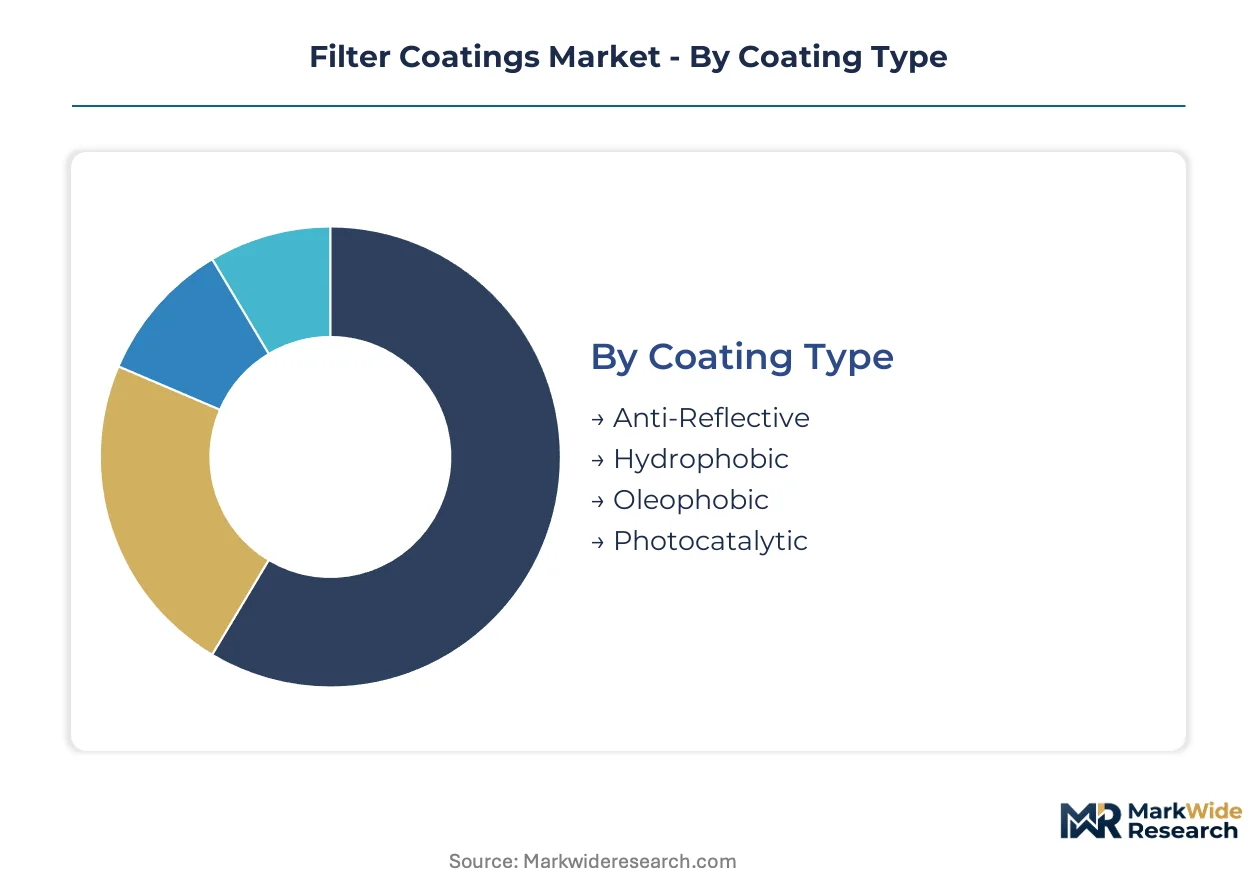
Filter coatings are critical for optimizing optical performance across diverse applications. Understanding market segmentation reveals how material science and deposition technologies align with end-user demands. This granular view highlights areas of concentrated value creation and future growth.
Coating Type:
The supply of filter coatings is concentrating towards multi-functional solutions that integrate several performance attributes into a single layer.
- Anti-Reflective:These coatings reduce light reflection from surfaces, enhancing light transmission and image clarity. Demand concentrates in consumer electronics displays and optical sensors for ADAS in the automotive sector, driven by reliability requirements.
- Hydrophobic:Hydrophobic coatings repel water, preventing fogging and improving visibility on optical surfaces. Automotive sensor systems and outdoor surveillance cameras in Europe demand these coatings for all-weather functionality.
- Oleophobic:Oleophobic coatings repel oils and fingerprints, maintaining surface cleanliness on touchscreens and camera lenses for consumer devices.
- Photocatalytic:Photocatalytic coatings use light to break down organic pollutants, primarily for self-cleaning surfaces in architectural and environmental applications.
Today's leader: Anti-Reflective. Tomorrow's challenger: Hydrophobic.
End User:
Cost-tiering for filter coatings varies significantly across end-user segments, reflecting differing performance needs and regulatory burdens.
- Automotive:This segment integrates coatings into LiDAR, camera, and infrared sensors for advanced driver-assistance systems, requiring high durability and environmental resistance. The push for autonomous driving systems in Germany and Japan drives significant investment in advanced coating solutions.
- Electronics:Electronics utilize coatings for displays, camera lenses, and optical components in smartphones and tablets. Volume demand for anti-reflective and oleophobic coatings is immense, particularly from Asian manufacturers.
- Aerospace:Aerospace applications demand extremely robust and lightweight coatings for cockpit displays, satellite optics, and sensor windows.
- Industrial:Industrial uses include optical filters for manufacturing processes, machine vision systems, and specialized lighting.
The Automotive sector exhibits the steepest expansion trajectory. The Aerospace sector maintains stringent performance requirements.
Application:
The volume of filter coatings consumed is heavily influenced by specific application requirements, from light management to environmental protection.
- Optical Devices:Filter coatings are fundamental to optical devices, selectively transmitting or blocking light for improved signal-to-noise ratios. Consumer electronics and medical imaging systems in the United States drive substantial demand for high-precision coatings.
- Water Treatment:These coatings are applied to membranes and sensors for water purification and quality monitoring. Environmental regulations and infrastructure projects in China are increasing the adoption of advanced filtration technologies.
- Air Purification:Coatings for air purification systems target volatile organic compounds and particulate matter, enhancing filter efficiency in industrial and residential settings.
- Photovoltaics:Coatings for photovoltaic panels minimize reflection losses and improve light absorption, increasing solar cell efficiency.
Optical Devices are currently gaining share fastest. Water Treatment applications are also expanding rapidly.
Material:
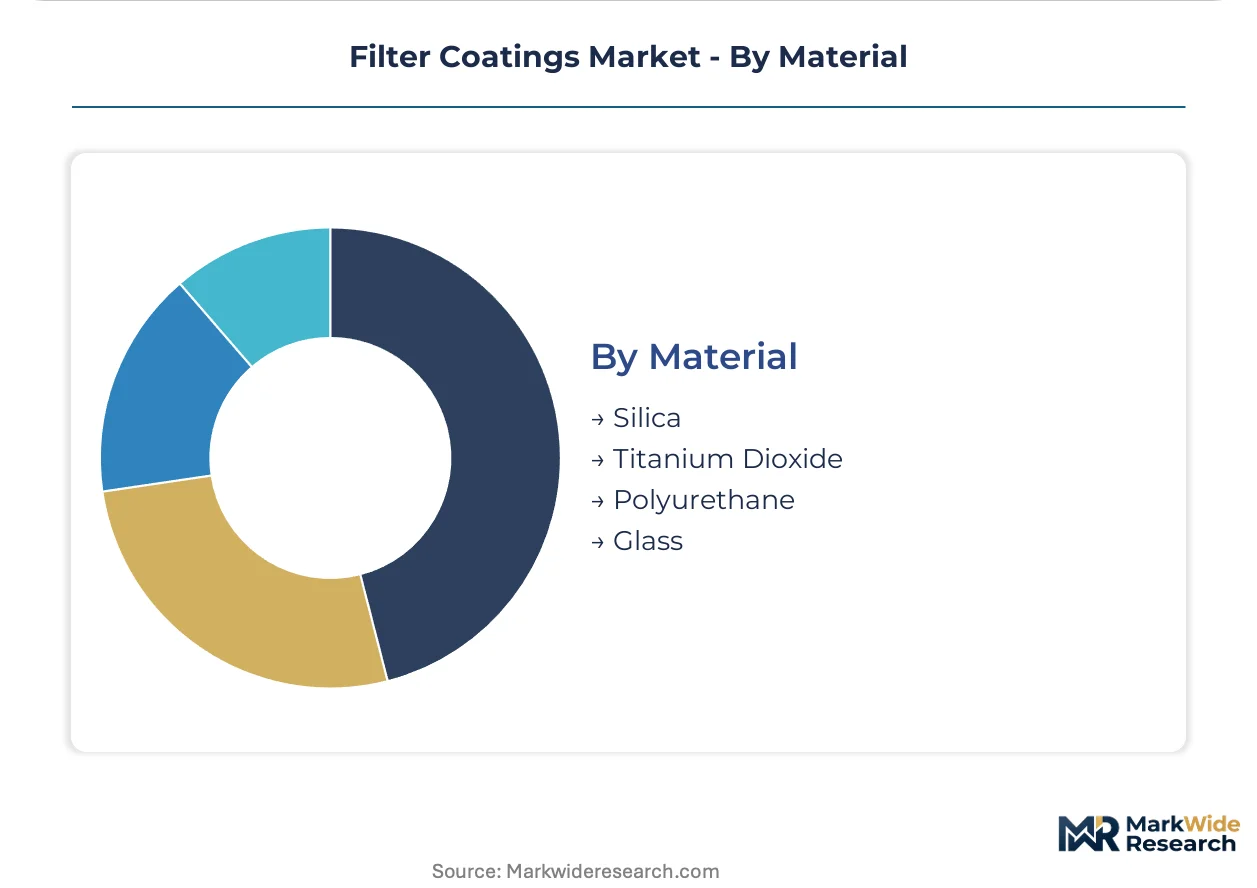
Material selection for filter coatings is often dictated by the desired optical properties and the specific application environment.
- Titanium Dioxide:This high-refractive-index material is crucial for multi-layer dielectric coatings, offering excellent optical performance and durability. Demand for advanced optical filters and protective layers in high-power laser systems is significant.
- Silica:Silica is a versatile material used for both anti-reflective and protective coatings due to its hardness and chemical inertness. It sees widespread use in consumer electronics and architectural glass applications across Europe.
- Polyurethane:Polyurethane coatings provide flexibility and impact resistance, often used as protective layers on plastic substrates.
- Glass:Glass-based coatings, especially for high-performance optics, offer superior scratch resistance and thermal stability.
Titanium Dioxide is climbing the fastest. Silica remains a foundational material.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The filter coatings industry initially scaled in regions with advanced optical manufacturing capabilities, driving early demand for precision light management. Today, regional dynamics reflect a complex interplay of regulatory frameworks, technological adoption, and industrial concentration. Specific national markets exhibit distinct growth trajectories based on their dominant end-user segments and material science investments.
China
China's deepening production capabilities for consumer electronics and optical devices fuel immense demand for filter coatings. The Ministry of Ecology and Environment (MEE) enforces stricter controls on volatile organic compound emissions, influencing coating applicator material choices. Industrial clusters in the Yangtze River Delta and Pearl River Delta concentrate significant manufacturing for mass-market optical components.
United States
Stringent US FDA guidelines for medical optical devices drive demand for high-grade, biocompatible filter coatings in diagnostic and surgical equipment. The integration of advanced driver-assistance systems in the automotive sector also creates a pull for specialized sensor coatings. Major technology hubs like Silicon Valley and the Boston-Cambridge area lead innovation in optical devices and medical imaging systems.
Germany
The German automotive sector, particularly its push for autonomous driving systems, requires durable and environmentally resistant filter coatings for LiDAR and camera sensors. European aerospace regulations demand robust and lightweight coatings for cockpit displays and satellite optics. Bavaria and Baden-Württemberg host significant automotive and industrial optics manufacturing, fostering coating innovation.
Japan
Japan's advanced electronics and automotive industries generate consistent demand for high-performance anti-reflective and hydrophobic coatings. The Ministry of Economy, Trade and Industry (METI) supports research into next-generation optical materials and manufacturing processes. Key industrial regions like Kanto and Chubu are centers for precision optics and automotive component production.
India
India's expanding manufacturing base for electronics, automotive components, and medical devices presents a significant growth opportunity for filter coating suppliers. The PLI scheme encourages domestic production across several sectors, increasing local demand for advanced materials. Industrial corridors in Maharashtra and Tamil Nadu are witnessing increased investment in optical and electronic manufacturing facilities.
Filter Coatings Market Key Industry Players
Premium-margin players sit above commodity-margin players across material science expertise and application specificity, creating a tiered market structure. The industry sees large-scale producers providing integrated performance solutions alongside specialized niche players focused on high-performance applications. Strategic archetypes include integrated optical solution providers, high-performance glass specialists, and volume-driven electronics suppliers. Capacity expansion and strategic partnerships remain dominant competitive moves across the market.
Among specialized optical solution providers, HOYA Corporation exemplifies a strategy of leveraging an extensive portfolio in optical applications to meet integrated performance demands. Schott AG occupies a position as a high-performance glass-based coatings specialist, serving industrial and aerospace end-users with stringent requirements. These companies anchor the premium segment by offering advanced material science expertise and application-specific solutions.
| Leading Market Players |
|---|
| ZEISS Group |
| Essilor International |
| HOYA Corporation |
| Schott AG |
| AGC Inc. |
| Inrad Optics |
| Newport Corporation |
| Abrisa Technologies |
| Denton Vacuum |
Cost & Logistics Intelligence
China's Ministry of Ecology and Environment (MEE) mandates stricter VOC emission controls, gating access for less compliant suppliers and creating a premium for advanced deposition technologies. This regulatory pressure influences both pricing dynamics and the geographic concentration of qualified manufacturing capabilities.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing in the filter coatings market, particularly for high-volume automotive and electronics applications. Price differentiation stems from the certification level required for specific end-uses, such as US FDA approval for medical devices, and the customization level for specialized optical components. Pricing softness reflects intense competition in mass-market consumer electronics, while highly specialized aerospace coatings maintain stronger margins. Electronics manufacturers are generally more price-sensitive compared to buyers in the regulated medical device sector.
Supply Chain Analysis
Logistics costs significantly impact filter coating pricing, especially for high-purity raw materials and specialized equipment. Geographic supply concentration for critical rare earth oxides and metals, such as tantalum and niobium, resides primarily in China, creating a potential single-source vulnerability. The supply chain relies heavily on specialized physical vapor deposition equipment from suppliers in Germany and Japan. Distribution runs through a mix of direct sales to large original equipment manufacturers and specialized distributors serving smaller industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in filter coatings stems from the increasing demand for integrated performance solutions in advanced optical systems. This shift allows for premium pricing on multi-functional coating bundles.
For Market Incumbents:Cement market leadership through sustained research and development investment in advanced material science, particularly for atomic layer deposition techniques. Expand production capacity in China's industrial clusters to counter emerging regional competitors and leverage economies of scale. The threat of substitution from advanced polymers necessitates continuous innovation in glass-based optical performance. Vertical integration into upstream raw material sourcing provides a strategic lever against input cost volatility.
For New Entrants and Emerging Players:A significant price-point gap exists between high-performance aerospace coatings and mass-market consumer electronics applications. Target underpenetrated industrial sectors in India, focusing on local finishing capabilities for medical devices and automotive components. Develop specialized coatings for agritech sensors, offering a unique value proposition for precision agriculture. A go-to-market angle centered on rapid prototyping and customizable solutions will attract niche buyers seeking tailored performance.
For Investors and Strategic Acquirers:Roll-up economics work for specialized coating solution providers because of the fragmented nature of niche application markets, particularly in medical and industrial optics. The long-term viability of this sector spans beyond a decade, driven by optical system advancements and evolving regulatory compliance. Acquisition targets should include mid-sized firms with proprietary deposition technologies or unique material science patents. Watch for increasing M&A activity in augmented and virtual reality optics as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in ALD Technology | Enhances precision for next-generation micro-optics and complex sensors in high-value applications. |
| Expand Production in China | Optimizes cost structures and access to the largest electronics and optical device manufacturing base. |
| Develop Agritech Sensor Coatings | Addresses a new, high-growth application area by enabling precise crop monitoring functionalities. |
| Acquire Material Science Startups | Secures intellectual property and expertise in novel coating materials for future performance demands. |
| Strengthen Regulatory Compliance | Ensures market access and competitive advantage in highly regulated sectors like medical and aerospace. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Key stakeholders included R&D directors, procurement managers at automotive OEMs, medical device engineers, and physical vapor deposition equipment suppliers. Secondary data sources comprised industry association reports, government regulatory filings, and company financial disclosures. This approach ensured bottom-up market sizing triangulated with top-down industry trends.
Segment-weighting approached market sizing by analyzing end-user demand across various applications and coating types over the projection horizon. The analytical framework incorporated material science advancements, regulatory impacts, and regional manufacturing shifts. Compound annual growth rates were derived from historical performance and anticipated technological adoption. Key forecast inputs included ADAS sensor integration rates and cleanroom facility investment trends.
The model assumes a particular technology adoption path; alternative pathways for advanced polymers or novel deposition techniques would alter the outlook. Forecasts reflect assumptions about raw material stability and geopolitical influences. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Filtration and Separation Market
Filters
Global Sterile Filtration Market
Filters
Global Filter Press Market
Filters
Residential Filters Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Intake Filter Media Market
Filters
Global Pleated Filters Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Anti-Microbial Filter Market
Filters
Europe Industrial Air Filtration Market
Filters
Industrial Filtration Market
Filters
Hydraulic Filters Market
Filters
Color Filter Glass Market
Filters
String Wound Filter Materials Market
Filters
Global Laboratory Filtration Market
Filters
Ceramic Filters Market