
 Europe Pharmaceutical Isolator Market | 2026-2036
Europe Pharmaceutical Isolator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Isolator Market Foresight
EU Annex 1 revision is broadening the cost-of-entry calculus for sterile manufacturing infrastructure across Europe. COMECER SpA leverages its Italian engineering base to dominate aseptic isolator production for radiopharmaceutical applications. Getinge AB anchors Nordic supply chains through integrated decontamination and isolation platforms. SKAN AG competes on precision-manufactured barrier systems tailored to Swiss pharmaceutical quality standards.
Pharmaceutical isolators are sealed, pressure-controlled enclosures engineered to maintain ISO 5/Grade A air cleanliness through HEPA-filtered unidirectional airflow, designed for aseptic processing, sterility testing, or potent compound containment. Aseptic isolators lead product type demand as parenteral drug manufacturing expands, while containment isolators capture premium margins from oncology and hormone therapy production. Static isolators retain mature market share in quality control laboratories, though dynamic isolators gain traction in continuous manufacturing lines where real-time material transfer is required.
EMA guidelines, EU GMP Annex 1, and CE marking requirements collectively mandate validated barrier separation for sterile operations, directly shaping procurement specifications and vendor qualification timelines. ECHA frameworks on occupational exposure limits further compel investment in containment isolators for high-potency active pharmaceutical ingredients. Stakeholders must weigh modular installation flexibility against dedicated suite throughput economics as multi-product facilities proliferate across European biopharma hubs.
Market Dynamics
The EU Annex 1 revision is compressing vendor qualification timelines and forcing pharmaceutical manufacturers to revalidate entire sterile processing suites, accelerating capital redeployment toward barrier isolation technology.
Growth Catalysts
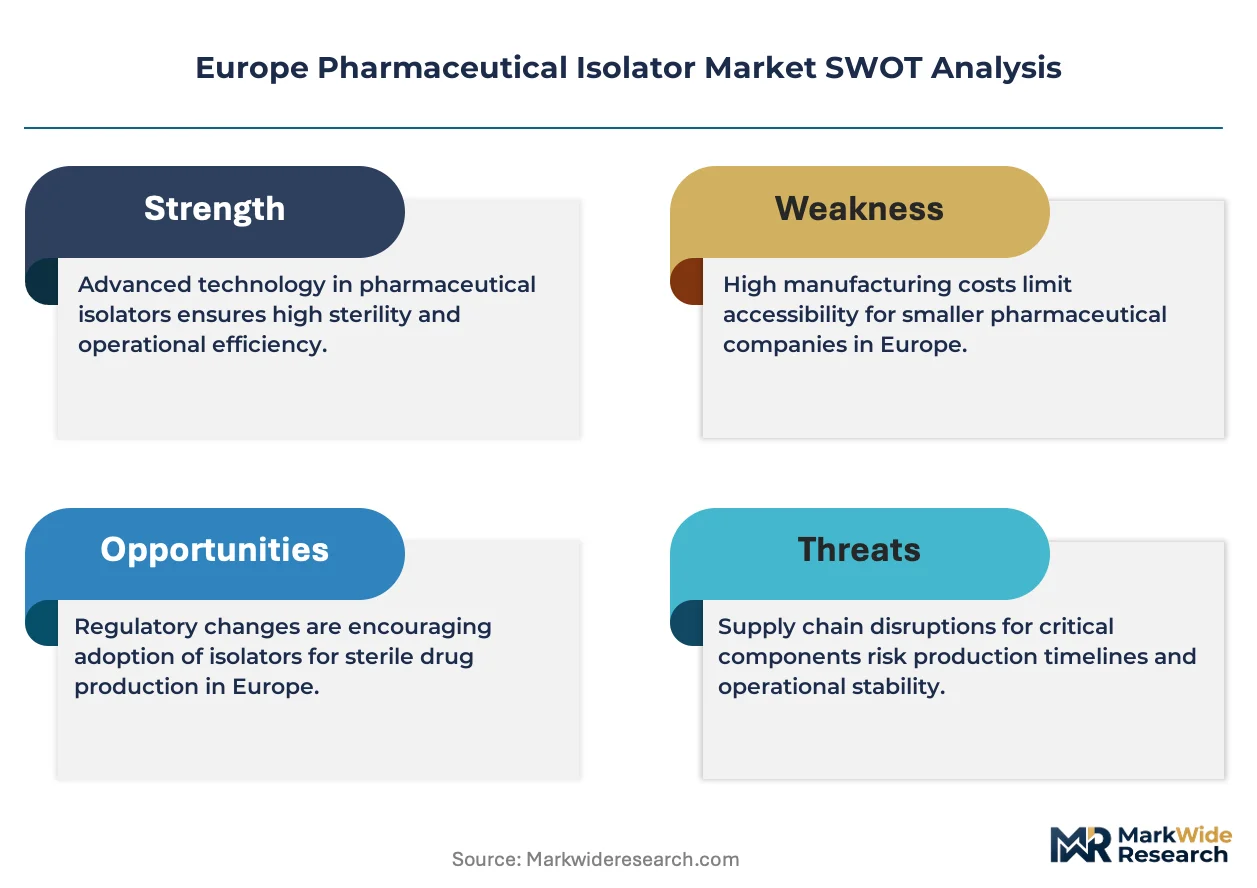
- EU GMP Annex 1 Contamination Control Mandate:The revised annex mandates physical barrier separation for Grade A operations, compelling sterile injectable manufacturers to retrofit existing cleanrooms with validated isolator systems.
- Radiopharmaceutical Manufacturing Expansion:Positron emission tomography (PET) tracer production facilities across Germany and France require lead-shielded aseptic isolators for short-half-life isotope handling.
- High-Potency API Containment Requirements:ECHA occupational exposure limit frameworks for cytotoxic compounds are driving oncology drug producers toward negative-pressure containment isolators with OEB 5 capability.
Market Restraints
- Stainless Steel and HEPA Filter Supply Concentration:Premium-grade 316L stainless steel and validated HEPA media concentrate among German and Swiss specialty suppliers, exposing procurement to input cost volatility.
- Extended CE Marking Validation Cycles:The EU Medical Device Regulation (MDR) reclassification of certain isolator configurations as Class IIa devices has lengthened notified body review timelines by 8-14 months.
- Modular Cleanroom Substitutes:Rapid-deployment restricted access barrier systems (RABS) offer lower capital entry points for mid-scale sterile operations, fragmenting demand at the economy tier.
Strategic Opportunities
- Central and Eastern European Biopharma Greenfield Investment:Poland and Hungary are attracting fill-finish contract manufacturing organizations seeking EU-accessible production capacity with modern isolator infrastructure.
- Continuous Manufacturing Integration:Real-time material transfer isolators enabling powder-to-injectable processing lines represent unpenetrated white space as batch-to-continuous conversion accelerates.
- EU Green Deal Energy Efficiency Incentives:Isolator systems with heat recovery and low-energy fan filter units qualify for national green transition subsidies in the Netherlands and Denmark.
Industry Challenges
- Contamination Control Strategy Documentation Burden:The Annex 1 requirement for holistic CCS documentation demands specialized quality assurance personnel scarce across European contract manufacturing organizations.
- Legacy Facility Retrofit Integration Complexity:Installing isolators within 1990s-era sterile suites requires structural reinforcement and HVAC rebalancing that disrupts validated environmental monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Isolator Market |
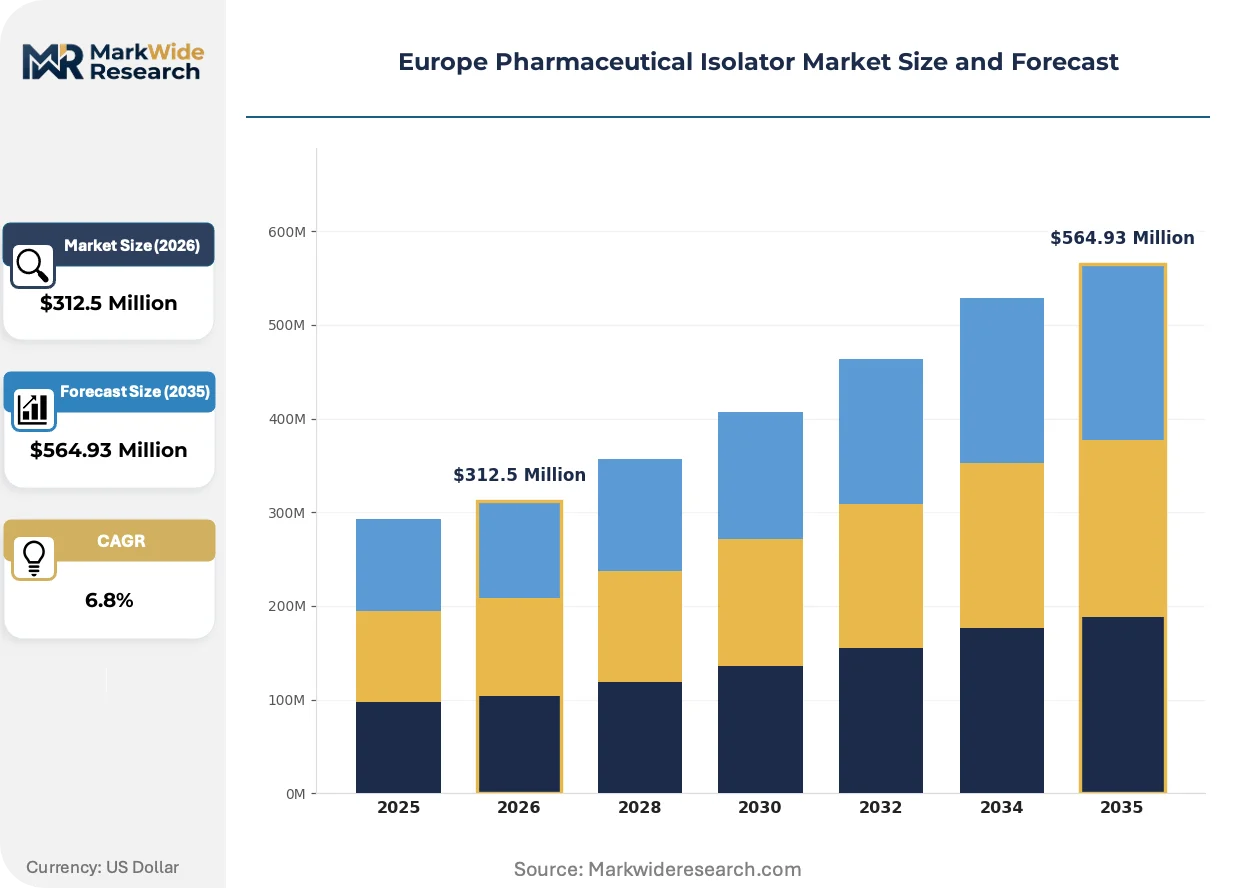
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zone Isolators, Aseptic Isolators, Containment Isolators, Sterility Test Isolators Technology: Static Isolators, Dynamic Isolators, Mobile Isolators, Barrier Isolators End User: Pharmaceutical Manufacturers, Research Laboratories, Contract Manufacturing Organizations, Biotech Companies Installation: Room Based, Modular, Dedicated Suite, Mobile |
| Companies Covered | COMECER SpA, M Braun Inertgas-Systeme GmbH, Getinge AB, Extract Technology Ltd., Azbil Telstar, SKAN AG, Fedegari Group, Tema Sinergie, Syntegon Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Isolator Market Shifts & Advancements
Isolator engineering is converging with digital process control and sustainable manufacturing mandates, compressing the traditional separation between physical barrier systems and data-driven contamination monitoring.
Single-use isolator interior technologies incorporating gamma-sterilized flexible film enclosures are rewriting capital deployment economics for multi-product biopharma facilities. Contract manufacturing organizations in Belgium and the Netherlands are adopting these systems to eliminate changeover cleaning validation between campaigns. The technology is compressing facility downtime from days to hours while reducing water-for-injectables consumption.
EMA guidance on data integrity and EU GMP Annex 11 computer system validation is mandating electronic batch records and environmental monitoring integration within isolator control architectures. Sterile drug manufacturers must now qualify isolator supervisory control and data acquisition (SCADA) systems alongside physical containment performance. This regulatory pressure is most acute in Germany, where large-volume parenteral producers are retrofitting legacy isolators with compliant data management layers.
Service unbundling is fragmenting traditional equipment-procurement relationships as pharmaceutical quality departments demand independent isolator performance qualification separate from vendor installation protocols. Third-party engineering consultancies in Switzerland and the UK are capturing validation-phase contracts that equipment suppliers previously retained. This behavioral shift is most visible among mid-cap European biotechs lacking in-house sterile processing expertise.
Europe Pharmaceutical Isolator Market Segmentation
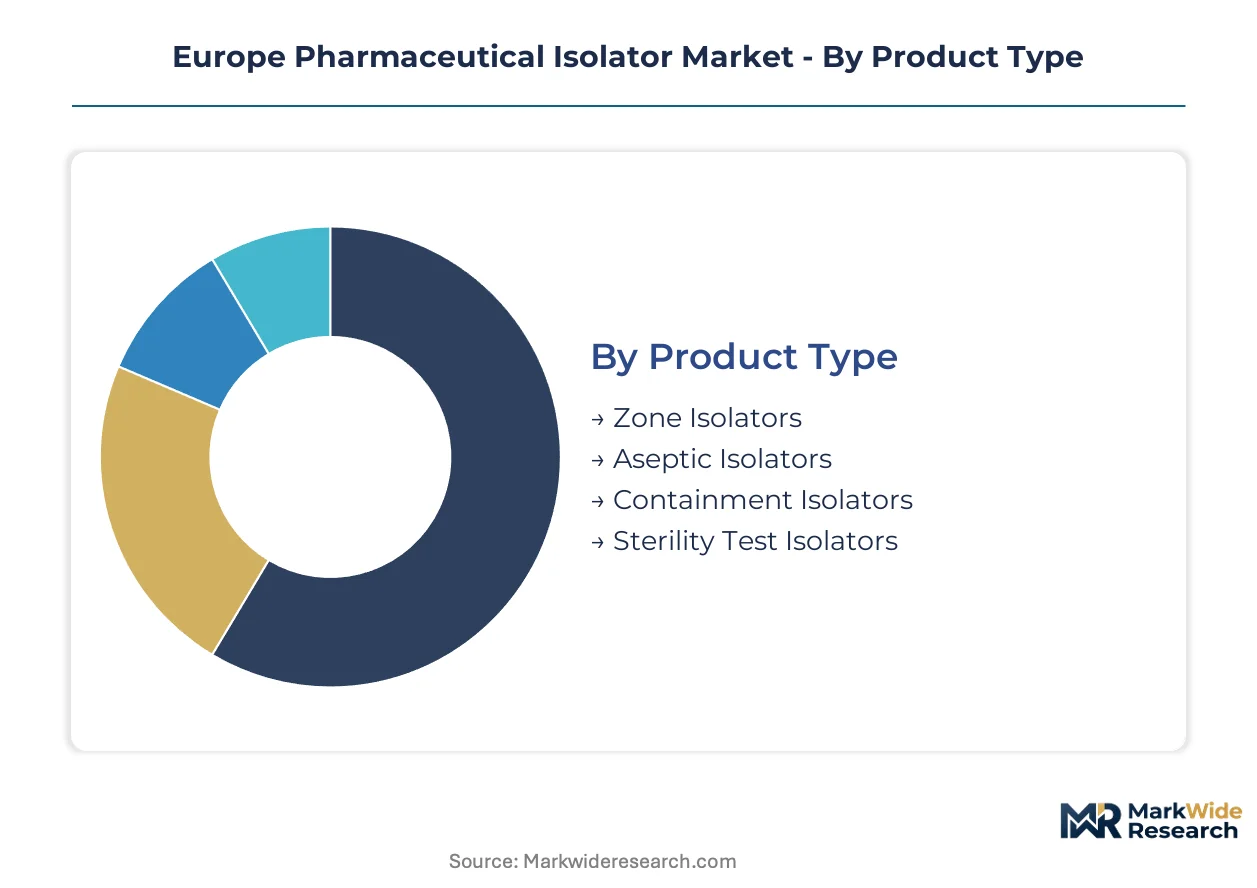
Pharmaceutical isolator procurement decisions in Europe pivot on contamination risk profiles, facility retrofit constraints, and multi-product operational flexibility. Segmentation reveals how EMA compliance mandates and manufacturing scale interact to determine technology selection across the region's sterile drug production ecosystem.
Product Type:
Buyer priorities center on barrier performance specifications required for specific drug categories and EMA contamination control mandates.
- Aseptic Isolators:These systems maintain ISO 5/Grade A unidirectional airflow through HEPA-filtered positive pressure enclosures designed for sterile injectable manufacturing. German parenteral drug producers dominate capital deployment here, driven by EU GMP Annex 1 mandates for physical barrier separation in Grade A operations.
- Containment Isolators:Negative-pressure enclosures engineered for OEB 5 capability with HEPA filtration on exhaust streams, protecting operators from high-potency APIs. Swiss and Belgian oncology drug manufacturers represent concentrated demand as ECHA occupational exposure frameworks tighten across the region.
- Sterility Test Isolators:Compact units for finished product sterility verification in quality control laboratories.
- Zone Isolators:Segmented barrier systems enabling simultaneous processing of different contamination risk levels within single enclosures.
Aseptic isolators lead on scale; containment isolators lead on momentum.
Technology:
Operational throughput requirements and continuous manufacturing adoption determine technology selection across European facilities.
- Dynamic Isolators:Systems incorporating real-time material transfer mechanisms through rapid transfer ports or continuous processing interfaces, enabling powder-to-injectable manufacturing lines. Dutch and Irish contract manufacturing organizations are expanding installations as batch-to-continuous conversion accelerates in biologics production.
- Static Isolators:Sealed enclosures without active material transfer during operation, relying on pre-sterilized component introduction. These retain substantial installed base across French and Italian quality control laboratories where batch processing economics remain favorable.
- Mobile Isolators:Self-contained units on castor systems for flexible deployment across multi-product suites.
- Barrier Isolators:Integrated wall-mounted systems forming permanent cleanroom boundaries.
Static isolators dominate current installed base; dynamic isolators show steepest expansion trajectory.
End User:
Capital availability and in-house sterile processing expertise shape procurement patterns across organizational types.
- Pharmaceutical Manufacturers:Large-volume parenteral producers with dedicated sterile suites and internal validation capabilities. German and Swiss originator companies anchor regional demand, investing in integrated isolator-decontamination platforms for blockbuster biologic portfolios.
- Contract Manufacturing Organizations:Fill-finish specialists serving multiple clients with campaign-based production models. Polish and Hungarian CMOs are expanding isolator infrastructure to capture biopharma outsourcing flows seeking EU-accessible capacity.
- Biotech Companies:Mid-scale innovators requiring flexible isolator configurations for clinical-to-commercial transitions.
- Research Laboratories:Academic and institutional users with lower-throughput sterility testing requirements.
Pharmaceutical manufacturers command the largest capital commitments; contract manufacturing organizations are gaining share fastest.
Installation:
Facility vintage and multi-product operational strategies determine architectural integration approaches.
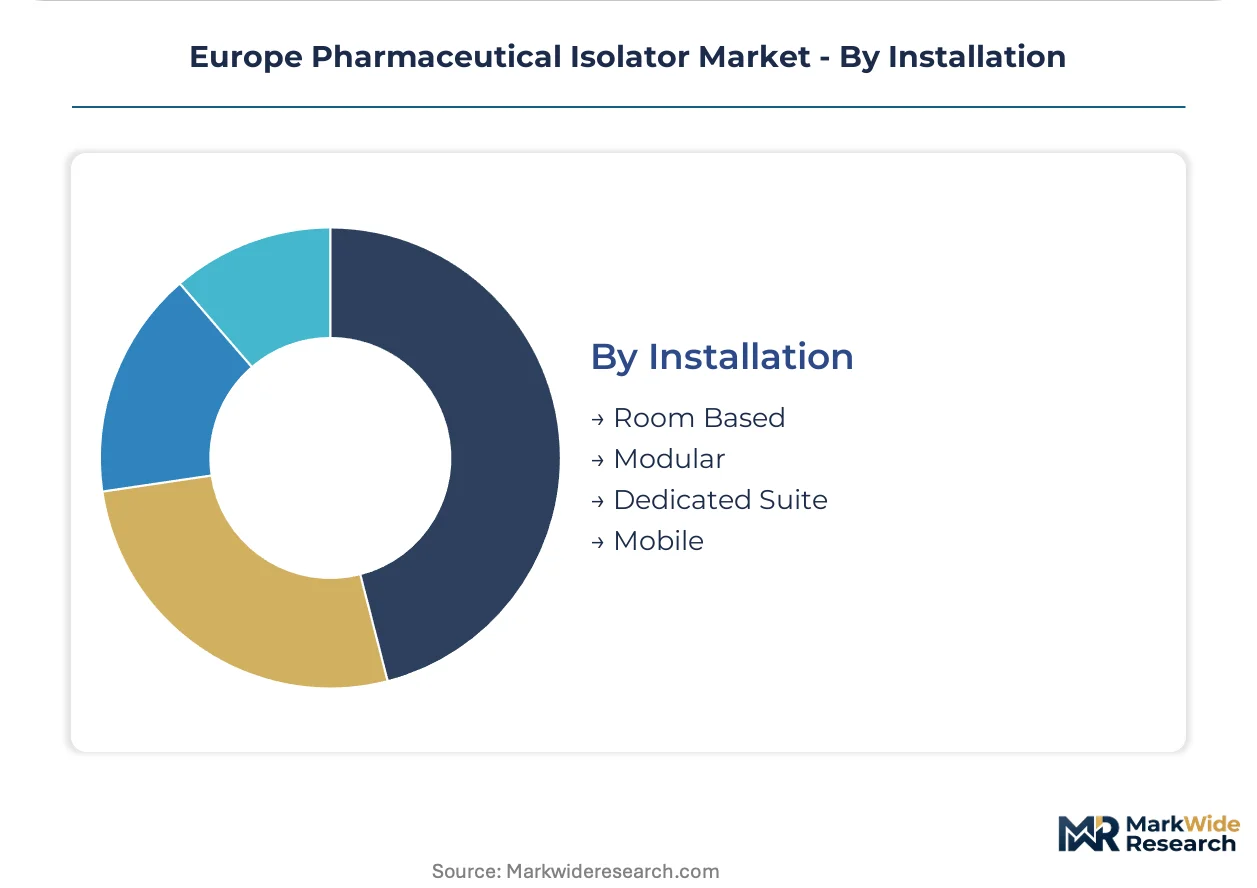
- Modular:Pre-fabricated isolator systems with standardized dimensions enabling rapid deployment and future relocation. Belgian and Netherlands biotech facilities favor these for portfolio flexibility and reduced structural modification requirements.
- Dedicated Suite:Permanently integrated isolator configurations within purpose-built sterile processing rooms. Large-scale German biopharma campuses deploy these for high-volume monoclonal antibody production where throughput optimization outweighs flexibility premiums.
- Room Based:Isolators installed within existing cleanroom envelopes requiring HVAC rebalancing.
- Mobile:Freestanding units deployable across multiple processing areas without fixed installation.
Dedicated suite installations represent the largest committed capital; modular configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European pharmaceutical isolator demand concentrates where sterile manufacturing expertise and regulatory enforcement intersect most intensely. Specialist engineering talent clusters in Alpine and Nordic regions anchor barrier technology development.
Germany
Large-volume parenteral producers in Bavaria and North Rhine-Westphalia drive capital deployment in integrated isolator-decontamination platforms. EU GMP Annex 1 mandates for physical barrier separation in Grade A operations compel retrofit investments across legacy sterile suites. The Rhine-Main biopharma corridor hosts multiple monoclonal antibody fill-finish facilities where dedicated suite installations dominate throughput planning.
Switzerland
Oncology drug manufacturers in Basel and Zurich require negative-pressure containment isolators with OEB 5 capability for cytotoxic API handling. ECHA occupational exposure limit frameworks tighten procurement specifications for high-potency compound processing. Swissmedic enforcement of barrier validation protocols accelerates vendor qualification timelines for regional biotechs.
Netherlands
Contract manufacturing organizations in the Randstad region adopt single-use isolator technologies to compress campaign changeover downtime. EU Green Deal energy efficiency incentives subsidize heat recovery and low-energy fan filter unit installations. Belgian and Dutch biotech facilities favor modular configurations for multi-product operational flexibility.
France
PET tracer production facilities in Île-de-France require lead-shielded aseptic isolators for short-half-life isotope handling. ANSM guidance on radiopharmaceutical manufacturing infrastructure shapes capital allocation for nuclear medicine expansion. The Paris-Saclay cluster concentrates demand for sterility test isolators in quality control laboratories serving regional pharma networks.
Poland
Fill-finish contract manufacturing organizations in Warsaw and Kraków expand isolator infrastructure to capture biopharma outsourcing flows seeking EU-accessible production capacity. National investment incentives for pharmaceutical manufacturing modernization accelerate greenfield facility development. Polish CMOs prioritize modular installations enabling rapid reconfiguration between client campaigns.
Europe Pharmaceutical Isolator Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with decontamination and isolation combined. German and Swiss engineering specialists dominate premium-tier aseptic and containment applications, while Italian fabricators capture radiopharmaceutical niche demand. Two strategic archetypes define positioning: full-suite sterilization-isolation integrators, and precision barrier specialists serving high-containment oncology manufacturing. Competitive moves concentrate on capacity expansion in Central European biopharma corridors and technology licensing for continuous manufacturing integration.
Within the integrated platform tier, Getinge AB anchors Nordic supply chain presence through combined decontamination and isolation offerings. COMECER SpA exemplifies radiopharmaceutical specialization leveraging Italian engineering capabilities for lead-shielded aseptic systems. SKAN AG occupies a position among precision-manufactured barrier fabricators aligned with Swiss pharmaceutical quality standards. These three represent distinct competitive vectors: sterilization integration, nuclear medicine containment, and precision barrier engineering.
| Leading Market Players |
|---|
| COMECER SpA |
| M Braun Inertgas-Systeme GmbH |
| Getinge AB |
| Extract Technology Ltd. |
| Azbil Telstar |
| SKAN AG |
| Fedegari Group |
| Tema Sinergie |
| Syntegon Technology |
| Others |
Supply & Pricing Matrix
EU GMP Annex 1 retrofit mandates across German and Swiss sterile manufacturing facilities are compressing procurement timelines and forcing buyers toward validated suppliers with CE-marked inventory, elevating pricing power for Tier 1 fabricators while squeezing mid-tier competitors on margin.
Pricing Analysis
Bundled installation-validation service packages command 15-25% premiums over equipment-only transactions across the European market. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-engineered containment systems from Italian radiopharmaceutical specialists and Eastern European fabricators. Pricing pressure stems from rapid-deployment RABS substitutes fragmenting demand at lower capital tiers. Contract manufacturing organizations in Poland and Hungary exhibit highest price sensitivity due to campaign-based utilization models, while German originator companies prioritize qualification speed over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss specialty suppliers of premium-grade 316L stainless steel and validated HEPA filtration media. Component sourcing draws from Alpine metalworking clusters, Nordic fan-filter unit manufacturers, and Italian precision engineering shops. Tariff exposure on specialty steel imports from non-EU sources amplifies input cost volatility for barrier system fabricators. Distribution runs through direct vendor-to-manufacturer relationships for large installations, with regional distributors serving aftermarket parts and smaller CMO accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Pharmaceutical Isolator Market functions as a regulatory compounder where EU GMP Annex 1 contamination control mandates continuously refresh capital deployment cycles across sterile manufacturing infrastructure.
For Market Incumbents: Anticipate accelerated qualification demands from EMA's evolving data integrity guidance by pre-integrating SCADA-compliant environmental monitoring layers into standard isolator architectures. Prioritize capacity expansion in Poland and Hungary to capture CMO outsourcing flows before regional competitors establish local validation support networks. Defend against single-use flexible film substitutes by emphasizing total cost of ownership advantages in high-volume parenteral applications. For New Entrants and Emerging Players: Mid-scale biotech companies transitioning from clinical to commercial manufacturing represent the most penetrable buyer archetype currently underserved by legacy vendor qualification timelines. Target modular isolator configurations with rapid deployment protocols for Belgian and Dutch multi-product facilities requiring campaign flexibility. Establish go-to-market positioning through independent validation partnerships with Swiss and UK engineering consultancies that pharmaceutical quality departments now prefer over bundled vendor protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with precision barrier specialists possessing Swissmedic-validated containment engineering capabilities for oncology manufacturing expansion. Five-to-ten-year viability hinges on continuous manufacturing integration readiness as batch-to-conversion accelerates across biologics. Monitor EMA guidance publication velocity on Annex 1 contamination control strategy documentation as the signal indicating inflection in quality assurance personnel demand and associated service revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration Pathway | EU MDR reclassification compresses notified body review timelines for Class IIa isolator configurations. |
| Continuous Manufacturing Integration | Real-time material transfer isolators enable powder-to-injectable processing lines for biologics conversion. |
| Central European Capacity Expansion | Polish and Hungarian greenfield facilities capture biopharma outsourcing flows seeking EU-accessible production. |
| Single-Use Technology Adoption | Gamma-sterilized flexible film enclosures compress campaign changeover downtime for multi-product CMOs. |
| Energy Efficiency Certification | Heat recovery and low-energy fan filter units qualify for Netherlands and Denmark Green Deal subsidies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured primary discussions with sterile processing engineers, regulatory affairs leads at EMA-notified manufacturers, CMO procurement directors, and validation consultancy principals with secondary triangulation against EMA guidance documents, EU GMP Annex 1 revision texts, Swissmedic enforcement bulletins, and CE marking notified body registration databases. Bottom-up isolator shipment data from German, Swiss, and Italian fabricators reconciled against top-down pharmaceutical capital expenditure disclosures across the region.
Segment-weighting approaches distributed value and volume projections across product type, technology, end user, and installation configuration dimensions, with additional modeling of regulatory compliance tier and facility vintage effects. CAGRs derived from fitted growth curves anchored to documented retrofit timelines and greenfield facility commissioning schedules across the analysis window. Forecast inputs incorporated EMA guidance implementation velocity, ECHA occupational exposure limit revision trajectories, and EU Green Deal subsidy allocation patterns for energy-efficient manufacturing equipment.
Underlying measurement precision varies by segment; aseptic isolator demand in established German parenteral facilities carries tighter precision than emerging radiopharmaceutical containment applications where isotope handling protocols remain in flux. Forecasts reflect documented assumptions on regulatory enforcement consistency and supply chain input cost stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market