
 Epinephrine Auto-Injectors Market | 2026-2036
Epinephrine Auto-Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Epinephrine Auto-Injectors Market Analysis
Homecare settings is consolidating as the fastest-expanding end-use vertical, overtaking traditional hospital-centric distribution as self-administration training programs expand. Viatris leverages its established retail pharmacy channel network to sustain brand presence across North American drugstore chains. Teva Pharmaceutical Industries anchors the generic segment with FDA-approved alternatives that compete aggressively on price against originator products. Kaléo differentiates through voice-instruction technology embedded in its delivery platform, occupying a premium niche for caregiver-assisted administration.
Epinephrine auto-injectors are spring-loaded or electronic drug-delivery devices pre-filled with a measured dose of epinephrine, typically 0.15 mg or 0.3 mg, designed for emergency intramuscular injection into the thigh during acute anaphylaxis. These devices incorporate needle-safety mechanisms and pressure-activated triggers to ensure rapid drug release without visualization of the injection site. Single-dose disposable units dominate volume shipments due to regulatory mandates for patient-specific emergency kits, while multi-dose reusable platforms capture margin pools in institutional settings where waste reduction drives procurement. Intramuscular delivery leads across all patient demographics because of faster systemic absorption rates compared with subcutaneous routes, though nasal delivery modes are gaining traction in pediatric applications where needle anxiety limits compliance.
The FDA enforces strict stability-labeling requirements under its combination-product regulations, while the EMA's Medical Device Regulation imposes enhanced clinical-evidence standards for reusable injector platforms. These frameworks elevate barriers for new entrants and compel incumbents to maintain validated cold-chain documentation across distribution networks. Stakeholders must monitor evolving pharmacovigilance reporting obligations and reimbursement coding changes that could reshape commercial access dynamics.
Market Dynamics
Needle-free delivery platforms are compressing traditional spring-loaded device margins as pediatric allergy clinics and school health offices prioritize anxiety-reducing administration methods for children.
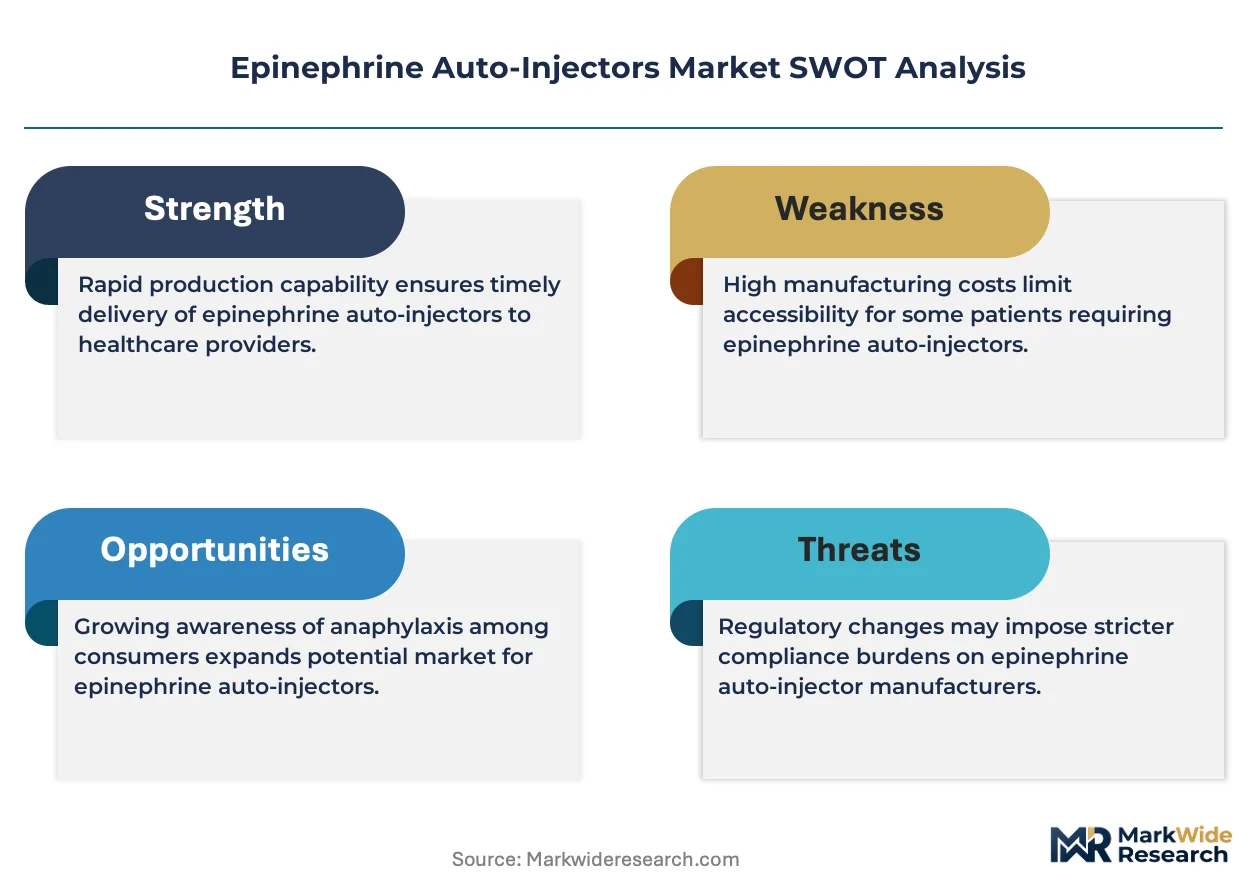
Growth Catalysts
- US school-based preparedness mandates:State-level anaphylaxis emergency kit requirements in educational institutions are institutionalizing replacement cycles for legacy auto-injectors.
- EMA Medical Device Regulation:Enhanced clinical-evidence standards for reusable platforms are accelerating incumbents' investments in validated cold-chain documentation capabilities.
- Self-administration training expansion:Homecare settings are overtaking hospital-centric distribution as pharmacy-led patient education programs broaden the addressable patient base.
Market Restraints
- Temperature-sensitive biologics stability costs:Epinephrine's narrow thermal stability window elevates distribution infrastructure costs and limits generic substitution flexibility.
- FDA combination-product regulatory friction:Strict stability-labeling requirements under device-drug combination rules extend approval timelines for platform modifications.
- Needle-free nasal delivery substitution threat:Alternative intranasal epinephrine formulations are capturing pediatric market share where needle anxiety drives non-compliance.
Strategic Opportunities
- Voice-instruction embedded platforms:Caregiver-assisted administration technology converges with connected health monitoring to reduce emergency response errors.
- Commercial payer coverage expansion:United States insurance formulary broadening creates white space for premium-tier devices with enhanced safety features.
- Institutional waste reduction procurement:Multi-dose reusable platforms address margin pools in hospital and clinic settings seeking to reduce single-use device expenditure.
Industry Challenges
- Pharmacovigilance reporting skill gaps:Post-market surveillance obligations for combination products require specialized adverse-event documentation expertise that manufacturers struggle to staff.
- Cold-chain reconfiguration capex intensity:Validated distribution network upgrades demand substantial capital investment to meet tightening EMA and FDA documentation standards.
Report Scope
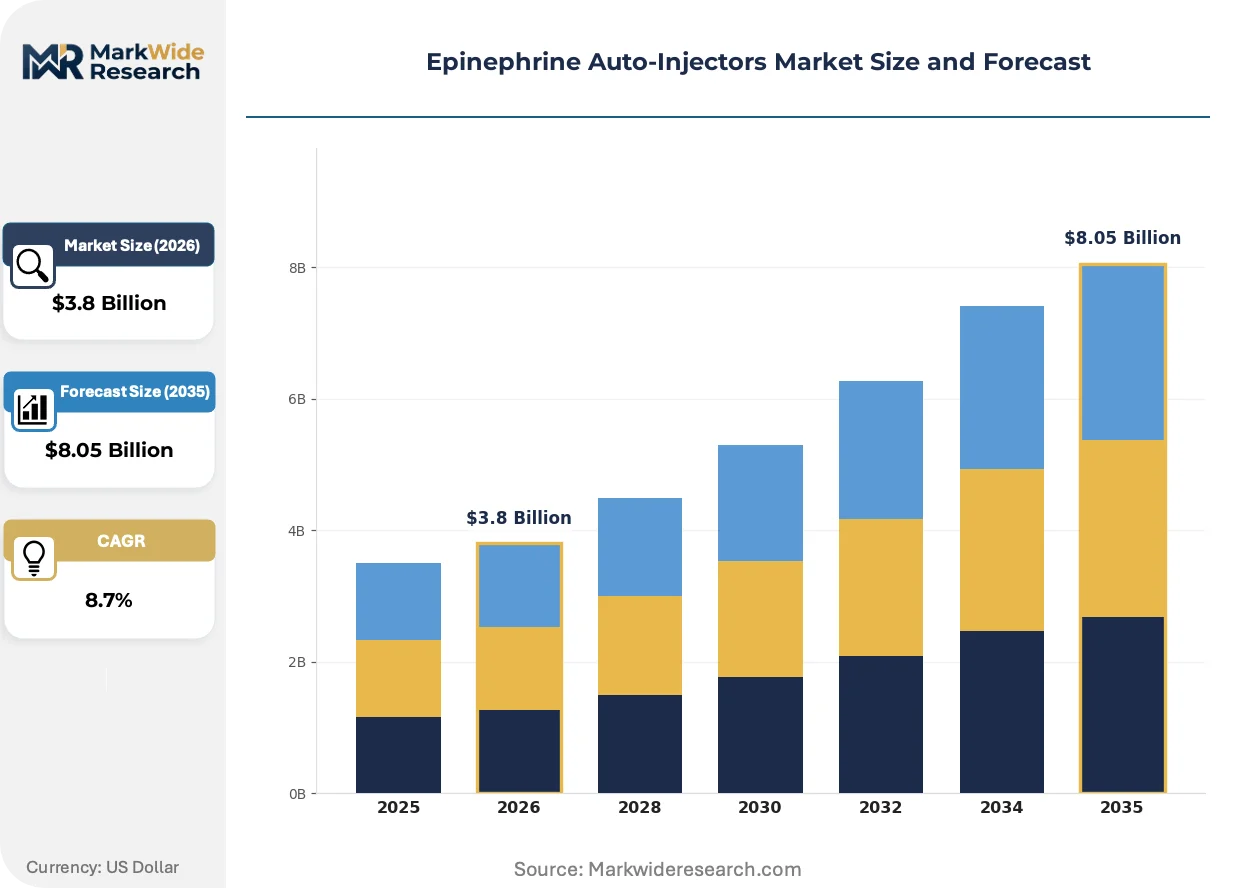
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epinephrine Auto-Injectors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Dose, Multi-Dose, Disposable, Reusable End User: Hospitals, Clinics, Homecare, Emergency Services Delivery Mode: Intramuscular, Subcutaneous, Intravenous, Nasal Application: Anaphylaxis, Allergic Reactions, Asthma Attacks, Others |
| Companies Covered | Viatris, Teva Pharmaceutical Industries, Amneal Pharmaceuticals, Bausch Health Companies, ALK-Abello, Kaléo, Sandoz Group, BIOPROJET, Crossject, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epinephrine Auto-Injectors Market Emerging Trajectories
Connected delivery platforms and alternative administration routes are fragmenting the historically standardized auto-injector category, creating tiered performance expectations across patient demographics.
Electronic auto-injector platforms with integrated dose confirmation sensors are automating the injection verification process that previously required manual technique validation. Pediatric allergy clinics in the United States are adopting these devices at accelerated rates to reduce caregiver error during school-based emergencies. This automation is compressing liability exposure for institutional purchasers while elevating the technical barrier for new market entrants lacking electromechanical integration capabilities.
EMA's Medical Device Regulation imposes enhanced clinical-evidence requirements for reusable injector platforms that exceed prior CE-marking thresholds. Manufacturers must now submit extended usability studies and biocompatibility data for devices intended for multiple patient administrations. Reusable platform developers in Germany and France are responding by consolidating regulatory affairs functions and extending development timelines to accommodate notified body review periods.
School district procurement offices are consolidating purchasing authority away from individual nurse practitioners toward centralized health services administrators. This buyer concentration is displacing the fragmented retail pharmacy channel that historically dominated emergency kit fulfillment. The shift is most visible in United States public school systems where state mandate compliance deadlines are compressing vendor selection cycles and favoring established suppliers with proven distribution scale.
Epinephrine Auto-Injectors Market Segmentation
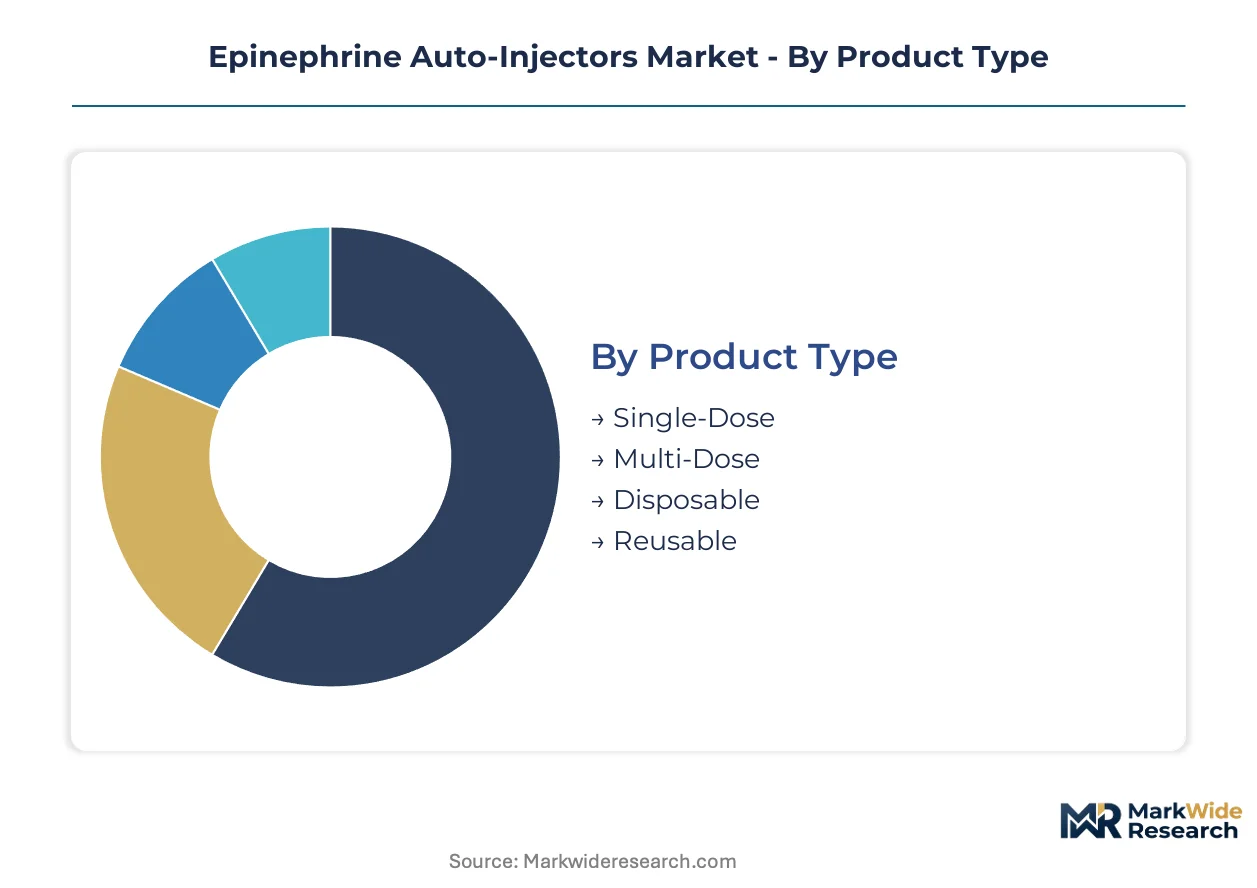
Epinephrine auto-injector segmentation reflects divergent procurement priorities across emergency medicine, chronic allergy management, and institutional preparedness. Device selection varies sharply between patient-controlled homecare scenarios and clinician-administered acute settings.
Product Type:
Standardization dominates high-volume channels while customization concentrates in institutional contracts seeking waste reduction.
- Single-Dose:Pre-filled disposable units with fixed 0.15 mg or 0.3 mg epinephrine loads and integrated needle-safety shields. School district bulk purchasing in the United States favors these devices for individual student emergency kits under state mandate compliance programs.
- Multi-Dose:Reusable platforms with cartridge-based drug reservoirs enabling 50-100 administrations before decommissioning. Hospital pharmacy directors in Germany specify these systems for emergency department crash carts to reduce per-dose procurement expenditure.
- Disposable:Fully sealed units with tamper-evident packaging designed for single-patient assignment and post-use sharps disposal. Retail pharmacy chains stock these exclusively for prescription fulfillment due to liability simplicity.
- Reusable:Electromechanical housings with sterilizable contact surfaces and validated cleaning protocols for multi-patient deployment. French allergy clinics pilot these under EMA Medical Device Regulation usability study requirements.
Leading the category by volume: Single-Dose. Growing fastest: Reusable.
End User:
Channel concentration shifts from acute care facilities toward distributed self-administration points.
- Hospitals:Emergency departments and intensive care units stock multi-dose platforms for rapid sequential dosing during refractory anaphylaxis. These sites prioritize device reliability over unit cost given liability exposure.
- Clinics:Pediatric allergy practices in the United States deploy electronic auto-injectors with dose confirmation sensors to reduce caregiver technique errors during supervised challenge testing.
- Homecare:Self-administration training programs through community pharmacies now distribute more auto-injectors annually than hospital discharge protocols.
- Emergency Services:Paramedic units carry both intramuscular and intranasal alternatives to address needle anxiety in pediatric field emergencies.
Homecare claims the steepest expansion trajectory. Hospitals retain the highest per-unit procurement value.
Delivery Mode:
Absorption kinetics and patient anxiety tolerance drive route selection across demographic segments.
- Intramuscular:Thigh-delivered injection via 25mm needle achieving peak plasma epinephrine within 5-15 minutes. FDA combination-product regulations mandate specific bioequivalence documentation for generic alternatives seeking this route.
- Subcutaneous:Shorter needle penetration with slower systemic absorption rates. This route persists only in legacy device inventories being phased from institutional formularies.
- Intravenous:Reserved for hospital settings with continuous cardiac monitoring capability during refractory anaphylaxis requiring titrated dosing.
- Nasal:Atomized mucosal delivery eliminating needle visualization. Pediatric emergency departments in France evaluate these devices under ANSM post-market surveillance protocols for anxiety-reduced compliance.
Intramuscular administration dominates prescription volumes. Nasal delivery is gaining share fastest among pediatric specialists.
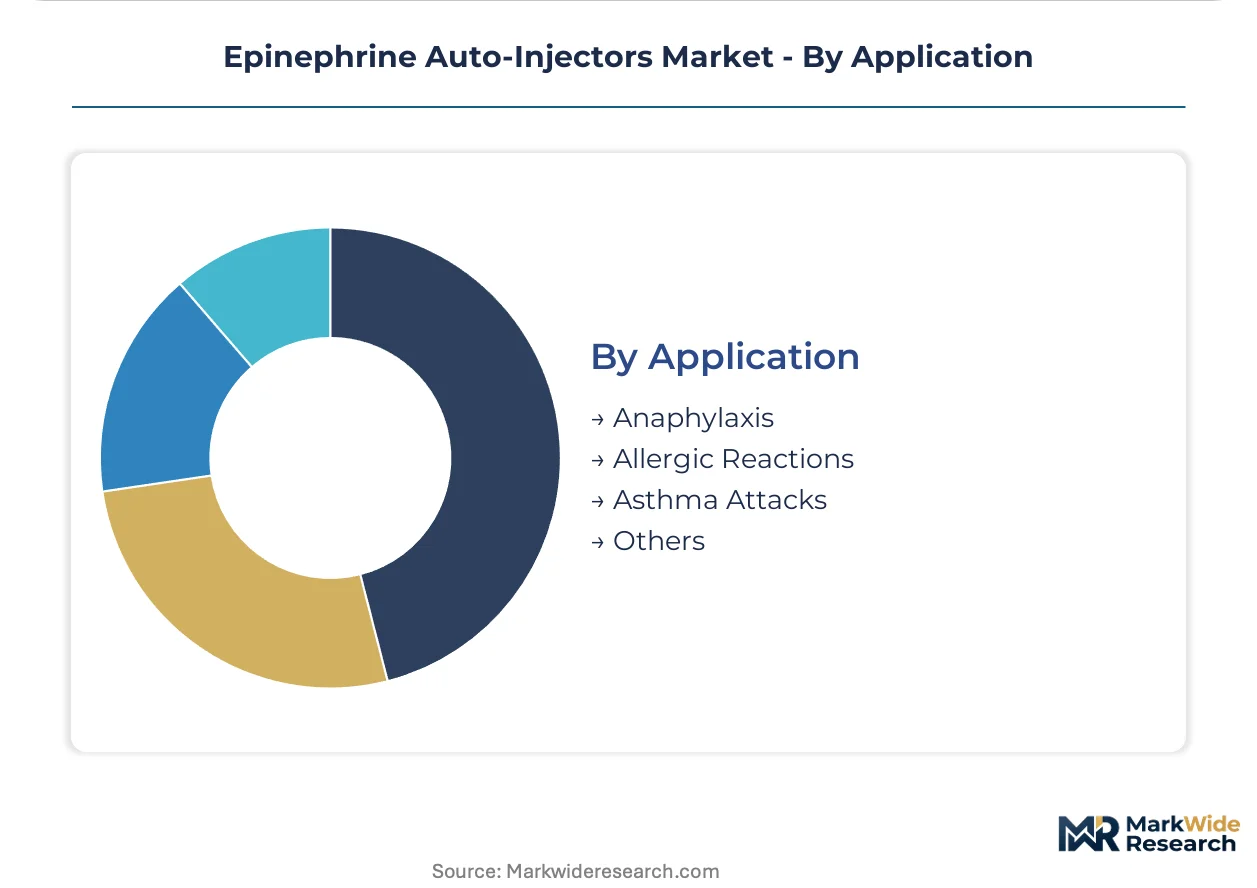
Application:
Indication severity determines device specification, training intensity, and replacement cycle frequency.
- Anaphylaxis:Life-threatening systemic hypersensitivity requiring immediate epinephrine as first-line intervention. School nurses in the United States replace these devices every 12-18 months per manufacturer stability labeling regardless of use.
- Allergic Reactions:Moderate presentations where epinephrine serves as rescue therapy pending definitive care. Urgent care clinics stock lower-dose alternatives for this risk stratum.
- Asthma Attacks:Adjunctive use during acute bronchospasm with allergic trigger component. Pulmonology practices specify dual-indication labeling to reduce patient device burden.
- Others:Off-protocol applications including exercise-induced anaphylaxis and idiopathic urticaria emergencies. These prescriptions concentrate in academic medical center allergy divisions.
Anaphylaxis anchors category volume. Allergic Reactions applications are expanding most quickly as diagnostic thresholds broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates and Singapore concentrate distribution infrastructure for temperature-sensitive biologics, creating tax-advantaged staging points for regional supply networks. These zones attract cold-chain logistics investment from manufacturers seeking to minimize stability-risk exposure during transshipment.
United States
School district procurement consolidation drives bulk purchasing of single-dose devices for student emergency kits under state mandate programs. FDA combination-product regulations enforce strict stability-labeling requirements that extend approval timelines for platform modifications. The Dallas-Fort Worth metroplex anchors distribution networks serving the Southwest region's allergy clinic chains.
Germany
Hospital pharmacy directors specify multi-dose reusable platforms for emergency department crash carts to reduce per-dose procurement expenditure. EMA Medical Device Regulation imposes enhanced clinical-evidence standards for reusable injector platforms that exceed prior CE-marking thresholds. The Rhine-Ruhr industrial corridor hosts notified bodies conducting extended usability studies for device manufacturers.
France
Pediatric emergency departments evaluate intranasal delivery devices under ANSM post-market surveillance protocols for anxiety-reduced compliance. The country's national pharmaceutical regulator maintains pharmacovigilance reporting obligations that manufacturers must navigate for combination products. The Lyon-Grenoble cluster concentrates medical device engineering talent developing electromechanical integration capabilities.
United Kingdom
NHS procurement frameworks prioritize device reliability over unit cost for emergency department stocking, sustaining premium-tier device penetration. MHRA alignment with EMA standards post-Brexit maintains equivalent clinical-evidence requirements for reusable platforms. The Cambridge-Oxford-London triangle concentrates allergy research institutions driving diagnostic threshold expansion.
Japan
PMDA oversight of combination products ensures bioequivalence documentation requirements for generic alternatives seeking intramuscular route approval. Community pharmacy-led patient education programs expand self-administration training beyond hospital discharge protocols. The Osaka-Kobe industrial zone hosts precision manufacturing facilities producing needle-safety mechanisms.
Epinephrine Auto-Injectors Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator firms defending premium positioning through embedded technology while generic entrants compress pricing in high-volume channels. The market structure concentrates around three to five incumbents with validated cold-chain documentation capabilities, creating elevation barriers for new entrants. Two strategic archetypes dominate: vertically integrated pharmaceutical-device combinations and standalone device specialists licensing drug formulations. Competitive moves center on M&A to secure combination-product expertise and capacity expansion to meet school district bulk procurement deadlines.
Among originator-tier anchors, Kaléo occupies a position exemplifying voice-instruction embedded platforms for caregiver-assisted administration, while Viatris represents the pharmaceutical-device integration archetype leveraging established retail pharmacy channel networks. Teva Pharmaceutical Industries sits within the generic substitution tier, anchoring price-competitive alternatives against originator products. These three firms collectively illustrate the competitive tension between premium feature differentiation and formulary-driven cost containment.
| Leading Market Players |
|---|
| Viatris |
| Teva Pharmaceutical Industries |
| Amneal Pharmaceuticals |
| Bausch Health Companies |
| ALK-Abello |
| Kaléo |
| Sandoz Group |
| BIOPROJET |
| Crossject |
| Others |
Supply Flow & Price Mechanics
Epinephrine API sourcing costs cascade through three pricing tiers, with United States-sourced active pharmaceutical ingredient commanding premium placement in FDA-validated cold-chain documentation tiers while Indian and Chinese API feeds standard-economy positioning in price-sensitive institutional procurement.
Pricing Analysis
Short lead-time premiums concentrate in school district emergency kit fulfillment, where state mandate compliance deadlines compress vendor selection cycles and elevate spot pricing for validated cold-chain stock. Pricing stratifies across premium, standard, and economy tiers based on FDA combination-product certification status and embedded technology features like voice-instruction platforms. Cost compression in the generic substitution tier intensifies as Teva Pharmaceutical Industries and Sandoz Group expand formulary access, while premium devices with dose-confirmation sensors retain pricing power in pediatric allergy clinic procurement. Hospital pharmacy directors exhibit lowest price sensitivity, prioritizing liability reduction over per-unit expenditure.
Supply Chain Analysis
Precision manufacturing workforce availability in the Osaka-Kobe industrial zone and Lyon-Grenoble cluster anchors needle-safety mechanism and electromechanical housing production for tier-one device suppliers. The supply chain draws from United States and European Union API manufacturers for originator-grade epinephrine, while Indian and Chinese chemical synthesis feeds generic cartridge production. Single-source vulnerability concentrates in sterilizable contact surface materials for reusable platforms under EMA Medical Device Regulation biocompatibility requirements. Distribution runs through tax-advantaged free trade zones in the United Arab Emirates and Singapore for temperature-sensitive transshipment to Asia-Pacific and Middle Eastern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capacity for validated cold-chain documentation capabilities remains constrained relative to school district bulk procurement demand, propping pricing power for incumbents with established FDA and EMA compliance infrastructure.
For Market Incumbents: Lock in multi-year school district contracts ahead of state mandate compliance deadlines to preempt generic substitution in the institutional channel. Prioritize backward integration into epinephrine API production to reduce exposure to Indian and Chinese chemical synthesis price volatility. Expand electromechanical integration capabilities to defend premium positioning against intranasal delivery substitution threats in pediatric applications.
For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models targeting French and German pediatric allergy practices evaluating reusable platforms under EMA usability study requirements. Concentrate initial penetration on the homecare segment, where pharmacy-led patient education programs create lower barriers than hospital formulary access. Differentiate through needle-free delivery technology to capture anxiety-driven compliance demand in school health offices.
For Investors and Strategic Acquirers: Distressed-cycle entries favor combination-product specialists with validated FDA 510(k) pathways and established cold-chain documentation capabilities in United States distribution networks. Long-term viability over the projection horizon hinges on regulatory moat sustainability rather than manufacturing scale alone. Watch FDA stability-labeling requirement amendments as the critical inflection signal for generic substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA Medical Device Regulation compliance unlocks reusable platform access across German and French hospital systems. |
| Hospital System Partnership | Pediatric allergy clinic adoption of electronic auto-injectors with dose-confirmation sensors reduces institutional liability exposure. |
| Reimbursement Strategy | Commercial payer coverage expansion in United States insurance formularies creates white space for premium-tier device placement. |
| Software Companion Development | Voice-instruction embedded platforms converge with connected health monitoring to reduce emergency response errors in caregiver-assisted administration. |
| FDA Submission | Combination-product regulatory approval for needle-free nasal delivery alternatives captures pediatric market share from spring-loaded devices. |
Methodological Framework
Multi-period observation of school district procurement volumes, FDA 510(k) submission timelines, and EMA notified body review queues anchored the trend analysis, supplemented by interviews with regulatory affairs leads at combination-product manufacturers, hospital pharmacy directors, pediatric allergy clinicians, GPO contracts managers, and cold-chain logistics specialists. Secondary validation drew from FDA combination-product filings, EMA Medical Device Regulation guidance documents, hospital procurement databases, and CMS Medicare reimbursement coding updates. Bottom-up device shipment estimates triangulated against top-down epinephrine API consumption data.
Segment-weighting across the projection horizon applied product type, end user, delivery mode, and application dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to validated baseline shipment data, incorporating EMA Medical Device Regulation implementation pace and United States state mandate adoption timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path for electronic auto-injector platforms; alternative pathways for intranasal delivery gaining faster pediatric specialist acceptance would alter the outlook. Forecasts reflect assumptions regarding FDA stability-labeling enforcement consistency and EMA notified body capacity expansion. Material deviation in school district procurement centralization pace or needle-free delivery bioequivalence confirmation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Hemodynamic Monitoring Devices Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market