
 Solid Tumor Testing Market | 2026-2036
Solid Tumor Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Tumor Testing Market Outlook
Subscription-based bioinformatics analysis is repositioning how sequencing data gets monetized in oncology workflows. Illumina leverages its cloud-based analytics platform to deepen customer retention across clinical and research accounts. Thermo Fisher Scientific anchors its position through integrated instrument-reagent-software bundles that lock in laboratory workflows. F. Hoffmann-La Roche differentiates via end-to-end tissue-to-data pipelines spanning companion diagnostics and centralized pathology services.
Solid tumor testing encompasses laboratory and imaging methods that detect, characterize, and monitor malignant neoplasms in non-hematological cancers, employing techniques ranging from immunohistochemical staining with antibody panels to next-generation sequencing panels detecting single nucleotide variants, insertions, deletions, and copy number alterations at allele frequencies down to one percent. Its primary purpose is to guide therapeutic selection, predict treatment response, and enable longitudinal disease surveillance across lung, breast, colorectal, prostate, and other carcinomas. Molecular testing commands the deepest clinical integration as oncologists depend on genomic profiling to match patients to targeted therapies and immunotherapy regimens. Liquid biopsy represents the fastest-expanding segment because blood-based circulating tumor DNA analysis enables serial monitoring without repeated invasive tissue sampling. Next-generation sequencing platforms concentrate the largest capital investment and margin pool, though PCR maintains dominance in single-gene companion diagnostic applications where turnaround time and reimbursement clarity favor simpler workflows.
The FDA's in vitro diagnostic and companion diagnostic frameworks govern premarket approval pathways and label claims that directly determine commercial viability of tumor profiling assays in the United States. EMA's IVDR transition in Europe is elevating clinical evidence requirements and constraining smaller manufacturers unable to finance expanded performance studies. China's NMPA streamlined innovation channels are accelerating domestic assay approvals while tightening post-market surveillance. Stakeholders must monitor how divergent evidentiary standards across these regulators reshape competitive access and portfolio prioritization decisions.
Market Dynamics
Liquid biopsy platforms are compressing tissue-based testing volumes as oncology clinics prioritize serial monitoring capabilities over single-point genomic snapshots.
Growth Catalysts
- FDA Tumor Profiling Guidance:The framework clarifies companion diagnostic approval pathways, accelerating assay commercialization timelines for developers targeting lung and colorectal cancer indications.
- China's Tier-One Hospital Networks:Concentrated demand for NGS panels within Beijing and Shanghai's flagship oncology centers creates scalable deployment templates for domestic assay manufacturers.
- Medicare Coverage Determinations:National reimbursement clarity for circulating tumor DNA testing removes payment uncertainty that previously constrained community oncology adoption.
Market Restraints
- Reagent Supply Concentration:Three manufacturers control over eighty percent of high-fidelity polymerase supply, exposing laboratories to price volatility and allocation constraints during demand surges.
- EMA IVDR Clinical Evidence Requirements:Expanded performance study mandates disproportionately burden mid-sized European developers, forcing portfolio rationalization or partnership dependence.
- Single-Gene PCR Substitution:Rapid turnaround and established reimbursement codes for EGFR and ALK companion diagnostics limit NGS panel penetration in urgent treatment initiation scenarios.
Strategic Opportunities
- India's Underserved Oncology Infrastructure:Tier-two and tier-three cities lack molecular pathology capacity, creating first-mover advantage for decentralized testing platforms with simplified workflows.
- Minimal Residual Disease Surveillance:Post-surgical monitoring applications expand addressable testing occasions beyond initial diagnosis into longitudinal revenue streams.
- Cloud-Based Bioinformatics Subscriptions:Recurring analytics revenue models reposition instrument vendors as ongoing service partners rather than one-time capital equipment suppliers.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories struggle to recruit variant interpretation specialists capable of translating complex genomic data into actionable therapy recommendations.
- LIMS Integration Complexity:Legacy laboratory information management systems require costly middleware development to accommodate NGS data volumes and regulatory audit trails.
- Sample Pre-Analytics Standardization:Pre-analytical variables in circulating tumor DNA collection tubes create inter-laboratory discordance that undermines clinical confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Tumor Testing Market |
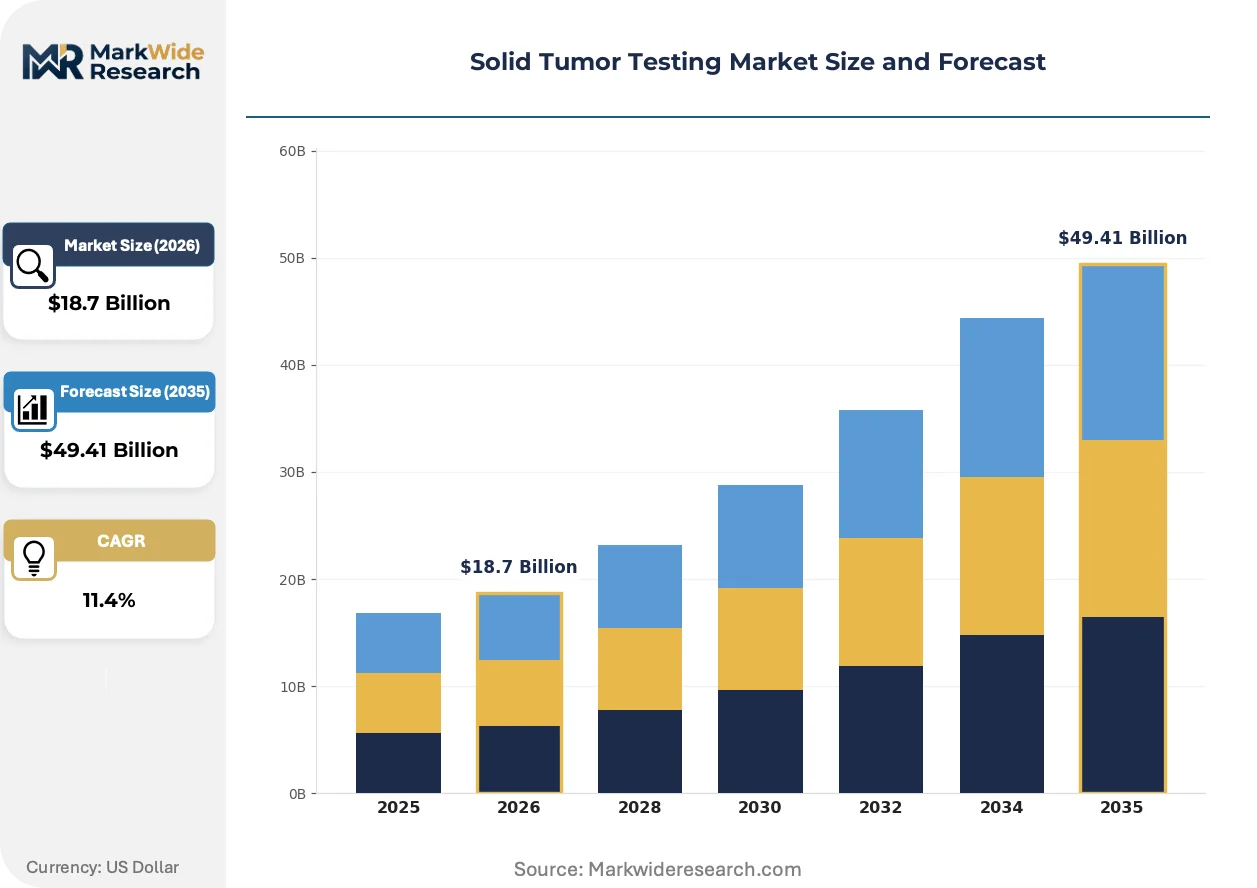
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Biopsy, Liquid Biopsy, Imaging, Molecular Testing Sample Type: Tissue, Blood, Urine, Saliva End User: Hospitals, Diagnostic Labs, Research Centers, Oncology Clinics Technology: Next-Generation Sequencing, PCR, Immunohistochemistry, Fluorescence In Situ Hybridization |
| Companies Covered | F. Hoffmann-La Roche, Illumina, Thermo Fisher Scientific, QIAGEN, Abbott Laboratories, Agilent Technologies, Quest Diagnostics, Myriad Genetics, Biocare Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Tumor Testing Market Strategic Shifts
Multi-omics integration and artificial intelligence-assisted variant classification are redefining competitive differentiation beyond raw sequencing throughput metrics.
Artificial intelligence variant interpretation tools are converging with cloud-based analytics platforms to reduce manual curation burden in high-volume molecular pathology laboratories. Community oncology networks and regional reference laboratories are deploying these systems to expand testing menus without proportional staffing increases. This convergence is compressing the economic advantage previously held by centralized academic medical center laboratories.
China's NMPA accelerated review channels for innovative oncology assays are shortening domestic approval timelines while tightening post-market surveillance requirements. Domestic test developers gain competitive access to tier-one hospital procurement channels, forcing multinational manufacturers to localize manufacturing and clinical trial infrastructure. Multinational firms are responding through joint ventures with domestic partners to satisfy local content preferences.
Subscription-based service contracts are displacing per-test reimbursement models in large integrated delivery networks. Health systems in the United States are consolidating vendor relationships around multi-year agreements that bundle instruments, reagents, and bioinformatics into predictable operational expenditures. This shift is most visible within multi-hospital systems seeking to standardize molecular pathology capabilities across geographically dispersed sites.
Solid Tumor Testing Market Segmentation
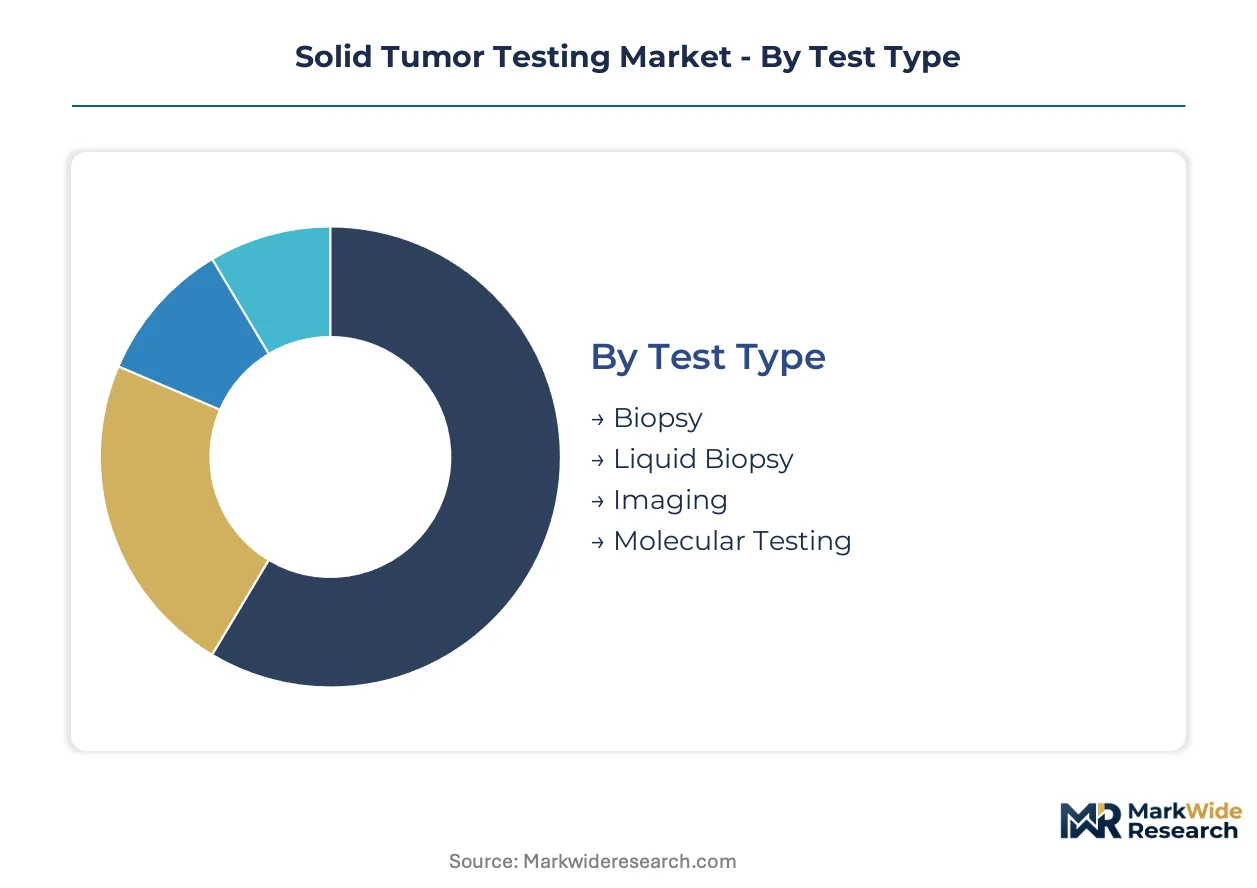
Solid tumor testing segments reflect divergent clinical workflows and capital intensity. Biopsy methods compete on invasiveness versus diagnostic yield. Technology platforms differentiate on throughput, turnaround time, and reimbursement clarity.
Test Type:
Oncologists select methods based on disease stage and monitoring frequency.
- Liquid Biopsy:Circulating tumor DNA analysis from blood samples enables serial monitoring without tissue acquisition. Oncology clinics in the United States prioritize this for treatment response tracking and recurrence surveillance.
- Molecular Testing:Genomic profiling identifies actionable mutations for targeted therapy selection. China's tier-one hospital networks concentrate demand for comprehensive NGS panels in lung and colorectal cancer protocols.
- Biopsy:Tissue acquisition remains essential for initial diagnosis and histological classification.
- Imaging:Radiological assessment provides anatomical staging and treatment response evaluation.
Volume sits with molecular testing; growth tilts toward liquid biopsy.
Sample Type:
Collection logistics and analyte stability shape laboratory preferences.
- Blood:Standard venipuncture enables widespread access and standardized pre-analytical handling. Liquid biopsy workflows in community oncology settings depend on blood-based circulating tumor DNA.
- Tissue:Formalin-fixed paraffin-embedded specimens provide DNA, RNA, and protein for multi-modal analysis. Academic medical centers maintain tissue-based testing for complex variant interpretation.
- Urine:Non-invasive collection suits longitudinal monitoring applications.
- Saliva:Germline mutation screening leverages buccal cell collection for hereditary cancer risk assessment.
Clinical utility concentrates in blood and tissue; emerging applications expand urine collection.
End User:
Site-of-care economics and test complexity determine vendor targeting.
- Hospitals:Integrated health systems consolidate molecular pathology within centralized laboratories. Multi-hospital networks in the United States negotiate multi-year bundled contracts spanning instruments and bioinformatics.
- Diagnostic Labs:Independent reference laboratories compete on turnaround time and specialized assay menus. Regional players in India target tier-two cities lacking in-hospital molecular capacity.
- Oncology Clinics:Community-based practices prioritize rapid single-gene testing for urgent treatment decisions.
- Research Centers:Academic institutions drive assay development and biomarker discovery.
Procurement authority rests with hospitals; point-of-care expansion targets oncology clinics.
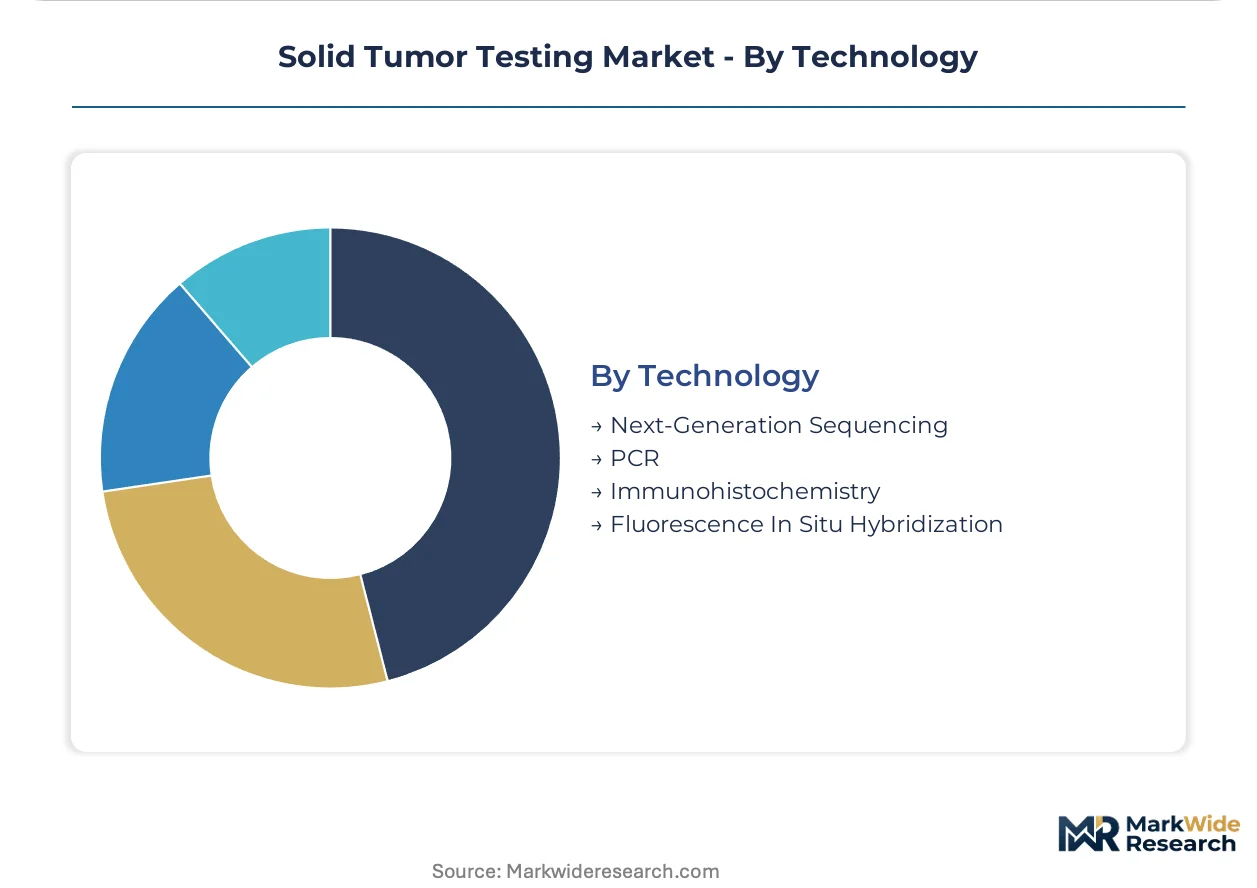
Technology:
Capital requirements and regulatory pathways segment competitive positioning.
- Next-Generation Sequencing:Massively parallel sequencing detects variants across hundreds of genes simultaneously. NMPA accelerated review channels in China compress approval timelines for domestic NGS panel developers.
- PCR:Polymerase chain reaction delivers rapid, cost-effective single-gene analysis. Established reimbursement codes for EGFR and ALK companion diagnostics sustain PCR dominance in urgent clinical scenarios.
- Immunohistochemistry:Protein expression profiling guides immunotherapy patient selection.
- Fluorescence In Situ Hybridization:Chromosomal rearrangement detection supports hematologic and solid tumor classification.
Revenue pools concentrate in NGS; PCR retains volume in companion diagnostic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the United States, Germany, and China while clinical consumption clusters in tier-one hospital networks across Beijing, Shanghai, and Boston. Regional regulatory divergence reshapes competitive access as developers navigate FDA, EMA, and NMPA pathways simultaneously.
United States
Oncology clinics expand liquid biopsy adoption for serial monitoring while academic medical centers drive complex variant interpretation demand. FDA tumor profiling guidance clarifies companion diagnostic approval pathways for lung and colorectal cancer indications. The Greater Boston corridor anchors NGS platform development and biomarker discovery pipelines.
China
Tier-one hospital networks in Beijing and Shanghai concentrate demand for comprehensive NGS panels in lung cancer protocols. NMPA accelerated review channels compress approval timelines for domestic assay developers while tightening post-market surveillance. The Yangtze River Delta hosts manufacturing clusters serving both clinical and research end users.
Germany
University hospitals in Munich and Heidelberg maintain tissue-based testing workflows for complex histological classification. EMA IVDR transition elevates clinical evidence requirements and constrains smaller manufacturers unable to finance expanded performance studies. The Rhine-Main region centralizes pathology reference laboratory networks.
Japan
PMDA regulatory frameworks govern premarket approval for tumor profiling assays targeting gastric and lung cancer indications. METI industrial policy supports domestic reagent manufacturing capacity to reduce import dependence. The Kanto region concentrates hospital procurement authority within Tokyo's flagship oncology centers.
India
Tier-two and tier-three cities lack molecular pathology capacity, creating first-mover opportunity for decentralized testing platforms. CDSCO regulatory pathways for in vitro diagnostics remain under development, creating uncertainty for multinational assay developers. Maharashtra and Karnataka host emerging diagnostic laboratory networks targeting underserved oncology infrastructure.
Solid Tumor Testing Market Competitive Environment
Capital-heavy instrument manufacturers compete with asset-light assay developers for laboratory workflow integration. The market structure consolidates around three dominant platform providers while fragmenting across hundreds of specialized test developers. Strategic archetypes span integrated instrument-reagent-software bundlers, end-to-end tissue-to-data pipeline operators, and cloud-based analytics subscription providers. Competitive moves concentrate on multi-year service contracts and geographic localization partnerships.
Among Swiss and American platform operators, F. Hoffmann-La Roche and Illumina occupy positions spanning companion diagnostics and sequencing infrastructure. Thermo Fisher Scientific exemplifies the integrated bundling archetype through captive control over reagent supply chains. These three anchors represent divergent bets on how oncology workflows monetize—recurring consumables versus capital equipment versus subscription analytics.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Illumina |
| Thermo Fisher Scientific |
| QIAGEN |
| Abbott Laboratories |
| Agilent Technologies |
| Quest Diagnostics |
| Myriad Genetics |
| Biocare Medical |
| Others |
Value Chain & Pricing Dynamics
Multi-year bundled service contracts from United States hospital systems are forcing instrument manufacturers to absorb upfront capital costs into recurring subscription models, compressing immediate margin realization while locking in long-term consumable revenue streams.
Pricing Analysis
Margin tightening in NGS panel testing reflects Medicare reimbursement compression and single-gene PCR substitution in urgent clinical scenarios. Three-tier pricing structure across premium comprehensive panels, standard targeted assays, and economy single-gene tests separates academic medical centers from community oncology clinics from reference laboratories. Cost-down pressure on liquid biopsy workflows accelerates because CMS coverage determinations demand demonstrated clinical utility before national payment establishment. Community oncology clinics exhibit highest price sensitivity; integrated health systems leverage volume consolidation for preferential contracting.
Supply Chain Analysis
High-fidelity polymerase supply rests on manufacturing concentration across the United States, Germany, and China, with three producers controlling over eighty percent of global capacity. Sequencing reagents, flow cells, and specialized collection tubes draw from captive production networks and third-party chemical synthesis. Single-source vulnerability in thermostable enzyme supply exposes laboratories to allocation constraints during demand surges. Distribution runs through direct sales forces for capital equipment and specialized distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent supply concentration creates a structural capacity bottleneck that props pricing power for polymerase and sequencing chemistry producers despite downstream reimbursement pressure.
For Market Incumbents: Anchor workflow lock-in through expanded bioinformatics subscription bundles that deepen switching costs for hospital laboratory customers. Defend against liquid biopsy platform substitution by integrating tissue-to-data pipelines with companion diagnostic regulatory exclusivity. Prioritize backward integration into high-fidelity polymerase production to secure supply continuity and margin control. For New Entrants and Emerging Players: The price-point gap between premium NGS comprehensive panels and economy single-gene PCR tests opens white-space opportunity for mid-plex targeted assays. India's tier-two cities lacking molecular pathology infrastructure offer the most penetrable geography for decentralized platform deployment. Pursue cloud-native analytics partnerships to bypass capital-intensive instrument manufacturing barriers. For Investors and Strategic Acquirers: The window for entry favors assay developers with NMPA-approved oncology panels and established tier-one hospital procurement relationships in China. Long-term viability hinges on regulatory exclusivity duration and reimbursement code expansion. Watch FDA tumor profiling guidance evolution as the primary inflection signal for companion diagnostic commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Bioinformatics Subscription | Illumina's analytics platform deepens customer retention across clinical and research accounts. |
| NMPA Accelerated Review Channel Entry | Domestic Chinese developers gain competitive access to Beijing and Shanghai hospital procurement. |
| Integrated Instrument-Reagent-Software Bundle | Thermo Fisher Scientific locks laboratory workflows through captive consumable supply. |
| End-to-End Tissue-to-Data Pipeline | F. Hoffmann-La Roche spans companion diagnostics and centralized pathology services. |
| Minimal Residual Disease Surveillance Expansion | Post-surgical monitoring applications extend addressable testing occasions beyond initial diagnosis. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this solid tumor testing market analysis. Primary interviews with molecular pathology laboratory directors, oncology clinic administrators, hospital procurement managers, and regulatory affairs specialists at assay developers informed demand-side validation. FDA 510(k) and PMA filings, NMPA approval databases, EMA IVDR transition guidance, Medicare coverage determinations, and hospital GPO contract disclosures supplied secondary triangulation. Bottom-up instrument placement and consumable consumption estimates reconciled against top-down healthcare expenditure flows.
Segment-level modeling addressed test type, technology platform, sample source, and end-user site-of-care across the analysis window. Next-generation sequencing panel penetration, liquid biopsy adoption curves, and PCR companion diagnostic volumes were projected with procedure-based build-ups. CAGRs derived from logistic diffusion curves applied to biomarker-addressable patient populations, adjusted for regulatory approval timelines and reimbursement pathway clarity. Pricing trajectories incorporated Medicare fee schedule evolution and private payer contracting dynamics.
Underlying measurement precision varies by segment; United States liquid biopsy adoption and China NGS panel deployment carry tighter precision than emerging market decentralization forecasts. Projections reflect assumptions regarding regulatory approval continuity and reimbursement expansion that regulatory pathway delays or coverage determinations could revise. A small set of triggers—FDA tumor profiling guidance updates, NMPA innovation channel policy shifts, and Medicare national coverage determinations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Europe Medical Device Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Outsourced Testing Services Market
Testing Services
Global Efficacy Testing Market
Testing Services
Biomarker Testing Services Market
Testing Services
Apoptosis Testing Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Active B12 Test Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Blood Pressure Test Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Global Multiplex Assays Market