
 Fiber Reinforced Plastic (FRP) Panels and Sheets Market | 2026-2036
Fiber Reinforced Plastic (FRP) Panels and Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Reinforced Plastic (FRP) Panels and Sheets Market Analysis
REACH compliance is hardening the cost-of-entry calculus for European FRP manufacturers, particularly for vinyl ester formulations containing styrene. Saint-Gobain leverages its integrated glass fiber supply chain to sustain margin stability amid raw material volatility. Owens Corning Corporation anchors its position through deep R&D investment in thermoplastic composites for automotive lightweighting. Crane Composites Inc. specializes in antimicrobial gel-coated panels for healthcare and food processing environments, differentiating on certified hygiene performance rather than commodity pricing.
Fiber reinforced plastic panels and sheets are composite laminates comprising polymer matrices reinforced with glass, carbon, or aramid fibers, typically manufactured through pultrusion, compression molding, or hand lay-up processes to achieve specific strength-to-weight ratios and corrosion resistance. These materials serve primarily as structural and cladding alternatives to metals and wood in environments demanding chemical resistance, thermal insulation, or reduced maintenance cycles. Polyester resin formulations dominate volume production for construction and marine applications due to cost efficiency and established supply chains, while epoxy-based systems command premium positioning in aerospace and high-performance automotive segments where fatigue resistance and dimensional stability justify higher material costs. Panel configurations capture the majority of construction sector demand, whereas sheet formats lead in transportation OEM supply programs requiring flat-stock processing compatibility.
The EPA oversees volatile organic compound emissions from FRP manufacturing facilities under Clean Air Act provisions, while OSHA enforces permissible exposure limits for styrene and respirable fibers in fabrication shops. ECHA's REACH restrictions on dibutyl phthalate plasticizers and cobalt carboxylate accelerators are forcing reformulation investments across European supply chains. China's MEE has tightened phenolic resin emission standards for composite producers in Jiangsu and Zhejiang provinces. Stakeholders must monitor evolving chemical hazard classifications across these jurisdictions, as synchronized regulatory tightening would compress formulation flexibility and elevate compliance costs for multi-regional suppliers.
Market Dynamics
EU Green Deal embodied carbon requirements are redirecting specification decisions toward lower-carbon composite formulations, forcing reformulation investments across European supply chains while compressing margin structures for conventional polyester resin systems.
Growth Catalysts
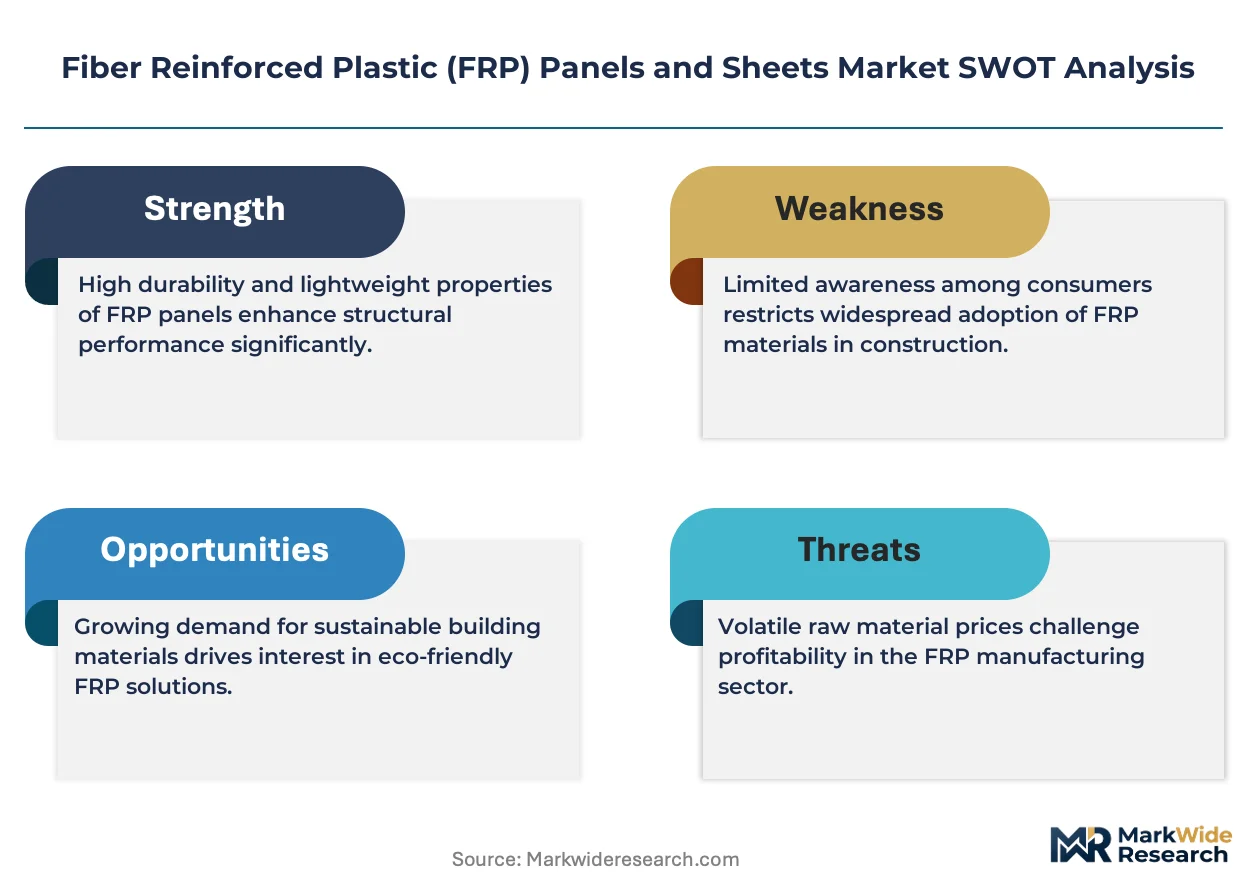
- Construction sector substitution:Builders specify FRP panels for corrosion-resistant cladding and structural applications, displacing traditional steel and concrete in chemical processing facilities and wastewater infrastructure.
- REACH compliance barriers:Hardening chemical hazard classifications for styrene-containing vinyl ester formulations protect established European manufacturers with integrated supply chains from low-cost import competition.
- Automotive lightweighting mandates:German rail manufacturers and automotive OEMs specify FRP interior panels to meet fleet weight reduction targets and improve energy efficiency metrics.
Market Restraints
- Raw material volatility:Glass fiber and resin feedstock prices fluctuate with energy costs, compressing margins for non-integrated fabricators lacking captive supply of reinforcement materials.
- Technical limitation in high-temperature service:Standard polyester and vinyl ester formulations degrade above 120°C, excluding FRP from exhaust systems and industrial ovens where metals retain dominance.
- Substitution threat from aluminum honeycomb:Aerospace and premium transportation segments specify aluminum core sandwich panels where fire resistance certification exceeds FRP capabilities.
Strategic Opportunities
- Antimicrobial gel-coat certification:Healthcare and food processing facilities demand certified hygiene performance, creating premium positioning for suppliers with validated antimicrobial surface technologies.
- Thermoplastic composite convergence:Recyclable thermoplastic matrices combined with continuous fiber reinforcement enable automotive closed-loop manufacturing and end-of-life material recovery.
- China MEE emission standard tightening:Jiangsu and Zhejiang province phenolic resin restrictions create import substitution opportunities for compliant foreign suppliers with cleaner production technologies.
Industry Challenges
- Styrene exposure compliance:OSHA permissible exposure limits require ventilation and PPE investments in fabrication shops, elevating operational costs relative to automated metal processing.
- Multi-jurisdictional chemical hazard tracking:Synchronized regulatory tightening across EPA, ECHA, and MEE jurisdictions compresses formulation flexibility and elevates compliance costs for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Reinforced Plastic (FRP) Panels and Sheets Market |
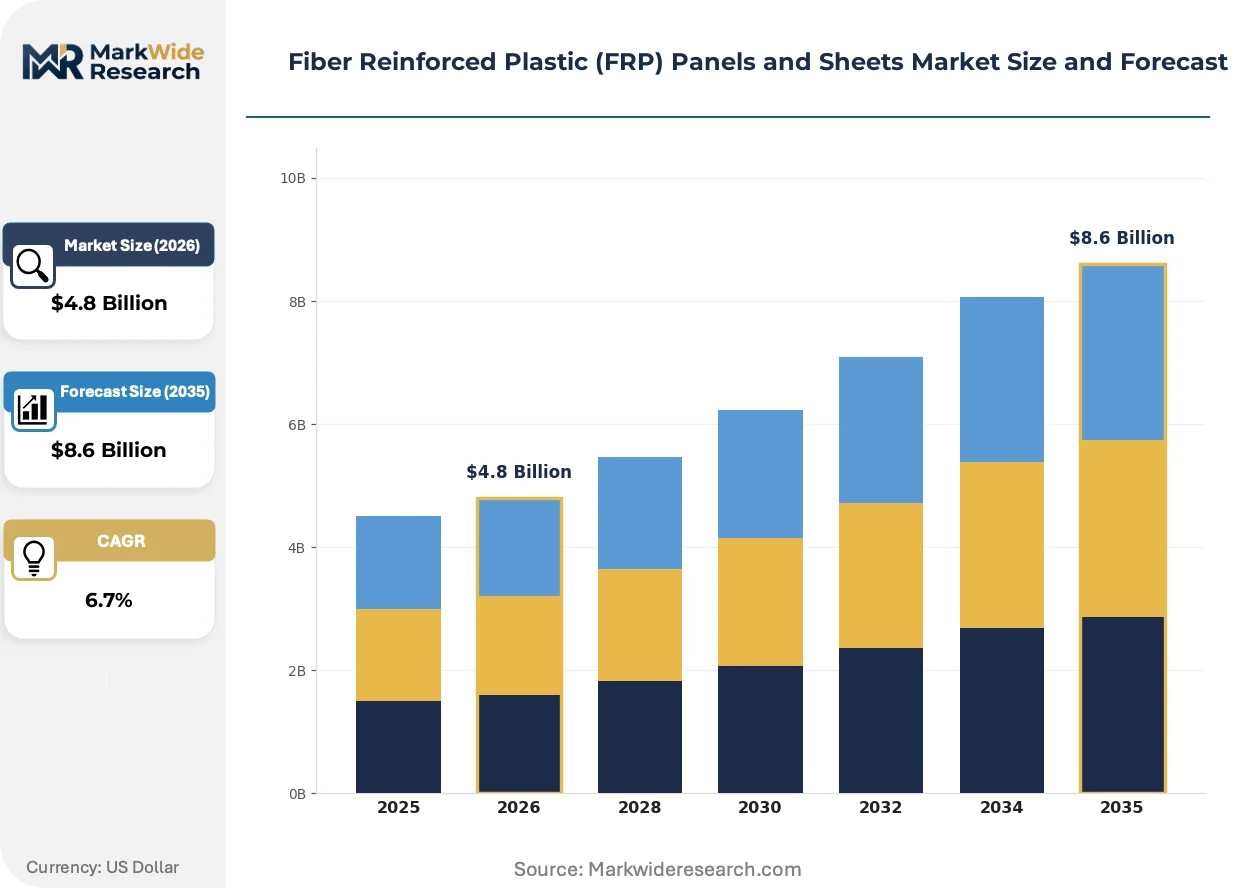
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Sheets, Rolls, Custom Shapes Material Type: Polyester, Vinyl Ester, Epoxy, Others End Use Industry: Construction, Automotive, Aerospace, Marine Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | Saint-Gobain, Owens Corning Corporation, Crane Composites Inc., Kingspan, 3A Composites GmbH, LAMILUX, Toray Industries, Inc., Polser Fiberglass Reinforced Plastics Inc., U.S. Liner Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Reinforced Plastic (FRP) Panels and Sheets Market Emerging Trajectories
Active reformulation of polymer matrices and reinforcement architectures is compressing the performance gap between commodity construction grades and high-specification transportation materials.
Thermoplastic composites with polypropylene and polyamide matrices are absorbing engineering investment from automotive tier suppliers seeking recyclable alternatives to thermoset epoxy systems. BMW and Mercedes-Benz interior programs specify these materials for door panels and seat structures. The technology is absorbing volume from conventional injection-molded plastics while displacing thermoset FRP in non-structural applications.
ECHA REACH restrictions on dibutyl phthalate plasticizers and cobalt carboxylate accelerators are forcing European manufacturers to reformulate polyester resin catalyst systems. Suppliers with in-house chemistry capabilities accelerate alternative accelerator development. Small-batch construction fabricators without technical resources face extended certification timelines and procurement disruption.
Buyers in transportation OEM supply programs consolidate vendor bases and demand flat-stock processing compatibility for automated cutting and bonding operations. Tier 1 suppliers specify sheet formats over molded panels to integrate with robotic assembly lines. German and Japanese automotive manufacturers lead this specification shift, compressing demand for traditional hand-lay-up panel configurations.
Fiber Reinforced Plastic (FRP) Panels and Sheets Market Segmentation
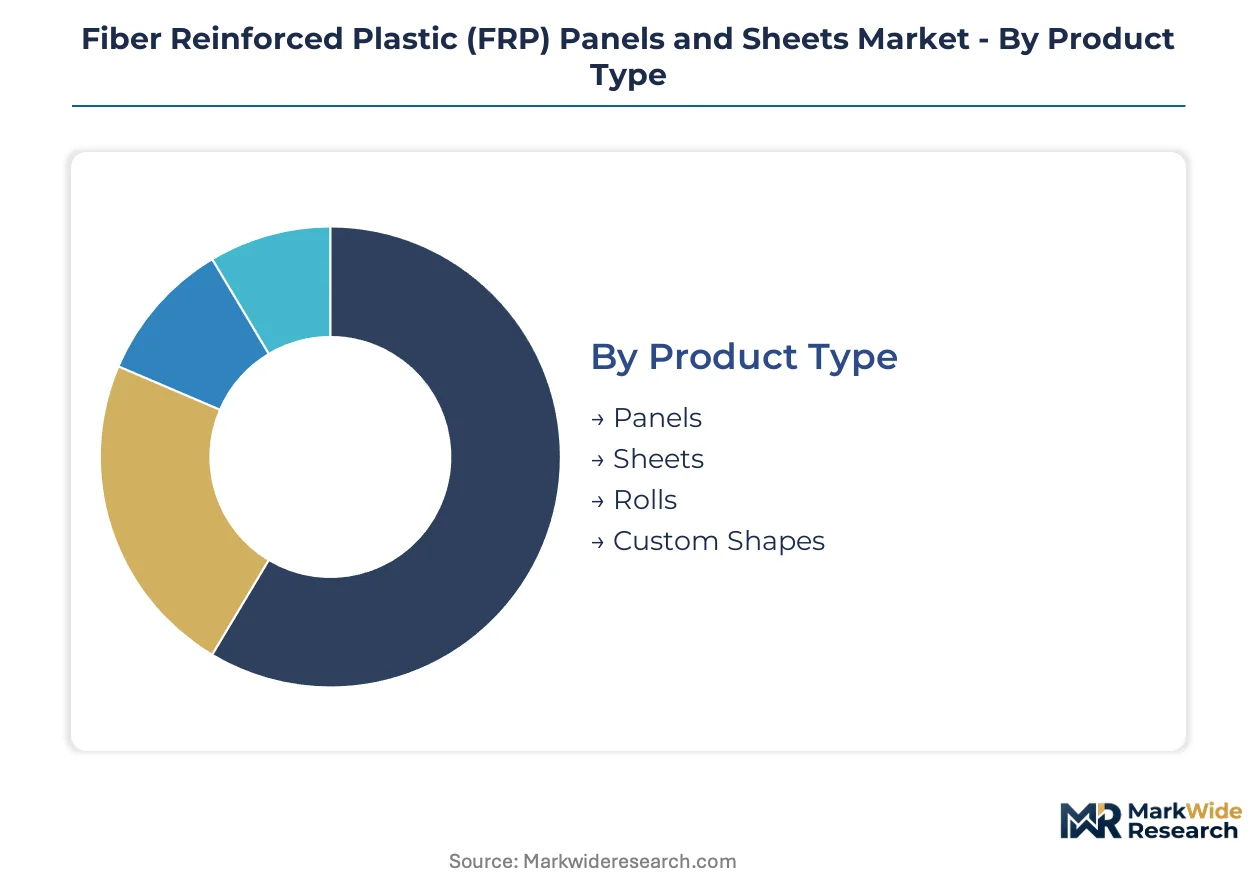
FRP panel and sheet manufacturers configure production lines around dimensional formats, resin chemistries, and thickness tolerances that dictate end-use eligibility. Specification decisions cascade from these technical foundations through to installation methods and lifecycle performance guarantees.
Product Type:
Standardization dominates commodity construction supply while custom geometries command premium positioning in OEM transportation programs.
- Panels:Rigid laminated configurations with gel-coated surfaces serve as structural cladding and interior wall systems. Construction sector procurement concentrates in Germany and the US Gulf Coast chemical corridor, driven by corrosion-resistant infrastructure replacement cycles.
- Sheets:Flat-stock formats enable automated cutting, drilling, and bonding operations in automotive and rail assembly lines. German automotive OEMs specify these for interior trim and seat substrates to satisfy fleet weight reduction mandates.
- Rolls:Continuous flexible laminates support roofing membrane and tank lining applications with reduced seam requirements.
- Custom Shapes:Molded or thermoformed geometries address equipment housings and architectural features requiring compound curves.
Most installed capacity flows through Panels. Expansion is steepest in Sheets.
Material Type:
Cost-performance positioning stratifies across resin families, with commodity formulations absorbing volume and engineered systems capturing margin.
- Polyester:Orthophthalic and isophthalic formulations dominate construction and marine volume production through established supply chains and processing familiarity. EU Green Deal embodied carbon requirements are redirecting specification decisions toward lower-carbon composite formulations, compressing margin structures for conventional polyester systems.
- Vinyl Ester:Hybrid chemistry delivers superior chemical resistance and toughness for chemical processing infrastructure. REACH compliance barriers for styrene-containing formulations protect established European manufacturers with integrated supply chains.
- Epoxy:High-performance matrices serve aerospace primary structures and premium automotive applications where fatigue resistance justifies material cost premiums.
- Others:Phenolic and thermoplastic alternatives address fire resistance and recyclability requirements in regulated transportation segments.
Polyester commands the largest production footprint. Vinyl Ester is gaining share fastest in corrosion-resistant infrastructure.
End Use Industry:
Application requirements diverge sharply between weathering-exposed construction and precision-tolerance transportation manufacturing.
- Construction:Cladding, roofing, and structural applications displace steel and concrete in corrosive environments. Builders specify FRP panels for wastewater treatment facilities and chemical processing plants across Germany, the Netherlands, and the US Gulf Coast.
- Automotive:Interior panels and structural reinforcements reduce vehicle mass. German rail manufacturers and automotive OEMs specify FRP interior panels to meet fleet weight reduction targets.
- Aerospace:Primary and secondary structures demand epoxy-based prepregs with certified traceability and autoclave processing.
- Marine:Hull construction and deck applications leverage FRP durability in saltwater environments with reduced maintenance cycles.
Construction absorbs the majority of tonnage. Automotive represents the steepest expansion trajectory.
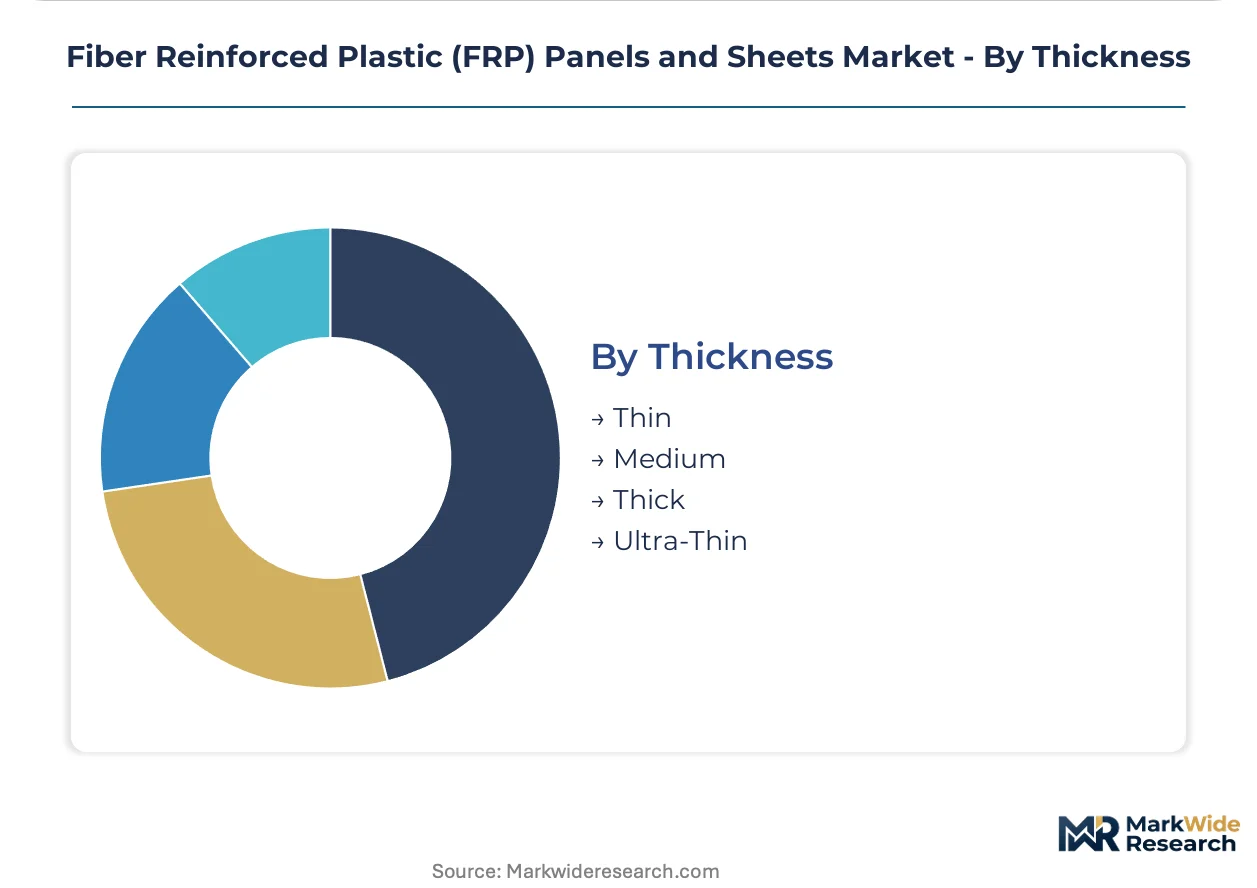
Thickness:
Structural load requirements and processing constraints segment demand across dimensional tolerances.
- Thin:Sub-2mm laminates serve decorative surfacing and non-structural cladding with reduced material cost.
- Medium:2-6mm configurations balance stiffness and weight for general-purpose panel applications.
- Thick:Heavy-section laminates above 6mm provide structural capacity for load-bearing walls and equipment bases.
- Ultra-Thin:Sub-millimeter films enable surface protection and membrane applications with minimal added mass.
Medium thickness commands the dominant production share. Ultra-Thin is climbing the fastest as electronics and aerospace surface protection applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized composite fabrication workforces cluster around chemical processing corridors and automotive manufacturing belts, anchoring demand geography for corrosion-resistant panel systems and lightweight interior substrates.
Germany
Rail manufacturers and automotive OEMs specify FRP interior panels to satisfy fleet weight reduction targets under EU CO2 regulations. ECHA REACH restrictions on cobalt carboxylate accelerators force polyester resin reformulation across Baden-Württemberg fabrication shops. The Stuttgart automotive belt concentrates specification authority for thermoplastic composite interior programs at BMW and Mercedes-Benz tier suppliers.
United States
Chemical processing facilities along the Gulf Coast drive corrosion-resistant cladding replacement cycles for FRP panel systems. EPA Clean Air Act provisions govern styrene emissions from fabrication facilities in Texas and Louisiana. Houston-area petrochemical infrastructure maintenance generates sustained demand for vinyl ester formulations in tank lining and ductwork applications.
China
Jiangsu and Zhejiang province phenolic resin producers face tightened MEE emission standards that compress capacity for conventional formulations. The Yangtze River Delta manufacturing cluster absorbs imported compliant materials for wind energy and transportation applications. Shanghai-based composite engineering centers accelerate thermoplastic matrix development for automotive lightweighting programs.
Japan
Automotive tier suppliers integrate FRP sheet formats into robotic assembly lines for interior trim and structural reinforcement applications. METI carbon neutrality roadmaps pressure material suppliers toward lower-embodied-carbon composite formulations. The Nagoya automotive manufacturing corridor concentrates demand for flat-stock processing compatibility in Toyota and Honda supply programs.
India
Infrastructure investment in chemical processing and wastewater treatment expands specification of FRP panels for corrosion-resistant construction applications. BIS standards for composite materials harden certification requirements for imported resin systems. Gujarat's petrochemical corridor anchors domestic fabrication capacity serving refinery and desalination plant projects.
Fiber Reinforced Plastic (FRP) Panels and Sheets Market Vendor Landscape
The competitive structure tilts toward integrated material suppliers with captive glass fiber production and specialized fabricators with certified antimicrobial or fire-resistant formulations. Tier 1 automotive supply programs consolidate vendor bases around flat-sheet processing capability, while construction sector procurement fragments across regional fabrication shops. Two strategic archetypes dominate: integrated glass-reinforcement producers controlling upstream raw material costs, and application specialists commanding premium positioning through certified performance guarantees. Capacity expansion and thermoplastic composite technology licensing represent the dominant competitive vectors as suppliers reposition for recyclable material mandates.
Among integrated material suppliers, Saint-Gobain and Owens Corning Corporation exemplify the backward-integrated archetype with in-house glass fiber supply chains that buffer margin pressure from resin feedstock volatility. Crane Composites Inc. occupies a specialist position within the certified-performance tier, representing fabricators that differentiate on validated antimicrobial gel-coat technologies rather than commodity pricing. These three companies span the structural spectrum from raw material integration through application-specific formulation expertise.
| Leading Market Players |
|---|
| Saint-Gobain |
| Owens Corning Corporation |
| Crane Composites Inc. |
| Kingspan |
| 3A Composites GmbH |
| LAMILUX |
| Toray Industries, Inc. |
| Polser Fiberglass Reinforced Plastics Inc. |
| U.S. Liner Company |
| Others |
Supply Flow & Price Mechanics
German automotive OEM procurement programs concentrate specification authority for FRP interior panels, compressing vendor margins through consolidated volume commitments while rewarding flat-stock processing capability with contract stability.
Pricing Analysis
Material-plus-fabrication bundling dominates construction sector procurement, while unbundled raw material supply prevails in automotive tier programs. Three-tier pricing structure across premium, standard, and economy levels separates certified antimicrobial gel-coat formulations from commodity polyester systems. Cost compression in standard-grade panels is intensifying because REACH-compliant vinyl ester reformulations elevate catalyst system costs. Construction fabricators exhibit highest price sensitivity due to fragmented procurement, whereas healthcare facilities accept premium positioning for validated hygiene performance.
Supply Chain Analysis
Regional distribution centers in Houston, Stuttgart, and Shanghai anchor hub-and-spoke patterns for resin and reinforcement materials. Glass fiber production concentrates in China, the United States, and Germany, while specialty epoxy formulations source from Japan and South Korea. Raw material supply rests on petroleum-derived resin feedstocks, borosilicate glass batch, and cobalt carboxylate accelerator chemicals. Single-source vulnerability in ECHA-restricted accelerator compounds elevates procurement risk for European fabricators. Distribution runs through chemical processing corridors with co-located fabrication capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on thermoplastic composite conversion, where recyclable matrix systems command premium positioning while eliminating end-of-life disposal liabilities.
For Market Incumbents: Deploy captive glass fiber supply chains to buffer styrene and resin feedstock volatility. Owens Corning Corporation and Saint-Gobain exemplify this defensive posture through backward integration into reinforcement manufacturing. Capacity addition in Baden-Württemberg fabrication clusters protects German automotive supply relationships from import competition. Certification investment in antimicrobial gel-coat technologies defends Crane Composites Inc.'s healthcare positioning against commodity polyester substitution. For New Entrants and Emerging Players: Enter via compliant phenolic resin supply to Jiangsu and Zhejiang province manufacturers facing MEE emission standard tightening. White-space concentration in China's wind energy sector and India's Gujarat petrochemical corridor offers penetrable entry points. Food processing facilities in the Netherlands and Belgium demand certified hygiene performance with limited incumbent specialization. Go-to-market execution should anchor on validated surface technology partnerships rather than commodity volume pricing. For Investors and Strategic Acquirers: Automotive tier suppliers with thermoplastic composite capabilities are the most active acquirer in this space, consolidating vendor bases around recyclable material mandates. Long-term viability favors targets with in-house chemistry reformulation capabilities to navigate synchronized EPA, ECHA, and MEE regulatory tightening. Vertically integrated fabricators with captive glass fiber supply command scarcity premiums. Watch for REACH restriction expansion on additional cobalt compounds as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Production | Saint-Gobain controls reinforcement costs through captive supply chains across European chemical corridors. |
| Thermoplastic Matrix Development | BMW and Mercedes-Benz tier suppliers specify polyamide-based composites for recyclable interior programs. |
| Antimicrobial Gel-Coat Certification | Crane Composites Inc. differentiates on validated hygiene performance for healthcare and food processing facilities. |
| REACH-Compliant Accelerator Reformulation | ECHA restrictions on cobalt carboxylate force European manufacturers toward alternative catalyst chemistry investments. |
| Flat-Stock Processing Capability Expansion | German automotive OEMs consolidate vendor bases around sheet formats compatible with robotic assembly lines. |
Methodological Framework
Direct dialogue with composite fabrication plant managers, automotive Tier 1 procurement officers, chemical processing facility maintenance directors, and ECHA regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from EPA Clean Air Act enforcement records, ECHA REACH restriction updates, China MEE emission standard filings, and SEC 10-K disclosures from integrated glass fiber producers. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across the analysis window.
Bottom-up modeling tracked resin chemistry, reinforcement architecture, and dimensional format segmentation, while top-down approaches validated against end-use industry consumption patterns. The projection horizon spans construction sector replacement cycles, automotive lightweighting program rollouts, and chemical infrastructure maintenance schedules. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs incorporated EU Green Deal embodied carbon trajectory assumptions and REACH regulatory expansion scenarios.
Inputs from automotive OEM procurement databases and chemical processing facility maintenance records were available through the study window; gaps in small-batch construction fabricator financial disclosures introduce uncertainty bands in margin structure estimates. Forecasts reflect documented assumptions on regulatory synchronization timing and thermoplastic composite adoption velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Sports Composites Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
Pultrusion Market
Composite Materials
Graphite Felt Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Synthetic Rope Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
Europe Composites Market