
 Global Carbon Felt and Graphite Felt Market | 2026-2036
Global Carbon Felt and Graphite Felt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Felt and Graphite Felt Market Foresight
High-purity aerospace-grade felt specifications is redrawing competitive boundaries across the supply base. Mersen leverages vertical integration from precursor fibers to finished felt rolls, sustaining quality consistency for furnace insulation buyers. SGL Carbon anchors European supply through captive carbonization assets in Germany and France. Toray Industries dominates PAN-based precursor technology, extending its polymer expertise into downstream felt production.
Carbon felt and graphite felt are non-woven fibrous structures manufactured from polyacrylonitrile (PAN), rayon, or pitch precursors through controlled oxidative stabilization and carbonization at temperatures exceeding 1,000°C, with graphite variants undergoing additional graphitization above 2,500°C to achieve thermal conductivity below 0.15 W/m·K and purity levels exceeding 99.9%. These materials serve primarily as high-temperature insulation, electrochemical electrodes, and filtration media in oxidizing or inert atmospheres up to 3,000°C. Carbon felt leads volume shipments for vacuum furnace insulation across steel manufacturing, while graphite felt captures premium pricing in energy storage electrodes where low electrical resistivity below 5 mΩ·cm proves critical. Siliconized felt variants represent the fastest-growing product category as chemical processing operators seek combined thermal and corrosion resistance.
FDA oversight of medical device sterilization equipment, EPA emissions rules for hazardous waste incineration, and China's GB standards for carbon fiber reinforced composites collectively tighten material traceability and purity documentation requirements. ECHA REACH compliance for imported carbon articles forces non-European suppliers to disclose precursor chemistries and heavy metal content. Stakeholders must monitor evolving battery-grade purity specifications from multiple national regulators before committing to capacity expansion in electrode-facing felt grades.
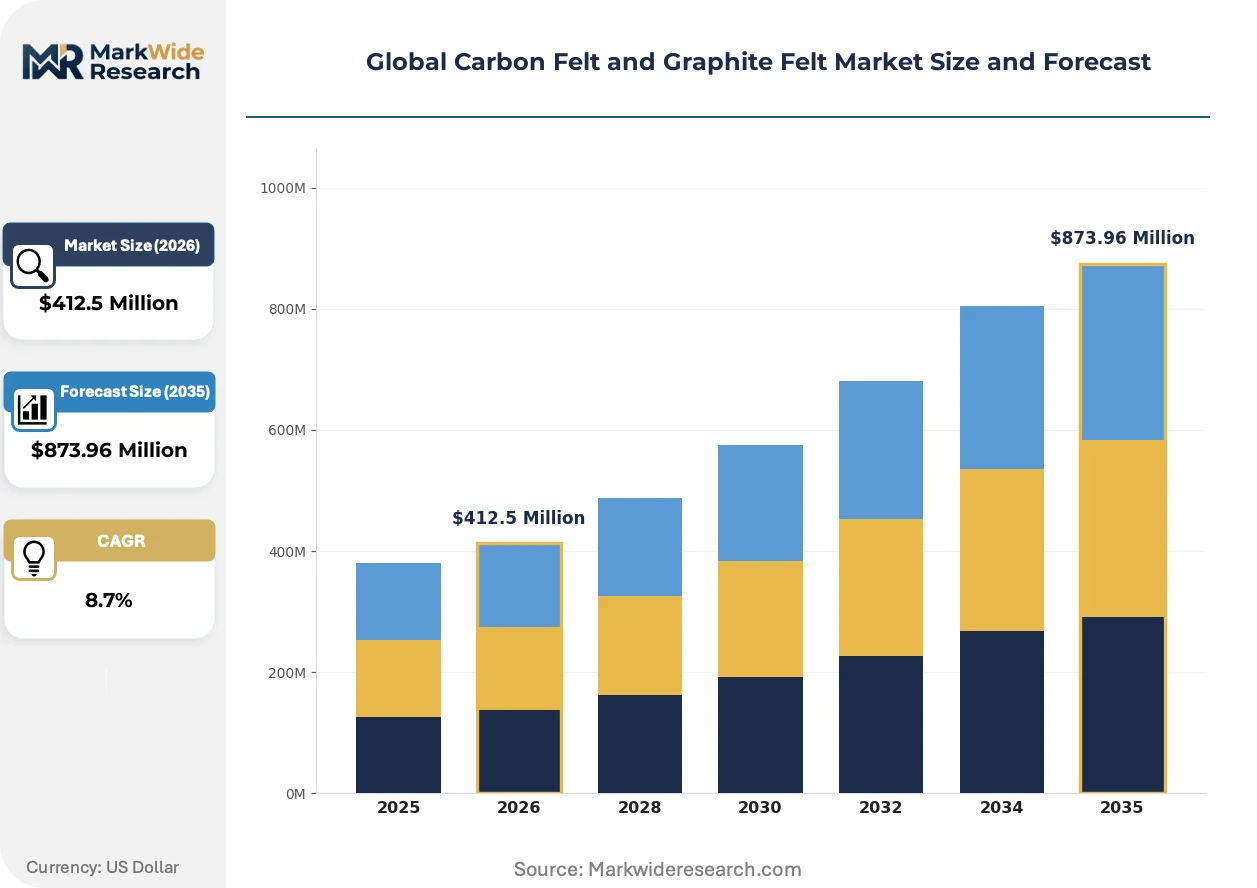
Market Dynamics
High-temperature furnace insulation specifications are tightening across steel and semiconductor manufacturing, forcing felt suppliers to certify batch-to-batch thermal conductivity below 0.15 W/m·K while scaling production of battery-grade electrode materials for energy storage systems.
Growth Catalysts
- China's dual carbon goals:MEE emissions benchmarks are accelerating furnace retrofits in Jiangsu and Shandong provinces, pulling demand for low-thermal-conductivity insulation in steel heat treatment.
- Solid-state battery commercialization:Siliconized felt electrodes are displacing conventional graphite anodes in next-generation cell architectures, requiring 99.9%+ purity carbon structures.
- Specialty chemical processing:German industrial clusters around Ludwigshafen and Leverkusen are specifying corrosion-resistant felt filtration for high-temperature acid gas handling.
Market Restraints
- Precursor fiber concentration:PAN supply chains concentrate among three Asian polymer producers, exposing felt manufacturers to acrylonitrile price volatility and allocation constraints.
- Graphitization capacity scarcity:Furnaces capable of sustained 2,500°C operation are concentrated in Germany, France, and Japan, creating bottlenecks for aerospace-grade material qualification.
- Ceramic fiber substitution:Aluminosilicate and polycrystalline wool alternatives are capturing furnace insulation share below 1,400°C operating temperatures.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are creating first-mover opportunities for electrode-facing felt localization outside established East Asian supply bases.
- Green hydrogen electrolysis:Proton exchange membrane and solid oxide electrolyzer stacks are emerging as high-volume applications for corrosion-resistant bipolar plate substrates.
- Digital inventory platforms:Direct procurement links between felt converters and furnace operators are compressing distributor margins while enabling specification-grade traceability documentation.
Industry Challenges
- Carbonization operator expertise:Controlled oxidative stabilization requires skilled technicians capable of managing exothermic reaction kinetics across 200-300°C temperature ramps, with talent concentrated in legacy European and Japanese facilities.
- Multi-regulator certification timelines:Concurrent FDA device sterilization, EPA hazardous waste incineration, and ECHA REACH compliance for a single product line extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Felt and Graphite Felt Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Felt, Graphite Felt, Siliconized Felt, Alumina-Coated Felt, Others Technology: Needle Punching, Air Lay, Wet Laid, Thermobonding Application: Thermal Insulation, Filtration Media, Electrodes, Energy Storage, Aerospace Sealing End User Industry: Steel Manufacturing, Electronics Fabrication, Aerospace Engineering, Chemical Processing |
| Companies Covered | Mersen, SGL Carbon, Toray Industries, Kureha Corporation, Nippon Carbon Co. Ltd., Morgan Advanced Materials, Beijing Great Wall Co. Ltd., CGT Carbon GmbH, Chemshine Carbon Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Felt and Graphite Felt Market Shifts & Advancements
Material science advances and regulatory traceability mandates are converging to redefine competitive advantage, with purity documentation and thermal performance verification becoming inseparable from commercial viability across high-specification end uses.
Siliconized felt variants are fragmenting the traditional product hierarchy by combining thermal insulation with acid gas corrosion resistance in single-layer configurations. Chemical processing operators in Germany's Rhine-Ruhr industrial corridor are specifying these materials for combined heat recovery and emission control systems. The technology is fragmenting procurement patterns that previously required separate ceramic and carbonaceous material layers.
REACH Article 33 disclosure obligations for imported carbon articles are forcing non-European suppliers to document precursor chemistries and heavy metal content down to 0.1% concentration thresholds. ECHA compliance teams are rejecting shipments lacking full Substances of Very High Concern traceability. Battery-grade felt imports into Rotterdam and Antwerp terminals now face mandatory third-party purity certification before customs release.
Long-term supply agreements with indexed precursor pricing are displacing spot market purchasing among major furnace insulation buyers. Steel heat treatment operators in the US Great Lakes region and Japan's Chubu industrial belt are locking in three-to-five-year carbon felt volumes to secure allocation. This contracting pattern concentrates procurement leverage among buyers with certified demand forecasts, marginalizing smaller heat treatment shops without ESG disclosure capabilities.
Global Carbon Felt and Graphite Felt Market Segmentation
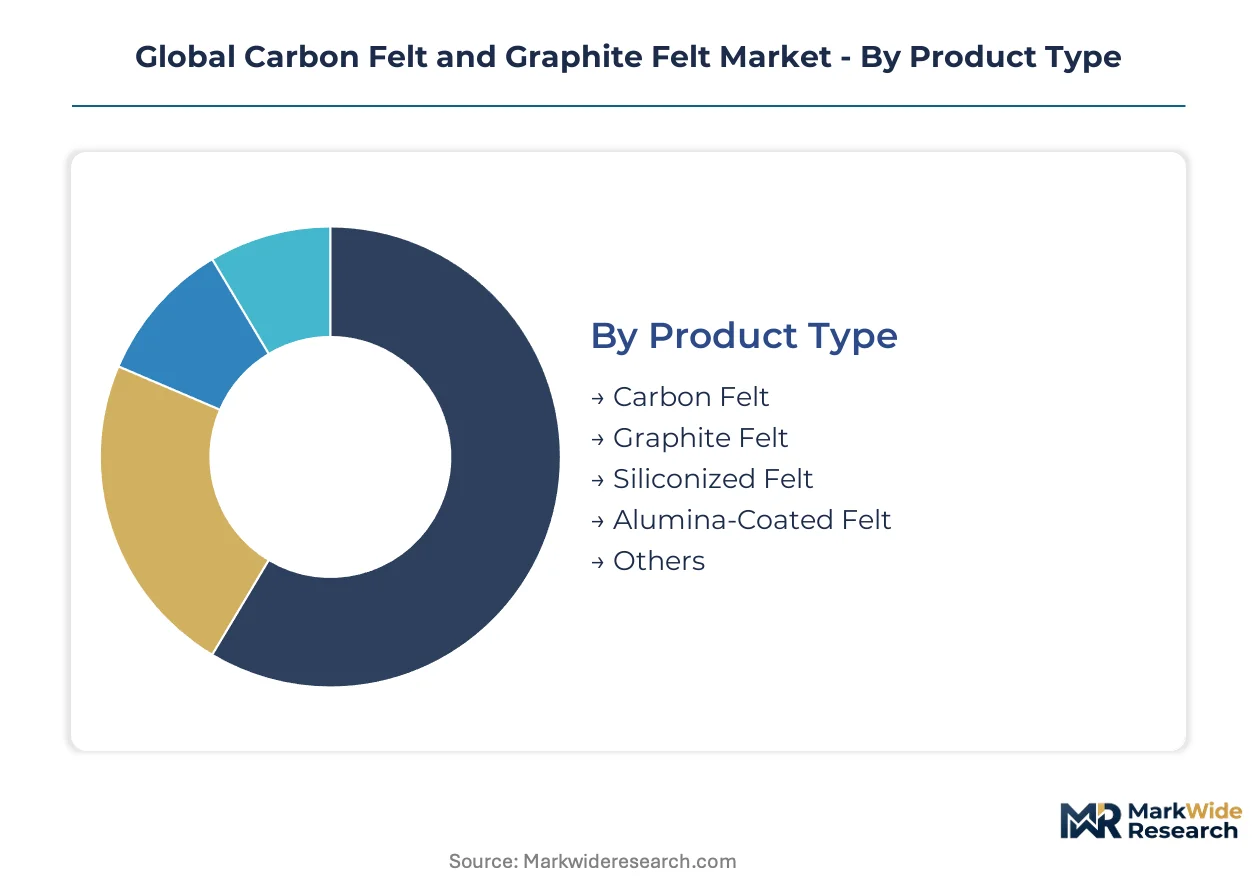
Carbon felt and graphite felt procurement patterns diverge sharply across product grades and end-use specifications. Each segment carries distinct thermal performance thresholds, purity documentation burdens, and substitution vulnerability profiles that reshape supplier positioning.
Product Type:
Alumina-coated and siliconized variants face acute pressure from ceramic fiber substitutes in furnace insulation below 1,400°C, while high-purity grades defend their positions through battery-grade certification requirements.
- Carbon Felt:PAN-derived non-woven structures carbonized above 1,000°C dominate vacuum furnace insulation across steel heat treatment operations. Demand concentrates in Japan's Chubu industrial belt where operators prioritize batch-to-batch thermal conductivity consistency below 0.15 W/m·K for heat treatment uniformity.
- Graphite Felt:Additional graphitization above 2,500°C yields purity exceeding 99.9% and electrical resistivity below 5 mΩ·cm. Solid-state battery developers in Germany's Baden-Württemberg cluster are qualifying these materials for next-generation electrode architectures requiring corrosion-resistant current collectors.
- Siliconized Felt:Chemical vapor infiltration of silicon carbide layers creates combined thermal and acid gas resistance for single-layer configurations in chemical processing.
- Alumina-Coated Felt:Surface ceramic coating extends oxidation resistance in aggressive atmospheres while maintaining carbonaceous core insulation properties.
- Others:Specialty grades including pitch-based felts for ultra-high-temperature applications above 2,800°C in semiconductor crystal growth furnaces.
Carbon felt anchors the volume base while siliconized felt gains share at the steepest rate.
Technology:
Manufacturing method selection hinges on fiber orientation control and throughput economics, with needle punching commanding premium furnace insulation contracts while air lay serves cost-sensitive filtration applications.
- Needle Punching:Mechanical entanglement of carbonized fibers produces controlled density gradients for thermal insulation performance. European furnace OEMs in Austria and Italy specify needle-punched structures for their superior dimensional stability under thermal cycling.
- Air Lay:Random fiber dispersion through air currents enables high-throughput production of lower-density filtration media. Water treatment operators in India's Gujarat state favor air-laid constructions for cost-effective particulate capture in aggressive chemical environments.
- Wet Laid:Aqueous suspension forming achieves uniform thin-gauge sheets for electrode substrates requiring precise thickness control.
- Thermobonding:Partial melting of thermoplastic binder fibers creates rigid felt structures for aerospace sealing applications requiring compression set resistance.
Needle punching commands the premium tier while air lay scales most efficiently for commoditized filtration demand.
Application:
Electrode-facing applications impose the steepest purity documentation burdens, with battery-grade certification timelines extending 18-24 months across concurrent FDA, EPA, and ECHA REACH compliance pathways.
- Thermal Insulation:Low-thermal-conductivity structures for vacuum and inert atmosphere furnaces operating up to 3,000°C. Steel heat treatment shops in the US Great Lakes region are locking in three-to-five-year supply agreements to secure allocation against precursor fiber scarcity.
- Energy Storage:Battery-grade felt electrodes for lithium-ion and emerging solid-state cell architectures. China's Jiangsu province battery manufacturers are driving qualification of 99.9%+ purity graphite felt for siliconized anode integration.
- Filtration Media:High-temperature particulate and acid gas capture in chemical processing operations.
- Electrodes:Electrochemical cell components for water treatment and metal recovery applications.
- Aerospace Sealing:Compression-resistant gaskets and thermal barriers for turbine and propulsion systems.
Thermal insulation generates the highest shipment volumes while energy storage applications expand most quickly.
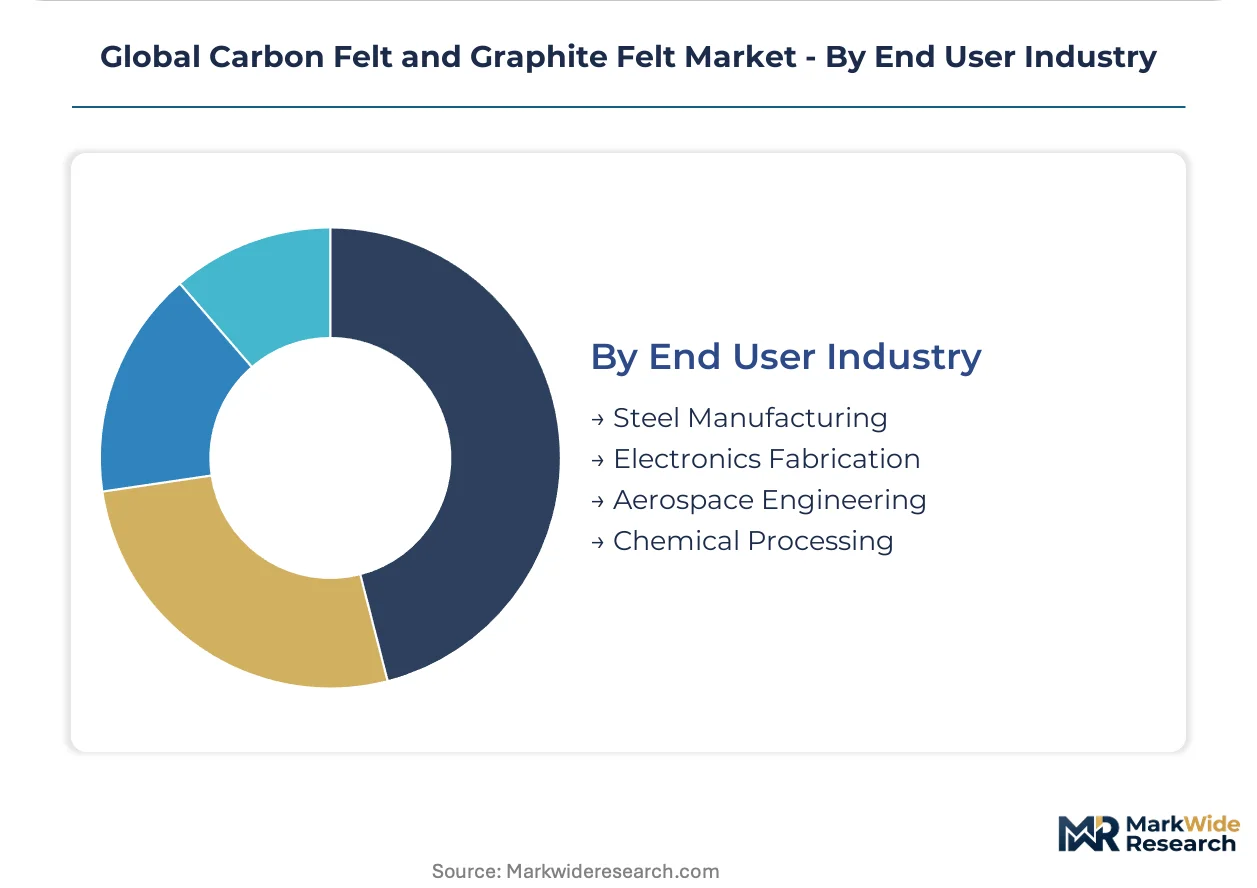
End User Industry:
Steel manufacturing's furnace retrofit cycle and aerospace engineering's lightweighting mandates create divergent demand profiles, with chemical processing emerging as the fastest-adopting sector for corrosion-resistant siliconized grades.
- Steel Manufacturing:Vacuum heat treatment and sintering furnace insulation for tool steel and specialty alloy production. Operators in China's Shandong province are accelerating furnace upgrades to meet MEE emissions benchmarks, pulling demand for low-thermal-conductivity insulation with documented batch consistency.
- Chemical Processing:High-temperature filtration and acid gas handling in specialty chemical and petrochemical operations. German industrial clusters around Ludwigshafen and Leverkusen are specifying siliconized felt for combined heat recovery and emission control in single-layer configurations.
- Electronics Fabrication:Semiconductor crystal growth furnace insulation and wafer processing thermal management.
- Aerospace Engineering:Lightweight thermal protection systems and propulsion sealing components requiring FAA certification traceability.
Steel manufacturing anchors procurement volumes while chemical processing drives the steepest technology substitution toward corrosion-resistant grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German graphitization facilities export aerospace-grade felt to US battery manufacturers, while Chinese carbonization plants supply furnace insulation to Japan's steel heat treatment sector. This trade architecture concentrates high-value qualification expertise in Western Europe and Japan while scaling commodity production across East Asia.
United States
Steel heat treatment operators in the Great Lakes region are locking in multi-year carbon felt contracts to secure allocation against precursor fiber scarcity. EPA hazardous waste incineration rules tighten material traceability requirements for furnace insulation buyers. Detroit-area automotive tool steel shops prioritize batch-to-batch thermal conductivity certification below 0.15 W/m·K.
Germany
Baden-Württemberg solid-state battery developers are qualifying graphite felt electrodes for siliconized anode integration. ECHA REACH Article 33 disclosure obligations force suppliers to document precursor chemistries and heavy metal content down to 0.1% thresholds. Ludwigshafen chemical processing clusters specify siliconized felt for combined heat recovery and acid gas handling.
China
Jiangsu and Shandong province steel manufacturers are accelerating furnace retrofits to meet MEE dual carbon emissions benchmarks. GB standards for carbon fiber reinforced composites tighten material traceability and purity documentation requirements. Shanghai-area battery manufacturers drive qualification of 99.9%+ purity graphite felt for energy storage electrodes.
Japan
Chubu industrial belt vacuum furnace operators demand consistent thermal conductivity performance for specialty alloy heat treatment. METI industrial decarbonization programs incentivize low-emission furnace insulation upgrades. Nagoya-area carbonization facilities concentrate skilled technician expertise for controlled oxidative stabilization processes.
India
Gujarat water treatment operators favor air-laid felt constructions for cost-effective particulate capture in aggressive chemical environments. PLI scheme incentives for advanced chemistry cells create first-mover opportunities for electrode-facing felt localization. Maharashtra industrial corridors are emerging as procurement hubs for furnace insulation serving domestic steel expansion.
Global Carbon Felt and Graphite Felt Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and qualification timelines, with publicly traded entities leveraging balance sheet capacity for multi-year precursor contracts while private fabricators concentrate on batch-customization for certified end uses. The supplier base fragments vertically rather than horizontally, with carbonization expertise concentrating in legacy European and Japanese facilities against downstream converting capacity scaling across China and India. Three archetypes dominate: integrated precursor-to-felt manufacturers, captive carbonization specialists, and regional converters dependent on merchant fiber supply. Competitive moves center on backward integration into PAN precursor production and long-term offtake agreements with battery-grade buyers.
Among European integrated manufacturers, Mersen and SGL Carbon exemplify the precursor-to-felt archetype through captive carbonization assets, while Toray Industries anchors the polymer-origin tier extending PAN-based expertise downstream. These three occupy positions spanning furnace insulation and battery electrode supply chains, with their geographic footprints reflecting historical carbonization infrastructure concentration.
| Leading Market Players |
|---|
| Mersen |
| SGL Carbon |
| Toray Industries |
| Kureha Corporation |
| Nippon Carbon Co. Ltd. |
| Morgan Advanced Materials |
| Beijing Great Wall Co. Ltd. |
| CGT Carbon GmbH |
| Chemshine Carbon Co. Ltd. |
| Others |
Supply & Pricing Matrix
Ninety-day precursor fiber lead times concentrate procurement leverage among buyers with certified demand forecasts, compressing margins for smaller furnace operators while amplifying pricing power for integrated manufacturers with captive PAN supply. This inventory dynamic reinforces the premium commanded by aerospace-grade qualification holders against commodity insulation suppliers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across premium, standard, and economy tiers differentiated by certification grade and volume scale. Battery-grade graphite felt with ECHA REACH documentation commands substantial premiums over furnace insulation grades lacking traceability. Cost compression in standard-grade carbon felt intensifies as ceramic fiber substitutes capture share below 1,400°C applications. Small heat treatment shops exhibit highest price sensitivity due to ESG disclosure capability gaps, while solid-state battery developers show lowest sensitivity given 18-24 month qualification timelines.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for merchant fiber buyers lacking regional carbonization assets. PAN precursor production centers on Japan, South Korea, and China, while graphitization capacity concentrates in Germany, France, and Japan. The supply chain draws from acrylonitrile feedstocks, carbonized fiber intermediates, and silicon carbide coating chemistries. Single-source vulnerability in 2,500°C graphitization furnaces creates structural risk for aerospace-grade material qualification. Distribution runs through direct procurement links between felt converters and furnace operators, compressing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through multi-jurisdiction certification timelines creates formidable switching costs for qualified suppliers.
For Market Incumbents: Consolidate backward integration into PAN precursor production to secure allocation against acrylonitrile price volatility. Lock in three-to-five-year offtake agreements with battery-grade buyers before India's PLI scheme matures domestic electrode-facing capacity. Ceramic fiber substitution below 1,400°C represents the priority threat requiring siliconized felt portfolio expansion. For New Entrants and Emerging Players: ECHA REACH fast-track certification for imported carbon articles offers entry path into Rotterdam and Antwerp battery material terminals. Target India's Gujarat and Maharashtra industrial corridors where PLI incentives for advanced chemistry cells outpace qualified local supply. Green hydrogen electrolyzer bipolar plate substrates present the most penetrable white-space application. Lead with cost-effective air-laid constructions for water treatment filtration to establish operational footprint before pursuing furnace insulation qualification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized carbonization assets in legacy European facilities. Five-to-ten year viability hinges on solid-state battery commercialization trajectories and furnace retrofit cycles in Chinese steel provinces. Monitor MEE emissions benchmark enforcement intensity in Jiangsu and Shandong as inflection indicator for insulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Mersen and SGL Carbon sustain quality consistency through captive fiber supply for furnace insulation buyers. |
| Long-term Supply Agreement | Steel heat treatment operators in the US Great Lakes region secure allocation against precursor scarcity. |
| Siliconized Felt Capacity Expansion | German chemical clusters around Ludwigshafen specify single-layer corrosion-resistant configurations. |
| REACH Compliance Certification | Non-European suppliers face mandatory third-party purity verification at Rotterdam and Antwerp terminals. |
| Green Hydrogen Electrolyzer Partnership | Proton exchange membrane stack manufacturers qualify corrosion-resistant bipolar plate substrates. |
Research Methodology
Desk research of customs trade data, SEC filings from carbon fiber producers, and ECHA REACH registration databases preceded structured interviews with furnace OEM procurement directors, battery manufacturer materials scientists, and carbonization plant operations managers. Primary fieldwork across Japan's Chubu industrial belt, Germany's Baden-Württemberg cluster, and India's Gujarat state validated secondary estimates. Bottom-up shipment analysis by product grade and end-use triangulated against top-down market sizing from precursor fiber consumption patterns.
Variance decomposition across product type, application, and regional production hub dimensions shaped the analytical framework over the projection horizon. Segment-level CAGRs derived from capacity expansion announcements, regulatory enforcement timelines, and substitution elasticity estimates for ceramic fiber alternatives. Forecast inputs incorporated MEE dual carbon goal implementation schedules and solid-state battery developer qualification pipelines.
Decision-makers should treat outputs as directional under sustained precursor fiber concentration and stable regulatory enforcement intensity; material deviation would warrant model refresh. Forecasts reflect assumptions of continued graphitization capacity scarcity and battery-grade purity specification tightening. Precursor price volatility, ceramic fiber substitution acceleration, or relaxation of ECHA REACH disclosure obligations would require model recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Graphite Felt Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Composite Rollers Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Biocomposites Market
Composite Materials
Lightweight Materials Market
Composite Materials
Marine Composites Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Epoxy Composite Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Composites Testing Market