
 Aramid Fiber Reinforced Polymer Market | 2026-2036
Aramid Fiber Reinforced Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Aramid Fiber Reinforced Polymer Market Analytics
ISO 14839 qualification cycles for ballistic-grade aramid composites is reorganizing which suppliers qualify for defense tenders in Western markets. DuPont de Nemours leverages its Kevlar production heritage to dominate North American military contracts. Teijin Limited anchors Asian supply chains through integrated para-aramid spinning and prepreg operations. Yantai Tayho Advanced Materials competes on cost-adjusted performance in industrial-grade sheet goods.
Aramid fiber reinforced polymer denotes a class of high-performance composites where aromatic polyamide fibers, typically para-aramid with tensile moduli exceeding 70 GPa, are embedded within thermoset or thermoplastic matrices to yield specific strength ratios surpassing conventional metals. These materials primarily serve applications requiring extreme strength-to-weight performance under dynamic loading, including ballistic protection, pressure vessel containment, and structural reinforcement in weight-critical assemblies. Composite formulations lead product architecture due to their adaptability in layup configurations for aerospace skins and military vehicle hulls, while sheet segments sustain margin pools in industrial gasket and insulation markets where processing simplicity outweighs customization needs. Film and rod categories occupy narrower specialist niches in electrical barrier and tension-member applications respectively.
FAA airworthiness directives and EU REACH chemical registration frameworks jointly govern material qualification pathways for aerospace and industrial applications, with ECHA substance evaluations periodically restricting certain epoxy hardener chemistries used in aramid matrix systems. NHTSA crashworthiness standards for commercial and military vehicles in the United States create downstream specification pull that propagates through Tier-1 laminate converters. Stakeholders must monitor evolving dual-use export control classifications that could restrict aramid prepreg shipments to specific end-user categories without de minimis content thresholds.
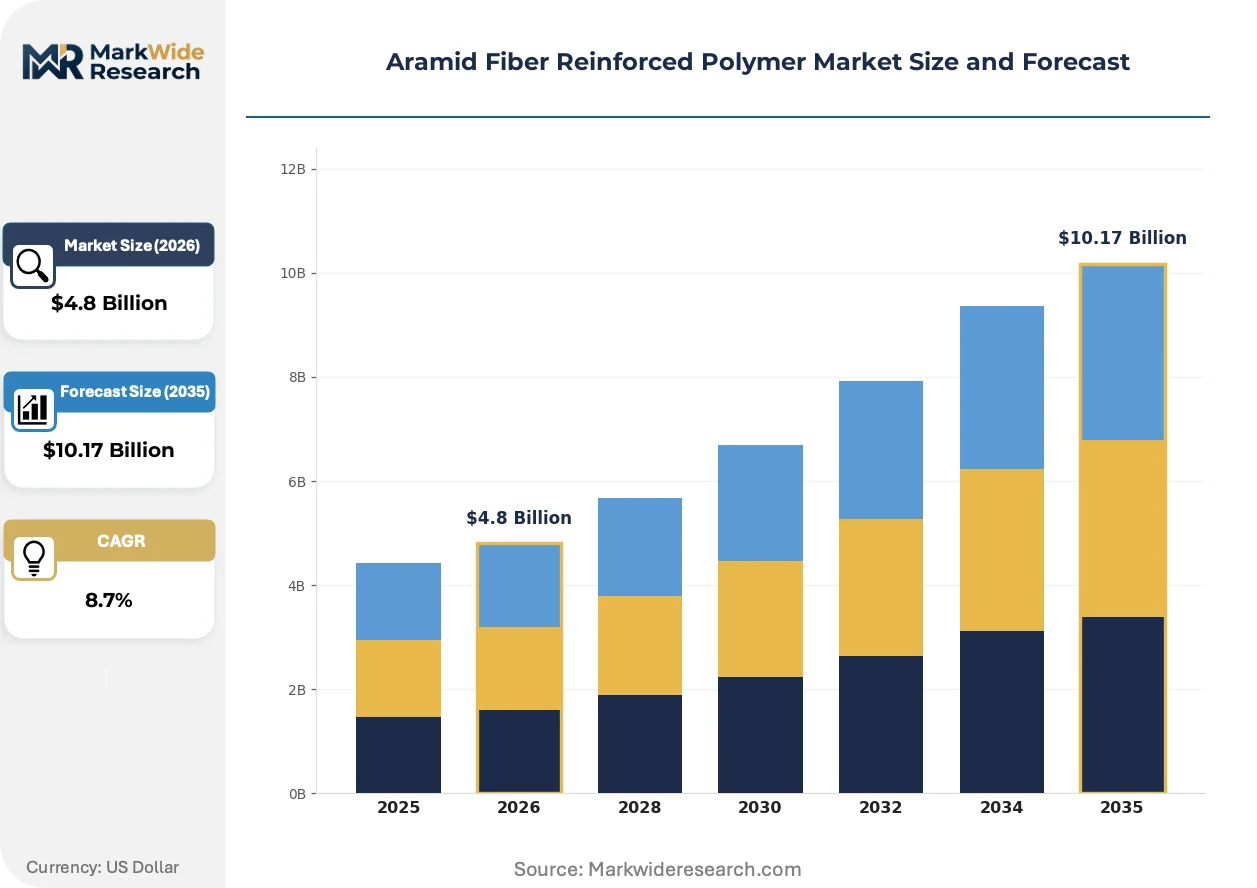
Market Dynamics
Defense procurement agencies in NATO member states are expanding aramid composite orders for personnel protection systems, while the EU Green Deal redirects R&D budgets toward high-performance fiber matrices for lightweighting transportation fleets. This dual demand pull from military and automotive sectors is reorganizing supplier qualification pathways and concentrating production capacity around specialized industrial clusters.
Growth Catalysts
- EU Green Deal lightweighting mandates:Transportation fleet efficiency targets are accelerating aramid composite adoption in automotive structural components, particularly in Germany's supplier corridor around Stuttgart and Munich.
- ISO 14839 ballistic qualification cycles:Updated certification standards for military-grade composites are opening defense tender access to suppliers meeting rigorous performance thresholds.
- Pressure vessel containment applications:Hydrogen storage infrastructure buildout is creating new demand for filament-wound aramid pressure vessels in energy distribution networks.
Market Restraints
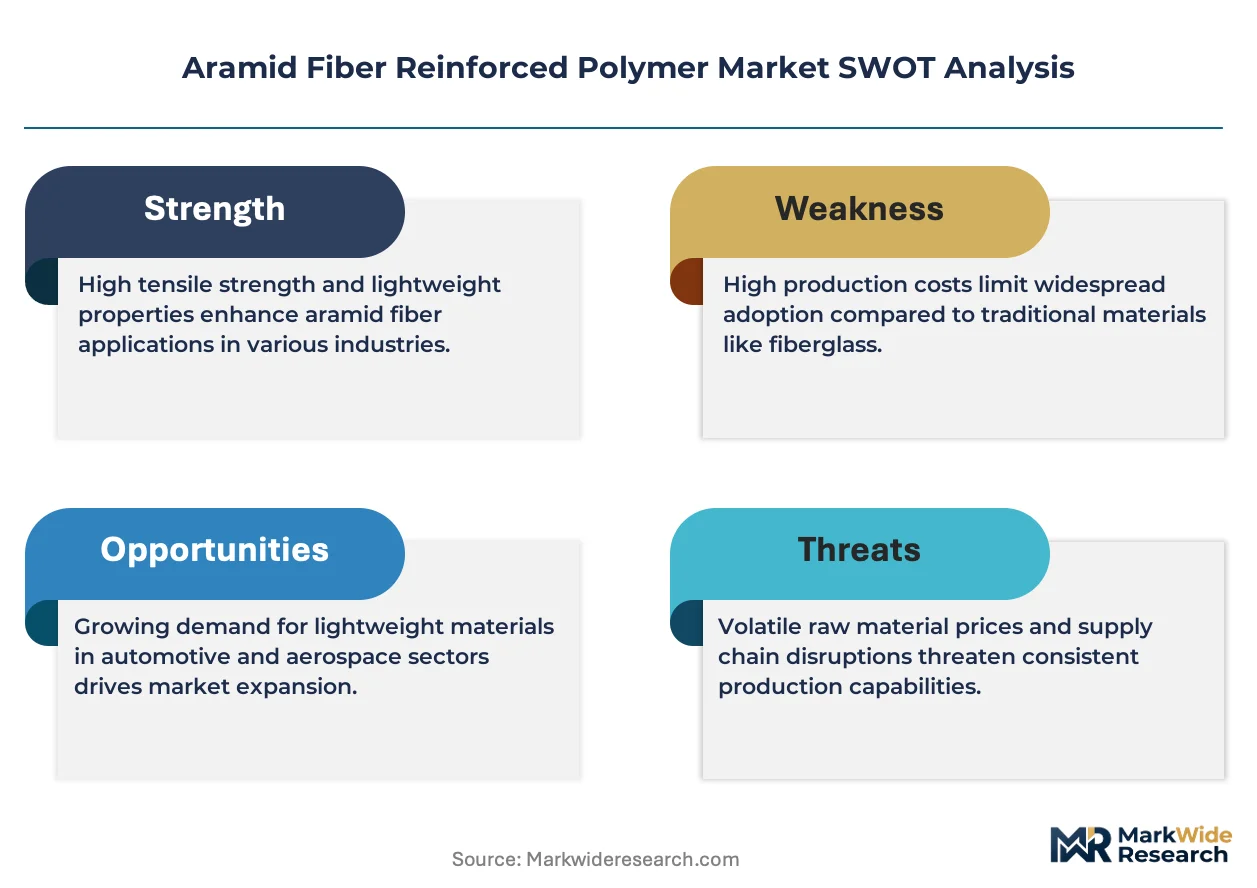
- Para-aramid fiber supply concentration:Production of high-modulus aromatic polyamide fibers remains concentrated among a limited set of integrated spinning operations, creating input bottlenecks for downstream converters.
- ECHA epoxy hardener restrictions:Periodic substance evaluations under EU REACH frameworks are limiting available matrix chemistries for aerospace-qualified laminates.
- Carbon fiber substitution in aerospace:Intermediate-modulus carbon composites are capturing share in secondary structural applications where weight reduction takes priority over impact resistance.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for electric vehicle manufacturing are opening procurement channels for aramid-reinforced body panels in domestic OEM supply chains.
- Recyclable thermoplastic matrices:Hybrid composite systems combining para-aramid with PEEK or PPS matrices address end-of-life regulations while maintaining ballistic performance.
- Digital twin qualification:Virtual testing protocols for laminate performance are compressing FAA airworthiness certification timelines for new aerospace formulations.
Industry Challenges
- Specialized composite technician scarcity:Hand layup and automated fiber placement operations require skilled labor pools that remain underdeveloped outside established aerospace manufacturing regions.
- Dual-use export control navigation:Aramid prepreg shipments face classification uncertainty under evolving military end-use restrictions, complicating cross-border order fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aramid Fiber Reinforced Polymer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite, Sheet, Film, Rod Application: Aerospace, Automotive, Industrial, Military End User: Manufacturers, Contractors, OEMs, Suppliers Distribution Channel: Online Retail, Direct Sales, Distributors, Agents |
| Companies Covered | Toray Industries, Yantai Tayho Advanced Materials, DuPont de Nemours, Huvis Corporation, Kermel S.A., Teijin Limited, Hyosung Corporation, Sinopec Yizheng, Kolon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aramid Fiber Reinforced Polymer Market Evolving Landscape
Material science advances and regulatory recalibration are converging to reshape how aramid composites are formulated, qualified, and procured across defense and industrial applications. Three distinct vectors are redefining competitive positioning in high-performance fiber markets.
Thermoplastic-aramid hybrid prepregs are supplanting traditional epoxy-based systems in military vehicle hull applications where rapid repair and weldability outweigh maximum temperature resistance. Armor system integrators in NATO procurement frameworks are specifying these materials for next-generation personnel carriers. The shift is compressing qualification timelines while expanding the supplier base beyond legacy thermoset specialists.
REACH substance evaluations under ECHA jurisdiction are systematically restricting aromatic amine hardener chemistries previously standard in aerospace matrix formulations. Composite engineers are reformulating with aliphatic alternatives that maintain mechanical properties while satisfying registration requirements. This regulatory pressure disproportionately affects Tier-1 laminate converters serving European commercial aviation programs.
Long-term offtake agreements with fixed-volume pricing are displacing spot-market purchasing for industrial-grade aramid sheet goods. Gasket and insulation manufacturers are consolidating supplier relationships to secure allocation amid fiber production constraints. This behavioral shift is most pronounced in German automotive supplier networks where just-in-sequence delivery requirements demand supply certainty.
Aramid Fiber Reinforced Polymer Market Segmentation
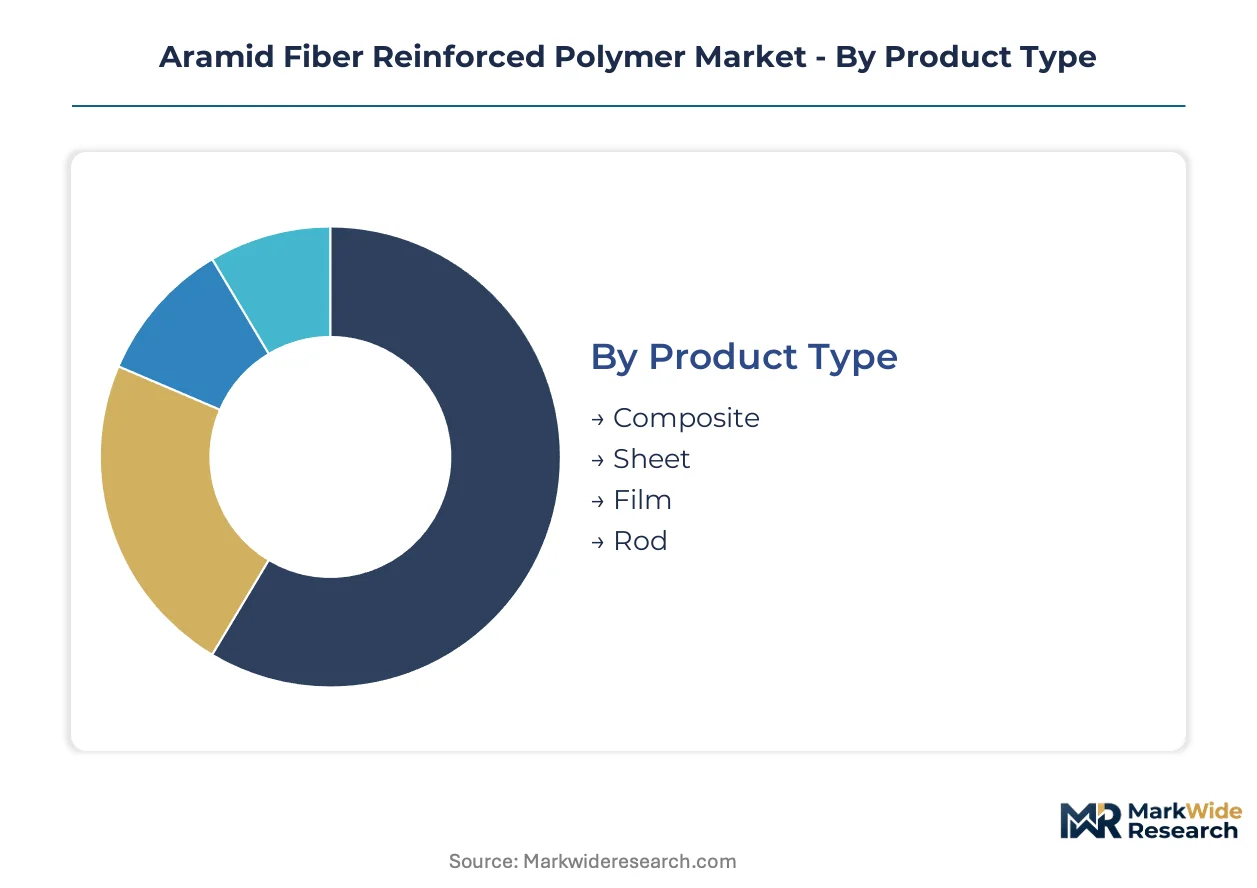
Aramid fiber reinforced polymer markets fragment across performance tiers that map directly to qualification burden and margin structure. Regulatory pathways for aerospace and defense applications impose segmentation logic that commercial segments rarely escape.
Product Type:
FAA airworthiness directives and ISO 14839 ballistic standards partition this category by certification intensity and matrix chemistry flexibility.
- Composite:Thermoset and thermoplastic matrices embedding para-aramid fibers in configurable layups for aerospace skins and military vehicle hulls. Demand concentrates in Germany's automotive supplier corridor around Stuttgart and Munich, where EU Green Deal lightweighting mandates accelerate procurement of structural prepregs.
- Sheet:Industrial-grade aramid laminates serving gasket and insulation markets where processing simplicity outweighs customization needs. German automotive supplier networks favor long-term offtake agreements for these goods to secure allocation amid fiber production constraints.
- Film:Thin-gauge aramid-reinforced barriers for electrical isolation applications in aerospace wiring harnesses.
- Rod:Pultruded tension members for specialist civil engineering and offshore mooring applications.
Composite handles the majority of throughput; Sheet is expanding most quickly on share as industrial buyers consolidate supplier relationships.
Application:
End-use concentration follows defense procurement cycles and transportation fleet efficiency mandates across NATO member states and EU jurisdictions.
- Military:Personnel protection systems and vehicle armor requiring ISO 14839 qualification. NATO defense agencies are expanding aramid composite orders, with procurement concentrated in hull and helmet applications where thermoplastic-aramid hybrids are supplanting epoxy systems.
- Aerospace:Secondary structural components and pressure vessel containment governed by FAA airworthiness directives. ECHA epoxy hardener restrictions under REACH frameworks are forcing reformulation with aliphatic alternatives for European commercial aviation programs.
- Automotive:Structural reinforcement in weight-critical assemblies, particularly electric vehicle body panels where India's PLI scheme incentives are opening domestic procurement channels.
- Industrial:Gasket, insulation, and general reinforcement markets where REACH substance evaluations periodically restrict available matrix chemistries.
Military commands the dominant share of value; Automotive is climbing the fastest as lightweighting mandates propagate through OEM supply chains.
End User:
Customer type determines specification authority and order consolidation patterns across defense and commercial procurement frameworks.
- OEMs:Original equipment manufacturers in aerospace and automotive sectors with direct material qualification authority and long-term offtake contracting power.
- Manufacturers:Tier-1 laminate converters serving European aviation programs, disproportionately affected by ECHA aromatic amine hardener restrictions.
- Suppliers:Material distributors and compounders managing allocation across fragmented industrial demand pools.
- Contractors:Installation and assembly specialists for civil engineering and infrastructure applications with limited specification influence.
OEMs direct the largest volume commitments; Manufacturers are gaining specification authority fastest as qualification timelines compress.
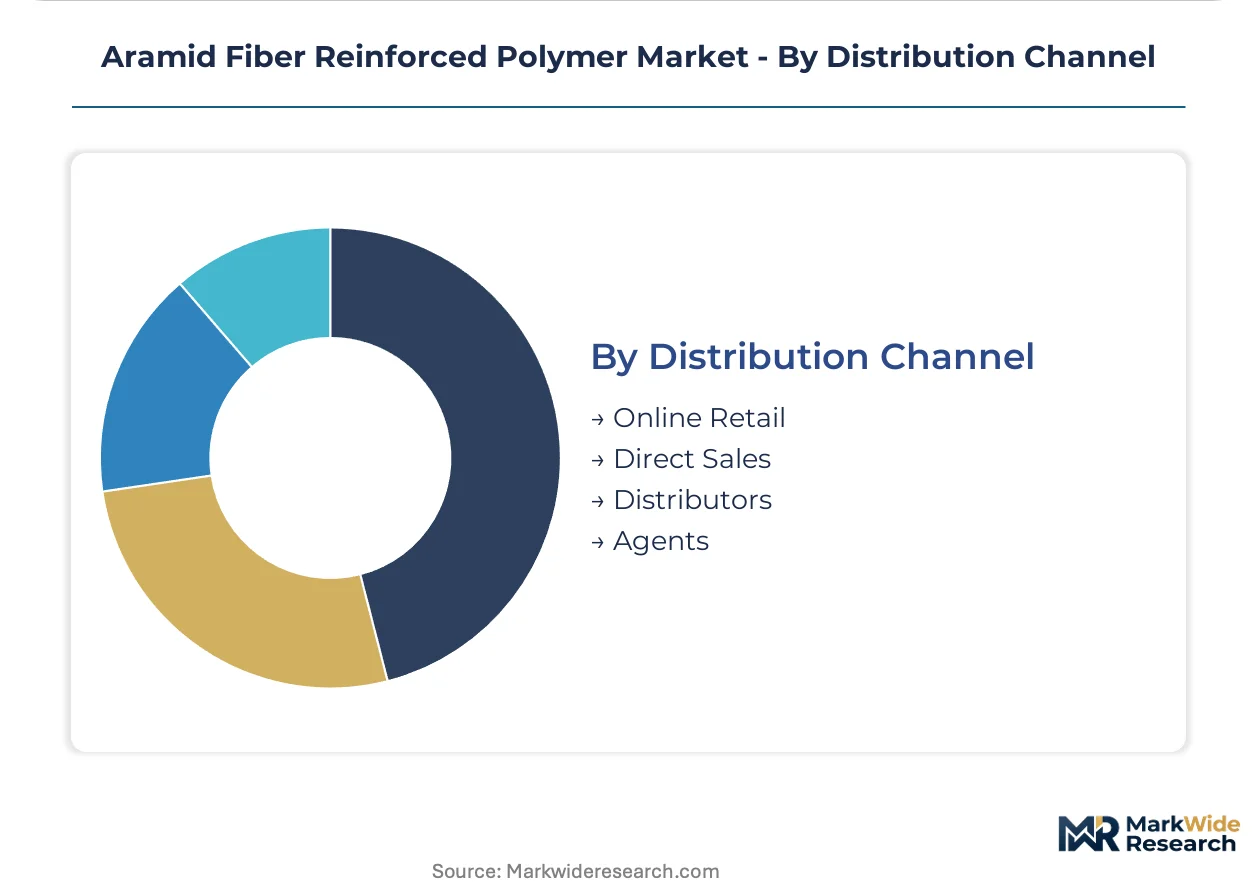
Distribution Channel:
Channel selection tracks order size, technical service requirements, and dual-use export control navigation complexity.
- Direct Sales:Large-volume contracts with OEMs and defense primes requiring technical liaison and qualification support, particularly for shipments facing classification uncertainty under evolving military end-use restrictions.
- Distributors:Regional stockists serving Tier-1 converters and industrial accounts with just-in-sequence delivery requirements in German automotive networks.
- Agents:Representative arrangements for market development in jurisdictions with emerging procurement frameworks like India's PLI scheme territories.
- Online Retail:Catalog sales for standardized industrial-grade sheet goods and small-laboratory quantities.
Direct Sales carries the heaviest transaction values; Distributors are extending reach fastest into newly qualified defense and automotive supply bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal transportation mandates and NATO defense procurement cycles are redistributing aramid composite capacity across three continents. Industrial clusters in Germany, the United States, Japan, India, and China now concentrate divergent supply chain functions from fiber spinning to finished laminate conversion.
United States
FAA airworthiness directives and NHTSA crashworthiness standards sustain demand for aerospace-qualified prepregs and military vehicle armor. Defense procurement through Pentagon acquisition channels prioritizes domestic fiber sources for ballistic protection systems. Industrial activity clusters in Virginia and South Carolina around established aerospace manufacturing corridors.
Germany
EU Green Deal lightweighting mandates for automotive fleets redirect R&D budgets toward structural aramid composites. KBA vehicle certification requirements propagate specification standards through Tier-1 supplier networks. Stuttgart and Munich anchor the supplier corridor where just-in-sequence delivery requirements consolidate long-term offtake agreements.
Japan
METI industrial technology roadmaps support para-aramid fiber development for pressure vessel containment in hydrogen infrastructure. JIS standards govern matrix formulation for domestic aerospace sub-tier suppliers. Nagoya and Osaka metropolitan areas concentrate prepreg conversion capacity serving regional commercial aviation programs.
India
PLI scheme incentives for electric vehicle manufacturing open procurement channels for aramid-reinforced body panels in domestic OEM supply chains. BIS standards for automotive materials create qualification pathways for local laminate converters. Tamil Nadu and Maharashtra industrial zones attract composite fabrication investments from tier suppliers.
China
MIIT dual carbon goals accelerate filament-wound pressure vessel deployment for hydrogen distribution networks. GB standards and SAMR technical regulations shape domestic composite qualification protocols. Yangtze River Delta manufacturing bases integrate para-aramid spinning with downstream prepreg operations.
Aramid Fiber Reinforced Polymer Market Competitive Landscape
Player mix skews toward integrated fiber-to-composite manufacturers and specialized laminate converters. Market structure shows moderate concentration at the fiber spinning tier with fragmentation downstream in prepreg formulation and finished goods fabrication. Two strategic archetypes dominate: heritage chemical conglomerates with captive aramid production, and independent converters competing on qualification speed and matrix customization. Capacity expansion and strategic partnerships represent the primary competitive vectors as qualification timelines compress.
Within the heritage chemical conglomerate tier, DuPont de Nemours and Teijin Limited exemplify integrated operations spanning para-aramid spinning through aerospace-qualified prepreg supply. Yantai Tayho Advanced Materials occupies a position among cost-adjusted performance specialists serving industrial-grade sheet markets where processing simplicity outweighs certification burden. These three entities represent divergent geographic and strategic positioning without implying specific market share claims.
| Leading Market Players |
|---|
| Toray Industries |
| Yantai Tayho Advanced Materials |
| DuPont de Nemours |
| Huvis Corporation |
| Kermel S.A. |
| Teijin Limited |
| Hyosung Corporation |
| Sinopec Yizheng |
| Kolon Industries |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with fixed-volume pricing lock in para-aramid fiber allocation for German automotive Tier-1 suppliers while compressing margin visibility for spot-market buyers in industrial sheet segments. This contract-structure pattern concentrates purchasing power among OEMs with qualification authority while exposing smaller converters to fiber production bottlenecks.
Pricing Analysis
Certification level (ISO 14839-grade) creates the primary spread between aerospace-qualified prepregs and industrial-grade sheet goods. Three-tier pricing structure across ballistic-certified, commercial aviation, and general industrial tiers reflects qualification burden and matrix chemistry flexibility. Cost compression in standard-grade laminates is intensifying because Yantai Tayho Advanced Materials competes on cost-adjusted performance. Automotive OEMs in Stuttgart and Munich demonstrate least price sensitivity due to EU Green Deal lightweighting mandates; gasket manufacturers show highest sensitivity as they consolidate supplier relationships for allocation certainty.
Supply Chain Analysis
Inventory cycles extending 16-20 weeks for para-aramid fiber from Teijin Limited and DuPont de Nemours strain just-in-sequence delivery commitments. Production concentrates in Japan, the United States, and China where integrated spinning operations feed downstream prepreg converters. Raw material dependencies span meta-phenylenediamine, terephthaloyl chloride, and specialty epoxy hardeners facing ECHA REACH restrictions. Single-source vulnerability around high-modulus fiber spinning creates supply chain risk. Distribution runs through direct sales channels for defense primes and specialized distributors serving German automotive networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ISO 14839 and FAA airworthiness directives constructs formidable defensive moats for qualified suppliers. Switching costs for defense primes and commercial aviation OEMs exceed requalification timelines of 18-24 months.
For Market Incumbents: Secure long-term para-aramid fiber offtake agreements with Teijin Limited or DuPont de Nemours to defend against input bottlenecks. Expand thermoplastic-aramid hybrid prepreg capacity in Germany's Stuttgart corridor to capture EU Green Deal procurement. Carbon fiber substitution in aerospace secondary structures threatens aramid share; counter with impact-resistant formulation R&D. For New Entrants and Emerging Players: Digital twin qualification protocols offer fast-track certification pathways for virtual laminate testing. Target India's PLI scheme territories where electric vehicle body panel standards remain unsettled. Pursue recyclable thermoplastic matrix partnerships with PEEK or PPS suppliers to differentiate on end-of-life compliance. For Investors and Strategic Acquirers: Capital is best deployed toward integrated fiber-to-composite manufacturers with captive spinning operations and established defense procurement relationships. Five-to-ten-year viability hinges on qualification speed compression and thermoplastic matrix transition execution. Monitor ECHA substance evaluation announcements for epoxy hardener restriction signals that would trigger reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Matrix Transition | REACH-compliant PEEK-aramid hybrids address ECHA hardener restrictions while enabling rapid military vehicle repair. |
| Digital Twin Qualification | Virtual testing protocols compress FAA airworthiness timelines for new aerospace laminate formulations. |
| India Manufacturing Footprint | PLI scheme incentives attract composite fabrication investments for electric vehicle body panel supply chains. |
| Backward Integration into Fiber Spinning | Captive para-aramid production insulates against Teijin-DuPont supply concentration and input price volatility. |
| Hydrogen Pressure Vessel Partnership | Filament-wound aramid containment systems capture MIIT dual carbon infrastructure buildout in China. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade data, SEC filings, ECHA substance evaluations, and defense procurement disclosures. Interviews with composite R&D directors, Tier-1 laminate converter procurement leads, defense program managers, and aerospace qualification engineers inform demand-side validation. Bottom-up segment sizing triangulates against top-down macroeconomic indicators and energy transition spending frameworks.
Segmentation dimensions modeled include product architecture (composite, sheet, film, rod), application sector (military, aerospace, automotive, industrial), and end-user type (OEM, manufacturer, supplier, contractor). CAGRs derive from regression analysis against defense procurement cycles, EU Green Deal implementation trajectories, and automotive lightweighting mandates. Hydrogen storage infrastructure deployment and thermoplastic matrix adoption curves constitute industry-specific forecast inputs across the analysis window.
Decision-makers should treat outputs as directional under assumptions of sustained NATO defense spending, ECHA regulatory continuity, and EU automotive fleet efficiency targets; material deviation would warrant model refresh. Specific risk factors include dual-use export control reclassification, para-aramid fiber production disruption, and carbon fiber cost parity achievement in aerospace applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
PCR Laminates Market
Composite Materials
FRP Reactor Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Phenolic Panel Market
Composite Materials
Global Composite Materials Market
Composite Materials
FRP Grating Market
Composite Materials
Transportation Composites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Global Composite Resin Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Global Geocomposites Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Polyurethane Composites Market