
 Global FRP Sheets and Panels Market | 2026-2036
Global FRP Sheets and Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global FRP Sheets and Panels Market Analysis
Competitive Landscape and Workforce Dynamics
Skilled laminating technicians is reorganizing output capacity across the Global FRP Sheets and Panels Market as European and North American plants struggle to replace retiring craft workers. Strongwell Corporation sustains its position in structural profiles through in-house pultrusion training programs at its Bristol, Virginia facility. Röchling SE and Co. KG anchors its European supply base with dedicated apprentice pipelines at German and Austrian manufacturing sites. Crane Composites differentiates through specialized gel-coat application expertise that limits competitor replication of its sanitary panel finishes.
Product Architecture and Segment Structure
FRP sheets and panels are fiber-reinforced polymer composites manufactured through pultrusion, compression molding, or hand lay-up, typically incorporating 25-35% glass fiber by weight in a thermoset matrix to achieve specific flexural strength and fire-resistance ratings for structural and decorative applications. Solid sheets command the largest revenue share within product type segmentation due to standardized dimensions and broad applicability across roofing and wall cladding installations. Honeycomb panels represent the fastest-expanding category as aerospace and rail interior specifications demand maximum stiffness-to-weight ratios. Polyester resin dominates material segmentation by volume, though epoxy formulations capture premium margin pools in marine and corrosion-barrier applications where chemical resistance thresholds are most stringent.
Regulatory Environment and Strategic Monitoring
The European Chemicals Agency enforces REACH compliance on styrene emissions from polyester resin production, while the EU Green Deal's embodied-carbon thresholds for construction materials are redirecting public procurement toward lower-carbon envelope solutions. In the United States, OSHA maintains permissible exposure limits for respirable crystalline silica during FRP cutting operations, affecting fabrication shop layouts and on-site installation protocols. Stakeholders must monitor evolving fire-classification harmonization between EN 13501 and ASTM E84 test methods, as divergent certification requirements continue to fragment cross-border product approvals and complicate unified manufacturing runs.
Market Dynamics
EU Green Deal embodied-carbon thresholds are redirecting public procurement toward fiber-reinforced polymer envelope solutions, compressing specification timelines for construction material suppliers across Germany, France, and the Netherlands.
Growth Catalysts
- Corrosion-resistant specification pull:Chemical processing and marine infrastructure operators in coastal China and the US Gulf Coast are specifying FRP over carbon steel for tank linings and decking systems.
- REACH compliance differentiation:Styrene emission controls enforced by the European Chemicals Agency are advantaging producers with closed-molding capabilities over open-mold competitors in polyester resin segments.
- Lightweighting mandates in rail interiors:Honeycomb FRP panel specifications for passenger compartment sidewalls and ceilings are expanding across Deutsche Bahn and SNCF rolling stock refurbishment programs.
Market Restraints
- Glass fiber supply concentration:E-glass roving production clusters in China and Egypt create input vulnerability for European and North American pultrusion operations during freight rate volatility.
- Epoxy resin cost structure:Bisphenol-A and amine hardener price swings compress margin stability for marine and chemical barrier applications against lower-cost polyester alternatives.
- Fire-classification fragmentation:Divergent EN 13501 and ASTM E84 test protocols force dual certification runs, extending product approval cycles for cross-border construction envelope projects.
Strategic Opportunities
- Modular construction penetration:Offsite manufacturing of bathroom pods and cleanroom modules in the UK and Scandinavia creates specification channels for gel-coated sanitary panels with integrated antimicrobial surfaces.
- EU F-Gas Regulation displacement:Refrigerated transport trailer manufacturers in Poland and Spain are substituting insulated FRP sandwich panels for polyurethane foam systems facing HFC phase-down constraints.
- Digital twin integration:Convergence of pultrusion process sensors with predictive maintenance software enables outcome-based panel performance warranties for wind turbine nacelle OEMs.
Industry Challenges
- Laminating technician attrition:Hand lay-up and spray-up craft knowledge is contracting as veteran workers retire without sufficient apprentice pipeline replacement in Bristol, Virginia and Mannheim production clusters.
- Capex intensity for fire-testing infrastructure:Single-burner and multi-burner test apparatus for achieving Class A surface burning ratings requires seven-figure facility investment, disadvantaging mid-scale panel fabricators.
Report Scope
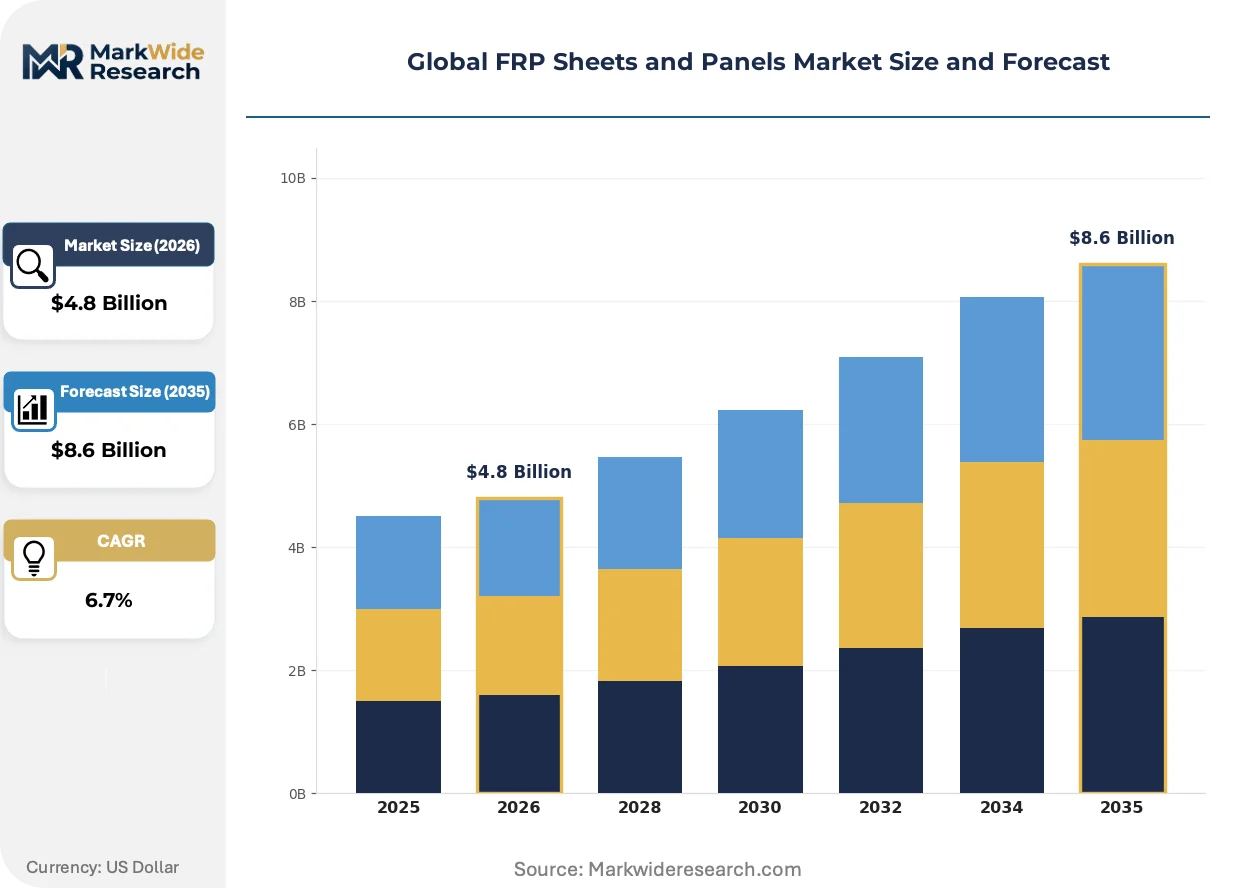
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global FRP Sheets and Panels Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Sheets, Honeycomb Panels, Laminated Panels, Rollable Sheets End User: Construction, Automotive, Aerospace, Marine Material: Polyester, Vinylester, Epoxy, Thermoplastic Application: Roofing, Wall Cladding, Flooring, Insulation |
| Companies Covered | US Liner Company, Polser Fiberglass Reinforced Plastics, Panolam Industries International, Strongwell Corporation, Röchling SE and Co. KG, Crane Composites, Brianza Plastica Spa, Optiplan GmbH, LAMILUX Heinrich Strunz Holding GmbH and Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global FRP Sheets and Panels Market Emerging Trajectories
Thermoset matrix formulation and automated fiber placement are compressing production cycle times while regulatory fire-performance thresholds harden, creating divergent technology adoption curves across end-use verticals.
Continuous basalt fiber reinforcement is bifurcating the structural panel segment. Rail interior manufacturers in Germany and Japan are specifying basalt-FRP sidewalls for superior smoke toxicity performance under EN 45545-2. The material is enabling premium pricing tiers against E-glass alternatives while compressing commodity polyester sheet margins in non-fire-critical applications.
The EU Green Deal's embodied-carbon disclosure requirements for construction products are tightening material passport documentation. Public procurement frameworks in France and the Netherlands now mandate Environmental Product Declarations for facade cladding above threshold contract values. German FRP producers with verified life-cycle assessments are securing preferred supplier status in municipal building tenders.
Specification authority is migrating from general contractors to facade engineering consultants with computational thermal bridging expertise. Building envelope performance guarantees in Nordic markets now bundle FRP panel supply with installation quality bonds. This shift is visible most acutely in Copenhagen and Stockholm commercial retrofit projects where energy efficiency certificates drive material selection.
Global FRP Sheets and Panels Market Segmentation
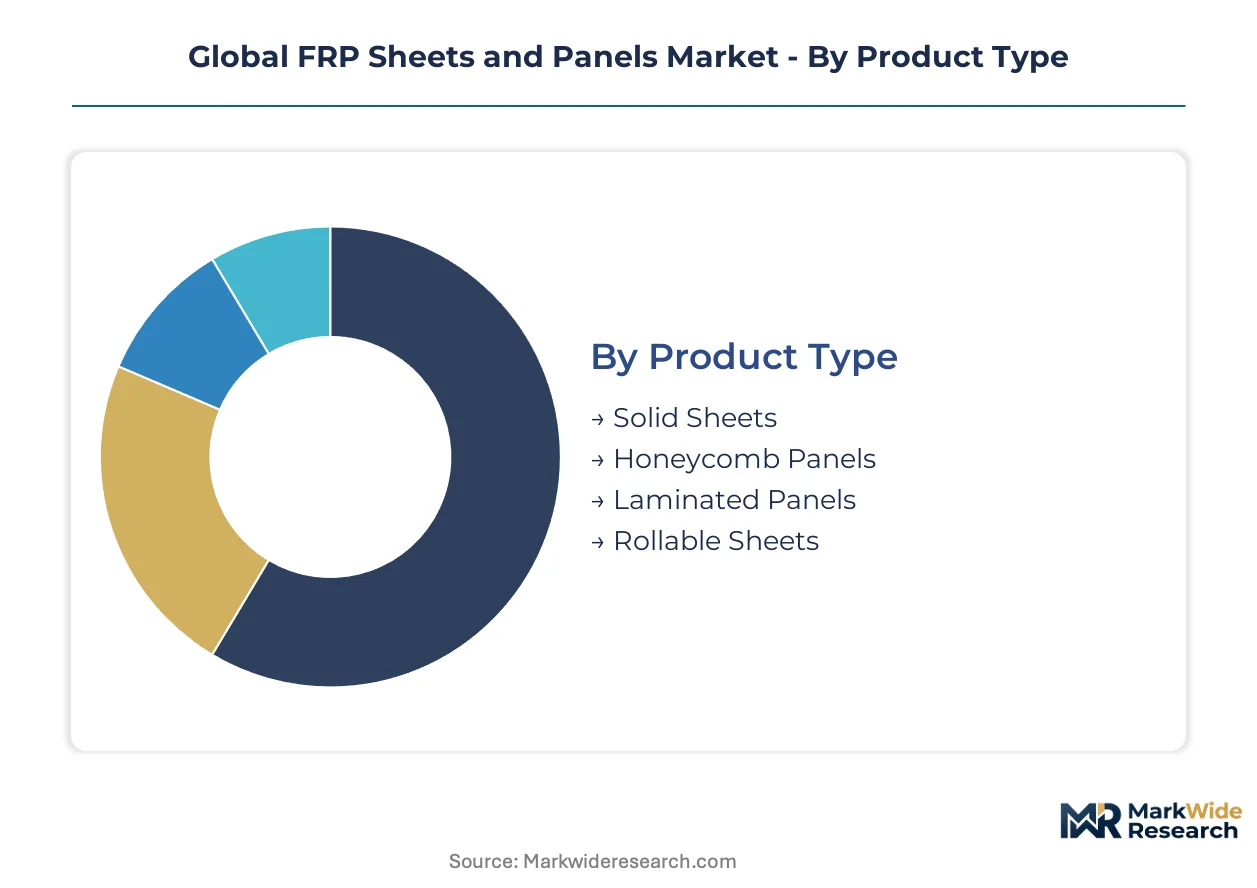
FRP sheet and panel specifications diverge sharply across load-bearing, aesthetic, and thermal performance requirements. Procurement patterns in this market track end-use certification complexity rather than commodity pricing, making segment-level technical differentiation the primary competitive variable.
Product Type:
Domestic consumption dominates solid sheet and laminated panel demand across German and US construction clusters, while honeycomb and rollable formats serve export-heavy aerospace and portable shelter supply chains.
- Solid Sheets:These incorporate 25-35% E-glass fiber by weight in thermoset matrices, delivering standardized flexural strength for roofing and wall cladding installations. German municipal building tenders specify solid sheets for corrosion-resistant envelope systems under EU Green Deal embodied-carbon thresholds. This segment holds the largest share; momentum sits with honeycomb configurations.
- Honeycomb Panels:Aluminum or aramid honeycomb cores bonded to FRP skins achieve maximum stiffness-to-weight ratios for rail interior and aerospace applications. Deutsche Bahn and SNCF rolling stock refurbishment programs are expanding specifications for passenger compartment sidewalls and ceilings. Honeycomb panels are climbing the fastest among product types.
- Laminated Panels:Multi-layer constructions with gel-coat surfaces serve sanitary and cleanroom modules in UK offsite manufacturing facilities.
- Rollable Sheets:Flexible FRP formulations enable curved architectural surfaces and temporary shelter systems for disaster relief logistics.
Solid sheets command procurement volume through construction standardization; honeycomb configurations drive technology investment.
End User:
Cost tiers separate these segments: construction and automotive operate on volume-scale polyester formulations, while aerospace and marine absorb premium epoxy and vinylester pricing for certification-critical applications.
- Construction:Lightweight cladding systems for commercial roofing and facade retrofit projects dominate procurement volumes. Builders in France and the Netherlands specify FRP over steel and aluminum for corrosion resistance and embodied-carbon compliance under tightening public procurement frameworks. Construction absorbs the highest volume; aerospace commands the steepest expansion trajectory.
- Automotive:Structural profiles and interior panels serve commercial vehicle and refrigerated transport trailer manufacturers. Polish and Spanish OEMs are substituting insulated FRP sandwich panels for polyurethane foam systems facing EU F-Gas Regulation HFC phase-down constraints.
- Aerospace:Fire-rated honeycomb panels for aircraft interiors require EN 45545-2 and FAR 25.853 certification, concentrating demand with qualified laminating technicians.
- Marine:Chemical-resistant tank linings and decking systems specify vinylester and epoxy matrices for coastal infrastructure operators in the US Gulf Coast and China.
Construction anchors volume demand; aerospace specifications are expanding most quickly on regulatory fire-performance mandates.
Material:
Volume concentration sits with polyester across domestic construction supply chains, while epoxy and vinylester serve specialized export markets requiring chemical resistance certification.
- Polyester:Orthophthalic and isophthalic formulations dominate by volume for roofing and wall cladding applications. REACH compliance on styrene emissions advantages producers with closed-molding capabilities over open-mold competitors in European supply bases. Polyester holds the largest share; thermoplastic resins are gaining share fastest.
- Vinylester:Superior chemical resistance specifies this material for marine tank linings and chemical processing infrastructure. US Gulf Coast operators specify vinylester over carbon steel for corrosion barriers.
- Epoxy:Bisphenol-A and amine hardener systems capture premium margins in aerospace and wind turbine nacelle applications where structural performance thresholds are most stringent. Price volatility in raw inputs compresses margin stability against polyester alternatives.
- Thermoplastic:Recyclable matrices enable circular economy specifications and automated processing speeds for high-volume automotive components.
Polyester dominates procurement economics; thermoplastic adoption is accelerating on sustainability and processing efficiency drivers.
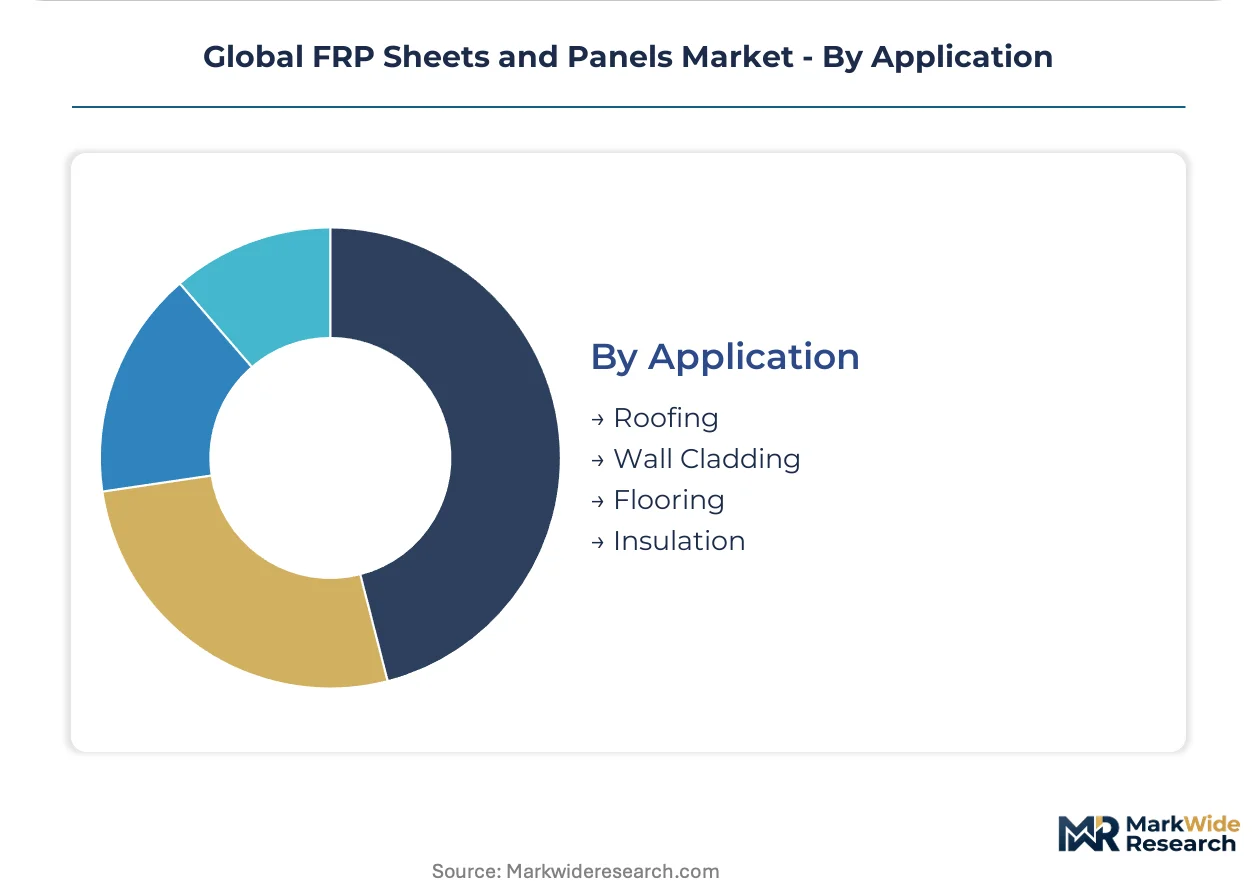
Application:
Customer type bifurcation separates specification authority: roofing and wall cladding decisions flow through facade engineering consultants, while flooring and insulation procurement concentrates with general contractors and modular manufacturers.
- Roofing:Corrugated and flat sheet configurations serve industrial and commercial building envelopes. Copenhagen and Stockholm retrofit projects bundle FRP panel supply with installation quality bonds tied to energy efficiency certificates. Roofing commands the largest application share; insulation is expanding most quickly.
- Wall Cladding:Aesthetic and functional facade systems require fire-classification harmonization between EN 13501 and ASTM E84 protocols. German producers with verified life-cycle assessments secure preferred supplier status in municipal tenders.
- Flooring:Anti-slip grating and plate systems serve chemical processing and marine decking applications where load-bearing and corrosion resistance converge.
- Insulation:Refrigerated transport trailer manufacturers in Poland and Spain specify insulated FRP sandwich panels as polyurethane foam substitutes under EU F-Gas Regulation constraints.
Roofing absorbs the highest specification volume; insulation applications are climbing fastest on regulatory displacement effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Austria commands premium positioning against volume-driven competition from Chinese pultrusion clusters. European embodied-carbon regulations compress specification timelines for domestic suppliers. Freight rate volatility on E-glass roving imports from Egypt and China destabilizes margin structures for North American fabricators.
United States
Chemical processing infrastructure along the Gulf Coast specifies FRP tank linings over carbon steel for corrosion resistance. OSHA permissible exposure limits for respirable crystalline silica reshape fabrication shop layouts and on-site installation protocols. Bristol, Virginia anchors pultrusion training programs that sustain structural profile output capacity.
Germany
Deutsche Bahn rolling stock refurbishment expands honeycomb panel specifications for passenger compartment sidewalls. EU Green Deal embodied-carbon thresholds redirect municipal building tenders toward verified life-cycle assessment holders. Mannheim and Bavaria production clusters face laminating technician attrition as veteran craft workers retire.
China
Coastal marine infrastructure operators specify FRP decking systems for saltwater corrosion barriers. National dual carbon goals tighten material passport documentation requirements for construction exports. Yangtze River Delta pultrusion operations concentrate E-glass roving consumption for domestic roofing and cladding supply chains.
France
Public procurement frameworks mandate Environmental Product Declarations for facade cladding above threshold contract values. SNCF rail interior specifications drive fire-rated panel demand under EN 45545-2 protocols. Paris-region facade engineering consultants displace general contractors as specification authority for commercial retrofit projects.
Poland
Refrigerated transport trailer manufacturers substitute insulated FRP sandwich panels for polyurethane foam systems facing EU F-Gas Regulation HFC phase-down constraints. Automotive component suppliers absorb volume-scale polyester formulations for commercial vehicle applications. Warsaw and Silesian manufacturing zones cluster modular construction supply for Scandinavian export markets.
Global FRP Sheets and Panels Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the FRP sheets and panels market. European specialists dominate fire-performance certification and gel-coat application expertise while Asian fabricators capture standardized construction volume through pultrusion scale. Three archetypes define competitive positioning: integrated resin-to-panel manufacturers, specialist laminators with certified technician pipelines, and modular system integrators bundling supply with installation bonds. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure glass fiber supply agreements and cross-border certification harmonization.
Among German-based integrated manufacturers, Röchling SE and Co. KG and LAMILUX Heinrich Strunz Holding GmbH and Co. KG exemplify the resin-to-finished-panel archetype with captive supply chain control. Strongwell Corporation represents the specialist laminator model with dedicated workforce development infrastructure. These three occupy positions across the premium and volume tiers without overlapping segment concentration.
| Leading Market Players |
|---|
| US Liner Company |
| Polser Fiberglass Reinforced Plastics |
| Panolam Industries International |
| Strongwell Corporation |
| Röchling SE and Co. KG |
| Crane Composites |
| Brianza Plastica Spa |
| Optiplan GmbH |
| LAMILUX Heinrich Strunz Holding GmbH and Co. KG |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied-carbon thresholds and REACH styrene emission controls gate supplier qualification and price differentiation simultaneously, advantaging closed-molding European producers over open-mold competitors while compressing margin pools for uncertified imports. Certification-holding manufacturers in Germany and Austria command premium positioning against volume-driven Chinese pultrusion clusters, with fire-classification dual-runs fragmenting pricing coherence across cross-border construction projects.
Pricing Analysis
German and Austrian producers capture 40-60% premiums over Chinese pultrusion exports for equivalent E-glass formulations, with EN 13501-1 Class A surface burning ratings and verified Environmental Product Declarations driving price stratification across premium-certified, standard-compliant, and economy-uncertified tiers. Cost compression in commodity polyester sheets intensifies as Yangtze River Delta capacity expansion feeds spot-market oversupply. Construction procurement teams in France and the Netherlands show highest price sensitivity for standardized roofing dimensions, while Deutsche Bahn and aerospace OEMs absorb premium epoxy honeycomb pricing for EN 45545-2 fire performance.
Supply Chain Analysis
E-glass roving production concentration in China and Egypt creates chokepoint vulnerability for European and North American pultrusion operations when Red Sea freight volatility disrupts Egyptian supply routes. German laminators draw from captive styrene and orthophthalic resin streams, while marine-grade vinylester formulations hinge on bisphenol-A and amine hardener imports from Belgian and Dutch chemical clusters. Single-source dependency on Chinese E-glass roving exposes margin instability during tariff escalation or port congestion episodes. Distribution runs through facade engineering consultants in Nordic retrofit markets and direct OEM supply agreements for rail and automotive tier-1 integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation quality bonds and predictive maintenance software subscriptions for pultrusion process monitoring are expanding faster than base panel hardware, creating service-attach revenue streams that recalibrate customer lifetime value calculations across construction and wind turbine OEM accounts.
For Market Incumbents: Consolidate laminating technician pipelines through dedicated apprentice programs at Mannheim and Bristol production clusters before demographic attrition erodes craft knowledge transfer. Lock in multi-year E-glass roving offtake agreements with Egyptian suppliers to hedge freight rate volatility. Prioritize closed-molding capacity additions that satisfy REACH styrene thresholds and sustain premium positioning against open-mold Asian imports. For New Entrants and Emerging Players: EN 45545-2 fire certification fast-tracks market access for rail interior honeycomb specifications where incumbent capacity constraints delay Deutsche Bahn and SNCF procurement timelines. Target Polish refrigerated transport trailer manufacturers facing EU F-Gas Regulation HFC phase-down deadlines with insulated FRP sandwich panel substitutes for polyurethane foam systems. Pursue modular construction partnerships in UK offsite manufacturing clusters where gel-coated sanitary panel demand outpaces qualified laminator supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fire-testing infrastructure as Class A surface burning certification requires seven-figure single-burner and multi-burner apparatus investments that screen out mid-scale fabricators. Acquire specialist laminators with verified life-cycle assessments and established municipal tender relationships in Germany and the Netherlands. Monitor EN 13501-1 and ASTM E84 harmonization negotiations as the signal for cross-border product approval simplification and unified manufacturing run economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into E-Glass Roving Supply | Captive Egyptian roving production insulates German pultruders from Red Sea freight volatility. |
| Closed-Molding Capacity Expansion | REACH-compliant styrene containment sustains premium positioning against open-mold Chinese competitors. |
| Fire-Testing Infrastructure Investment | Class A certification apparatus secures specification access for Deutsche Bahn and aerospace OEMs. |
| Installation Quality Bond Bundling | Copenhagen and Stockholm facade projects now require performance guarantees tied to energy certificates. |
| Predictive Maintenance Software Integration | Process sensor convergence enables outcome-based warranties for wind turbine nacelle manufacturers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA REACH registration databases, SEC 10-K filings, and national construction tender portals. Interviews with pultrusion plant managers, facade engineering consultants, rail OEM procurement leads, and laminating technician training coordinators informed demand-side validation. Bottom-up volume builds across product type, end user, material, and application segments triangulate against top-down macroeconomic indicators and construction output indices.
Segmentation dimensions modeled span product architecture (solid sheets, honeycomb panels, laminated panels, rollable formats), end-use vertical (construction, automotive, aerospace, marine), resin matrix (polyester, vinylester, epoxy, thermoplastic), and application function (roofing, wall cladding, flooring, insulation). CAGRs derive from historical trajectory analysis, regulatory mandate timing, and substitution elasticity estimates for steel and aluminum envelope systems. Wind turbine nacelle OEM demand curves and EU F-Gas Regulation phase-down schedules constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement, stable E-glass roving trade flows, and gradual EN 13501-1 and ASTM E84 harmonization; material deviation in regulatory stringency or raw material access would warrant model refresh. Practitioners should keep alternative scenarios live as REACH amendment timelines and Red Sea logistics conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Structural Composites Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Isostatic Graphite Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Graphite Felt Market
Composite Materials
Core Material for Composites Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Composite Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market