
 Global Composites Cylinder Market | 2026-2036
Global Composites Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Composites Cylinder Market Analysis
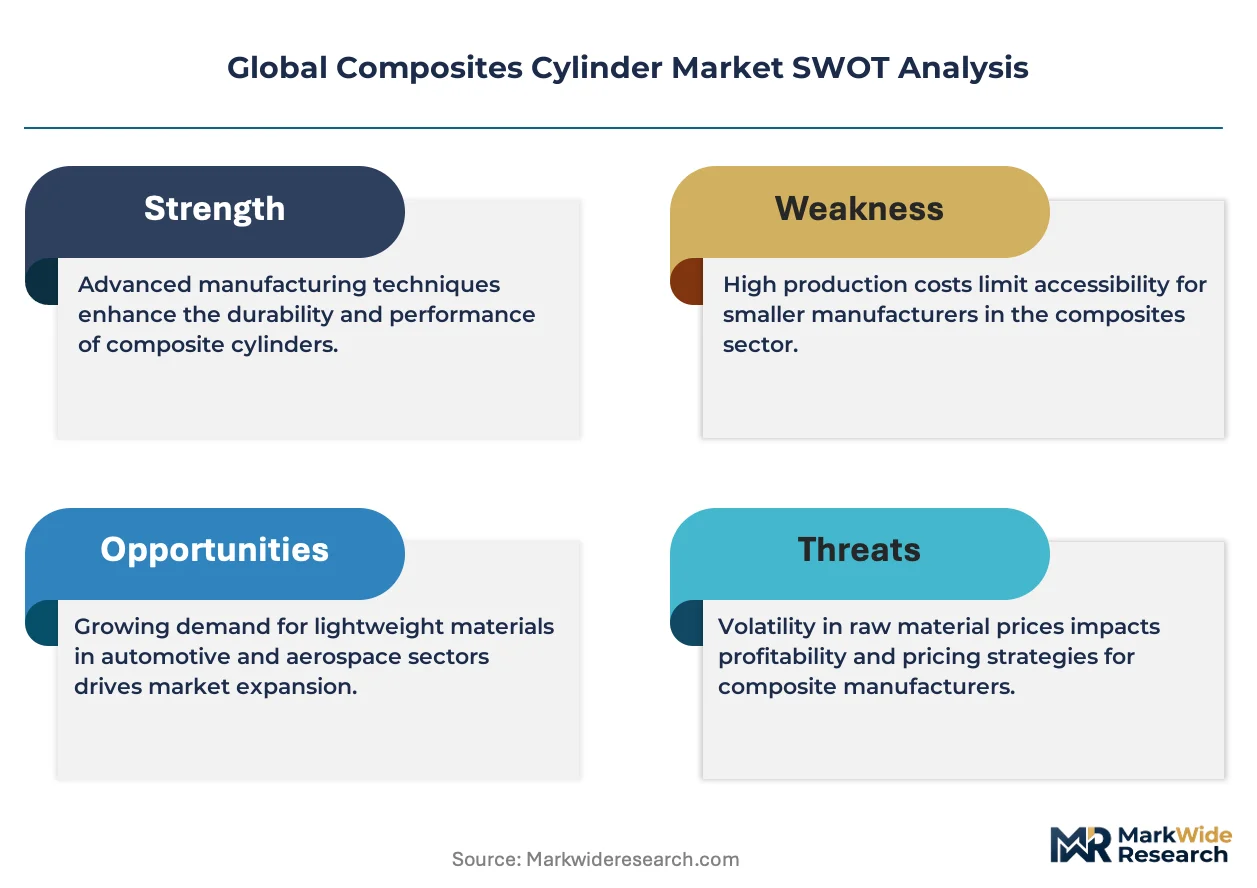
Project finance for hydrogen refueling infrastructure is fragmenting the competitive landscape for high-pressure composite cylinders. Hexagon Composites leverages its integrated filament winding capacity to anchor Nordic and North American hydrogen mobility supply chains. Luxfer Gas Cylinders sustains aerospace and medical oxygen positions through proprietary liner-to-composite bonding expertise. Faber Industrie competes on European industrial gas cylinder replacement cycles with ISO-certified Type III designs.
Composites cylinders are filament-wound or resin-transfer-molded pressure containment vessels combining thermoset polymer matrices with carbon, glass, or aramid fiber reinforcement, engineered to store compressed gases at operating pressures from 200 to 700 bar. Their primary purpose centers on weight-critical gas storage across mobility, industrial process, and energy distribution applications. Carbon fiber pressure vessels command premium positioning due to hydrogen-specific fatigue performance requirements, while glass fiber storage tanks dominate mature industrial air and nitrogen segments where weight sensitivity remains moderate. Filament winding manufacturing stages capture the deepest margin pools as tow-placement automation and in-situ monitoring reduce scrap rates in aerospace-qualified production.
FDA, EPA, and DOT regulations in the United States govern medical oxygen and compressed natural gas cylinder certification, with DOT-SP and ISO 11119-2 harmonization shaping export eligibility for North American manufacturers. Europe's ECHA REACH compliance and CE marking under the Pressure Equipment Directive determine market access for imported composite pressure vessels. Stakeholders must monitor evolving hydrogen-specific standards from ISO TC 197 and national fire codes as Type IV cylinder deployment scales beyond demonstration projects into commercial freight and maritime bunkering.
Market Dynamics
Filament winding automation is concentrating manufacturing margin in aerospace-qualified production lines, while South Korean hydrogen mobility programs and EU F-Gas phase-downs create divergent demand pulls across mobility and industrial gas replacement cycles.
Growth Catalysts
- EU F-Gas Regulation phase-down:Industrial operators in Germany's Ruhr cluster accelerate steel-to-composite pressure equipment replacement to meet containment compliance deadlines.
- Hydrogen mobility fleet programs:South Korean government-backed deployment of heavy-duty fuel cell vehicles pulls Type IV cylinder volumes into commercial vehicle supply chains.
- Carbon fiber fatigue performance:Hydrogen-specific cycling requirements elevate aerospace-grade tow placement and in-situ monitoring adoption in pressure vessel manufacturing.
Market Restraints
- Carbon fiber supply concentration:Aerospace-qualified fiber tows from limited Japanese and US suppliers create input cost volatility for 700-bar hydrogen cylinder producers.
- DOT-SP certification harmonization delays:Divergent US Department of Transportation special permits and ISO 11119-2 testing protocols extend export qualification timelines for North American manufacturers.
- Steel cylinder residual stock:Extended service life of legacy Type I industrial gas equipment in mature nitrogen and air segments defers composite replacement cycles.
Strategic Opportunities
- Maritime hydrogen bunkering:Port authorities in Rotterdam and Singapore evaluate Type IV cylinder arrays for shore-to-ship fueling infrastructure without cryogenic liquefaction.
- Medical oxygen homecare expansion:Lightweight composite cylinders penetrate ambulatory patient segments where aluminum weight limits mobility.
- ISO TC 197 hydrogen standards finalization:Anticipated harmonization of global cylinder testing protocols reduces multi-jurisdiction certification duplication for manufacturers.
Industry Challenges
- Filament winding technician scarcity:Aerospace-qualified tow placement operators command premium wages as automated winding cell deployment outpaces vocational training pipeline output.
- Multi-standard certification stacking:Cylinder producers face simultaneous DOT-SP, CE marking under Pressure Equipment Directive, and emerging national fire code compliance for hydrogen freight applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Composites Cylinder Market |
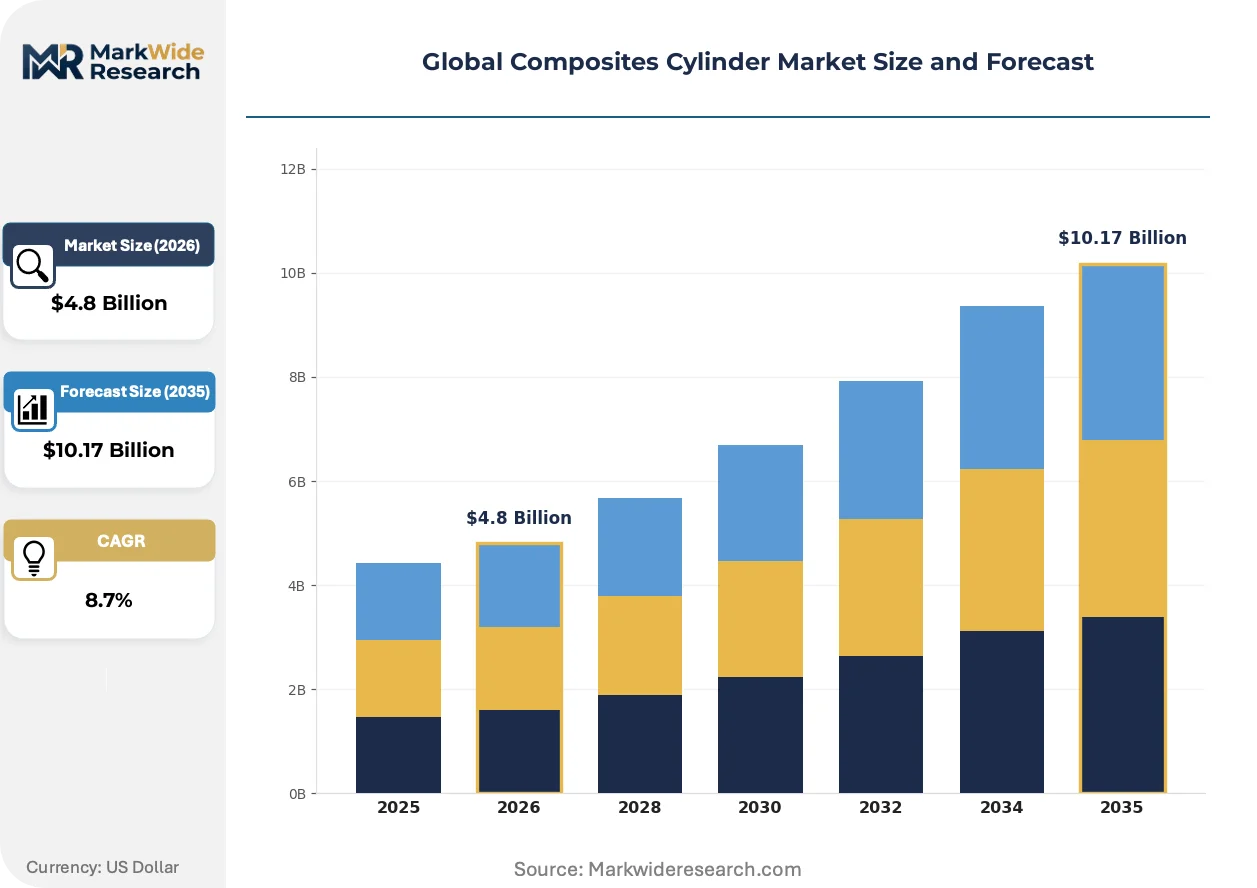
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Vessels, Storage Tanks, Pipes, Automotive Cylinders End User: Aerospace, Automotive, Industrial, Oil & Gas Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Others Manufacturing Stage: Pultrusion, Filament Winding, Resin Transfer Molding, Compression Molding |
| Companies Covered | Hexagon Composites, Luxfer Gas Cylinders, Faber Industrie, NPROXX, Amtrol-Alfa, Worthington Industries, Time Technoplast, Drägerwerk AG & Co. KGaA, EVAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Composites Cylinder Market Emerging Trajectories
Digital thread integration across filament winding cells is compressing scrap rates and traceability gaps, while regulatory fragmentation between hydrogen mobility and industrial gas codes forces parallel certification investments.
In-situ thermographic monitoring during automated tow placement is digitizing quality assurance in carbon fiber pressure vessel production. Aerospace cylinder manufacturers deploy real-time temperature and tension feedback loops to catch void formation before cure cycles. This capability is digitizing margin capture previously lost to post-cure non-destructive testing rework.
Europe's F-Gas Regulation phase-down redirects industrial refrigerant and process gas containment toward composite alternatives with lower permeation rates. Chemical operators in Germany and the Netherlands face replacement deadlines for steel equipment that cannot meet revised leakage thresholds. The regulation pressures cylinder distributors to maintain dual steel and composite inventories during transition periods.
Freight operators in South Korea and California now specify total-cost-of-ownership procurement models that weight cylinder weight against fuel consumption over vehicle life. Fleet managers compare aluminum, steel, and composite storage options using hydrogen payload efficiency metrics rather than unit acquisition cost. This evaluation framework favors Type IV carbon fiber cylinders in long-haul heavy-duty segments where weight directly determines range.
Global Composites Cylinder Market Segmentation
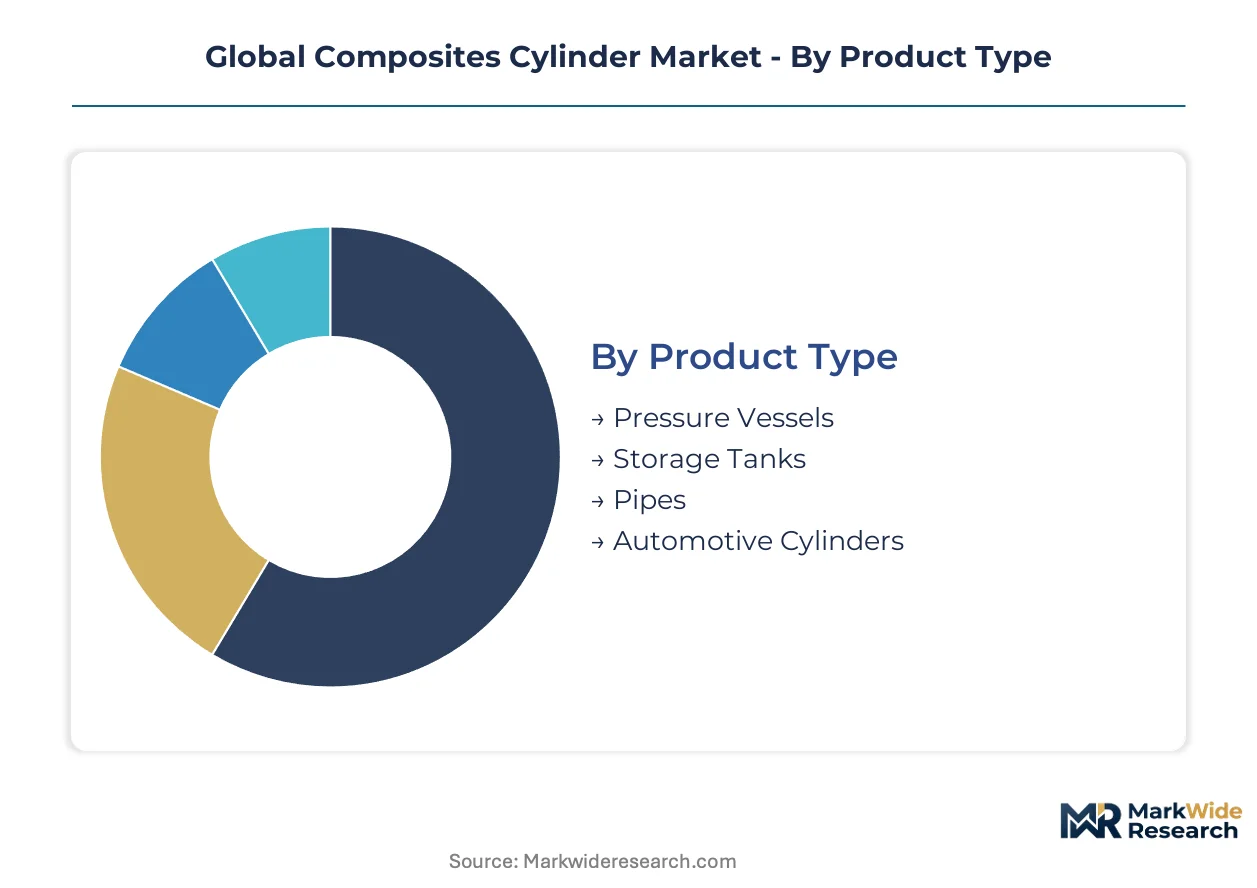
Segmentation in composites cylinders reveals divergent margin profiles across manufacturing stages and material grades. Service intensity varies sharply between aerospace-qualified pressure vessels and industrial storage tanks. Procurement patterns in hydrogen mobility differ fundamentally from replacement cycles in process gas containment.
Product Type:
After-sales service intensity escalates with operating pressure ratings and inspection frequency mandates. Pressure vessels demand recertification protocols that generate recurring revenue streams for qualified service providers.
- Pressure Vessels:High-pressure containment systems rated to 700 bar for hydrogen and compressed natural gas storage. South Korean fuel cell bus fleets specify Type IV filament-wound designs to maximize payload efficiency in heavy-duty routes. Aerospace-qualified production lines capture premium pricing through DOT-SP and ISO 11119-2 dual certification.
- Storage Tanks:Large-diameter filament-wound or resin-transfer-molded vessels for stationary industrial gas containment. Germany's Ruhr chemical cluster accelerates steel-to-composite replacement to meet EU F-Gas Regulation leakage thresholds. Stationary applications tolerate glass fiber reinforcement where weight sensitivity remains secondary to permeation resistance.
- Pipes:Filament-wound or pultruded composite piping for corrosive process fluid transport. Offshore oil platforms specify GRE (glass-reinforced epoxy) lines for seawater injection and crude oil gathering.
- Automotive Cylinders:Compact Type III and Type IV designs for passenger vehicle and light truck fuel storage. California fleet operators evaluate total-cost-of-ownership models that weight cylinder mass against hydrogen consumption over vehicle life.
Pressure vessels hold the largest share; momentum sits with automotive cylinders.
End User:
Application-specific certification requirements fragment procurement across end-use segments. Aerospace and medical oxygen demand traceable production records that industrial gas distributors rarely maintain.
- Aerospace:Cabin oxygen and emergency evacuation systems requiring FAA-compliant filament winding with full digital thread documentation. Real-time thermographic monitoring during tow placement eliminates post-cure rework in qualified production cells.
- Automotive:Hydrogen fuel cell and compressed natural gas vehicle storage with weight-driven specification trends. South Korean government-backed fleet programs pull Type IV carbon fiber volumes into commercial vehicle supply chains.
- Industrial:Process gas containment, refrigerant recovery, and welding gas distribution. EU F-Gas phase-down deadlines force German and Dutch chemical operators toward composite alternatives with lower permeation rates than legacy steel equipment.
- Oil & Gas:Downhole applications and offshore platform gas storage where corrosion resistance outweighs weight considerations. Glass-reinforced designs dominate mature nitrogen and air service segments.
Industrial applications anchor volume; automotive is climbing the fastest.
Material:
Raw material selection determines fatigue performance, permeation resistance, and ultimate cost structure. Fiber grade qualification timelines separate aerospace-certified supply chains from industrial commodity streams.
- Carbon Fiber:Aerospace-grade tow placement delivers hydrogen-specific cycling performance for 700-bar pressure vessels. Japanese and US supplier concentration creates input cost volatility for premium cylinder producers.
- Glass Fiber:E-glass and S-glass reinforcements for moderate-pressure industrial air, nitrogen, and CNG storage. Mature segments prioritize unit economics over weight minimization.
- Aramid Fiber:Hybrid reinforcement layers for impact-resistant liner designs in military and aerospace applications. Ballistic protection requirements drive specification in defense-related programs.
- Others:Basalt fiber and natural fiber composites in development-stage pressure containment research. Emerging alternatives target sustainability credentials in niche demonstration projects.
Carbon fiber commands premium positioning; glass fiber maintains volume leadership.
Manufacturing Stage:
Process automation intensity concentrates margin capture in filament winding cells. Scrap rate differentials between manual and automated production exceed ten percentage points in aerospace-qualified lines.
- Filament Winding:Automated tow placement with in-situ tension and temperature monitoring for aerospace and hydrogen pressure vessels. Real-time feedback loops digitize quality assurance previously dependent on post-cure non-destructive testing.
- Resin Transfer Molding:Closed-mold infusion for complex geometry storage tanks and large-diameter pipes. Rotterdam port authorities evaluate RTM-produced Type IV arrays for maritime hydrogen bunkering infrastructure.
- Pultrusion:Continuous profile production for composite piping and structural reinforcements. Standardized cross-sections enable high-throughput manufacturing with limited customization.
- Compression Molding:High-volume thermoset shaping for automotive cylinder end fittings and protective housings. Secondary operations integrate with filament-wound pressure vessel assemblies.
Filament winding captures the deepest margins; resin transfer molding is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial clusters where EU F-Gas deadlines force accelerated replacement cycles, while South Korean hydrogen mobility programs pull premium Type IV volumes through government-backed fleet procurement. Japan's carbon fiber supply chains anchor aerospace-qualified tow pricing. The United States DOT-SP certification friction creates export qualification premiums for domestic producers.
United States
California freight operators specify total-cost-of-ownership procurement models that weight cylinder mass against hydrogen consumption over vehicle life. DOT-SP special permits and ISO 11119-2 harmonization delays extend export qualification timelines for domestic manufacturers. Houston-Gulf Coast chemical operators evaluate composite alternatives for process gas containment as legacy steel equipment ages out.
Germany
Ruhr industrial cluster chemical operators accelerate steel-to-composite pressure equipment replacement to meet EU F-Gas Regulation containment compliance deadlines. ECHA REACH compliance and CE marking under the Pressure Equipment Directive govern market access for imported composite pressure vessels. Bavaria-based automotive suppliers integrate Type III designs into passenger vehicle fuel storage platforms.
South Korea
Government-backed deployment of heavy-duty fuel cell vehicles pulls Type IV cylinder volumes into commercial vehicle supply chains. MFDS medical device regulations shape certification pathways for lightweight oxygen cylinders in homecare segments. Busan-Ulsan port authorities evaluate shore-to-ship hydrogen bunkering infrastructure without cryogenic liquefaction.
Japan
Aerospace-qualified carbon fiber tow suppliers concentrate pricing power for 700-bar hydrogen cylinder producers facing fatigue performance requirements. METI industrial policy supports hydrogen mobility demonstration projects in metropolitan freight corridors. Nagoya-Chubu manufacturing clusters maintain filament winding technician training pipelines for automated production cells.
Netherlands
Rotterdam port authorities evaluate Type IV cylinder arrays for maritime hydrogen bunkering infrastructure serving North Sea shipping routes. ECHA REACH compliance redirects industrial refrigerant containment toward composite alternatives with lower permeation rates. Eindhoven-Brabant chemical operators face replacement deadlines for steel equipment that cannot meet revised EU F-Gas leakage thresholds.
Global Composites Cylinder Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in filament winding and liner manufacturing. The vendor base stratifies between aerospace-qualified pressure vessel producers and industrial gas cylinder distributors. Three archetypes dominate: integrated hydrogen mobility suppliers, medical oxygen specialists, and industrial gas replacement contractors. Capacity expansion in automated winding cells and strategic partnerships for carbon fiber supply security represent the dominant competitive moves.
Among Nordic and North American platform integrators, Hexagon Composites anchors integrated filament winding capacity for hydrogen mobility supply chains. Luxfer Gas Cylinders exemplifies the medical-specialist archetype through liner-to-composite bonding expertise. Faber Industrie occupies a position within European industrial gas replacement cycles. These three represent divergent strategic positions without implying specific market shares or operational details.
| Leading Market Players |
|---|
| Hexagon Composites |
| Luxfer Gas Cylinders |
| Faber Industrie |
| NPROXX |
| Amtrol-Alfa |
| Worthington Industries |
| Time Technoplast |
| Drägerwerk AG & Co. KGaA |
| EVAS |
| Others |
Supply Flow & Price Mechanics
Busan-Ulsan maritime corridors concentrate hydrogen cylinder logistics costs, amplifying price differentiation between aerospace-certified Type IV vessels and industrial glass-fiber alternatives while compressing margins for undifferentiated storage tank producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Ruhr chemical cluster and South Korean fleet programs. Price differentiation separates DOT-SP dual-certified aerospace pressure vessels from single-standard industrial equipment, with certification grade and after-sales service bundling as primary tiering mechanisms. Cost compression in glass-fiber storage tanks intensifies due to extended steel cylinder residual stock defers composite replacement cycles. Fleet operators exhibit lowest price sensitivity, prioritizing total-cost-of-ownership metrics over unit acquisition cost; commodity industrial gas distributors remain most price-sensitive.
Supply Chain Analysis
Toray Industries and Teijin Limited in Japan, alongside Hexcel Corporation in the United States, concentrate aerospace-qualified carbon fiber tow capacity. Raw material dependencies center on PAN precursor acrylonitrile, epoxy resin systems, and precision aluminum liners. Single-source vulnerability from Japanese-US fiber supplier concentration creates input cost volatility for 700-bar hydrogen cylinder producers. Distribution runs through authorized service networks for pressure vessel recertification, with direct OEM supply agreements dominating high-volume automotive and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales recertification protocols for pressure vessels generate recurring revenue streams expanding faster than hardware sales, positioning service-attach models as the dominant value capture mechanism across aerospace and hydrogen mobility segments.
For Market Incumbents: Pre-empt filament winding technician scarcity by automating tow placement cells in Nagoya-Chubu and Bavaria manufacturing clusters before vocational training pipeline gaps widen. Anchor carbon fiber supply security through long-term offtake agreements with Toray or Teijin, countering aerospace fiber allocation competition from satellite and wind energy sectors. For New Entrants and Emerging Players: Pursue medical oxygen homecare segments in South Korea and California where aluminum weight limits patient mobility and MFDS-FDA regulatory pathways remain less congested than hydrogen mobility certification queues. Target ambulatory patient cylinder replacement cycles through lightweight Type III designs, leveraging direct-to-homecare-provider distribution bypassing industrial gas distributor gatekeepers. For Investors and Strategic Acquirers: Automated filament winding cell operators with in-situ thermographic monitoring capabilities represent the priority acquisition archetype, capturing margin pools digitized through real-time quality assurance. Long-term viability hinges on hydrogen freight scaling beyond demonstration projects into commercial maritime bunkering and heavy-duty corridors. Monitor ISO TC 197 standards finalization as inflection signal reducing multi-jurisdiction certification duplication and unlocking cross-border manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Filament Winding Automation Deployment | Real-time thermographic monitoring eliminates post-cure rework in aerospace-qualified production cells. |
| Carbon Fiber Supply Security Agreement | Long-term offtake contracts with Japanese suppliers anchor input cost stability for 700-bar cylinder producers. |
| Dual Certification Investment | DOT-SP and ISO 11119-2 harmonization reduces export qualification timelines for North American manufacturers. |
| Aftermarket Service Network Expansion | Recertification protocol capabilities capture recurring revenue streams from pressure vessel inspection mandates. |
| Maritime Hydrogen Bunkering Pilot | Rotterdam and Singapore port authority evaluations open shore-to-ship fueling infrastructure without cryogenic liquefaction. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings from composite materials suppliers, and ECHA REACH registration records preceded structured interviews with filament winding plant managers, OEM procurement leads at hydrogen mobility fleet operators, aftermarket service heads, and regulatory affairs directors at pressure vessel manufacturers. Primary fieldwork combined with secondary validation from DOT special permit filings and ISO technical committee documentation. Bottom-up capacity estimates from automated winding cell counts triangulated against top-down hydrogen cylinder demand projections from fleet deployment schedules.
Assumptions held carbon fiber supply concentration and EU F-Gas phase-down timelines fixed across the projection horizon, while hydrogen mobility adoption rates and DOT-SP harmonization progress varied under sensitivity scenarios. Segmentation dimensions modeled included pressure rating tier, fiber reinforcement grade, manufacturing process type, end-use application, and regional regulatory cluster. CAGRs derived from volume-weighted average of segment growth trajectories, with hydrogen-specific fatigue performance requirements and medical oxygen homecare expansion as industry-specific demand inputs.
Sensitivities concentrate around carbon fiber allocation shifts to competing aerospace applications and delays in ISO TC 197 standards finalization extending certification duplication costs. Forecasts reflect documented assumptions regarding fleet deployment schedules and regulatory harmonization timelines. Quarterly review of hydrogen refueling infrastructure project finance closures and filament winding automation equipment order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Medical Composite Material Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
FRP Reactor Market
Composite Materials
Global Coupling Agents Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Core Material for Composites Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Carbon Composites Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Global Geocomposites Market