
 Dibutyl Ether Market | 2026-2036
Dibutyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Dibutyl Ether Market Outlook
Aftermarket solvent reclamation services is reshaping margin distribution across the dibutyl ether value chain. BASF SE leverages backward integration into butanol feedstock to control cost volatility at its Ludwigshafen complex. Merck KGaA anchors high-purity pharmaceutical-grade supply through stringent quality protocols. INEOS competes on scale economics across European industrial solvent distribution networks.
Dibutyl ether, a dialkyl ether with the molecular formula C8H18O and boiling point of 142°C, serves primarily as an aprotic solvent and reaction medium in organic synthesis and extraction processes. The solvent application dominates current volume flows through paints and coatings formulation networks, while pharmaceutical-grade extraction agent supply commands premium positioning due to stringent purity thresholds. Liquid form shipments sustain the majority of commercial transactions, though specialized gas-phase applications are gaining traction in precision chemical processing.
REACH registration requirements and ECHA substance evaluation protocols govern market access across Europe, while EPA hazard communication standards shape North American product stewardship obligations. FDA oversight of residual solvent limits in pharmaceutical applications directly determines specification thresholds for extraction-grade material. Stakeholders must monitor evolving green chemistry mandates that could accelerate substitution risk or create premium tiers for bio-based ether alternatives.
Market Dynamics
REACH compliance tightening across Europe is forcing reformulation of solvent systems in pharmaceutical extraction, redirecting volume toward high-purity dibutyl ether grades and compressing margins for standard industrial specifications.
Growth Catalysts
- Pharmaceutical-grade extraction protocols:FDA residual solvent limits are tightening purity thresholds for active pharmaceutical ingredient manufacturing, elevating demand for ultra-high-purity dibutyl ether in drug synthesis workflows.
- REACH substance evaluation:ECHA's rolling evaluation of ether-based solvents is disqualifying lower-grade alternatives, creating regulated demand concentration for compliant dibutyl ether supply.
- Butanol feedstock availability:Germany's chemical manufacturing corridor maintains captive n-butanol supply through integrated petrochemical complexes, securing cost-advantaged dibutyl ether production capacity.
Market Restraints
- N-butanol price volatility:Crude oil-linked feedstock costs transmit directly into dibutyl ether manufacturing economics, compressing processor margins during upstream commodity spikes.
- Substitution by methyl tert-butyl ether:Industrial cleaning and coating applications are migrating to MTBE where purity requirements permit, eroding volume in standard-grade dibutyl ether segments.
- REACH registration cost barriers:Small-volume specialty ether producers face disproportionate compliance burdens relative to tonnage, consolidating supply among registrants with scale economics.
Strategic Opportunities
- Bio-based ether alternatives:EU Green Deal bioeconomy incentives are creating premium-tier positioning for fermentation-derived dibutyl ether variants in sustainable pharmaceutical supply chains.
- Gas-phase precision processing:Semiconductor and advanced materials manufacturing is adopting vapor-phase dibutyl ether delivery for thin-film deposition, opening specialty volume outside traditional liquid solvent markets.
- Aftermarket solvent reclamation:Circular economy mandates in Germany and France are accelerating third-party reclamation service development, creating margin capture opportunities beyond virgin material sales.
Industry Challenges
- Analytical chemistry talent scarcity:Pharmaceutical-grade certification requires specialized chromatography and spectroscopy expertise that competes with broader biopharma labor markets.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and national pharmacopeia compliance creates 18-24 month product qualification cycles that lock working capital.
- Legacy coating formulation integration:Industrial paint and coating customers maintain entrenched solvent blends that resist specification changes despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dibutyl Ether Market |
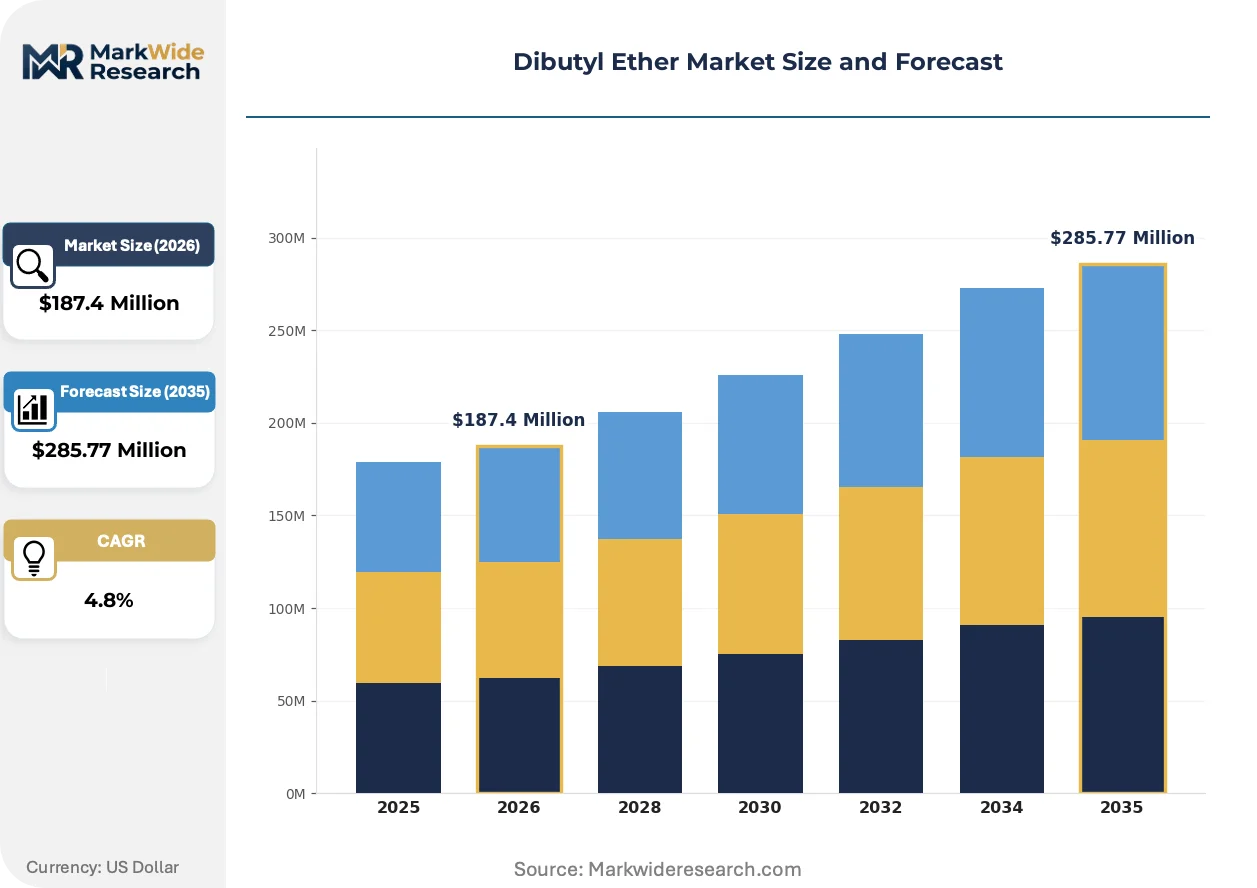
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Solvent, Fuel Additive, Chemical Intermediate, Extraction Agent End User: Paints & Coatings, Pharmaceuticals, Agriculture, Cosmetics Form: Liquid, Gas, Powder, Emulsion Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Tokyo Chemical Industry (TCI), Merck KGaA, Thermo Fisher Scientific, Alfa Aesar, INEOS, ExxonMobil, Huntsman Corporation, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dibutyl Ether Market Strategic Shifts
Process intensification technologies are compressing unit economics for high-purity ether production while regulatory chemistry mandates accelerate substitution dynamics across end-use verticals.
Continuous flow reactor technology for dialkyl ether synthesis is hybridizing batch and flow chemistry approaches to reduce solvent contamination risk. Pharmaceutical contract manufacturers in Switzerland and Germany are retrofitting multi-purpose plants with skid-mounted continuous units. This hybridizing architecture is collapsing the traditional purity-grade cost gradient by enabling on-demand pharmaceutical-grade output from standard industrial feedstock.
ECHA's 2024-2026 substance evaluation work program prioritizes ether compounds for hazard reassessment, with draft opinions expected to restrict certain impurity profiles. Industrial solvent distributors are pre-positioning compliant inventory ahead of formal restriction dates. Coating formulators in Italy and Spain are accelerating qualification of alternative ether blends to avoid supply disruption.
Consolidated procurement by multinational pharmaceutical manufacturers is concentrating volume with dual-source qualified suppliers and compressing spot-market participation. Large-scale API producers in Ireland and the Netherlands are mandating three-year supply agreements with fixed purity specifications. This behavior is most visible in oncology and hormone synthesis verticals where solvent residuals face heightened pharmacovigilance scrutiny.
Dibutyl Ether Market Segmentation
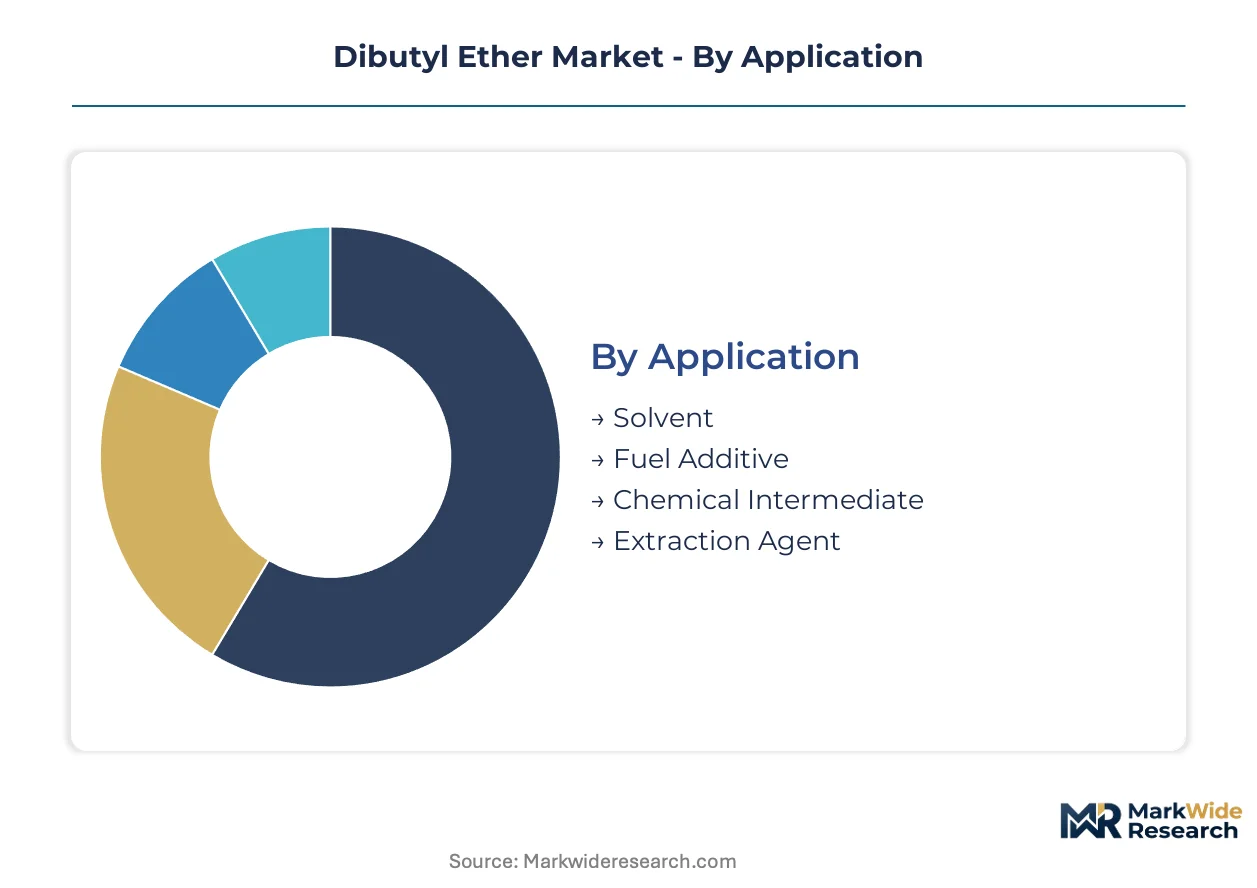
Dibutyl ether's functional versatility across aprotic solvent, extraction medium, and chemical feedstock roles creates distinct demand profiles. Each application carries divergent purity specifications, regulatory burdens, and margin structures that reshape competitive positioning across the value chain.
Application:
Use-case spectrum spans industrial commodity consumption to pharmaceutical-grade precision, with purity thresholds determining accessible end-markets and pricing power.
- Solvent:Aprotic solvent properties enable dissolution of polar and non-polar compounds in organic synthesis workflows. Paints and coatings formulation in Germany's industrial corridor absorbs the largest volume flows, though REACH substance evaluation is disqualifying lower-purity grades and compressing spot-market participation.
- Extraction Agent:Pharmaceutical-grade material meets FDA residual solvent limits for active pharmaceutical ingredient manufacturing, commanding substantial premiums over industrial specifications. Oncology and hormone synthesis verticals in Ireland and the Netherlands mandate multi-year supply agreements with fixed purity protocols, locking volume with qualified suppliers.
- Fuel Additive:Oxygenate functionality in diesel and gasoline blending applications faces displacement by MTBE where regulatory specifications permit.
- Chemical Intermediate:Dialkyl ether backbone serves as building block for surfactant and plasticizer synthesis, with demand tied to downstream polymer and personal care markets.
The dominant share belongs to Solvent, while Extraction Agent is closing the gap fastest.
End User:
Customer concentration patterns mirror regional manufacturing specialization, with pharmaceutical and coatings clusters anchoring distinct procurement behaviors.
- Paints & Coatings:Industrial formulation networks in Italy and Spain maintain entrenched solvent blends that resist specification changes despite regulatory pressure. Legacy coating customers prioritize volume scale and supply reliability over purity upgrades, creating margin compression for standard-grade suppliers.
- Pharmaceuticals:API manufacturers in Switzerland and Germany drive demand for ultra-high-purity material, with contract manufacturers retrofitting multi-purpose plants with continuous flow reactor technology to collapse purity-grade cost gradients.
- Agriculture:Pesticide and agrochemical formulation consumes standard-grade solvent for active ingredient dissolution and emulsion stabilization.
- Cosmetics:Personal care applications leverage dibutyl ether as fragrance carrier and formulation solvent, with EU Green Deal bioeconomy incentives creating premium positioning for sustainable variants.
Pharmaceuticals commands the steepest expansion trajectory, while Paints & Coatings retains volume leadership despite regulatory headwinds.
Form:
Physical state determines handling infrastructure, shipping economics, and accessible application technologies across end-use verticals.
- Liquid:Standard liquid shipments sustain the majority of commercial transactions, with bulk tanker and drum packaging serving established coatings and pharmaceutical workflows. Liquid form dominates current volume flows through European distribution networks.
- Gas:Vapor-phase delivery systems are gaining traction in semiconductor and advanced materials manufacturing for thin-film deposition processes, opening specialty volume outside traditional liquid solvent markets.
- Powder:Solid-state formulations serve niche encapsulation and controlled-release applications in agrochemical and pharmaceutical delivery systems.
- Emulsion:Aqueous dispersion formats enable water-based coating formulations and reduced-VOC compliance in environmentally regulated jurisdictions.
Liquid form maintains entrenched dominance, while Gas-phase applications are gaining share fastest in precision processing segments.
Distribution Channel:
Channel selection reflects customer scale, specification complexity, and regulatory documentation requirements across end-use categories.
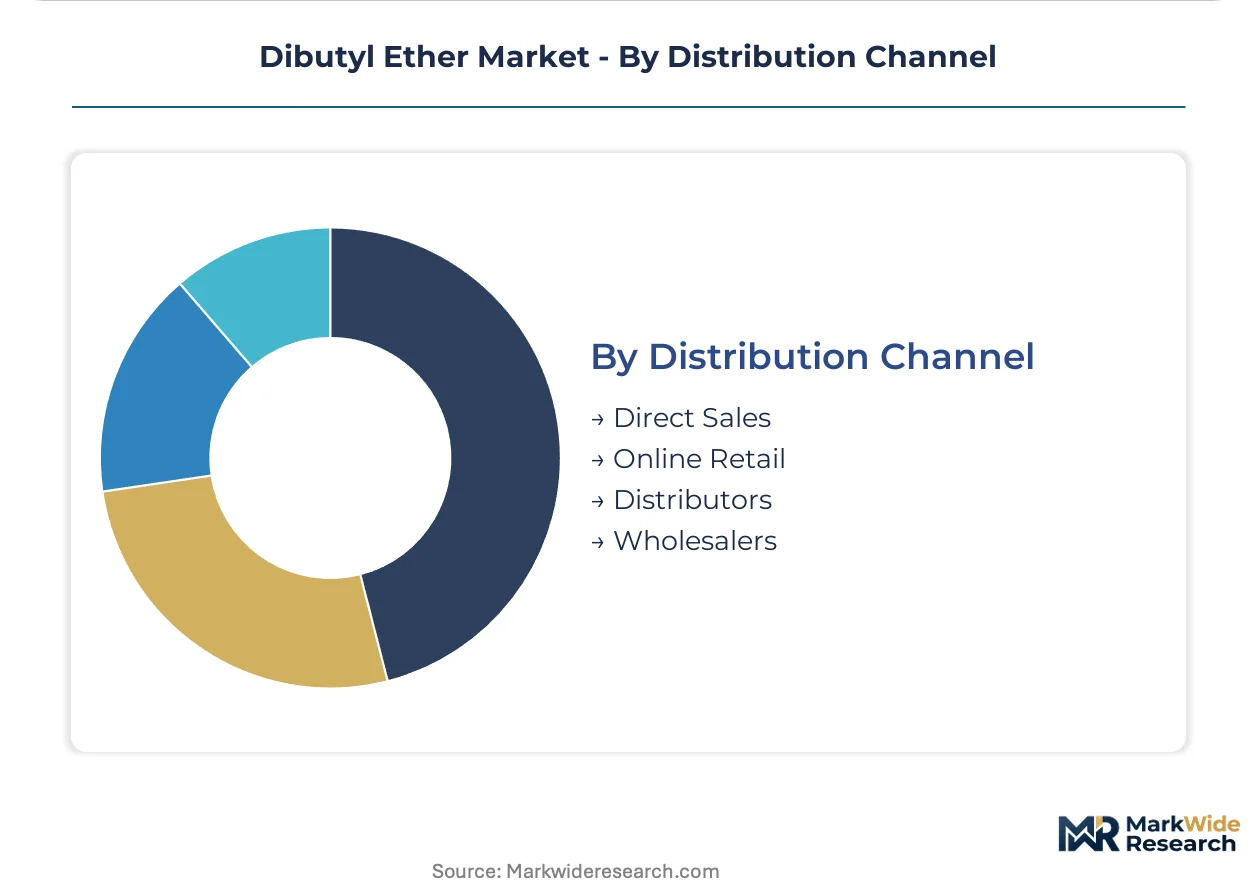
- Direct Sales:Large-scale API producers and multinational coatings manufacturers consolidate procurement through direct relationships with qualified suppliers, mandating three-year supply agreements with fixed purity specifications and compressing spot-market participation.
- Distributors:Industrial solvent distributors across European networks compete on scale economics and inventory positioning, pre-positioning REACH-compliant inventory ahead of formal restriction dates.
- Online Retail:Digital procurement platforms serve small-volume specialty buyers and research laboratories with fragmented demand patterns.
- Wholesalers:Bulk intermediaries aggregate standard-grade volume for downstream resale to regional coatings and agricultural formulators.
Direct Sales captures the largest revenue concentration, while Distributors are expanding most quickly through aftermarket solvent reclamation service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers in Switzerland and Germany exhibit minimal price elasticity, while industrial coatings customers in Italy and Spain remain acutely sensitive to standard-grade dibutyl ether pricing. REACH compliance costs and n-butanol feedstock availability create divergent margin pressures across European demand clusters.
Germany
BASF SE and Merck KGaA anchor pharmaceutical-grade supply relationships through the Ludwigshafen chemical corridor. ECHA substance evaluation protocols under REACH are disqualifying lower-purity ether alternatives from market access. Captive n-butanol supply through integrated petrochemical complexes secures cost-advantaged production capacity for compliant dibutyl ether grades.
Switzerland
Contract manufacturers serving oncology and hormone synthesis verticals drive demand for ultra-high-purity extraction agents. Swissmedic oversight of residual solvent limits in API manufacturing elevates specification thresholds beyond standard industrial grades. Basel-area pharmaceutical clusters mandate multi-year supply agreements with fixed purity protocols, compressing spot-market participation.
Netherlands
Large-scale API producers in Rotterdam and Amsterdam consolidate procurement through direct supplier relationships with stringent documentation requirements. EU Green Deal bioeconomy incentives are creating premium-tier positioning for sustainable ether variants in pharmaceutical supply chains. Industrial solvent distributors pre-position REACH-compliant inventory ahead of formal restriction dates.
Italy
Paints and coatings formulators in Lombardy and Veneto maintain entrenched solvent blends that resist specification changes despite regulatory pressure. Legacy industrial customers prioritize volume scale and supply reliability over purity upgrades, creating margin compression for standard-grade suppliers. Aftermarket solvent reclamation services are gaining traction under circular economy mandates.
Spain
Coating formulators in Catalonia and the Basque Country are accelerating qualification of alternative ether blends to avoid supply disruption from impending ECHA restrictions. N-butanol price volatility transmits directly into manufacturing economics, compressing processor margins during upstream commodity spikes. Industrial solvent demand concentrates in automotive and construction coating applications.
Dibutyl Ether Market Competitive Environment
Capability concentration sits with pharmaceutical-grade specialists; scale advantage sits with integrated petrochemical majors. The market structures around three tiers: backward-integrated feedstock controllers, purity-certification specialists, and distribution-scale intermediaries. Dominant competitive moves include captive butanol supply integration and continuous flow reactor technology licensing for on-demand pharmaceutical-grade output.
Among German-based integrated producers, BASF SE exemplifies feedstock control through captive n-butanol supply at Ludwigshafen. Merck KGaA occupies a position anchoring high-purity pharmaceutical-grade certification through stringent quality protocols. INEOS sits within the scale-driven tier competing across European industrial solvent distribution networks. Tokyo Chemical Industry represents the specialty chemical distributor archetype serving fragmented laboratory and research demand.
| Leading Market Players |
|---|
| BASF SE |
| Tokyo Chemical Industry (TCI) |
| Merck KGaA |
| Thermo Fisher Scientific |
| Alfa Aesar |
| INEOS |
| ExxonMobil |
| Huntsman Corporation |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
Germany's captive n-butanol supply through integrated petrochemical complexes anchors cost-advantaged dibutyl ether production, concentrating margin capture with backward-integrated producers while standard-grade suppliers face compression from feedstock volatility and REACH compliance burdens.
Pricing Analysis
Aftermarket solvent reclamation services are reshaping lifetime value capture across the value chain. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and reclaimed solvent levels separates premium extraction agents from commodity solvents. Cost compression in standard industrial grades is intensifying because MTBE substitution erodes volume in coatings applications. Paints and coatings formulators in Italy and Spain exhibit acute price sensitivity, while Swiss and German pharmaceutical buyers show minimal elasticity for FDA-compliant material.
Supply Chain Analysis
N-butanol feedstock availability centers on Germany, Belgium, and the Netherlands through integrated petrochemical corridors. Raw material dependencies include crude oil-linked n-butanol, catalytic dehydration equipment, and pharmaceutical-grade filtration systems. Single-source vulnerability concentrates with BASF's Ludwigshafen complex for high-purity European supply. Distribution runs through direct sales channels for large-scale API producers and industrial solvent distributors for fragmented coatings demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance tightening is functioning as a platform-economics inflection, concentrating qualified supply relationships with registrants possessing scale economics and ECHA dossier expertise while disqualifying fragmented competitors.
For Market Incumbents: Entrench pharmaceutical-grade certification moats through continuous flow reactor licensing and captive butanol supply expansion at Ludwigshafen-scale complexes. Defend against bio-based ether entrants by pre-positioning compliant inventory ahead of ECHA restriction dates. Lock volume with three-year supply agreements featuring fixed purity protocols for oncology and hormone synthesis verticals.
For New Entrants and Emerging Players: Establish a beachhead in aftermarket solvent reclamation services under Germany and France circular economy mandates. Target gas-phase precision processing for semiconductor thin-film deposition as the most penetrable specialty volume outside liquid solvent markets. Pursue fermentation-derived dibutyl ether qualification under EU Green Deal bioeconomy incentives as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial solvent distributors lacking pharmaceutical-grade certification infrastructure. Long-term viability favors purity-certification specialists with ECHA dossier completion and FDA master file access. Watch ECHA's 2024-2026 substance evaluation draft opinions as the signal for regulatory-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butanol Feedstock | BASF's Ludwigshafen complex secures cost-advantaged production capacity against n-butanol price volatility. |
| Continuous Flow Reactor Technology Licensing | Swiss and German contract manufacturers collapse purity-grade cost gradients through hybrid batch-flow architectures. |
| Pharmaceutical-Grade Certification Investment | FDA master file completion and ECHA REACH dossier submission lock out non-compliant competitors from oncology synthesis. |
| Aftermarket Solvent Reclamation Expansion | Circular economy mandates in Germany and France create margin capture beyond virgin material sales. |
| Bio-Based Ether Alternative Development | Fermentation-derived variants qualify for EU Green Deal premium positioning in sustainable pharmaceutical supply chains. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pharmaceutical procurement managers, coatings formulators, solvent distribution channel heads, and ECHA regulatory affairs specialists. Secondary validation drew from ECHA substance evaluation dossiers, FDA residual solvent guidance documents, Cefic solvent market reports, and customs trade flow data. Bottom-up volume modeling triangulated against top-down petrochemical capacity assessments.
Calibration anchored forward projections to historical REACH implementation patterns and pharmaceutical-grade pricing trajectories across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use vertical, physical form, and regional regulatory cluster. CAGRs were derived from regression analysis against n-butanol feedstock pricing and pharmaceutical manufacturing capacity expansion. Industry-specific inputs incorporated ECHA restriction timeline probabilities and FDA inspection frequency trends.
Stress conditions across n-butanol price volatility bands, REACH registration cost escalation, and MTBE substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and pharmaceutical manufacturing location decisions. Cross-checking against ECHA's published substance evaluation work program updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Nitrobenzene Market
Solvents
Oxygenated Solvents Market
Solvents
Green Solvents Market
Solvents
Global Xylenols Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Saudi Arabia Methanol Market
Solvents
Butyl Glycol Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Hexylene Glycol Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Global Acetonitrile Market
Solvents
Benzene Market
Solvents
Piperylene Market
Solvents
Citrus Solvents Market
Solvents
Methyl Acetate Market
Solvents
Mesitylene Market