
 Graphite Felt Market | 2026-2036
Graphite Felt Market Size, Share, and Industry Trends Forecast 2026-2036
Graphite Felt Market Outlook
A capital-intensity divergence between integrated carbon precursor producers and downstream felt converters is bifurcating competitive tiers. Morgan Advanced Materials leverages in-house carbon fiber spinning to control raw material quality from PAN precursor to finished felt. SGL Carbon anchors European supply through captive pitch-based carbon fiber operations near Meitingen. Beijing Great Wall Co. Ltd dominates cost-sensitive Asian procurement by operating large-scale needle-punched lines with domestic coal-tar pitch feedstock.
Graphite felt consists of carbonized and graphitized fibrous mats, typically processed from polyacrylonitrile or pitch precursors at temperatures exceeding 2000°C to achieve thermal conductivity below 0.15 W/m·K and oxidation resistance above 400°C in inert atmospheres, serving primarily as high-temperature insulation and electrochemical electrode substrates. Needle-punched forms occupy the volume core due to mechanical integrity under cyclic thermal stress, while rolled configurations for flow battery electrodes command premium positioning as vanadium redox installations multiply. Aerospace applications in thermal protection systems sustain mature margins despite lower volume growth relative to energy sector demand.
EPA emissions guidelines for carbon fiber manufacturing and REACH substance restrictions on polycyclic aromatic hydrocarbons in Europe are elevating environmental compliance costs for precursor producers. China's MEE enforcement of dual carbon targets is accelerating furnace upgrades and energy efficiency mandates at Shandong and Jiangsu felt mills. Stakeholders must monitor evolving battery electrode specifications from energy storage integrators and carbon content thresholds from building insulation certifiers as qualification requirements tighten.
Market Dynamics
Vanadium redox flow battery manufacturers are consolidating electrode procurement around needle-punched graphite felt specifications, forcing precursor-to-felt supply chain reconfiguration as energy storage deployment scales.
Growth Catalysts
- China's dual carbon goals:MEE enforcement of carbon intensity benchmarks is accelerating furnace upgrades at Jiangsu and Shandong felt mills, expanding domestic capacity for battery-grade material.
- Energy storage deployment:Vanadium redox flow battery integrators are qualifying graphite felt electrodes against stricter conductivity and oxidation resistance thresholds, pulling volume through dedicated supply agreements.
- Pitch-based precursor innovation:Coal-tar pitch carbonization yields are improving through controlled oxidative stabilization, lowering unit costs for cost-sensitive thermal insulation applications.
Market Restraints
- PAN precursor cost volatility:Acrylonitrile feedstock prices fluctuate with petrochemical cycles, compressing margins for polyacrylonitrile-based felt producers serving aerospace thermal protection.
- European supply concentration:SGL Carbon's captive pitch-fiber operations near Meitingen anchor regional electrode supply, creating single-source vulnerability for flow battery manufacturers.
- REACH PAH restrictions:ECHA substance limitations on polycyclic aromatic hydrocarbons in carbon fiber manufacturing elevate environmental compliance costs for precursor producers exporting to EU markets.
Strategic Opportunities
- India energy storage:CEA grid-scale battery mandates and PLI scheme incentives for domestic manufacturing create procurement pull for imported graphite felt electrodes as local precursor capacity remains underdeveloped.
- Solid oxide fuel cell integration:Convergence of high-temperature fuel cell stack designs with graphite felt bipolar plate substrates opens electrode supply contracts outside traditional battery verticals.
- Direct mill procurement:Vanadium redox developers are bypassing distributors to negotiate long-term offtake directly with Jiangsu felt processors, compressing channel margins and securing specification control.
Industry Challenges
- Graphitization furnace operator scarcity:Skilled technicians capable of managing 2000°C+ thermal profiles and atmosphere control are concentrated at legacy carbon material facilities in China and Germany.
- Battery electrode certification timelines:Flow battery integrators require 18-24 month qualification cycles for felt electrode batches, locking working capital and delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphite Felt Market |
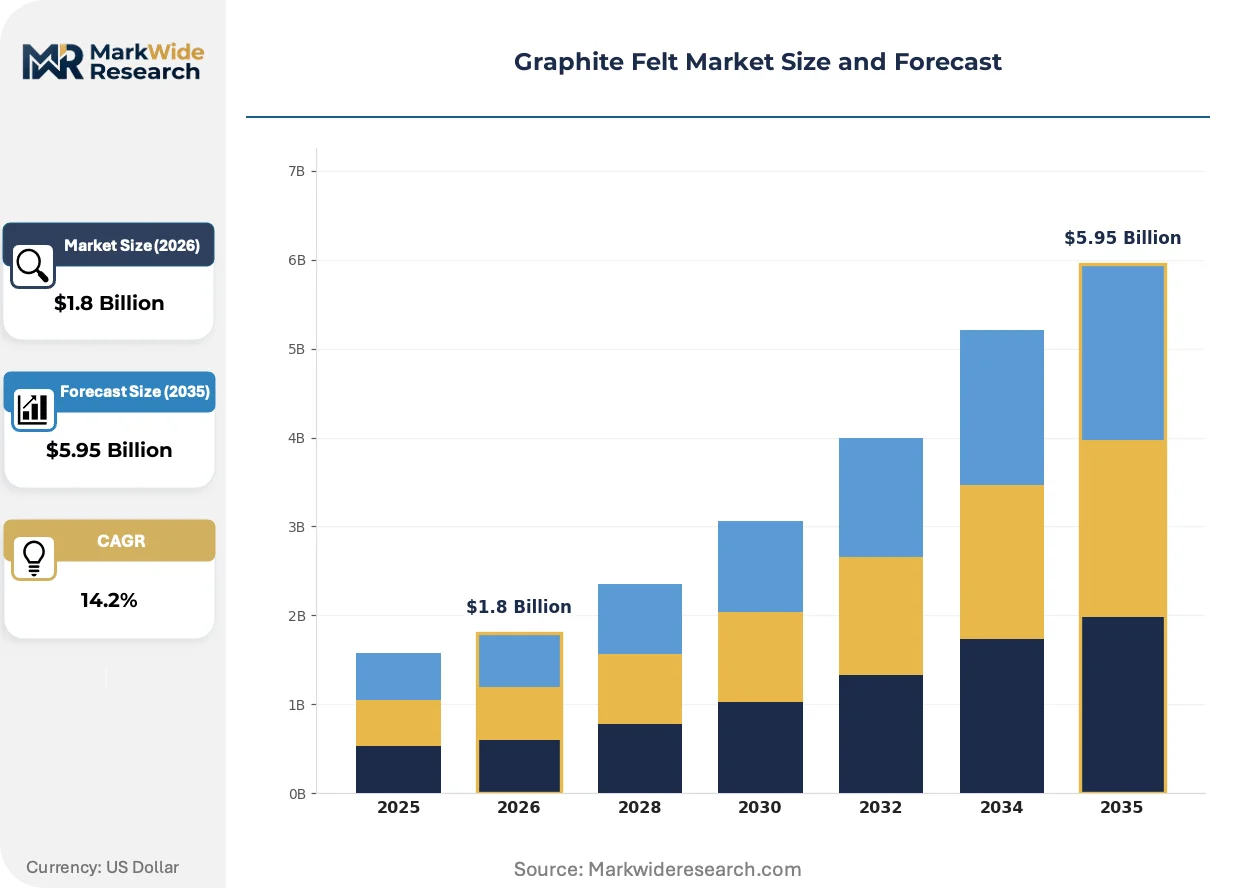
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle-Punched, Extruded, Woven, Taped Application: High-Temperature Insulation, Electrode Manufacturing, Aerospace Components, Industrial Furnaces End User: Aerospace, Automotive, Energy, Electronics Form: Blanket, Roll, Sheet, Board |
| Companies Covered | Morgan Advanced Materials, SGL Carbon, Mersen Graphite, Nippon Carbon Co. Ltd, Schunk Carbon Technology, Beijing Great Wall Co. Ltd, Kureha Corporation, CGT Carbon GmbH, Carbon Composites Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphite Felt Market Strategic Shifts
Electrochemical energy storage specifications are rewriting material performance thresholds faster than traditional thermal insulation demand patterns, splitting graphite felt development pathways between battery-optimized and furnace-grade product lines.
Needle-punched felt architecture is bifurcating the market. Battery electrode applications demand controlled fiber orientation and compressed thickness tolerances for vanadium redox stack assembly. Thermal insulation buyers prioritize loft recovery and handling durability for furnace lining installation. The divergence is compressing interchangeability between end-use segments and forcing producers to commit capacity to single specification tracks.
REACH substance restrictions on polycyclic aromatic hydrocarbons are tightening precursor processing standards across European carbon fiber operations. ECHA enforcement is elevating wastewater treatment and emissions capture investments at pitch-based fiber facilities. German and French felt converters are responding by qualifying Asian PAN-based alternatives to reduce regulatory exposure.
Long-term electrode supply agreements are displacing spot procurement for utility-scale vanadium redox installations. Developers in Australia and South Africa are negotiating five-year offtake contracts directly with Chinese felt mills, bypassing traditional chemical distribution channels. The shift concentrates volume with integrated precursor-to-felt producers capable of warranting batch consistency across extended delivery schedules.
Graphite Felt Market Segmentation
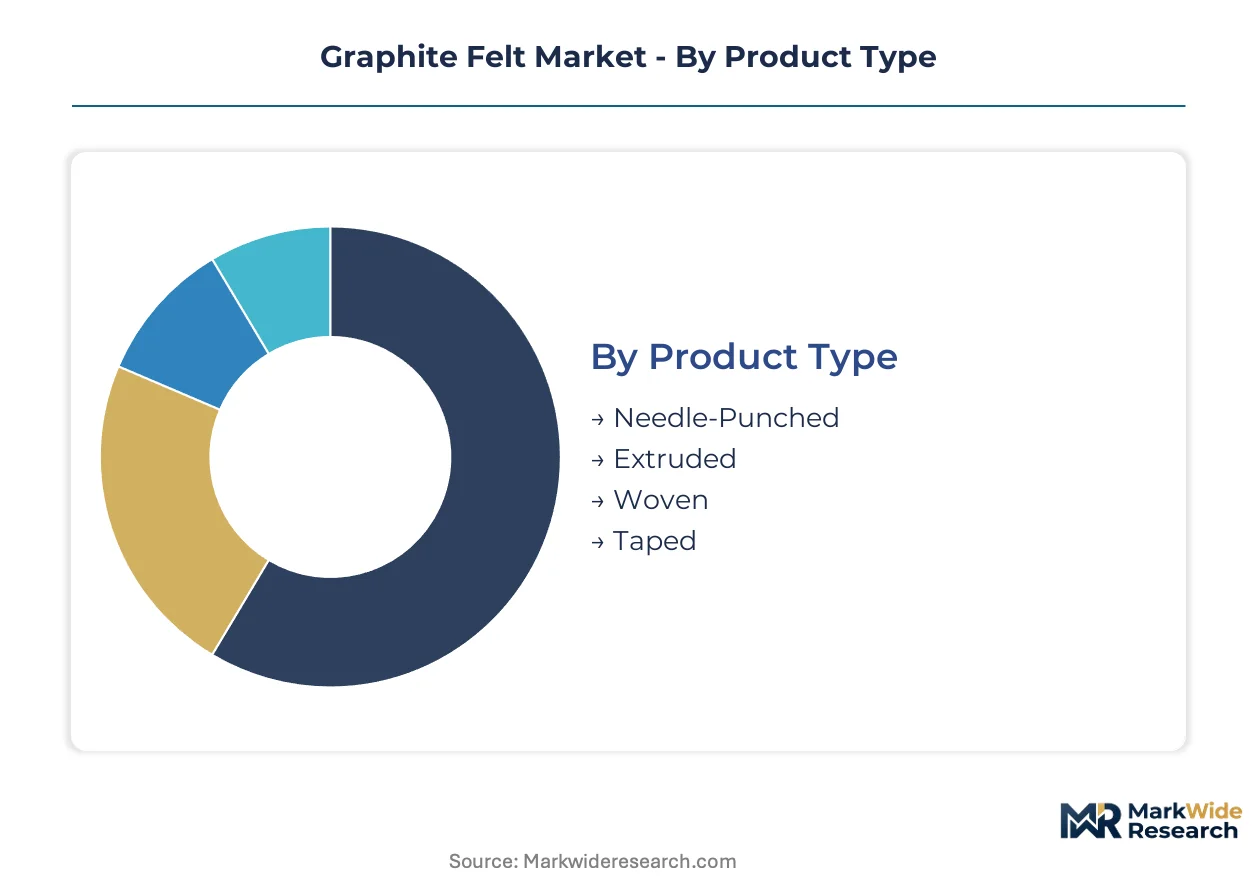
Graphite felt specifications diverge sharply between electrochemical and thermal applications, forcing producers to commit furnace capacity to discrete qualification tracks. Segment boundaries harden as battery integrators impose conductivity tolerances incompatible with legacy insulation grades.
Product Type:
Needle-punched architectures face substitution pressure from compressed rolled configurations in flow battery stacks, where thickness uniformity outweighs mechanical resilience.
- Needle-Punched:Fibrous mats interlocked through barbed needle mechanical bonding retain loft under cyclic thermal stress. Demand concentrates in Jiangsu province furnace lining contracts where handling durability during installation outweighs electrochemical performance.
- Extruded:Densified profiles formed through controlled compression and binder carbonization achieve dimensional stability for bipolar plate substrates. Solid oxide fuel cell stack assemblers in Germany specify extruded felt for gas diffusion layer compatibility.
- Woven:Orthogonal fiber interlacing produces surface uniformity for aerospace thermal protection systems. NASA and ESA qualification protocols sustain mature procurement volumes despite slower expansion than energy sector applications.
- Taped:Adhesive-backed narrow rolls serve furnace maintenance patching and emergency lining repair. Industrial maintenance contractors in Shandong province stock taped inventory for rapid turnaround during planned outages.
Needle-punched forms anchor the volume base while extruded configurations gain share at the steepest rate.
Application:
Cost tier stratification separates furnace-grade insulation from electrode-specification material commanding threefold price multiples.
- High-Temperature Insulation:Low-density felt batts lining vacuum and inert atmosphere furnaces require oxidation resistance above 400°C. Chinese dual carbon enforcement at Jiangsu mills is tightening energy efficiency benchmarks for this mature demand segment.
- Electrode Manufacturing:Graphitized felt substrates for vanadium redox flow batteries demand controlled fiber orientation and compressed thickness below 5mm. Australian and South African developers negotiate five-year offtake contracts directly with Shandong processors, bypassing distribution.
- Aerospace Components:Thermal protection system applications sustain qualification-intensive procurement with batch traceability from PAN precursor through graphitization. Boeing and Airbus tier-1 suppliers require ISO-certified furnace logs for every production lot.
- Industrial Furnaces:Batch and continuous furnace lining replacement cycles drive recurring demand from steel heat treatment and carbonization facilities. German automotive component suppliers specify felt density grades calibrated to specific thermal cycling profiles.
High-temperature insulation commands the largest revenue pool while electrode manufacturing climbs fastest.
End User:
Customer type concentration varies by procurement sophistication, with energy developers imposing stricter qualification protocols than industrial maintenance buyers.
- Aerospace:Prime contractors and tier-1 thermal protection system suppliers require AS9100-certified production with full precursor chain of custody. Margins sustain premium positioning despite lower volume velocity than energy applications.
- Automotive:Solid oxide fuel cell research programs and specialized heat treatment operations represent emerging procurement. German KBA emissions compliance for fuel cell vehicle testing is accelerating felt specification standardization.
- Energy:Vanadium redox flow battery integrators and utility-scale storage developers dominate electrode-grade demand. India's CEA grid-scale battery mandates are creating procurement pull for imported felt as domestic precursor capacity remains underdeveloped.
- Electronics:Semiconductor crystal growth furnace insulation and silicon carbide processing equipment sustain niche volume. Japanese METI semiconductor equipment export controls are reshaping supply chain sourcing for this segment.
Energy sector procurement is expanding most quickly while aerospace retains the highest margin tier.
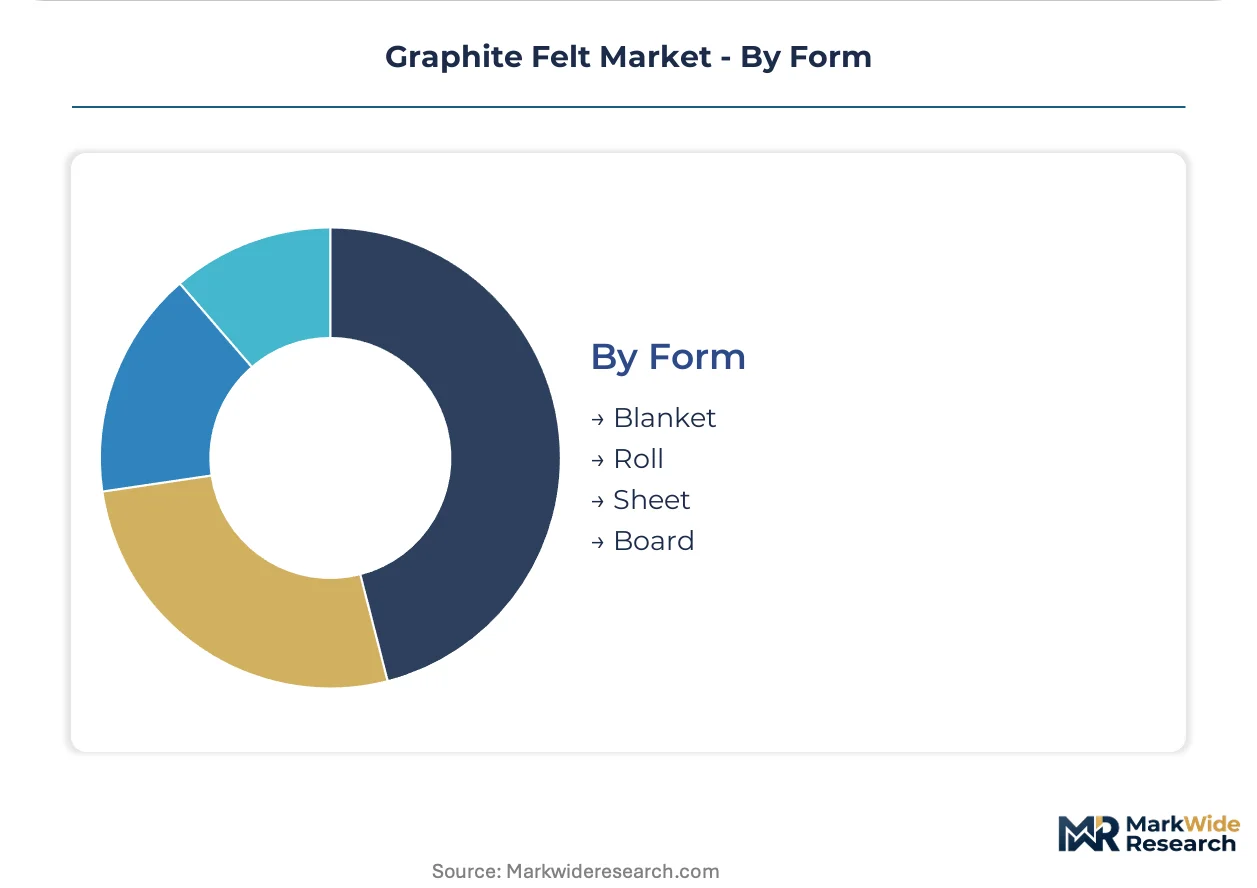
Form:
Supply concentration in Chinese processing clusters shapes form factor availability, with rolled configurations for battery electrodes commanding dedicated production lines.
- Blanket:Large-format batts for furnace lining installation prioritize loft recovery after compression during shipping. Shandong mills operate dedicated blanket needle-punch lines with widths exceeding 2 meters for industrial furnace contracts.
- Roll:Continuous wound felt for automated electrode cutting and flow battery stack assembly requires tight thickness tolerance. Vanadium redox developers specify roll formats to minimize seam joints in large-format cell stacks.
- Sheet:Cut-to-dimension panels serve aerospace thermal protection and specialized research equipment. Swiss and French converters stock sheet inventory for rapid prototyping and qualification sample production.
- Board:Rigidized felt composites with ceramic binders withstand compressive loads in structural insulation applications. German industrial furnace OEMs specify board formats for door seals and structural support elements.
Blanket formats dominate tonnage shipments while roll configurations achieve the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese felt mills command pricing leverage over European converters due to integrated precursor capacity and lower energy costs, while German manufacturers retain premium positioning through qualification-intensive aerospace contracts.
China
Vanadium redox battery electrode demand and vacuum furnace insulation replacement cycles drive procurement volume. MEE enforcement of dual carbon goals accelerates furnace upgrades at Jiangsu and Shandong processing clusters. Beijing's GB standards for carbon materials tighten domestic production benchmarks, consolidating output around large-scale needle-punch lines.
Germany
Solid oxide fuel cell stack assembly and aerospace thermal protection sustain high-margin procurement. KBA emissions compliance for fuel cell vehicle testing elevates felt specification standardization. Meitingen anchors captive pitch-based carbon fiber operations serving European electrode supply.
United States
Utility-scale energy storage deployment and semiconductor crystal growth furnace maintenance create dual demand tracks. EPA emissions guidelines for carbon fiber manufacturing elevate environmental compliance costs for domestic precursor producers. Texas and Arizona industrial corridors concentrate procurement for high-temperature insulation contracts.
India
CEA grid-scale battery mandates and PLI scheme incentives for domestic manufacturing generate electrode felt import demand. BIS certification requirements for carbon materials remain underdeveloped, delaying local precursor investment. Maharashtra and Gujarat ports handle bulk shipments from Chinese mills as developers bypass distribution channels.
Japan
Semiconductor equipment insulation and specialized research applications sustain niche volume. METI export controls on semiconductor manufacturing equipment reshape supply chain sourcing for carbon felt components. Kyushu and Chubu industrial zones maintain qualification-intensive relationships with aerospace prime contractors.
Graphite Felt Market Competitive Environment
Concentration sits with integrated precursor-to-felt producers who control quality from PAN or pitch feedstock through graphitization. The vendor base separates into three tiers: multinational material conglomerates with captive carbon fiber spinning, regional Chinese mills operating coal-tar pitch lines at scale, and specialized European converters serving qualification-intensive aerospace and fuel cell verticals. Dominant competitive moves include backward integration into precursor production and long-term offtake contracting with vanadium redox developers.
Within the multinational tier, Morgan Advanced Materials and SGL Carbon exemplify integrated positioning through in-house carbon fiber operations. Beijing Great Wall Co. Ltd occupies the cost-sensitive Asian procurement segment through large-scale domestic processing. Kureha Corporation represents Japanese specialization in pitch-based carbon materials for electrochemical applications.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| SGL Carbon |
| Mersen Graphite |
| Nippon Carbon Co. Ltd |
| Schunk Carbon Technology |
| Beijing Great Wall Co. Ltd |
| Kureha Corporation |
| CGT Carbon GmbH |
| Carbon Composites Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with vanadium redox developers lock in both supply access and price visibility for Jiangsu and Shandong felt mills, compressing spot market liquidity while insulating integrated producers from acrylonitrile feedstock volatility. Australian and South African utility-scale projects negotiate five-year capacity reservations directly with Chinese processors, bypassing chemical distributors and establishing fixed-price corridors that standard-grade thermal insulation buyers cannot access.
Pricing Analysis
Configured-to-order pricing for battery-grade rolled felt commands spreads exceeding threefold over standard needle-punched blanket formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by fiber orientation control, graphitization furnace log certification, and batch conductivity consistency. Cost compression in the economy tier intensifies as Beijing Great Wall Co. Ltd scales coal-tar pitch lines, while aerospace procurement sustains premium positioning through AS9100 traceability requirements. Energy developers exhibit lowest price sensitivity due to electrode certification lock-in, whereas industrial furnace maintenance buyers prioritize unit cost over specification tolerance.
Supply Chain Analysis
Graphitization furnace operator scarcity concentrated at legacy facilities in China and Germany creates a chokepoint that constrains global electrode-grade output expansion. Raw material flows draw from polyacrylonitrile precursors in Japan and pitch-based carbon fiber operations near Meitingen, with finished felt processing anchored in Jiangsu and Shandong provinces. Single-source vulnerability runs through SGL Carbon's captive pitch-fiber supply for European flow battery manufacturers. Distribution runs through direct mill procurement channels for utility-scale developers, while thermal insulation contracts move through regional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through 18-24 month electrode certification cycles locks out unqualified competitors and secures incumbent pricing power.
For Market Incumbents: Secure long-term offtake agreements with Australian and South African vanadium redox developers before India's CEA grid-scale battery mandates accelerate import demand. Add graphitization capacity in Shandong province to capture MEE dual carbon enforcement tailwinds. Defend against pitch-based precursor substitution by investing in PAN fiber spinning backward integration. For New Entrants and Emerging Players: ISO 9001 fast-track qualification for solid oxide fuel cell bipolar plate substrates opens white-space access outside saturated battery electrode competition. Target India's Maharashtra and Gujarat port corridors where BIS certification gaps delay domestic precursor investment and developers bypass distribution for direct Chinese mill procurement. Lead with compressed rolled formats for automated stack assembly compatibility. For Investors and Strategic Acquirers: Integrated precursor-to-felt producers with captive carbon fiber spinning and existing utility-scale developer relationships represent the optimal acquisition archetype. Long-term viability hinges on energy storage deployment velocity across the next decade rather than thermal insulation replacement cycles. Watch for India's PLI scheme incentive clarifications as the inflection signal for local manufacturing investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor Production | Morgan Advanced Materials controls quality from feedstock through graphitization, reducing acrylonitrile cost volatility exposure. |
| Long-term Supply Agreement with Utility-Scale Developers | Five-year offtake contracts with Australian vanadium redox projects compress channel margins and secure batch consistency warranties. |
| Capacity Expansion in Jiangsu Processing Clusters | MEE enforcement of dual carbon goals accelerates furnace upgrades, consolidating domestic output around large-scale needle-punch lines. |
| Green Manufacturing Transition | ECHA REACH PAH restrictions elevate wastewater treatment investments at pitch-based facilities, favoring PAN-based alternatives for EU export. |
| Joint Venture with Solid Oxide Fuel Cell Stack Assemblers | CGT Carbon GmbH partnerships in Germany open electrode supply contracts outside traditional battery verticals. |
Study Parameters
The analysis maps needle-punched, extruded, woven, and taped product architectures, each validated through interviews with vanadium redox battery procurement directors, carbon fiber plant managers, aerospace tier-1 thermal protection suppliers, and industrial furnace maintenance contractors. Primary fieldwork combined with secondary validation from ECHA substance restriction filings, MEE enforcement notices, CEA grid-scale battery mandates, and customs trade data for carbon fiber precursor flows. Bottom-up demand modeling from end-use application specifications triangulates against top-down capacity assessments from Jiangsu and Shandong mill surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, application, end user, and form factor, with additional modeling across precursor source and graphitization temperature tier. CAGRs were derived from deployment trajectories in utility-scale energy storage and vacuum furnace replacement cycles. Key forecast inputs include vanadium redox stack assembly specifications and MEE dual carbon enforcement timelines.
Decision-makers should treat outputs as directional under assumptions of sustained CEA mandate implementation and stable acrylonitrile feedstock pricing; material deviation in either would warrant model refresh. Forecasts reflect these base conditions alongside semiconductor equipment insulation maintenance patterns and solid oxide fuel cell commercialization velocity. Practitioners should keep alternative scenarios live as India's PLI scheme incentive structures and ECHA REACH enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Preforms Market
Composite Materials
Biocomposites Market
Composite Materials
Isostatic Graphite Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Fiber Reinforced Composite Tapes Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Synthetic Rope Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
Wood Plastic Composite (WPC) Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Lightweight Materials Market
Composite Materials
Case Material Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Structural Core Materials Market