
 Decorative High-Pressure Laminates Market | 2026-2036
Decorative High-Pressure Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative High-Pressure Laminates Market Analysis
Southeast Asian laminate production capacity is realigning toward specialty-grade output for export markets. Greenlam Industries Limited leverages integrated resin-to-sheet manufacturing across Indian facilities to control input costs. FunderMax GmbH anchors its position through architectural-grade product lines certified for exterior cladding performance. Wilsonart LLC competes via extensive North American distribution and rapid-sample fulfillment networks.
Decorative high-pressure laminates are multi-layered sheets composed of kraft paper cores impregnated with thermosetting resins, surfaced with decorative printed papers, and fused under pressures exceeding 7 MPa at temperatures near 150°C to produce durable, chemically resistant finishes for interior surfaces. The textured product category dominates volume in furniture applications where tactile authenticity commands specification preference. Glossy and metallic finishes lead margin pools in hospitality and retail environments where visual impact drives procurement decisions. Matte surfaces sustain growth in residential countertops as consumer preferences shift toward subdued, naturalistic aesthetics.
EPA formaldehyde emission standards under TSCA Title VI constrain resin formulation choices for US-bound production, while REACH regulations in Europe govern phenol and melamine chemical registrations across the supply chain. China's GB standards for indoor decoration materials set mandatory volatile organic compound limits that manufacturers must certify through the national standards body. Stakeholders must monitor evolving carbon border adjustment mechanisms and building certification schemes that increasingly embed lifecycle assessment requirements into material specification protocols.
Market Dynamics
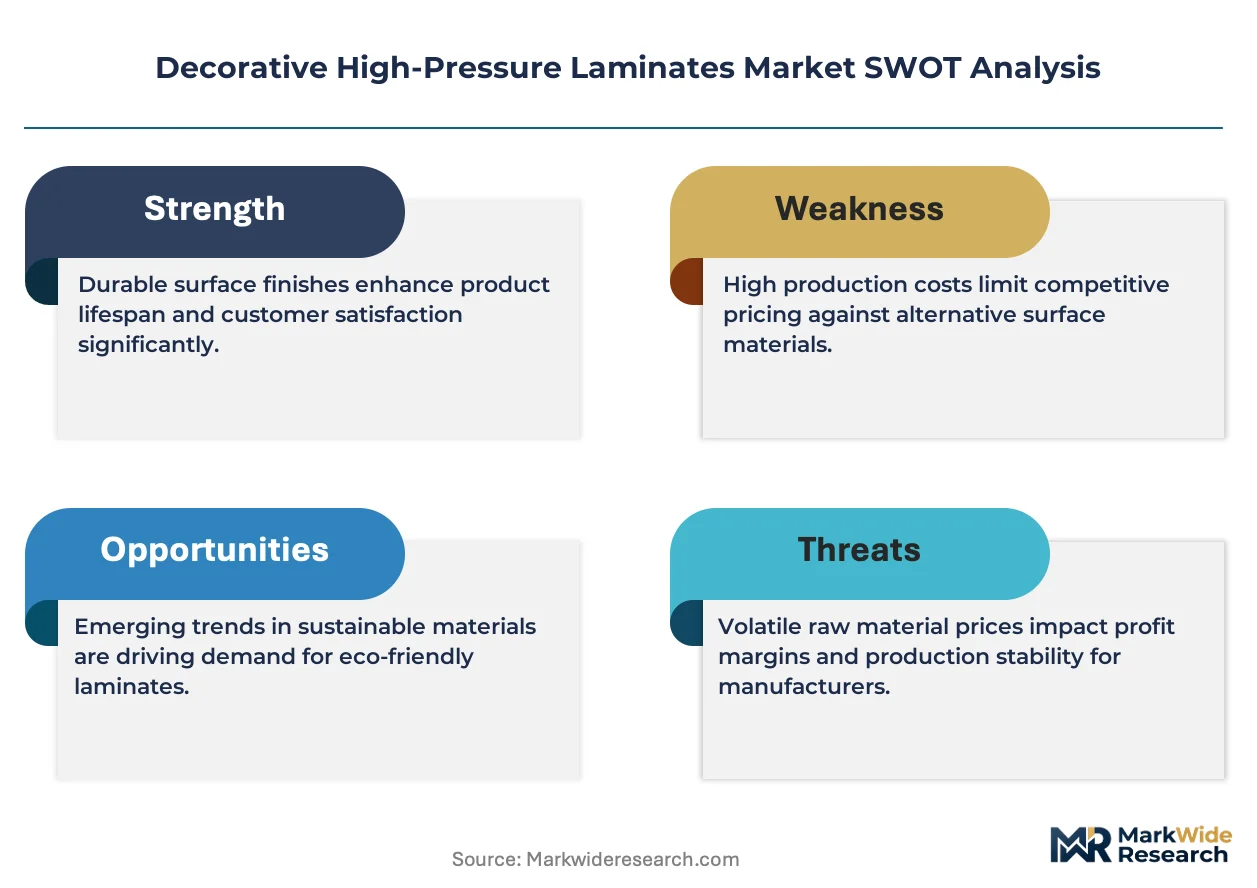
The Decorative High-Pressure Laminates Market is experiencing structural pressure from embodied carbon accounting mandates, which are forcing resin system reformulation across manufacturing footprints and reshaping competitive advantage toward low-emission chemistry capabilities.
Growth Catalysts
- EU Green Deal Carbon Reporting:Mandatory lifecycle disclosure requirements for construction materials are accelerating specification of lower-emission laminate grades in European commercial interiors.
- Hospitality Procurement Clusters:Premium hotel and resort developments across Dubai and Riyadh are consolidating surfacing material contracts, creating concentrated demand for metallic and textured finishes.
- Furniture Manufacturing Scale:Production hubs around Dongguan and Foshan are absorbing specialty-grade laminates at volumes that justify dedicated supply chain configurations.
Market Restraints
- Phenol Input Volatility:Kraft paper core impregnation depends on phenol-formaldehyde resin pricing, which fluctuates with petrochemical feedstock costs and energy tariffs.
- Resin System Concentration:Thermosetting resin production clusters in specific coastal Chinese provinces create geographic supply vulnerability for non-integrated laminate manufacturers.
- Thin-Panel Substitution:Continuous pressure laminates and thermally fused melamine papers are capturing share in cost-sensitive residential cabinetry applications.
Strategic Opportunities
- Exterior Cladding Certification:Architectural-grade laminates certified for rainscreen and facade applications command premium positioning in commercial building envelopes.
- Southeast Asian Export Pivot:Specialty-grade production realignment toward Vietnam and Indonesia addresses quality requirements in Australian and Middle Eastern import markets.
- Digital Sample-to-Specification Platforms:Rapid virtual material libraries are compressing the architect and designer selection cycle, reducing traditional distributor fulfillment delays.
Industry Challenges
- Resin Chemistry Expertise Gap:Formulation of low-formaldehyde and bio-based resin systems requires polymer science capabilities scarce in traditional laminate engineering teams.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with EPA TSCA Title VI, REACH chemical registrations, and China's GB standards extends product launch timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative High-Pressure Laminates Market |
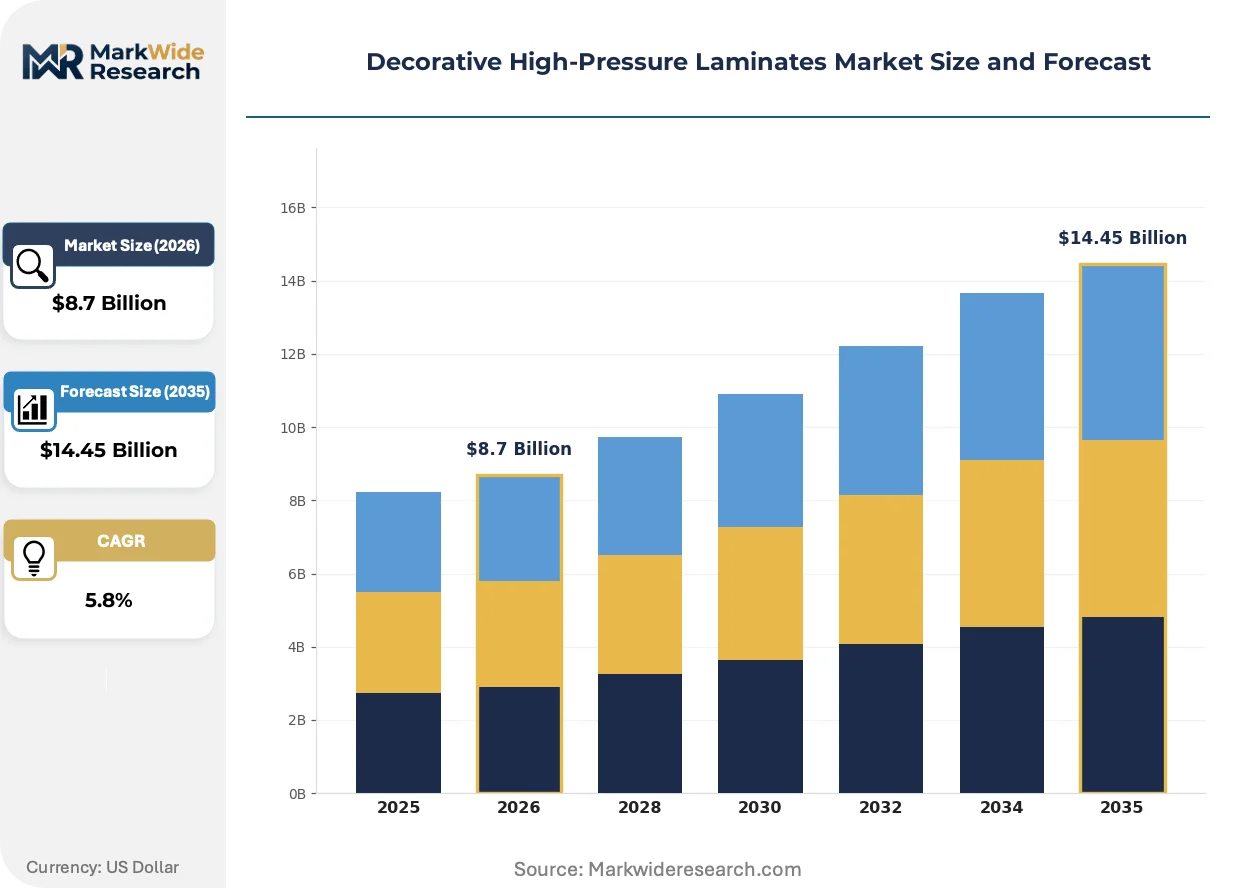
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured, Glossy, Metallic, Matte End User: Residential, Commercial, Hospitality, Retail Application: Furniture, Wall Panels, Flooring, Countertops Thickness: Standard, Thinner, Thicker, Custom |
| Companies Covered | Greenlam Industries Limited, Abet Laminati S.p.A., Formica Group, Stylam Industries Limited, Arpa Industriale S.p.A., Wilsonart LLC, FunderMax GmbH, Trespa International B.V., Kronospan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative High-Pressure Laminates Market Emerging Trajectories
Surface finishing technologies and specification workflows are undergoing parallel transformation, with digital tools compressing decision cycles while material science advances expand performance boundaries into exterior applications.
Digital printing technology for decorative paper layers is expanding into short-run custom pattern production, enabling architect-specified surface designs without minimum order constraints. Boutique hospitality projects in Milan and Singapore are adopting this capability for branded interior environments. The technology is compressing the traditional six-week sample-to-production cycle into days, reshaping competitive dynamics toward responsive manufacturing networks.
REACH regulations governing phenol and melamine chemical registrations are tightening supply chain documentation requirements across European laminate distribution channels. Manufacturers must now maintain substance volume tracking and safety data sheet interoperability across multiple regulatory frameworks. Exterior cladding product lines face the steepest compliance burden, as facade applications trigger additional construction product regulation obligations in Germany and France.
Specification behavior among commercial interior designers is rotating toward subdued, naturalistic aesthetics that favor matte surface finishes over high-gloss alternatives. Residential countertop applications are driving this preference shift, with tactile authenticity commanding premium positioning. Scandinavian and Japanese design influence is most visible in this transition, where material honesty and understated surface character dominate procurement criteria.
Decorative High-Pressure Laminates Market Segmentation
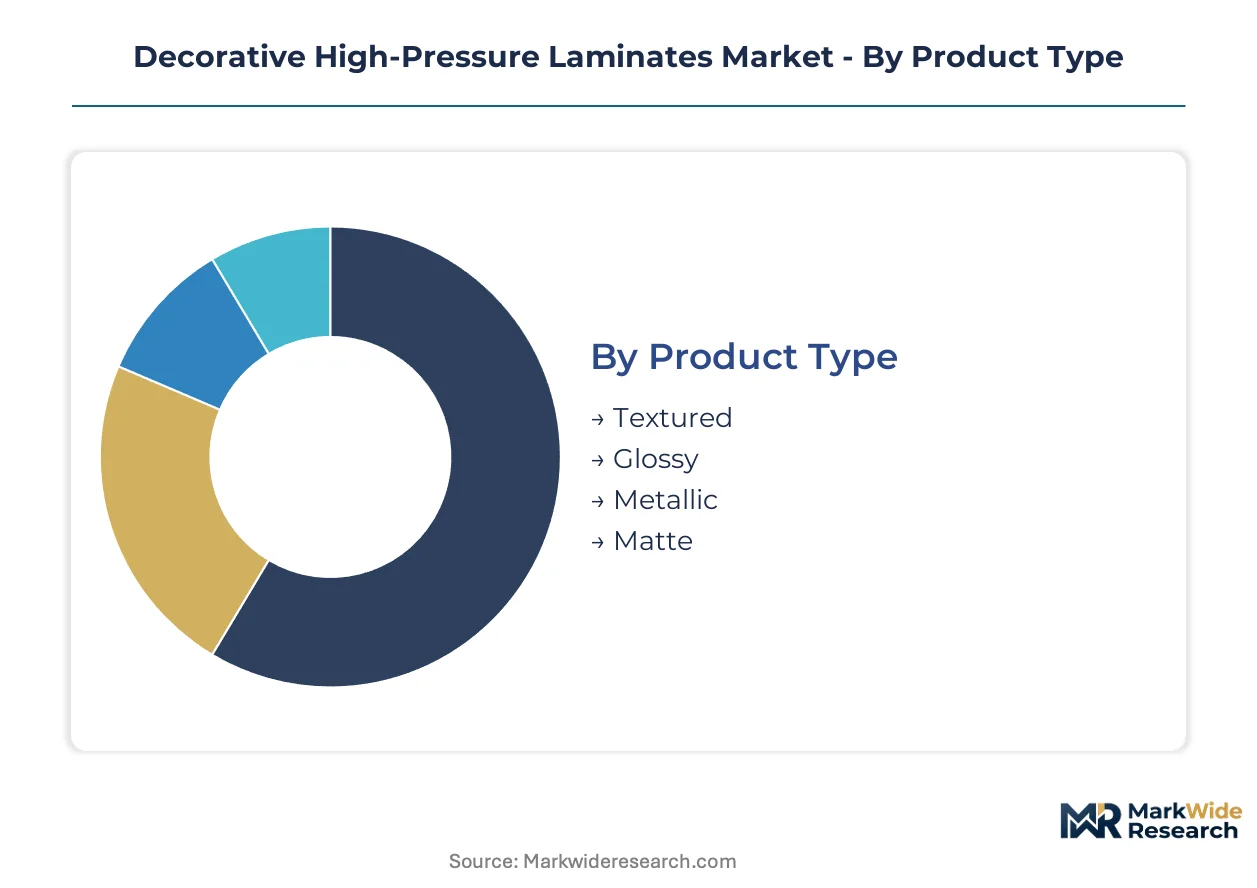
Segmentation in decorative high-pressure laminates reveals how capital deployment, resin chemistry specialization, and certification requirements concentrate competitive advantage across distinct product tiers and end-use specifications.
Product Type:
Capital intensity varies sharply across surface finish technologies, with metallization and precision texture embossing demanding specialized press configurations and decorative paper printing investments.
- Textured:Deep-embossed surface patterns replicate wood grain, stone, and fabric tactile properties through synchronized steel press plates. Furniture manufacturers in Dongguan and Foshan specify textured finishes for mid-market cabinetry where authenticity commands procurement preference. Kraft paper core density and resin saturation rates determine embossing fidelity and wear resistance.
- Glossy:High-pressure polishing after resin curing produces mirror-like surface reflectance requiring contamination-controlled production environments. Hospitality developments in Dubai and Riyadh source glossy laminates for reception desks and retail fixtures where visual impact drives specification decisions. Energy-intensive post-cure finishing elevates unit capital costs above textured alternatives.
- Metallic:Aluminum oxide or metal-vapor deposition layers integrated between decorative paper and overlay films create reflective chromatic effects. Premium hotel contracts in Milan and Singapore absorb metallic output for branded interior environments.
- Matte:Controlled surface micro-roughening reduces gloss units to sub-10 measurements, serving residential countertop preferences for subdued, naturalistic aesthetics.
Textured finishes absorb the bulk of installed capacity; metallic is expanding most quickly.
End User:
Specification authority and procurement scale diverge across customer types, with hospitality and retail consolidating contract volumes while residential demand fragments across distributor networks.
- Residential:Kitchen and bathroom renovation cycles drive replacement demand through big-box retail and specialty distributor channels. Matte and textured finishes dominate as consumer preferences shift toward Scandinavian-influenced naturalistic aesthetics.
- Commercial:Office fit-out and healthcare interior projects specify fire-rated and chemical-resistant grades through architect-led procurement. EPA TSCA Title VI compliance documentation is mandatory for US-bound commercial specifications.
- Hospitality:Hotel and resort developers consolidate surfacing contracts across property portfolios, creating concentrated demand for premium metallic and custom-printed finishes. Procurement clusters in Dubai and Riyadh anchor Middle Eastern volume.
- Retail:Fixture manufacturers for fashion and electronics brands prioritize glossy and metallic surfaces for brand-aligned visual merchandising. Rapid sample-to-production cycles compress traditional six-week lead times.
Commercial end users represent the largest addressable base; hospitality procurement is climbing the fastest.
Application:
Performance certification requirements and installation labor intensity create divergent margin structures across surface applications, with vertical installations demanding lighter panel weights and specialized adhesives.
- Furniture:Cabinetry, shelving, and casegood surfacing consumes the highest laminate volumes through automated edge-banding and membrane pressing operations. Chinese manufacturing clusters around Dongguan absorb specialty-grade output at scale justifying dedicated supply chain configurations.
- Wall Panels:Vertical surfacing applications require lighter grammage kraft paper cores to reduce installation labor and adhesive consumption. Exterior cladding certifications for rainscreen applications command premium positioning in commercial building envelopes.
- Flooring:Abrasion-resistant overlays with enhanced melamine content withstand foot traffic wear in retail and hospitality environments. REACH chemical registration documentation extends product launch timelines for European distribution.
- Countertops:Post-formed and self-edging applications demand thermoformable grades with controlled resin flow characteristics. Residential preference shifts toward matte finishes reshape specification behavior among commercial interior designers.
Furniture applications dominate volume absorption; wall panels are gaining share fastest.
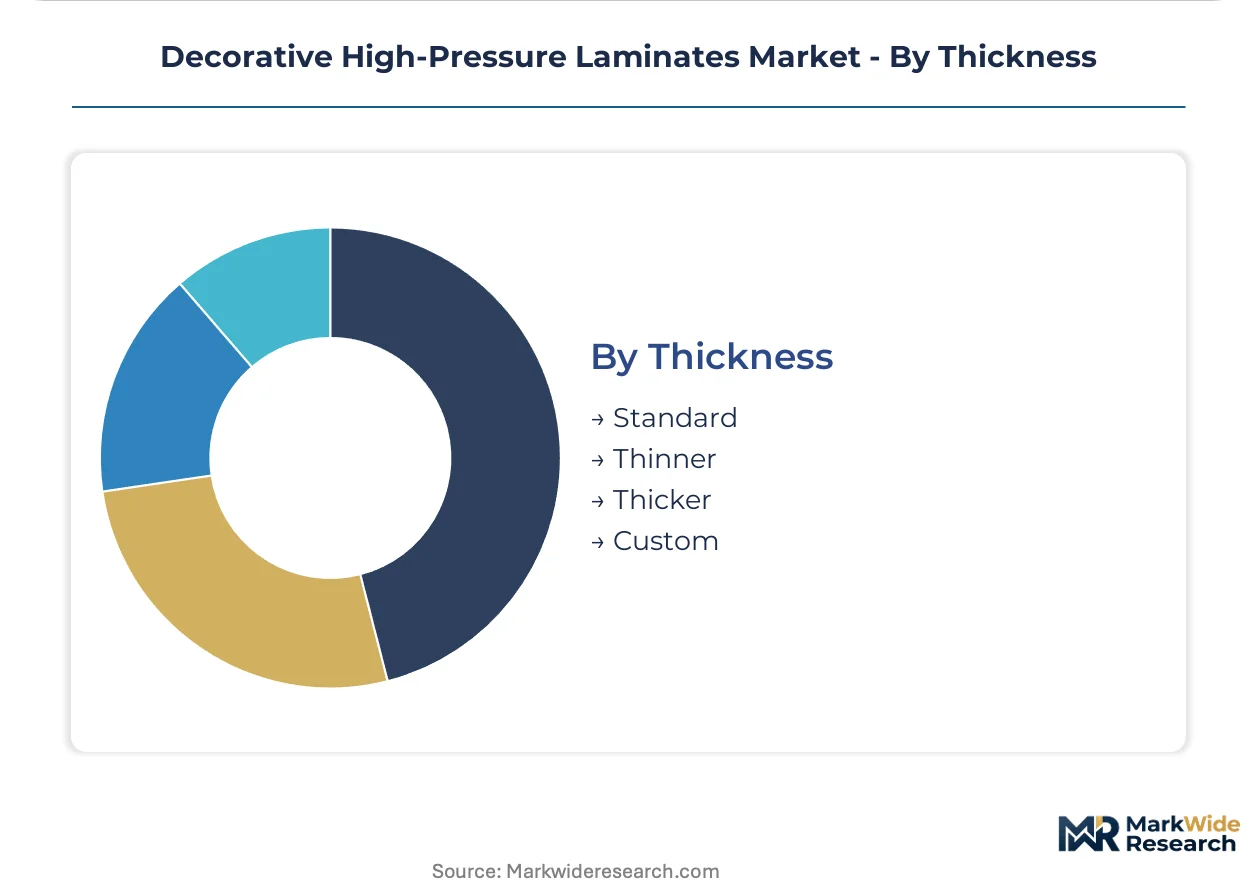
Thickness:
Press utilization rates and raw material yields vary with panel caliper, with thinner gauges enabling higher throughput per machine hour but requiring tighter process control.
- Standard:0.7-1.0mm caliper serves general-purpose furniture and interior surfacing through balanced durability and formability. Standard thickness commands the widest specification compatibility across applications.
- Thinner:Sub-0.6mm gauges reduce material costs and shipping weight for high-volume residential cabinetry. Continuous pressure laminates and thermally fused melamine papers capture share in cost-sensitive thin-panel applications.
- Thicker:1.5-2.0mm panels provide post-forming depth for countertop edges and heavy-duty commercial surfaces. Thicker grades require extended press cycle times and higher resin loading, elevating unit production costs.
- Custom:Non-standard calipers serve specialized industrial and marine applications with bespoke performance certifications. Custom thickness production disrupts press scheduling and requires minimum order thresholds.
Standard thickness commands the majority of press capacity; thinner gauges are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phenol-formaldehyde resin production clusters in coastal Chinese provinces anchor raw-material availability for laminate manufacturing across Asia-Pacific, while European and Middle Eastern demand centers pull finished goods through diverging regulatory and specification channels.
China
Furniture manufacturing hubs in Dongguan and Foshan absorb specialty-grade laminates at volumes justifying dedicated supply chain configurations. GB standards for indoor decoration materials mandate volatile organic compound limits certified through the national standards body. Thermosetting resin production concentrates in Jiangsu and Zhejiang provinces, creating geographic supply vulnerability for non-integrated manufacturers.
United States
Commercial interior projects specify fire-rated and chemical-resistant grades through architect-led procurement channels concentrated in Texas and California metro areas. EPA formaldehyde emission standards under TSCA Title VI constrain resin formulation choices for US-bound production. Wilsonart LLC leverages extensive North American distribution networks from Tennessee operations.
Germany
Architectural-grade product lines certified for exterior cladding performance anchor premium positioning in commercial building envelopes across Berlin and Munich developments. REACH regulations govern phenol and melamine chemical registrations, tightening supply chain documentation requirements. FunderMax GmbH maintains production capabilities serving rainscreen and facade applications.
United Arab Emirates
Hospitality interiors in Dubai and Riyadh expand procurement of premium surfacing materials with metallic and textured finishes for hotel and resort developments. MOHAP oversees construction product safety frameworks influencing material import protocols. Specification clusters concentrate around Dubai Design District and Riyadh's King Abdullah Financial District projects.
India
Greenlam Industries Limited leverages integrated resin-to-sheet manufacturing across Indian facilities to control input costs and serve domestic furniture production. BIS certification requirements for decorative laminates establish quality benchmarks for commercial and residential applications. Manufacturing concentrates in Gujarat and Haryana with distribution reaching Mumbai and Delhi-NCR construction markets.
Decorative High-Pressure Laminates Market Vendor Landscape
Global majors compete with regional champions across certification capabilities and distribution density, producing a tiered structure where integrated resin-to-sheet manufacturers hold cost advantages over assembly-focused competitors. The vendor base spans European architectural-grade specialists, Asian volume producers, and North American distribution-heavy operators. Three archetypes dominate: vertically integrated chemical-to-sheet manufacturers, design-forward architectural specialists, and scale-driven distributors with rapid-sample fulfillment networks. Competitive moves concentrate on exterior cladding certification acquisition and Southeast Asian capacity realignment toward export-quality output.
Among European architectural specialists, FunderMax GmbH and Arpa Industriale S.p.A. exemplify the premium-tier positioning built around facade-performance certifications and specification-grade product lines. Greenlam Industries Limited and Stylam Industries Limited represent the integrated-manufacturing archetype with captive resin production capabilities. Wilsonart LLC occupies a position anchored in North American distribution density and rapid-sample fulfillment infrastructure. These three groupings illustrate how competitive advantage fragments across chemistry control, specification authority, and logistics responsiveness rather than concentrating in any single capability dimension.
| Leading Market Players |
|---|
| Greenlam Industries Limited |
| Abet Laminati S.p.A. |
| Formica Group |
| Stylam Industries Limited |
| Arpa Industriale S.p.A. |
| Wilsonart LLC |
| FunderMax GmbH |
| Trespa International B.V. |
| Kronospan Holdings |
| Others |
Supply Flow & Price Mechanics
Hospitality procurement clusters in Dubai and Riyadh anchor premium-tier pricing through consolidated contract volumes for metallic and textured finishes, while furniture manufacturers in Dongguan and Foshan negotiate standard-grade laminates on spot-market terms. This buyer-archetype divergence produces bifurcated pricing power: brand-integrated suppliers command specification premiums, whereas commodity-grade producers face margin compression from thin-panel substitutes.
Pricing Analysis
Warranty-backed performance guarantees and exterior cladding certification documentation are unbundled from base product pricing, creating transparent upgrade paths for architectural-grade specifications. Three-tier pricing structure across premium, standard, and economy levels separates certified rainscreen performers from general-purpose furniture grades. Cost compression in standard-thickness residential cabinetry intensifies because continuous pressure laminates capture share at 15-20% unit cost advantage. Furniture manufacturers in Chinese clusters exhibit highest price sensitivity; hospitality developers in Middle Eastern procurement hubs demonstrate lowest.
Supply Chain Analysis
Skilled press operator availability constrains capacity expansion in Jiangsu and Zhejiang provinces, where thermosetting resin production concentrates for decorative laminate manufacturing. Kraft paper core supply draws from Scandinavian pulp mills, phenol-formaldehyde resin feeds from petrochemical complexes in coastal China, and decorative printed paper originates from specialized Italian and German converters. Single-source vulnerability runs through Jiangsu resin clusters, where environmental compliance shutdowns disrupt non-integrated laminate producers. Distribution runs through regional distributor networks in North America, direct mill relationships in European project channels, and consolidated procurement offices in Middle Eastern hospitality developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH chemical registration requirements and EPA TSCA Title VI formaldehyde standards erect barrier-to-entry moats favoring incumbent players with established certification infrastructure and documented supply chain traceability.
For Market Incumbents: Hedge phenol-input volatility through backward integration into captive resin production or long-term offtake agreements with Jiangsu and Zhejiang chemical complexes. Accelerate exterior cladding certification acquisition for rainscreen applications before European building codes tighten lifecycle disclosure requirements. Defend specification authority against thin-panel substitutes by emphasizing fire-rated performance documentation in commercial architect channels.
For New Entrants and Emerging Players: EU Green Deal carbon reporting requirements in European member states open a window for low-emission resin system specialists to capture specification share from legacy phenol-formaldehyde producers. Target digital sample-to-specification platform integration as the most penetrable white-space, compressing traditional six-week fulfillment cycles into responsive architect-facing interfaces. Pursue boutique hospitality projects in Milan and Singapore as initial reference customers for custom-printed short-run capabilities.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated manufacturers with captive resin-to-sheet capabilities and established multi-jurisdiction certification portfolios. Long-term viability hinges on polymer science expertise for bio-based and low-formaldehyde formulation transitions. Watch Southeast Asian capacity realignment toward Vietnam and Indonesia as the signal for export-quality production cost structures achieving parity with Chinese manufacturing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Exterior Cladding Certification | Architectural-grade rainscreen approval unlocks premium positioning in German and French commercial building envelopes. |
| Low-Emission Resin Reformulation | Bio-based phenol alternatives align with EU Green Deal embodied carbon mandates reshaping specification criteria. |
| Southeast Asian Capacity Realignment | Vietnam and Indonesia production addresses Australian and Middle Eastern import quality requirements. |
| Digital Sample Platform Investment | Virtual material libraries compress architect selection cycles and reduce distributor fulfillment infrastructure. |
| Backward Integration into Resin | In-house phenol-formaldehyde production insulates margin structures from petrochemical feedstock volatility. |
Methodological Framework
Independent corroboration across laminate plant managers, furniture OEM procurement leads, distribution channel partners, and architectural specification consultants underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC 10-K filings of listed building materials companies, and national standards body certification registries. Bottom-up production capacity assessments and top-down demand segmentation triangulate volume estimates across the analysis window.
Comparable historical periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-regulatory-shift adoption curves. The modeling framework segments by surface finish technology, end-use vertical, application type, and thickness grade, with regional production hub economics as an additional dimension. CAGRs derive from production capacity expansion schedules, substitution elasticity estimates for thin-panel alternatives, and hospitality construction pipeline tracking across Dubai, Riyadh, Milan, and Singapore.
Caveats apply where resin chemistry breakthroughs, carbon border adjustment mechanism implementations, or abrupt phenol feedstock price spikes could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency, certification timeline stability, and hospitality construction cycle continuity. A small set of named triggers—REACH substance restriction updates, Chinese environmental compliance actions in Jiangsu province, and Middle Eastern procurement consolidation patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Epoxy Composite Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
FRP Reactor Market
Composite Materials
High Performance Composites Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Pultrusion Market
Composite Materials
Composites Distributor Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Scrim Reinforced Films Market