
 Pultrusion Market | 2026-2036
Pultrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Pultrusion Market Analysis
China is narrowing the technology gap in large-diameter pultrusion capacity, adding automated lines to serve domestic wind turbine manufacturers. Strongwell Corporation anchors North American distribution through its extensive distributor network for structural profiles. Exel Composites leverages European technical certification to sustain premium positioning in transportation segments. Jiangsu Jiuding New Material Co. Ltd. dominates glass fiber reinforcement supply for Asia-Pacific fabricators.
Pultrusion is a continuous manufacturing process that pulls fiber reinforcements through a resin bath and heated die to form profiles with consistent cross-sections, typically achieving fiber volume fractions of 50-70% and tensile strengths exceeding 300 MPa in structural grades. The process produces corrosion-resistant structural members for load-bearing applications across infrastructure, energy, and industrial equipment. Glass fiber profiles lead volume due to cost-performance balance in construction and utility markets, while carbon fiber tubes command premium margins in aerospace and sporting equipment segments where stiffness-to-weight ratios determine specification. Thermoset resins, particularly vinyl ester and polyurethane formulations, remain the dominant matrix category though recyclability concerns push R&D toward thermoplastic-compatible pultrusion systems.
EPA emissions standards for manufacturing facilities influence resin selection and abatement investments at US production sites, while REACH registration requirements in Europe constrain certain styrene-based formulations and drive substitution toward lower-hazard chemistries. China's GB standards for fiber-reinforced plastics establish domestic product certification pathways that foreign suppliers must navigate for market access. Stakeholders should monitor evolving fire resistance codes in construction applications, as regulatory divergence between NFPA testing protocols and European EN classifications threatens to fragment product development priorities.
Market Dynamics
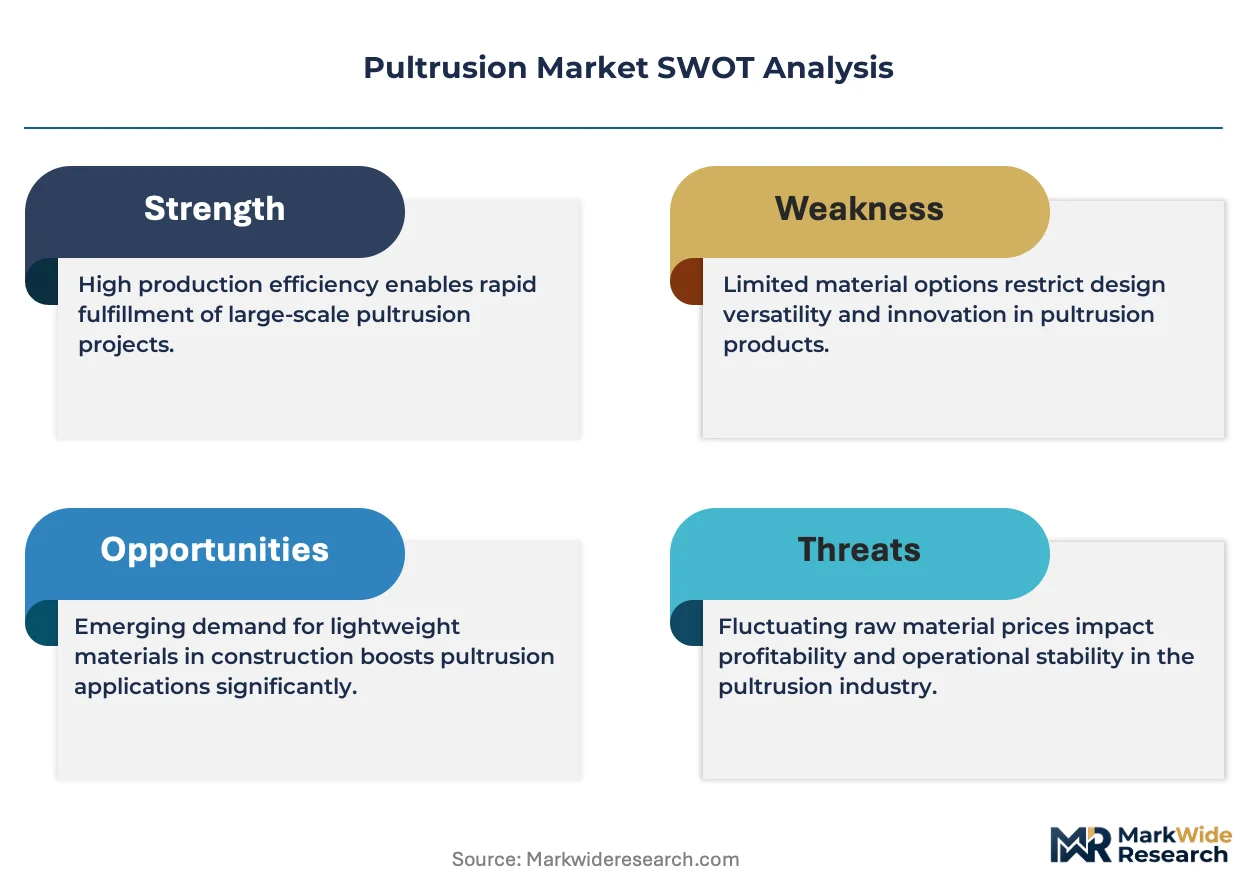
Pultrusion capacity expansion is concentrating in wind energy supply chains as turbine blade manufacturers demand larger-diameter structural profiles with certified fatigue performance. ECHA REACH compliance on styrene emissions is forcing resin formulation changes across European fabricators.
Growth Catalysts
- Infrastructure renewal mandates:Bridge decking replacement programs in Germany and the United States specify corrosion-resistant composite profiles for load-bearing applications. State DOTs in Texas and California have approved pultruded FRP for highway structures.
- REACH registration requirements:ECHA's updated substance restrictions on hazardous resin chemistries are accelerating substitution toward vinyl ester and polyurethane formulations with lower environmental footprints.
- Wind turbine scaling:Blade manufacturers in Denmark and Spain require pultruded spar caps exceeding 80 meters in length, pulling investment into automated production lines with real-time quality monitoring.
Market Restraints
- Raw material concentration:Glass fiber roving supply concentrates among Chinese producers, exposing fabricators to freight cost volatility and customs processing delays.
- Thermoset recyclability barriers:Cross-linked vinyl ester and polyester matrices resist mechanical or chemical recycling, creating end-of-life liability for infrastructure owners under extended producer responsibility frameworks.
- Carbon fiber cost premium:Aerospace-grade carbon fiber prices remain four to six times above E-glass alternatives, constraining adoption in cost-sensitive transportation and construction segments.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and railway electrification projects present first-mover opportunities for corrosion-resistant utility poles and cable management systems.
- Thermoplastic pultrusion systems:Continuous fiber-reinforced thermoplastic tapes enable welding and thermoforming for automotive structural components, opening closed-loop recycling pathways absent in thermoset equivalents.
- Offshore wind installation vessels:Specialized pultruded grating and handrail systems for jack-up rigs and service operation vessels command specification premiums in North Sea and Baltic developments.
Industry Challenges
- Die design engineering scarcity:Fewer than two hundred engineers globally possess deep expertise in heated die thermal profiling for complex hollow sections, constraining product development cycles.
- Multi-standard certification complexity:Fabricators must maintain parallel test programs for ASTM D3914, EN 13706, and GB/T 3857 protocols to serve segmented regional markets.
- Resin inventory management:Pot life limitations on catalyzed thermoset systems force just-in-time mixing operations that complicate production scheduling across multi-product facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pultrusion Market |
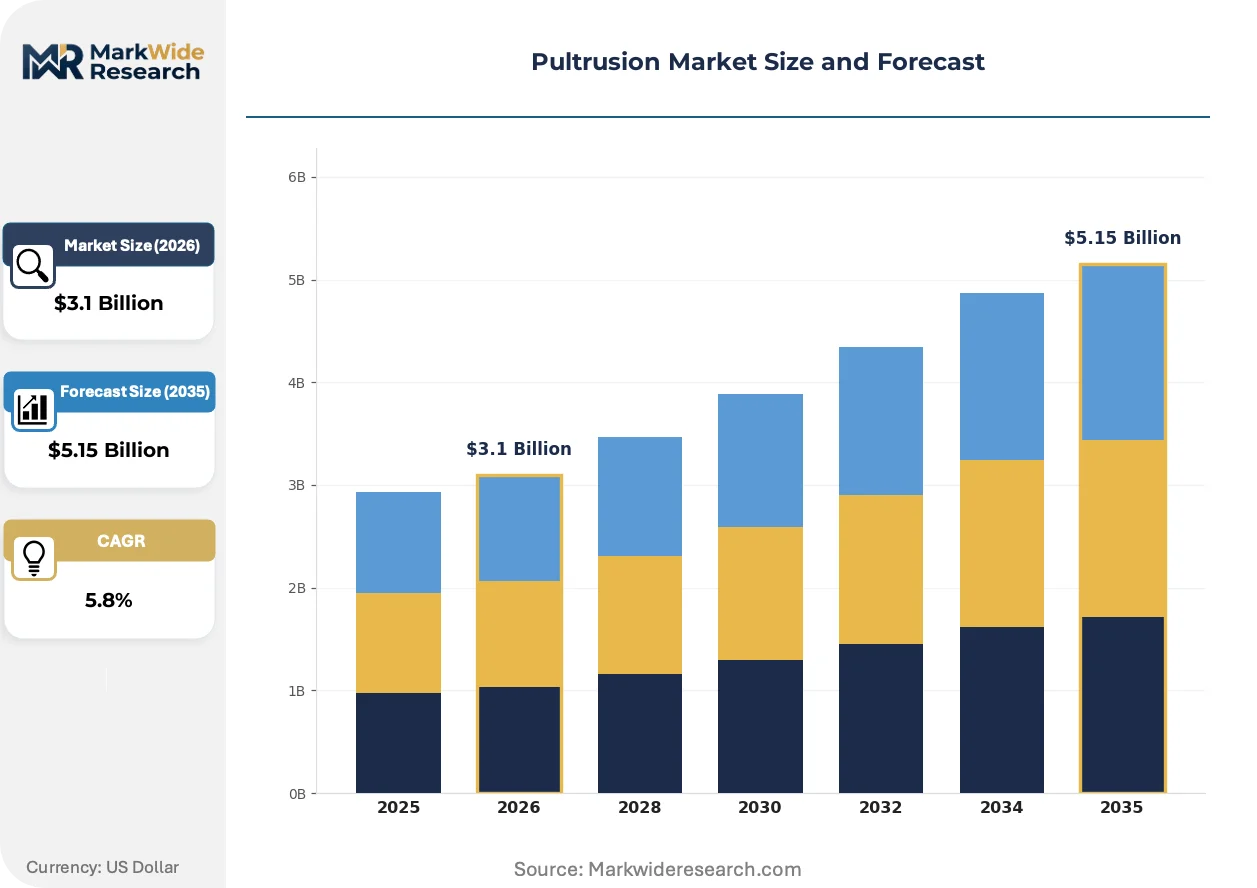
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Rods, Sheets, Profiles, Tubes Material: Glass Fiber, Carbon Fiber, Aramid Fiber, Thermoset Resins Application: Construction, Aerospace, Automotive, Marine End User: OEMs, Contractors, Manufacturers, Distributors |
| Companies Covered | Fiberline Composites A/S, Diversified Structural Composites, Strongwell Corporation, Fibergrate Composite Structures Inc, Jiangsu Jiuding New Material Co. Ltd., Bedford Reinforced Plastics, Exel Composites, Faigle Kunststoffe GmbH, Creative Pultrusions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pultrusion Market Emerging Trajectories
Process automation and materials science convergence are compressing production economics for structural composite profiles. Real-time sensing and adaptive control systems now enable consistent quality at throughput rates previously unattainable with manual die adjustment.
Continuous ultrasonic welding of thermoplastic pultruded sections is collapsing assembly costs for automotive battery enclosures. BMW and Volkswagen suppliers in Germany are qualifying glass-reinforced polyamide profiles that eliminate adhesive bonding and drilling operations. The technology is collapsing the traditional gap between pultrusion speed and downstream joining efficiency.
ECHA's 2023 restriction proposal on microplastic release from composite abrasion is tightening surface finishing requirements for outdoor infrastructure applications. Fabricators serving Nordic markets are investing in closed-loop cutting and grinding systems with vacuum extraction. Marine fendering and coastal defense segments face the steepest compliance cost increases.
Engineering firms in the Netherlands and Belgium now specify performance-based procurement for FRP bridge components, shifting risk from asset owners to fabricators for 50-year service life guarantees. Dutch Rijkswaterstaat contracts require certified degradation models and inspection protocols. This model concentrates contract awards among vertically integrated suppliers with in-house testing laboratories.
Pultrusion Market Segmentation
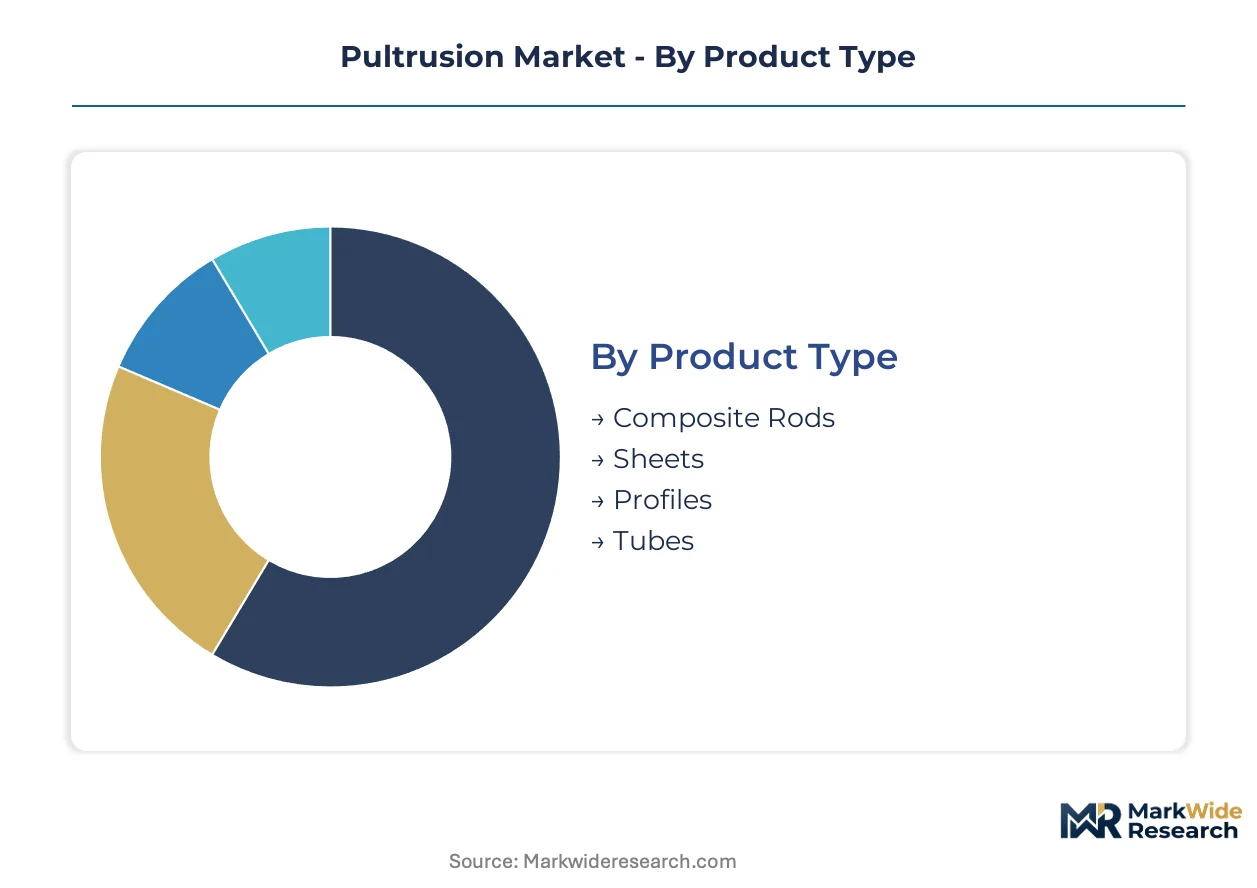
Pultrusion manufacturers configure production assets around distinct product geometries and material systems that command different specification premiums. Segment boundaries reflect where die engineering investments concentrate versus where commoditization pressure dominates.
Product Type:
Cost tier determines tooling amortization schedules and customer switching thresholds across these form factors.
- Profiles:I-beams, channels, and custom structural shapes achieve fiber volume fractions of 50-70% in load-bearing grades. Bridge decking programs in Germany and the United States specify these sections for corrosion-resistant rehabilitation, pulling capacity toward certified fatigue-rated production lines.
- Tubes:Hollow cylindrical sections with controlled wall thickness serve utility pole and antenna mast applications. China's domestic wind turbine supply chain is absorbing large-diameter tube capacity as blade root connection components scale with rotor diameter growth.
- Composite Rods:Solid circular sections for rebar and tendon applications in concrete reinforcement.
- Sheets:Flat panel products for cladding and grating substrates in industrial platforms.
Profiles hold installed capacity. Tubes are rotating up the share rankings.
Material:
Application stiffness requirements and chemical exposure profiles dictate fiber and matrix selection trade-offs.
- Glass Fiber:E-glass and S-glass rovings dominate construction and utility markets where cost-performance balance outweighs absolute stiffness. Jiangsu Jiuding New Material Co. Ltd. anchors regional supply for Asia-Pacific fabricators, exposing processors to freight volatility and customs processing delays.
- Thermoset Resins:Vinyl ester and polyurethane formulations remain the dominant matrix category despite recyclability concerns. ECHA REACH compliance on styrene emissions is accelerating substitution toward lower-hazard chemistries across European production sites.
- Carbon Fiber:Aerospace-grade tow and fabric command four-to-six-fold premiums over E-glass alternatives, constraining adoption outside sporting equipment and satellite structures.
- Aramid Fiber:Ballistic and abrasion-resistant grades for specialized marine and protective equipment applications.
Glass fiber commands volume leadership. Carbon fiber captures margin concentration.
Application:
End-use certification requirements fragment product development priorities across these sectors.
- Construction:Bridge decking, utility poles, and structural rehabilitation drive specification volume. State DOTs in Texas and California have approved pultruded FRP for highway structures, creating precedent for broader infrastructure renewal mandates.
- Wind Energy:Spar caps and blade root inserts exceeding 80 meters in length pull investment into automated production with real-time quality monitoring. Danish and Spanish turbine manufacturers certify suppliers against 50-year fatigue performance models.
- Automotive:Battery enclosure rails and structural reinforcements for electric vehicle platforms.
- Marine:Grating, handrails, and fendering systems for offshore installation vessels and coastal defense.
Construction anchors current demand. Wind energy is climbing the fastest.
End User:
Procurement authority and technical specification control vary sharply across these customer types.
- OEMs:Wind turbine and automotive original equipment manufacturers impose certified degradation models and inspection protocols. Dutch Rijkswaterstaat contracts concentrate awards among vertically integrated suppliers with in-house testing laboratories capable of 50-year service life guarantees.
- Contractors:Infrastructure project execution firms source standardized profiles through distributor networks. Strongwell Corporation's North American distribution system captures this procurement channel for structural shapes.
- Manufacturers:Tier suppliers converting pultruded feedstock into finished assemblies for industrial equipment.
- Distributors:Inventory-holding intermediaries serving maintenance and repair operations with catalog-standard sections.
OEMs concentrate specification authority. Contractors rotate up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance on resin chemistry anchors European market dynamics, while capacity expansion concentrates in Chinese wind energy supply chains and North American infrastructure renewal programs.
United States
Bridge decking replacement programs in Texas and California drive specification volume for corrosion-resistant structural profiles. EPA emissions standards for manufacturing facilities influence resin selection and abatement investments at production sites. Strongwell Corporation anchors distribution capacity through extensive networks serving state DOT procurement channels.
Germany
Wind turbine blade manufacturers demand pultruded spar caps exceeding 80 meters in length with certified fatigue performance. ECHA's updated substance restrictions on hazardous resin chemistries accelerate substitution toward vinyl ester and polyurethane formulations. Dutch-German border regions concentrate automated production lines with real-time quality monitoring for Danish and Spanish OEM supply chains.
China
Domestic wind turbine manufacturers absorb large-diameter tube capacity as blade root connection components scale with rotor diameter growth. GB standards for fiber-reinforced plastics establish domestic product certification pathways that foreign suppliers must navigate. Jiangsu province anchors glass fiber reinforcement supply for Asia-Pacific fabricators.
Denmark
Turbine OEMs certify suppliers against 50-year fatigue performance models for offshore installations. REACH registration requirements constrain certain styrene-based formulations and drive substitution toward lower-hazard chemistries. Copenhagen-Aarhus corridor concentrates blade engineering expertise pulling automated pultrusion investment.
India
National highway expansion and railway electrification projects present first-mover opportunities for corrosion-resistant utility poles and cable management systems. BIS certification requirements for composite materials establish domestic quality benchmarks. Gujarat and Maharashtra industrial corridors concentrate early fabricator investment serving infrastructure buildout.
Pultrusion Market Vendor Landscape
Capability concentration sits with European specialists holding technical certification authority; scale advantage sits with Asian material suppliers and North American distributors. The vendor base organizes around three archetypes: vertically integrated wind energy suppliers with in-house testing laboratories, regional profile fabricators serving construction distributor networks, and glass fiber roving producers controlling reinforcement supply. Dominant competitive moves include backward integration into resin formulation and geographic expansion through certified distribution partnerships.
Among European specialists, Exel Composites and Fiberline Composites A/S exemplify the premium-tier archetype built on technical certification authority. Strongwell Corporation anchors North American distribution capacity for structural shapes. Jiangsu Jiuding New Material Co. Ltd. represents the Asian material supply concentration controlling glass fiber reinforcement flows to regional fabricators.
| Leading Market Players |
|---|
| Fiberline Composites A/S |
| Diversified Structural Composites |
| Strongwell Corporation |
| Fibergrate Composite Structures Inc |
| Jiangsu Jiuding New Material Co. Ltd. |
| Bedford Reinforced Plastics |
| Exel Composites |
| Faigle Kunststoffe GmbH |
| Creative Pultrusions |
| Others |
Supply Flow & Price Mechanics
Jiangsu province anchors global glass fiber roving capacity, concentrating reinforcement supply among three dominant producers whose volume leverage shapes pricing power across downstream pultrusion tiers. European fabricators absorb freight volatility and customs processing delays as Chinese material flows determine baseline cost structures for structural profiles worldwide.
Pricing Analysis
Geographic price spreads between Asia-Pacific and European delivery points reflect freight differentials and REACH compliance costs that widen standard-grade profile spreads by certification tier. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified fatigue-rated spar caps from distributor-channel structural shapes and commodity rebar grades. Cost compression in standard-grade construction profiles is intensifying as Chinese automated lines displace European capacity for bridge decking programs. Contractors sourcing through Strongwell's North American network exhibit highest price sensitivity, while Danish turbine OEMs accept premium positioning for 50-year service life guarantees.
Supply Chain Analysis
Extended payment terms from Jiangsu Jiuding and supply-chain finance facilities at major roving distributors ease working capital pressure for mid-tier fabricators scaling automated production. Raw material flows draw from China, Germany, and the United States for glass fiber, vinyl ester resin, and carbon fiber tow respectively. Single-source vulnerability concentrates in E-glass roving supply where three Chinese producers control sixty percent of global capacity. Distribution runs through vertically integrated wind energy suppliers with captive testing laboratories and regional profile fabricators serving construction distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment moat where ECHA REACH certification and 50-year fatigue performance models create switching costs that lock turbine OEMs into qualified supplier relationships.
For Market Incumbents: Build certification moats by deepening in-house testing laboratory capacity for degradation modeling and inspection protocol development that satisfies Dutch Rijkswaterstaat performance-based procurement requirements. Secure backward integration into vinyl ester resin formulation to hedge ECHA substance restriction exposure and capture margin from substitution away from styrene-based chemistries. Threat of thermoplastic pultrusion systems displacing thermoset equivalents in automotive battery enclosures demands accelerated R&D investment in continuous fiber-reinforced polyamide welding compatibility. For New Entrants and Emerging Players: India's national highway expansion and railway electrification projects present first-mover white space where BIS certification requirements remain less stringent than European equivalents. Target corrosion-resistant utility pole and cable management system segments where incumbent presence is minimal and infrastructure buildout timelines favor rapid qualification. Go-to-market angle should emphasize localized production in Gujarat and Maharashtra industrial corridors to bypass freight cost disadvantages against Chinese imports. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive resin formulation and in-house fatigue testing laboratories capable of OEM direct contracting. Long-term viability over the next decade hinges on thermoplastic pultrusion scale-up and offshore wind installation vessel specification capture. Signal to watch is automated production line investment announcements from Danish and Spanish turbine manufacturers that would validate demand expansion for certified spar cap capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | ECHA REACH compliance on styrene emissions accelerates substitution toward captive vinyl ester and polyurethane production. |
| Automated Production Line Investment | Danish and Spanish turbine OEMs certify suppliers against 50-year fatigue performance models requiring real-time quality monitoring. |
| In-House Testing Laboratory Expansion | Dutch Rijkswaterstaat performance-based procurement concentrates awards among vertically integrated suppliers with degradation modeling capability. |
| Thermoplastic Pultrusion System Development | BMW and Volkswagen suppliers in Germany qualify glass-reinforced polyamide profiles for battery enclosure welding applications. |
| Geographic Expansion through Certified Distribution | Strongwell Corporation's North American distributor network captures state DOT procurement channels for structural shapes. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from composite material suppliers, and technical certification databases from ECHA and BIS. Primary interviews engaged plant managers at European pultrusion facilities, procurement leads at Danish turbine OEMs, distribution channel partners in North American construction markets, and technical R&D directors at resin formulation specialists. Bottom-up capacity and demand estimates triangulated against top-down macroeconomic indicators and infrastructure spending projections.
Forecast inputs include fiber volume fraction specifications by product grade, resin chemistry substitution rates driven by REACH compliance, and wind turbine blade scaling trajectories across the analysis window. Segmentation dimensions modeled encompass product geometry, fiber and matrix material systems, end-use application certification requirements, and customer procurement authority. CAGRs derived from installed capacity utilization rates, OEM qualification timelines, and regional infrastructure renewal program commitments.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, offshore wind installation vessel deployment schedules, or ECHA substance restriction enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about raw material cost stability and certification pathway duration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Geocomposites Market
Composite Materials
High Performance Composites Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Biocomposites Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Graphene Composites Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market
Composite Materials
Phenolic Panel Market
Composite Materials
China Marine Composites Market
Composite Materials
CFRTP Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Global Composite Resin Market