
 Flexible Cables Market | 2026-2036
Flexible Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Cables Market Foresight
CE marking under the EU Construction Products Regulation is reorganizing competitive entry in European flexible cable supply. Prysmian Group leverages integrated compound-to-cable manufacturing across Italian and Dutch facilities. Nexans sustains technology leadership in subsea dynamic power umbilicals through dedicated R&D centers in Norway. Sumitomo Electric Industries anchors Asian supply through captive copper refining and specialized polymer compounding operations in Japan.
Flexible cables are stranded conductor assemblies with elastomeric or thermoplastic insulation engineered to withstand repeated bending radii below five times outer diameter, serving critical functions in motion-intensive machinery and portable power distribution. Copper conductor segments dominate value capture due to conductivity requirements in precision motion systems, while optical fiber variants are expanding fastest in robotic sensing harnesses where electromagnetic immunity is mandatory. Power cables retain the largest volume share across utilities and heavy manufacturing, though data transmission cables command premium positioning in aerospace system retrofits.
FDA electrical safety standards for medical equipment cabling, FCC emissions rules governing shielded flex assemblies in telecommunications, and EU RoHS substance restrictions on insulation additives collectively elevate compliance costs for non-specialized manufacturers. ECHA REACH candidate list updates on phthalate plasticizers are forcing reformulation timelines across European supply chains. Stakeholders must monitor evolving national building codes for fire-resistant flexible cable mandates before committing capacity expansion decisions.
Market Dynamics
REACH candidate list updates on phthalate plasticizers are forcing compound reformulation across European supply chains, while EV charging infrastructure procurement is accelerating demand for high-cycle flex assemblies.
Growth Catalysts
- EV Charging Infrastructure:Electric vehicle manufacturers are scaling procurement of high-flexibility charging cables capable of withstanding thousands of insertion cycles. This demand concentrates in Germany's industrial automation corridor.
- REACH Compliance:ECHA's tightening restrictions on halogen-containing insulation materials are mandating halogen-free compound adoption across European flexible cable supply.
- Robotic Sensing Harnesses:Industrial automation integrators are specifying optical fiber flex variants for electromagnetic immunity in precision motion systems.
Market Restraints
- Copper Price Volatility:Conductor cost fluctuations in LME-traded copper create margin compression for manufacturers lacking backward integration into metal supply.
- Specialized Polymer Concentration:High-performance elastomer compounding capabilities concentrate in Japanese and German chemical suppliers, creating single-source dependencies.
- Subsea Umbilical Technical Limits:Dynamic power cable fatigue life in deepwater applications remains constrained by polymer creep under combined tensile and torsional loading.
Strategic Opportunities
- India Manufacturing:Production capacity expansion under India's PLI scheme for electronics manufacturing targets cable harness localization for automotive and telecom export.
- Aerospace Retrofit:Data transmission flex cable replacement cycles in commercial aviation avionics are compressing as carriers accelerate fleet modernization.
- China GB Standards:Domestic certification alignment with international IEC standards is creating regulatory tailwinds for halogen-free insulation adoption in Chinese-built industrial equipment.
Industry Challenges
- Polymer Formulation Talent:Compound development expertise spanning electrical, mechanical, and chemical engineering disciplines remains scarce in emerging manufacturing regions.
- CE Marking Timelines:EU Construction Products Regulation compliance documentation for fire-resistant flex cables extends certification cycles by six to twelve months.
- Legacy System Integration:Retrofit installations in industrial automation require custom bend-radius solutions incompatible with standardized cable geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Cables Market |
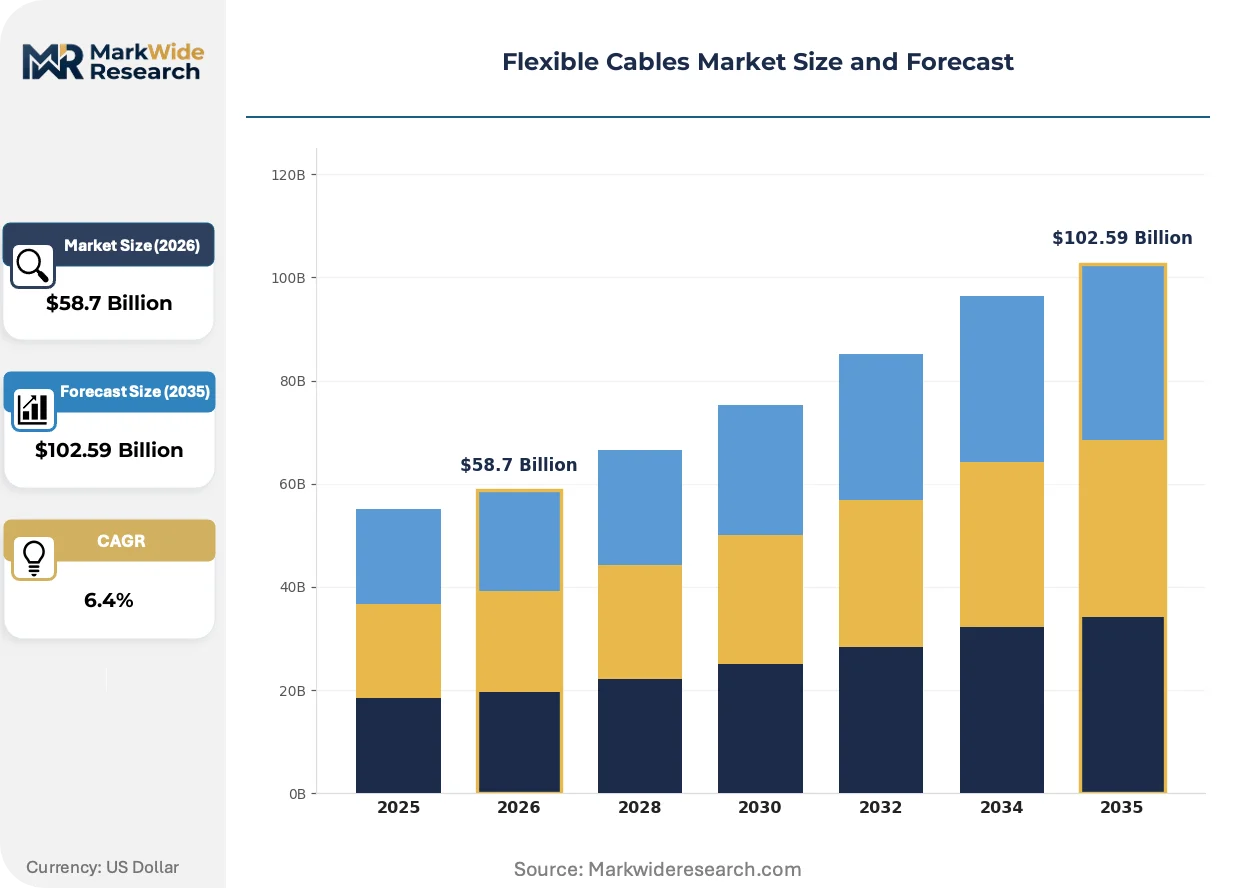
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Cables, Power Cables, Instrumentation Cables, Data Transmission Cables, Coaxial Cables Material: Copper, Aluminum, Optical Fiber, Silver-Coated Copper, Tinned Copper Application: Energy Generation, Telecommunications, Marine Operations, Aerospace Systems, Consumer Electronics End User: Utilities, Communication Providers, Shipping Companies, Aviation Firms, Electronics Manufacturers |
| Companies Covered | Prysmian Group, Nexans, Southwire Company, Belden Inc., Leoni AG, Lapp Group, Sumitomo Electric Industries, General Cable, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Cables Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are splitting product development pathways, while procurement behavior is compressing supplier qualification cycles.
High-temperature thermoplastic elastomers are displacing traditional cross-linked rubber insulation in continuous-flex applications. Automotive tier-one suppliers are specifying these materials for EV charging cable assemblies rated above ten thousand cycles. The technology is bifurcating the market between commodity PVC-sheathed products and premium elastomeric solutions.
EU RoHS substance restrictions on insulation additives are elevating compliance costs for non-specialized manufacturers. ECHA's scheduled 2025 REACH candidate list expansion targets additional phthalate plasticizers used in cable jacketing. European industrial OEMs are accelerating supplier audits to secure compound documentation ahead of enforcement deadlines.
Buyers are consolidating vendor panels around integrated compound-to-cable manufacturers capable of delivering certified harness assemblies. Distributor-led specification is declining as end-users demand direct technical engagement on bend-radius and fatigue-life parameters. This consolidation is most visible in German automotive and robotics sectors where procurement teams are reducing qualified supplier lists by forty to sixty percent.
Flexible Cables Market Segmentation
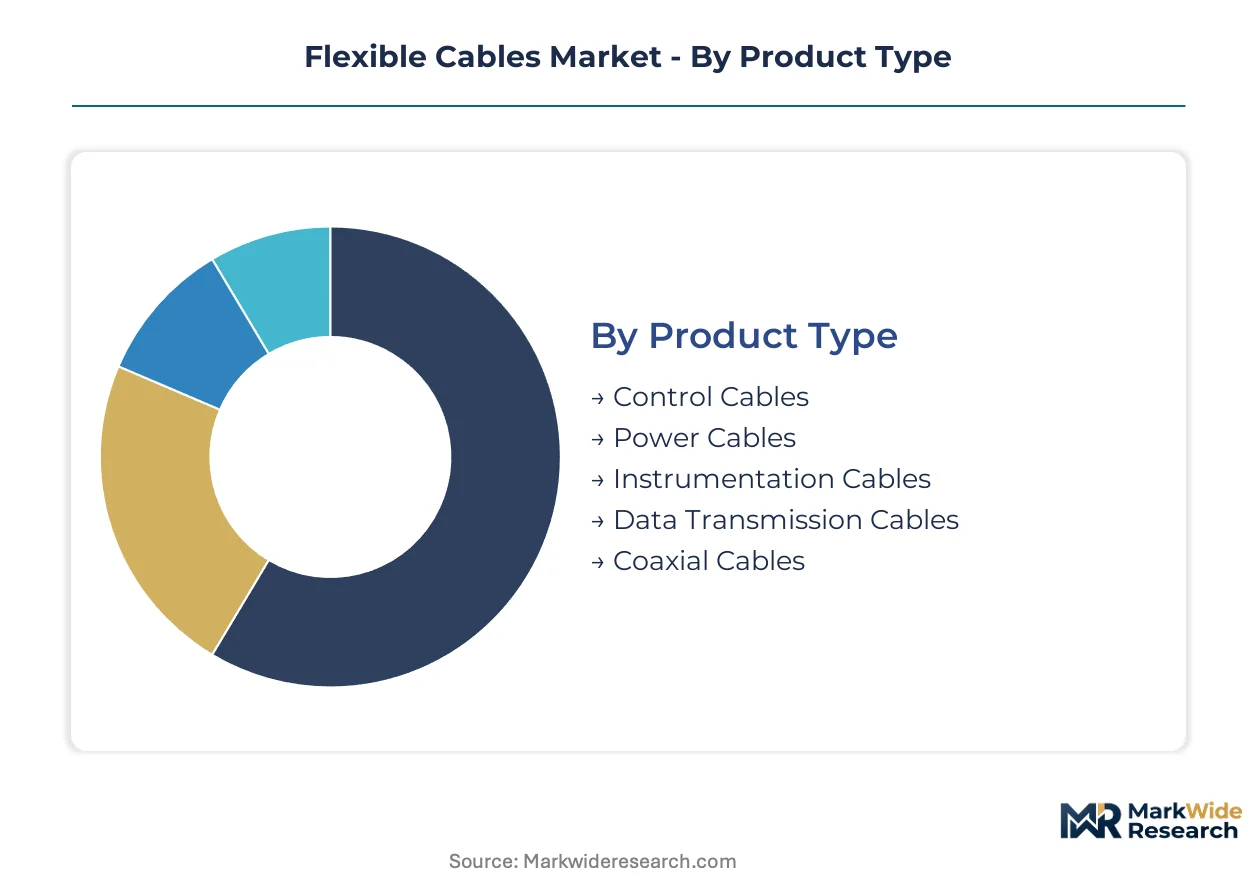
Flexible cable procurement decisions split across technical performance tiers and regulatory compliance requirements. Manufacturers configure product portfolios around conductor material economics and end-use durability specifications.
Product Type:
Margin pools concentrate in assemblies requiring continuous flex cycling validation and subsea dynamic load certification.
- Power Cables:Stranded copper conductors with cross-linked elastomer insulation rated for repeated bending below five times outer diameter. Demand concentrates in Germany's industrial automation corridor for EV charging infrastructure requiring ten-thousand-cycle durability.
- Data Transmission Cables:Shielded twisted-pair or fiber-optic assemblies engineered for electromagnetic immunity in precision motion systems. Aerospace system retrofits in commercial aviation avionics are compressing replacement cycles as carriers accelerate fleet modernization.
- Control Cables:Multi-conductor flex assemblies for signal transmission in robotics and automated machinery.
- Instrumentation Cables:Low-capacitance pairs for sensor and measurement device connectivity in process industries.
- Coaxial Cables:Central conductor with dielectric insulation and braided shield for RF signal transmission.
The dominant share belongs to Power Cables, while Data Transmission Cables is closing the gap fastest.
Material:
Cost tier stratification separates commodity conductors from premium coated variants with specialized corrosion resistance.
- Copper:Electrolytic tough-pitch or oxygen-free high-conductivity strands delivering conductivity requirements in precision motion systems. LME-traded price volatility creates margin compression for manufacturers lacking backward integration into metal supply.
- Optical Fiber:Glass or plastic core with polymer cladding for electromagnetic immunity in robotic sensing harnesses. Industrial automation integrators in Japan and Germany are specifying these variants where signal integrity is mandatory.
- Aluminum:Lightweight conductor for weight-sensitive applications with lower conductivity tolerance.
- Silver-Coated Copper:Base conductor with precious metal plating for high-frequency signal transmission.
- Tinned Copper:Hot-dipped or electroplated tin coating for solderability and oxidation resistance in marine environments.
Copper retains volume leadership, though Optical Fiber is expanding most quickly in sensing applications.
Application:
Customer type concentration varies by durability certification requirements and procurement scale.
- Energy Generation:Utility-scale flexible interconnections for renewable generation and grid infrastructure. Procurement is accelerating for high-cycle flex assemblies in offshore wind turbine nacelles.
- Aerospace Systems:Avionics harnesses meeting FAA electrical safety standards for bend-radius and fatigue-life parameters. Fleet modernization programs are driving replacement demand.
- Telecommunications:Shielded flex assemblies governed by FCC emissions rules for data center and mobile infrastructure.
- Marine Operations:Dynamic power umbilicals for subsea oil and gas extraction with polymer creep constraints under combined loading.
- Consumer Electronics:Portable device charging cables with standardized connector interfaces.
Energy Generation commands the largest procurement volumes, while Aerospace Systems is gaining share fastest on retrofit cycles.
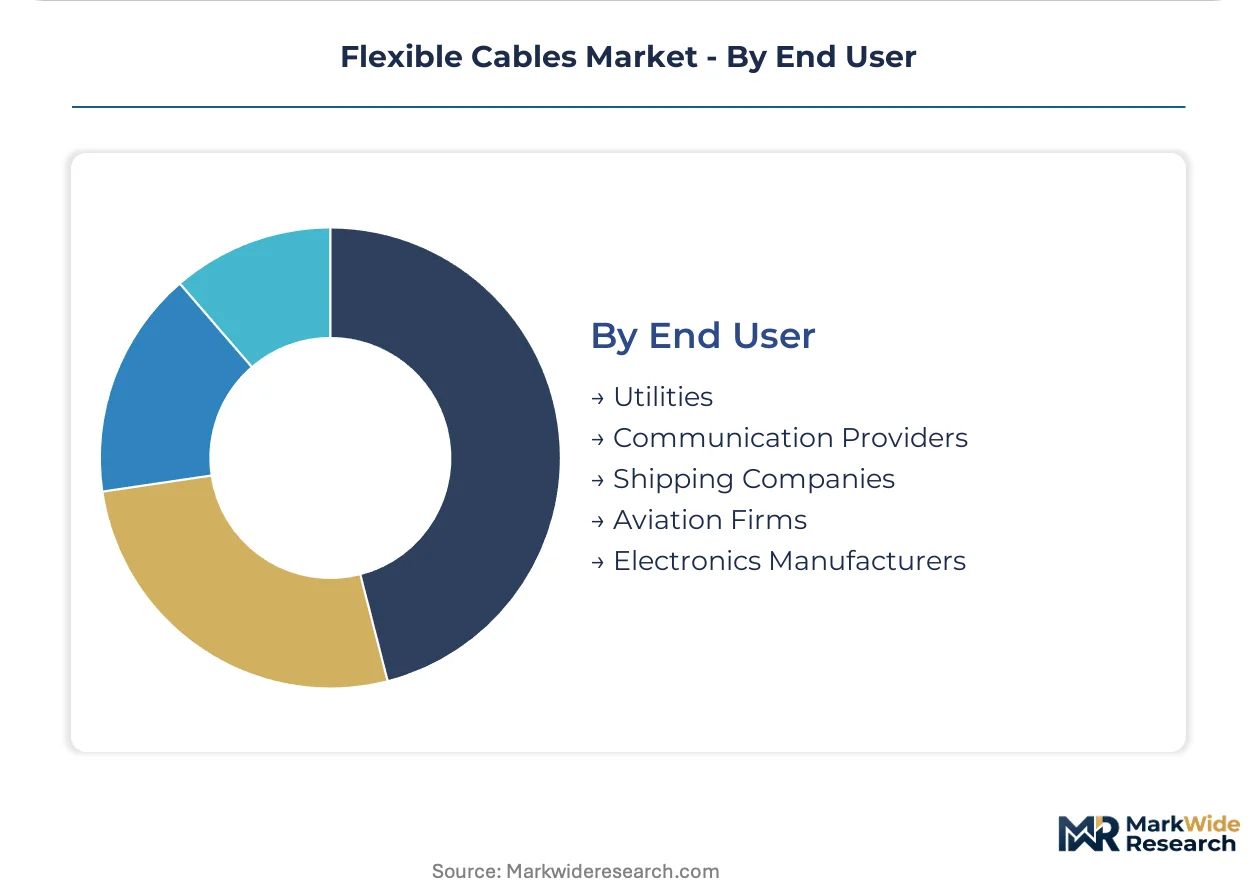
End User:
Supply concentration tracks toward integrated compound-to-cable manufacturers capable of delivering certified harness assemblies.
- Utilities:Grid operators and renewable developers procuring fire-resistant flexible cable for substation and generation interconnection. EU Construction Products Regulation CE marking extends certification cycles by six to twelve months.
- Aviation Firms:Commercial carriers and defense contractors specifying custom bend-radius solutions for avionics retrofits. Direct technical engagement on fatigue-life parameters is displacing distributor-led specification.
- Communication Providers:Telecom operators and data center operators sourcing shielded assemblies.
- Shipping Companies:Maritime fleet operators requiring corrosion-resistant conductor coatings.
- Electronics Manufacturers:OEMs integrating cable harnesses into finished consumer and industrial equipment.
Utilities dominate procurement scale, while Aviation Firms is climbing the fastest on compressed modernization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for electric vehicle infrastructure and industrial automation are redirecting procurement flows across major manufacturing economies. National regulators are tightening material specifications for halogen-free insulation while local industrial clusters specialize in high-cycle flex assemblies.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are scaling orders for charging cables rated above ten thousand insertion cycles. ECHA REACH candidate list updates on phthalate plasticizers are forcing compound reformulation across domestic supply chains. The Stuttgart industrial corridor concentrates demand from robotics integrators specifying optical fiber variants for electromagnetic immunity.
China
MIIT's GB standards alignment with international IEC specifications is accelerating halogen-free insulation adoption in industrial equipment. Domestic certification requirements are creating regulatory tailwinds for cable harness localization. The Yangtze River Delta manufacturing belt anchors supply for automotive and telecom export markets under the country's dual carbon goals.
United States
FCC emissions rules governing shielded flex assemblies are elevating compliance costs for telecommunications infrastructure. FAA electrical safety standards for bend-radius and fatigue-life parameters are compressing avionics replacement cycles. The Southeast manufacturing corridor spanning Georgia and the Carolinas is attracting capacity expansion for EV charging cable assemblies.
Japan
METI's industrial policy supports captive copper refining and specialized polymer compounding for precision motion systems. JIS standards certification creates entry barriers for non-integrated manufacturers. The Nagoya industrial zone concentrates robotic sensing harness demand where signal integrity mandates optical fiber deployment.
Flexible Cables Market Competitive Landscape
Listed leaders compete with private specialists across integrated manufacturing capabilities. The vendor base splits between compound-to-cable integrators and assembly-focused fabricators. Three archetypes dominate: European integrated manufacturers with in-house polymer compounding, Asian metal-integrated producers with captive copper supply, and North American specialty cable engineers focused on certification-heavy applications. Competitive moves concentrate on backward integration into conductor supply and strategic partnerships for halogen-free compound access.
Among European integrated manufacturers, Prysmian Group and Nexans exemplify the compound-to-cable archetype with cross-border manufacturing footprints. Sumitomo Electric Industries anchors the Asian metal-integrated tier through operations in Japan. These three occupy positions spanning premium elastomeric solutions and high-cycle flex assemblies for automotive and industrial automation procurement.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Belden Inc. |
| Leoni AG |
| Lapp Group |
| Sumitomo Electric Industries |
| General Cable |
| Amphenol Corporation |
| Others |
Supply & Pricing Matrix
Halogen-free elastomer compounds displacing legacy PVC insulation across European supply chains are simultaneously shifting procurement geography toward integrated compound-to-cable manufacturers and compressing margin pools for non-specialized fabricators lacking in-house polymer formulation capabilities.
Pricing Analysis
Certification level — CE marking under EU Construction Products Regulation versus commodity-grade assemblies — creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium elastomeric, mid-grade thermoplastic, and economy PVC-sheathed products reflects durability validation and regulatory compliance investment. Pricing pressure stems from LME copper volatility and REACH-driven reformulation costs. Automotive OEMs exhibit lowest price sensitivity due to cycle-life specifications, while consumer electronics procurement teams drive hard volume negotiations.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for copper conductor feedstock and specialized polymer additives. Manufacturing concentrates in Germany, Japan, and China, with compound development anchored in Italian and Dutch facilities. Raw material dependencies center on LME-traded copper cathode, halogen-free flame retardants, and high-purity optical fiber preforms. Single-source vulnerability in Japanese and German elastomer compounding creates structural risk. Distribution runs through direct technical engagement with automotive and robotics OEMs, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where CE marking timelines and REACH compliance documentation create switching costs that entrench integrated compound-to-cable manufacturers against assembly-focused competitors.
For Market Incumbents: Compound backward integration into halogen-free polymer formulation to capture margin pools escaping commodity fabricators. Expand capacity in Germany's industrial automation corridor where EV charging cable procurement concentrates. Defensive priority: lock in automotive OEM direct technical engagement before qualification cycles compress supplier panels further. For New Entrants and Emerging Players: Differentiate on India PLI scheme localization for automotive harness export under electronics manufacturing incentives. Target aerospace retrofit segments where FAA fatigue-life certification creates qualification barriers incumbents navigate slowly. White-space entry runs through custom bend-radius solutions for legacy industrial automation retrofits incompatible with standardized geometries. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive compound capabilities. Long-term viability hinges on regulatory entrenchment rather than pure scale. Acquisition target archetype: mid-tier European fabricators with CE marking infrastructure but lacking polymer compounding. Signal to watch: ECHA REACH candidate list expansion accelerating forced exits among non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captures margin pools from Japanese and German chemical suppliers while securing REACH compliance documentation. |
| CE Marking Infrastructure Investment | Extends certification cycle advantage under EU Construction Products Regulation for fire-resistant flex assemblies. |
| India PLI Scheme Capacity Expansion | Localizes automotive and telecom harness production for export markets under electronics manufacturing incentives. |
| Direct OEM Technical Engagement | Displaces distributor-led specification in German automotive and robotics procurement panels. |
| Halogen-Free Compound Reformulation | Aligns with ECHA REACH candidate list updates ahead of 2025 enforcement deadlines. |
Research Methodology
A standing panel of cable procurement managers at automotive OEMs, plant engineers at industrial automation integrators, polymer compounding technical directors, and regulatory affairs specialists at certification bodies provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation against ECHA REACH substance databases, EU Construction Products Regulation technical documentation, SEC filings from listed manufacturers, and customs trade data on copper conductor and polymer additive flows. Bottom-up segment sizing triangulated against top-down market envelope checks.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled product type, material grade, application durability requirements, and end-user procurement scale dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating EV charging infrastructure deployment curves, aerospace fleet modernization schedules, and industrial automation capital expenditure patterns.
Material uncertainties — copper price volatility, ECHA regulatory timeline shifts, polymer formulation talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions on procurement behavior and certification cycle durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Assembly Market
Cables
Class 1E Electric Cables Market
Cables
Usb Data Cable Market
Cables
GCC Cable Accessories Market
Cables
Europe Cable Accessories Market
Cables
Polyurethane Cable Market
Cables
Premise Cable Market
Cables
Cable Carrier Market
Cables
South Africa Wire and Cable Market
Cables
USB Cable Market
Cables
United States Cable Accessories Market
Cables
Latin America Wire and Cable Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Cable Market
Cables
Global Cable Gland Market
Cables
Industrial Cable Reels Market