
 Global Disconnector Switch Market | 2026-2036
Global Disconnector Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disconnector Switch Market Foresight
Modular switchgear bundling is pivoting procurement patterns across utility and industrial buyers. ABB leverages captive manufacturing of vacuum interrupters to control cost positions in gas-insulated disconnector lines. Siemens AG anchors European demand through specialized high-voltage offerings for substation modernization. Schneider Electric SE differentiates via integrated digital monitoring packages bundled with interlocked disconnector systems.
A disconnector switch is an electromechanical device designed to isolate electrical circuits under no-load conditions, typically rated for voltages from 1 kV to 800 kV with visible break air gaps or gas-insulated sealed chambers. Its primary purpose is to provide guaranteed electrical isolation for maintenance, safety, and sectionalization in power generation, transmission, and distribution networks. Vacuum technology leads in medium-voltage segments where arc quenching reliability determines lifecycle economics, while gas-insulated variants capture premium positions in space-constrained urban substations. Air-insulated disconnectors occupy mature, price-sensitive utility contracts where established maintenance protocols reduce switching technology risk.
FDA oversight of electrical safety in healthcare facility infrastructure, EPA rules on sulfur hexafluoride emissions from gas-insulated equipment, and IEC 62271 standards enforced by national regulators in Germany, India, and China collectively tighten product compliance thresholds. These frameworks compel manufacturers to certify arc extinction performance and material traceability before market access. Stakeholders must monitor evolving F-Gas Regulation amendments and dual carbon goals in China as these will redirect R&D investment toward SF6-free insulation technologies.
Market Dynamics
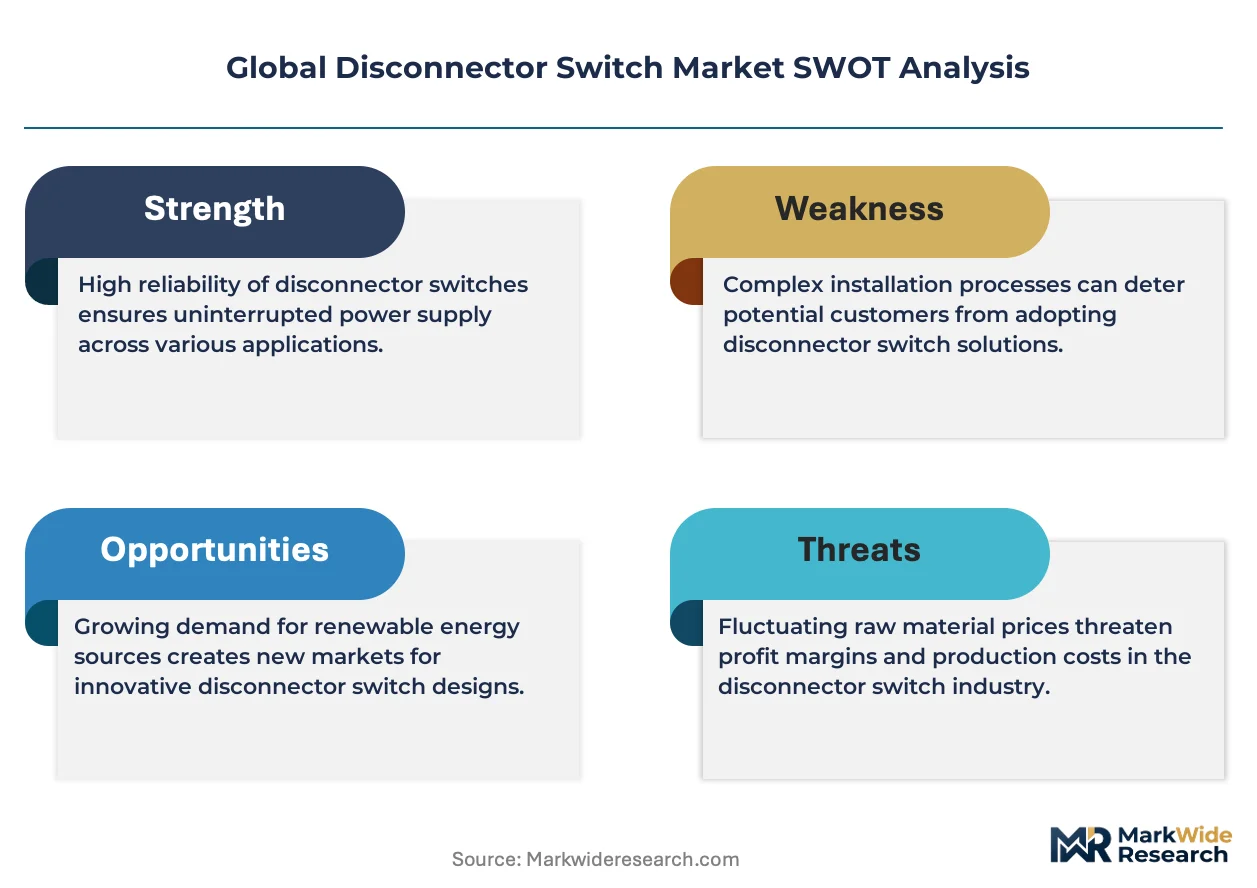
SF6 phase-out mandates across Germany, India, and China are compressing product development cycles while forcing R&D redirection toward alternative insulation mediums. Manufacturers face simultaneous pressure from tightening IEC 62271 certification timelines and utility procurement consolidation.
Growth Catalysts
- Transmission infrastructure renewal:Grid modernization programs in India and Germany accelerate replacement cycles for aging air-insulated disconnectors in substations exceeding 40 years of service.
- Renewable interconnection mandates:Wind and solar farm developers in China must install visible-break isolation equipment compliant with revised CEA technical standards for grid-tied generation assets.
- F-Gas Regulation amendments:The EU's tightening sulfur hexafluoride emission caps force utilities to specify SF6-free alternatives in tender documents for new urban substation projects.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings for conductive components compress margin predictability in long-delivery utility contracts.
- Vacuum interrupter supply concentration:Captive production of critical arc-quenching components clusters among three integrated manufacturers, creating procurement bottlenecks for independent switchgear assemblers.
- SF6 inventory lock-in:Existing gas-insulated installed base in European utilities delays replacement demand despite regulatory pressure, extending payback periods for alternative insulation R&D.
Strategic Opportunities
- Digital twin integration:Sensor-embedded disconnector systems enabling predictive maintenance protocols open premium pricing tiers for industrial microgrid operators.
- India rural electrification:Unelectrified distribution networks in Bihar and Uttar Pradesh present volume demand for cost-optimized air-insulated sectionalizing switches.
- Clean hydrogen production clusters:Electrolyzer facilities in Germany require specialized high-current isolation equipment for DC bus protection, creating application-specific product lines.
Industry Challenges
- IEC 62271-102 certification timelines:Extended type-testing durations for new insulation mediums delay product launches by 18-24 months, compressing competitive windows.
- Legacy substation interoperability:Retrofit installations demand mechanical compatibility with 1970s-era mounting configurations, constraining design freedom for compact gas-insulated alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disconnector Switch Market |
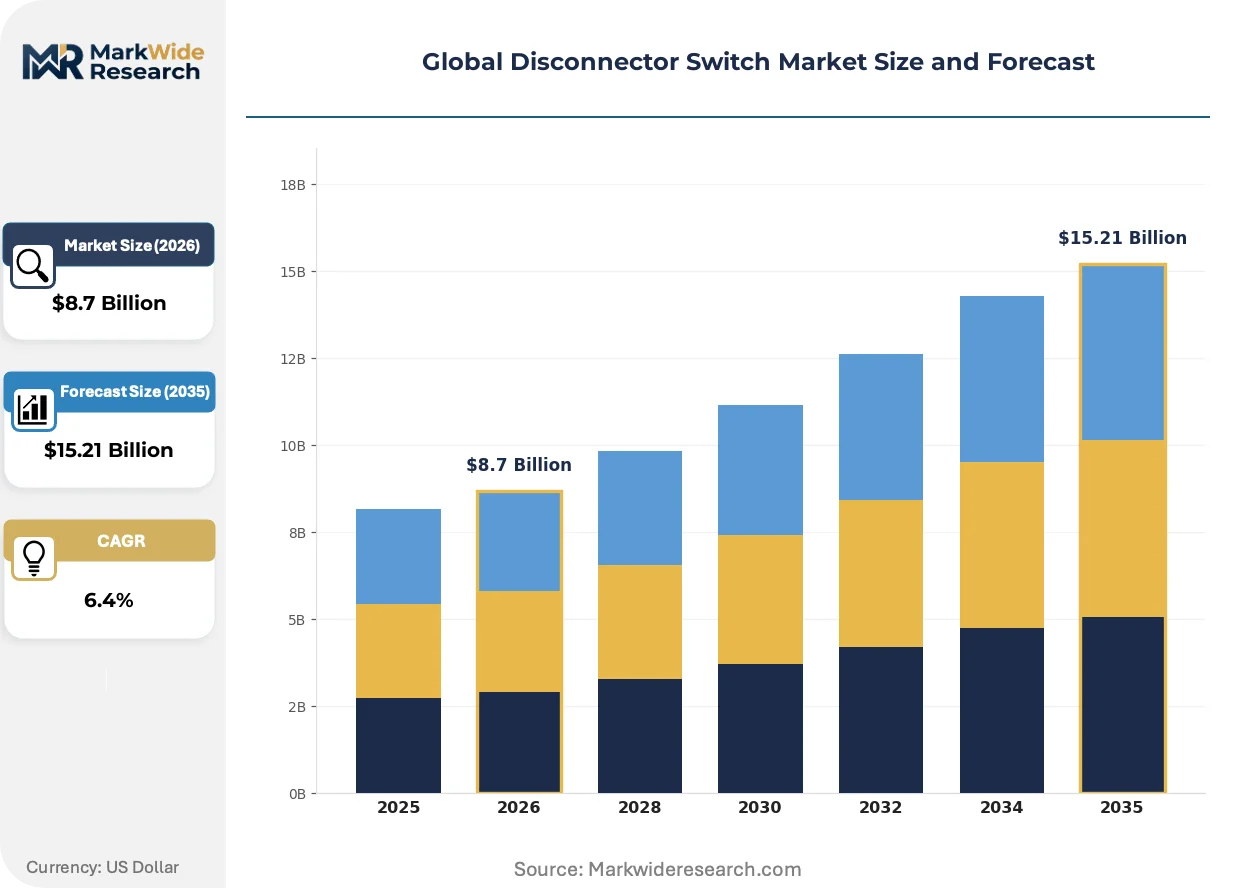
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Visible Break, Load Break, Interlocked, Fusible, Solid Blade Technology: Plain Contact, Magnetic, Vacuum, Gas Insulated, Air Insulated Application: Power Distribution, Generation Plants, Substations, Transmission Lines, Railways End User: Utility Providers, Electrical Contractors, Renewable Energy Providers, Mining Companies, Rail Operators |
| Companies Covered | ABB, Schneider Electric SE, General Electric, Siemens AG, Eaton Corporation, Havells India Limited, Littelfuse, Honeywell International, WEG SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disconnector Switch Market Shifts & Advancements
Solid-state switching concepts and alternative gas insulation are converging to redefine performance benchmarks across voltage classes. The competitive frontier shifts from mechanical reliability to intelligent condition monitoring and environmental compliance.
Dry air and fluoronitrile mixtures are absorbing the functional role of sulfur hexafluoride in medium-voltage gas-insulated disconnectors. German utilities pilot these alternatives in Berlin and Munich substations where space constraints prohibit air-insulated designs. The technology is absorbing premium pricing power previously held by SF6 equipment while compressing maintenance interval advantages.
The EU F-Gas Regulation's 2024 tightening of sulfur hexafluoride phase-down quotas forces manufacturers to redesign sealed-for-life chambers around alternative mediums. Industrial consequence includes accelerated obsolescence of existing gas-handling infrastructure and retraining of field service technicians. High-voltage segments in Germany and France face the steepest compliance ramps, with tenders now specifying global warming potential thresholds below SF6 levels.
Utility procurement departments now bundle disconnector purchases with digital monitoring packages and long-term service agreements, displacing transactional equipment-only contracts. Integrated suppliers capture multi-year revenue streams while pure-play manufacturers face margin compression. This pattern concentrates in German municipal utilities and Chinese provincial grid companies with centralized sourcing mandates.
Global Disconnector Switch Market Segmentation
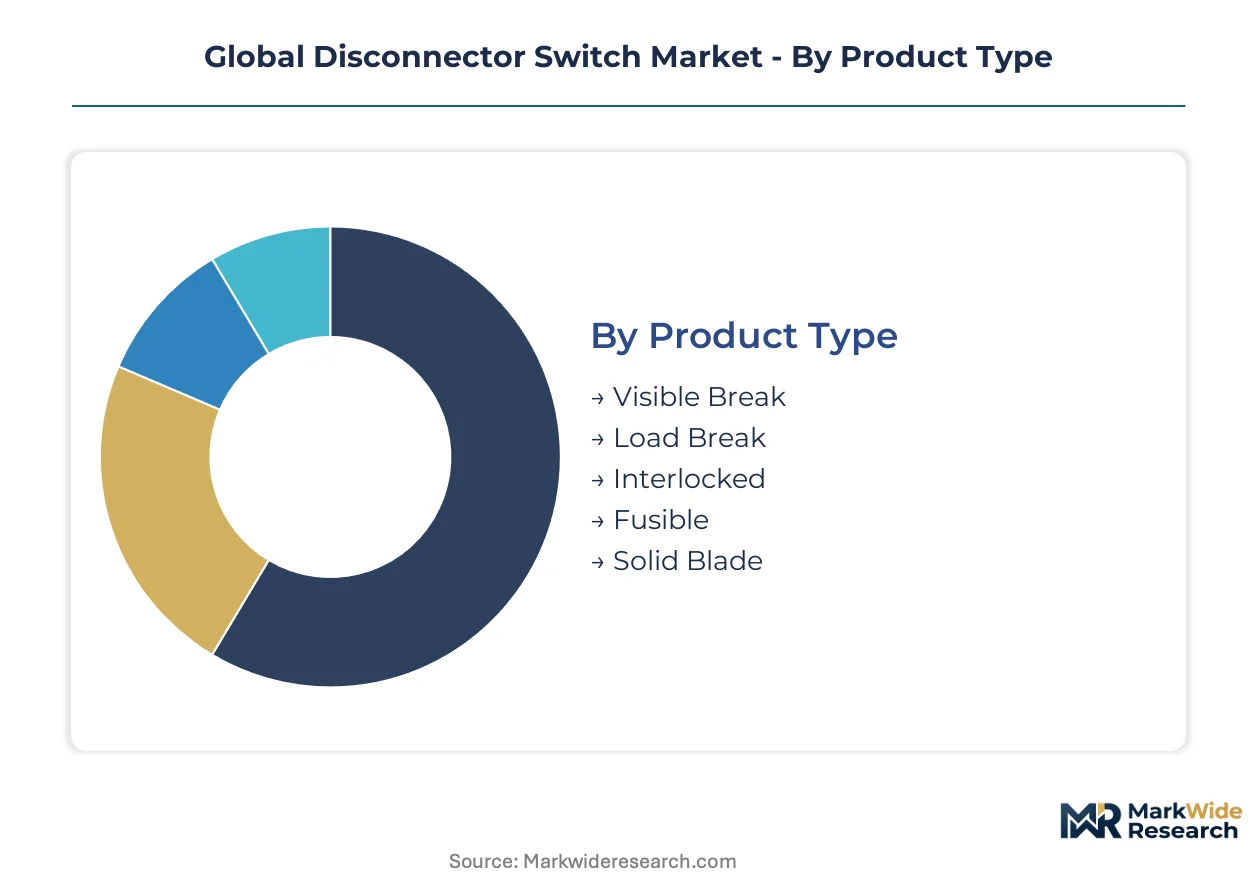
Disconnector switch segmentation reveals how integration depth varies by voltage class and operational criticality. Standalone visible-break units dominate outdoor substation installations, while embedded vacuum and gas-insulated variants integrate into compact switchgear assemblies for urban density constraints.
Product Type:
Integration depth splits sharply between standalone visible-break designs and embedded interlocked systems bundled with switchgear enclosures.
- Visible Break:Air-gap isolation designs with mechanical blade visibility satisfy IEC 62271-102 requirements for guaranteed disconnection verification. German transmission operators specify these for outdoor substations exceeding 245 kV where visual confirmation of isolation remains mandatory under national safety protocols.
- Interlocked:Mechanically coupled systems prevent operation until protective devices isolate load current, embedding directly into gas-insulated switchgear lines. Chinese provincial grid companies bundle these with digital monitoring packages in tender documents for new urban substation projects, compressing procurement cycles.
- Load Break:Limited switching capability designs handle low-magnitude fault currents in distribution networks.
- Fusible:Overcurrent protection integration targets industrial feeder applications with cost-sensitive maintenance protocols.
- Solid Blade:Compact non-fusible designs serve space-constrained panelboard installations in commercial buildings.
Visible Break leads volumes today; Interlocked is gaining share fastest.
Technology:
Cost tier stratification separates commodity air-insulated platforms from premium sealed-chamber alternatives commanding maintenance interval premiums.
- Vacuum:Hermetically sealed arc quenching eliminates atmospheric degradation, extending service intervals beyond 30,000 operations. Indian distribution utilities specify these for rural electrification projects in Bihar where technician access constraints favor minimal maintenance architectures.
- Gas Insulated:Sealed SF6 or fluoronitrile chambers enable 72.5 kV ratings in one-tenth the footprint of air-insulated equivalents. German municipal utilities pilot dry-air alternatives in Berlin substations where F-Gas Regulation compliance now mandates global warming potential thresholds below sulfur hexafluoride levels.
- Plain Contact:Basic blade-and-jaw mechanisms occupy mature utility replacement cycles with established maintenance protocols.
- Magnetic:Electromagnetic actuation accelerates opening speeds for high-current DC isolation in rail traction systems.
- Air Insulated:Open-contact designs dominate price-sensitive procurement in transmission corridors with adequate clearance margins.
Air Insulated commands the largest installed base; Gas Insulated exhibits the steepest expansion trajectory.
Application:
Customer type concentration clusters procurement authority differently across generation assets versus networked infrastructure.
- Substations:Voltage transformation nodes require coordinated isolation at multiple bus sections, driving bundled disconnector-transformer specifications. Transmission infrastructure renewal programs in India and Germany accelerate replacement demand for aging air-insulated units exceeding 40 years of service.
- Power Distribution:Radial and ring-main feeder sectionalization demands cost-optimized visible-break designs with pad-mount compatibility. Chinese wind farm developers install compliant isolation equipment under revised CEA technical standards for grid-tied renewable assets.
- Generation Plants:Thermal and hydro facilities specify heavy-duty designs for generator circuit breaker isolation.
- Transmission Lines:Series compensation and shunt reactor switching require specialized high-voltage ratings.
- Railways:Traction power supply isolation demands DC-rated magnetic actuation for rapid fault clearing.
Substations absorb the highest absolute unit volumes; Power Distribution demonstrates the most rapid demand acceleration.
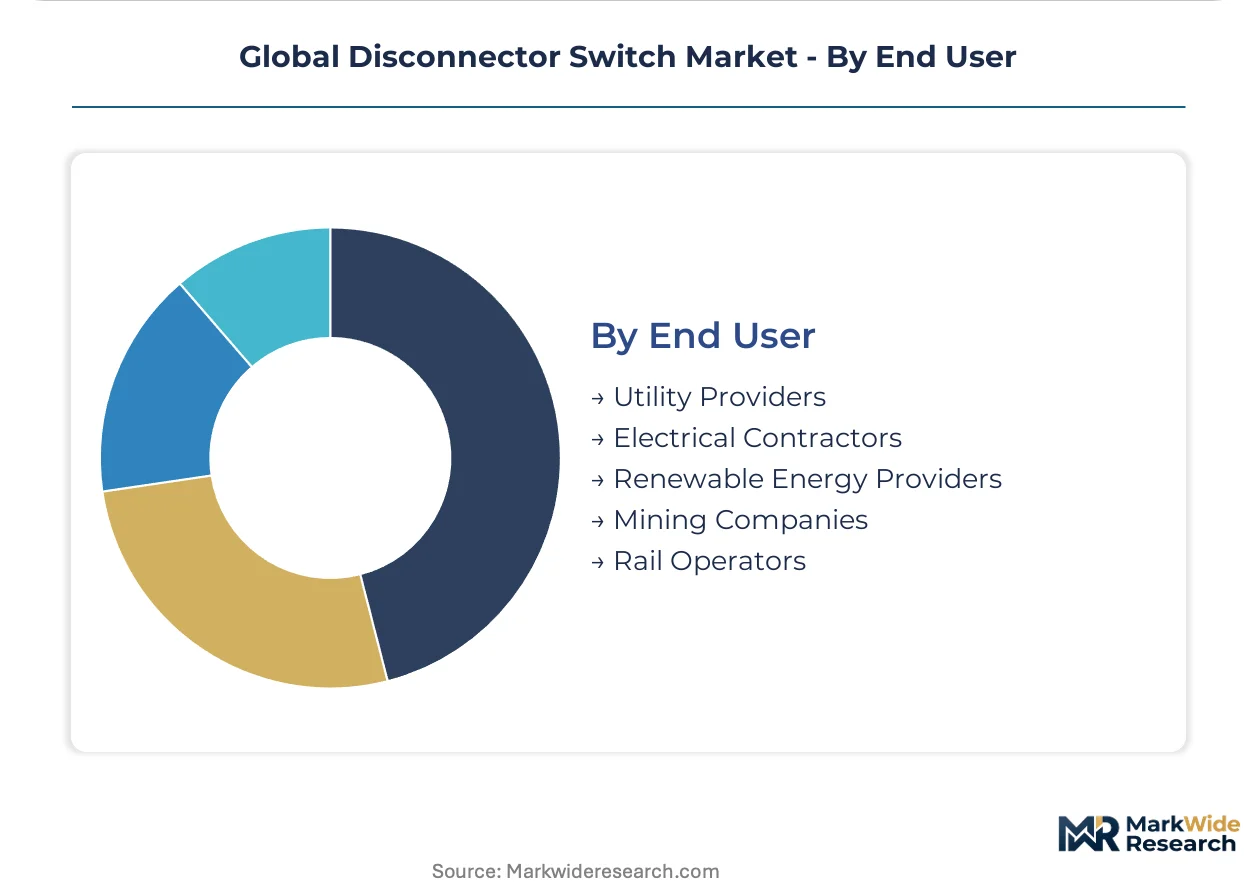
End User:
Procurement consolidation patterns separate centralized utility sourcing from fragmented contractor purchasing.
- Utility Providers:Vertically integrated transmission and distribution operators specify lifecycle-cost-optimized platforms with 40-year service horizons. German municipal utilities bundle disconnector purchases with digital monitoring packages and long-term service agreements, displacing transactional equipment-only contracts.
- Renewable Energy Providers:Wind and solar farm developers face interconnection mandates requiring visible-break isolation with grid-code certification. Indian solar park operators in Rajasthan source cost-optimized air-insulated sectionalizing switches for collection grid aggregation.
- Electrical Contractors:Project-based procurement favors standard catalog configurations with rapid delivery availability.
- Mining Companies:Harsh environment specifications prioritize sealed enclosures against dust and moisture ingress.
- Rail Operators:Traction power specifications demand DC-rated magnetic actuation with rail-specific mechanical interlocking.
Utility Providers dominate current procurement volumes; Renewable Energy Providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The disconnector switch industry traces its modern scaling to German engineering origins in high-voltage substation equipment during the 1960s, with subsequent manufacturing expansion into China and India following grid privatization waves in the 1990s and 2000s.
China
Provincial grid companies in Jiangsu and Guangdong drive procurement volumes for urban substation modernization under State Grid Corporation's 14th Five-Year Plan targets. The National Energy Administration enforces revised CEA technical standards mandating visible-break isolation for all grid-tied renewable assets. Yangtze River Delta manufacturing clusters around Shanghai supply gas-insulated variants for space-constrained metro substations.
Germany
Municipal utilities in Berlin and Munich pilot dry-air insulation alternatives to comply with EU F-Gas Regulation phase-down quotas for sulfur hexafluoride. The Federal Network Agency (Bundesnetzagentur) mandates lifecycle-cost evaluations in transmission tender documents. Bavarian industrial zones anchor demand for high-voltage interlocked systems bundled with digital monitoring packages.
India
Rural electrification programs in Bihar and Uttar Pradesh generate volume demand for cost-optimized air-insulated sectionalizing switches with minimal maintenance architectures. The Central Electricity Authority (CEA) enforces technical standards for renewable interconnection equipment. Rajasthan solar park operators source visible-break disconnectors for collection grid aggregation under national solar mission targets.
United States
Utility procurement departments in Texas and California bundle disconnector purchases with predictive maintenance service agreements under FERC grid reliability guidelines. The EPA regulates sulfur hexafluoride emissions from gas-insulated equipment in federal infrastructure projects. Midwest transmission operators replace aging air-insulated units exceeding 40 years of service in Illinois and Ohio substation corridors.
Japan
Tokyo Electric Power and regional utilities specify vacuum interrupter designs for seismic-resistant substation installations under METI resilience standards. The Ministry of Economy, Trade and Industry enforces JIS certification timelines for arc extinction performance verification. Kansai industrial corridors around Osaka demand compact gas-insulated variants for urban density constraints.
Global Disconnector Switch Market Competitive Landscape
Premium-margin players sit above commodity-margin players across insulation technology tiers, with gas-insulated and vacuum-sealed variants commanding maintenance-interval premiums over air-insulated commodity lines. The vendor base organizes into three strategic archetypes: integrated electrical conglomerates with captive component manufacturing, specialized switchgear assemblers dependent on external interrupter supply, and regional fabricators serving price-sensitive utility replacement cycles. Dominant competitive moves include backward integration into vacuum interrupter production and geographic expansion through localized certification partnerships.
Among integrated electrical conglomerates, ABB and Siemens AG exemplify archetypes with in-house control over critical arc-quenching component supply chains. Schneider Electric SE occupies a position within the digital-integration tier, representing suppliers that bundle hardware with sensor-embedded monitoring platforms. Havells India Limited sits among regional-scale specialists addressing cost-optimized procurement in emerging market distribution networks.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric SE |
| General Electric |
| Siemens AG |
| Eaton Corporation |
| Havells India Limited |
| Littelfuse |
| Honeywell International |
| WEG SA |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between IEC 62271-102 certified gas-insulated systems and commodity air-insulated units manifests in both pricing power and supply chain configuration. Premium-tier manufacturers in Germany and China command maintenance-interval premiums through captive vacuum interrupter production, while price-sensitive procurement in Indian rural electrification channels compresses margins for independent assemblers dependent on external component supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates gas-insulated SF6-free alternatives from vacuum-sealed medium-voltage designs from plain-contact air-insulated units. Price differentiation hinges on IEC 62271 certification grade and after-sales service bundling, with German municipal utilities paying premiums for digital monitoring integration. Cost compression in air-insulated tiers is intensifying because raw material volatility in copper and aluminum squeezes long-delivery contract margins. Indian distribution utilities exhibit highest price sensitivity, while German transmission operators show lowest sensitivity due to lifecycle-cost procurement mandates.
Supply Chain Analysis
Regional distribution centers in Shanghai, Berlin, and Mumbai anchor hub-and-spoke patterns serving utility procurement clusters across Asia-Pacific and Europe. Manufacturing concentrates in China, Germany, and India, with vacuum interrupter supply anchored in captive production facilities of integrated conglomerates. Raw material dependencies rest on copper cathode, aluminum billet, and specialized ceramic insulator feedstocks. Single-source vulnerability clusters around three manufacturers controlling arc-quenching component supply, creating procurement bottlenecks for independent switchgear assemblers. Distribution runs through authorized utility channel partners with long-term service agreement bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Disconnector Switch Market represents a late-cycle quality story as F-Gas Regulation amendments and dual carbon goals in China redirect procurement specifications toward SF6-free premium platforms with embedded digital monitoring.
For Market Incumbents: Cement position through backward integration into vacuum interrupter production and capacity expansion in Indian distribution corridors threatened by emerging regional assemblers. Prioritize IEC 62271-102 certification investment for alternative insulation mediums before regulatory timelines compress competitive windows for SF6-free product launches. For New Entrants and Emerging Players: Enter via cost-optimized air-insulated sectionalizing switches targeting Bihar and Uttar Pradesh rural electrification programs where technician access constraints favor minimal maintenance architectures. Pursue partnership-based go-to-market models with Chinese provincial grid companies seeking localized certification support for urban substation modernization tenders. For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum interrupter supply concentration creates acquisition premiums for captive production capabilities. Five-to-ten-year viability favors integrated electrical conglomerates with in-house arc-quenching component supply and digital monitoring platform bundling. Watch F-Gas Regulation amendment enforcement velocity in Germany and France as the inflection signal for alternative insulation R&D payoff timing.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Product Line Development | EU F-Gas Regulation compliance secures tender eligibility in German and French municipal utility procurement. |
| Digital Monitoring Platform Integration | Sensor-embedded systems enable predictive maintenance revenue streams with German grid operators. |
| Vacuum Interrupter Capacity Expansion | Captive production insulates margin positions against supply bottlenecks in critical arc-quenching components. |
| India Distribution Network Localization | Manufacturing presence in Maharashtra and Gujarat reduces delivery costs for Bihar electrification programs. |
| Alternative Gas Insulation R&D Partnership | Fluoronitrile and dry-air collaborations with German utilities accelerate certification timelines under IEC 62271-102. |
Research Methodology
Coverage spans China, India, Germany, the United States, and Japan, with primary inputs from each market combining structured interviews with utility planning officers, switchgear procurement managers, EPC contractors, aftermarket service heads, and regulatory affairs leads at national standards bodies. Secondary validation draws from IEC publication databases, CEA technical standard filings, EU F-Gas Regulation amendment documents, and customs trade data for copper and aluminum component flows. Bottom-up utility procurement tracking triangulates against top-down transmission infrastructure investment forecasts.
Granularity-level modeling disaggregates volume and value outputs by insulation technology, voltage class, integration depth, end-user procurement consolidation pattern, and regional regulatory framework cluster across the analysis window. CAGRs derive from utility capital expenditure pipeline analysis and renewable interconnection mandate enforcement trajectories. Industry-specific forecast inputs include SF6 phase-down quota implementation schedules and rural electrification program budget allocations.
The model holds under stable regulatory enforcement timelines and raw material price corridors; deviation in F-Gas Regulation amendment velocity or copper-aluminum volatility spikes would shift replacement cycle timing and margin compression severity. Forecasts reflect documented assumptions on certification timeline durations and utility procurement bundling adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Electromechanical Microwave Switch Market
Switches
Paralleling Switchgear Market
Switches
Residual Current Circuit Breaker Market
Switches
South Korea Reed Sensors Switches Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Temperature and Pressure Switches Market
Switches
Solid State Relay Market
Switches
Analog Switches Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Intelligent Power Switches Market
Switches
Pad-Mounted Switchgear Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Asia Pacific Reed Sensors Switches Market
Switches
Europe Low Voltage Switchgear Market