
 Military Cable Market | 2026-2036
Military Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Military Cable Market Insights
Defense procurement concentration is decoupling from traditional prime-contractor hierarchies as tier-one system integrators and foreign military sales channels fragment buying authority across multiple national arsenals. Prysmian Group leverages its submarine cable expertise to anchor naval fleet contracts in Mediterranean and Pacific basins. Nexans S.A. sustains manufacturing scale across European defense corridors while TE Connectivity competes on interconnect density for avionics platforms.
Military cables are specialized electrical and optical transmission assemblies engineered to MIL-STD-810 environmental resilience, MIL-DTL-17 coaxial specifications, and flame-retardant jacketing for battlefield survivability; they deliver power, signal, and data integrity across platforms subjected to electromagnetic interference, thermal shock, and mechanical flexure. Optical fiber cables now lead growth in command and control networks where bandwidth requirements outpace copper limitations, while armored technology segments capture margin pools in weapon systems exposed to abrasion and projectile threats. Shielded coaxial configurations remain mature in radar equipment applications where proven interference suppression outweighs substitution risk.
FDA oversight of military medical evacuation systems, FCC Part 15 emissions constraints on tactical radios, and FAA airworthiness directives for airborne cable harnesses collectively elevate compliance costs and barrier thresholds for non-qualified suppliers. NATO standardization agreements and country-specific defense procurement codes further compartmentalize market access across allied territories. Stakeholders must monitor evolving electromagnetic spectrum allocation rules and fiber-optic interoperability mandates to preserve program eligibility and avoid redesign cycles.
Market Dynamics
Pentagon modernization programs and NATO naval fleet upgrades are compressing cable replacement cycles while fragmenting procurement authority across tier-one system integrators and foreign military sales channels.
Growth Catalysts
- MIL-STD-810 Environmental Testing Mandates:Hardened cable specifications for thermal shock and mechanical flexure are expanding qualified supplier pools across combat platform categories.
- Fiber-Optic Bandwidth Expansion:Command and control networks are migrating from copper limitations to optical interconnects for battlefield data integrity.
- Naval Fleet Electrification:Submarine and surface vessel power distribution upgrades are accelerating armored cable assembly procurement in Mediterranean and Pacific basins.
Market Restraints
- Raw Material Concentration:Specialty fluoropolymer jacketing and high-purity copper sourcing depends on limited Asian refining capacity.
- Regulatory Fragmentation:FCC Part 15 emissions constraints on tactical radios and FAA airworthiness directives for airborne harnesses create multi-jurisdiction compliance costs.
- Qualification Timeline Compression:MIL-DTL-17 coaxial certification cycles extend 18-24 months, freezing out non-incumbent suppliers from near-term program slots.
Strategic Opportunities
- Unmanned Platform Electrification:UAV and UUV power distribution architectures require miniaturized, high-flexure cable assemblies with electromagnetic shielding.
- Medical Evacuation System Integration:FDA oversight of military MEDEVAC platforms creates certified supplier niches for biocompatible, flame-retardant interconnects.
- Allied Standardization Convergence:NATO standardization agreements are harmonizing procurement codes across member arsenals, reducing country-specific redesign requirements.
Industry Challenges
- Electromagnetic Spectrum Allocation Uncertainty:Shifting frequency assignments for tactical communications force iterative shielding redesigns and retesting cycles.
- Legacy Platform Integration Complexity:Fiber-optic retrofits into copper-dependent radar and weapons systems require hybrid interconnect architectures and specialized termination training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Cable Market |
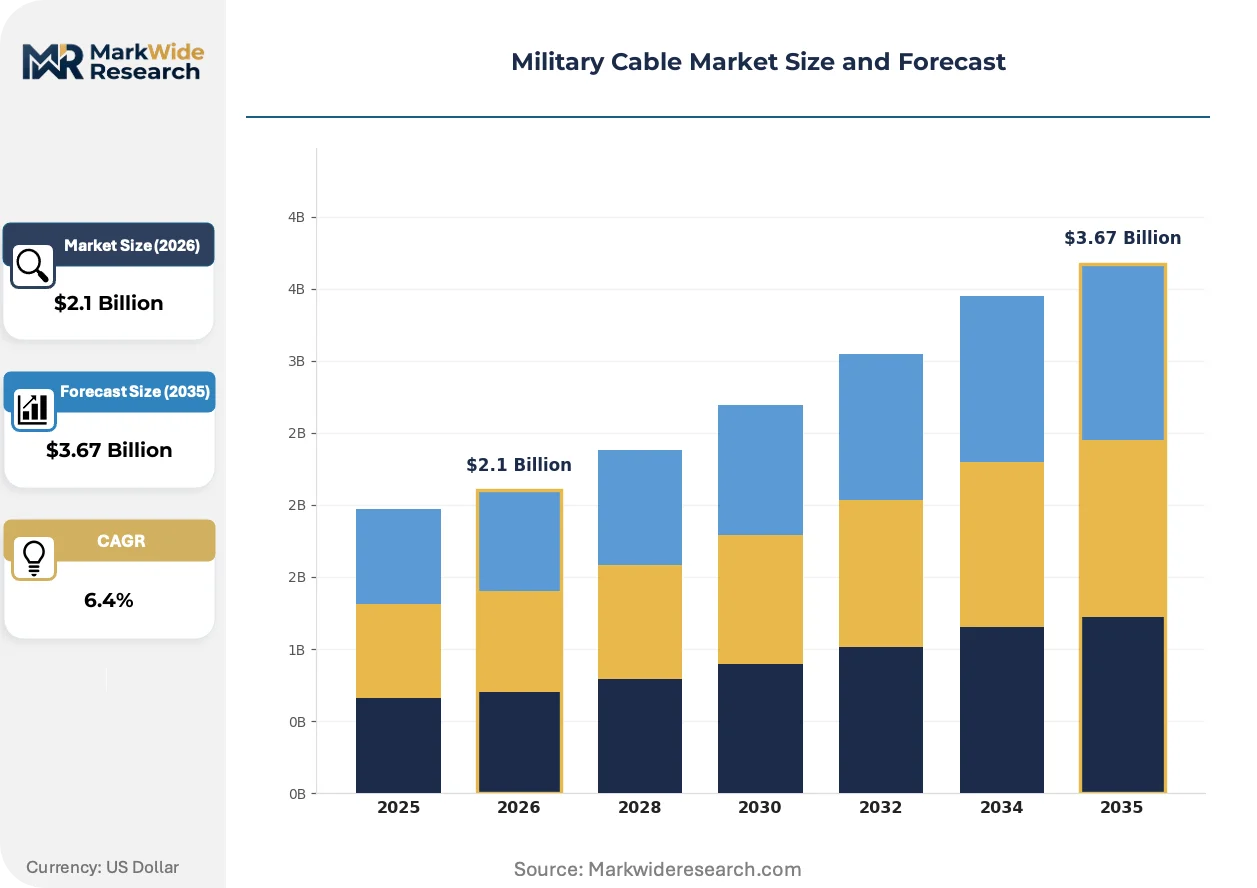
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial Cables, Optical Fiber Cables, Twin Axial Cables, Multicore Cables, Ribbon Cables Technology: Shielded, Armored, Non-Armored, Teflon Insulated, Polyethylene Insulated Application: Communication Systems, Radar Equipment, Weapon Systems, Navigation Devices, Command & Control End User: Defense Contractors, Military Bases, Naval Fleets, Air Forces, Intelligence Agencies |
| Companies Covered | Prysmian Group, Nexans S.A., Sumitomo Electric Industries Ltd, Amphenol Corporation, TE Connectivity, Carlisle Interconnect Technologies, Belden, Southwire Company, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Cable Market Trends and Innovations
Interconnect architectures are fragmenting from monolithic harness designs toward distributed, field-reconfigurable assemblies that reduce platform downtime and simplify battlefield maintenance logistics.
Photonic power-over-fiber systems are modularizing energy delivery for remote sensors and unmanned platforms by eliminating copper conductors in electromagnetic-sensitive environments. Naval research laboratories and airborne ISR program offices are piloting these assemblies for weight reduction and interference immunity. This technology is modularizing traditional power distribution hierarchies into wavelength-multiplexed, software-defined networks that compress physical cable counts while expanding functional density.
EU F-Gas Regulation phase-down schedules are restricting fluorinated polymer production for high-performance cable jacketing, forcing reformulation toward halogen-free flame-retardant compounds. European defense contractors face reformulation costs and requalification timelines for submarine and armored land vehicle applications. Mediterranean naval programs are accelerating supplier diversification into non-fluorinated material streams to preserve program eligibility.
Platform prime contractors are consolidating subsystem procurement under long-term performance-based logistics contracts that bundle cable replacement with availability guarantees. Foreign military sales channels are displacing direct OEM relationships in allied nation procurement, particularly for Pacific basin naval modernization. United States defense contractors are restructuring field service organizations to capture aftermarket cable lifecycle revenue under consolidated platform support agreements.
Military Cable Market Segmentation
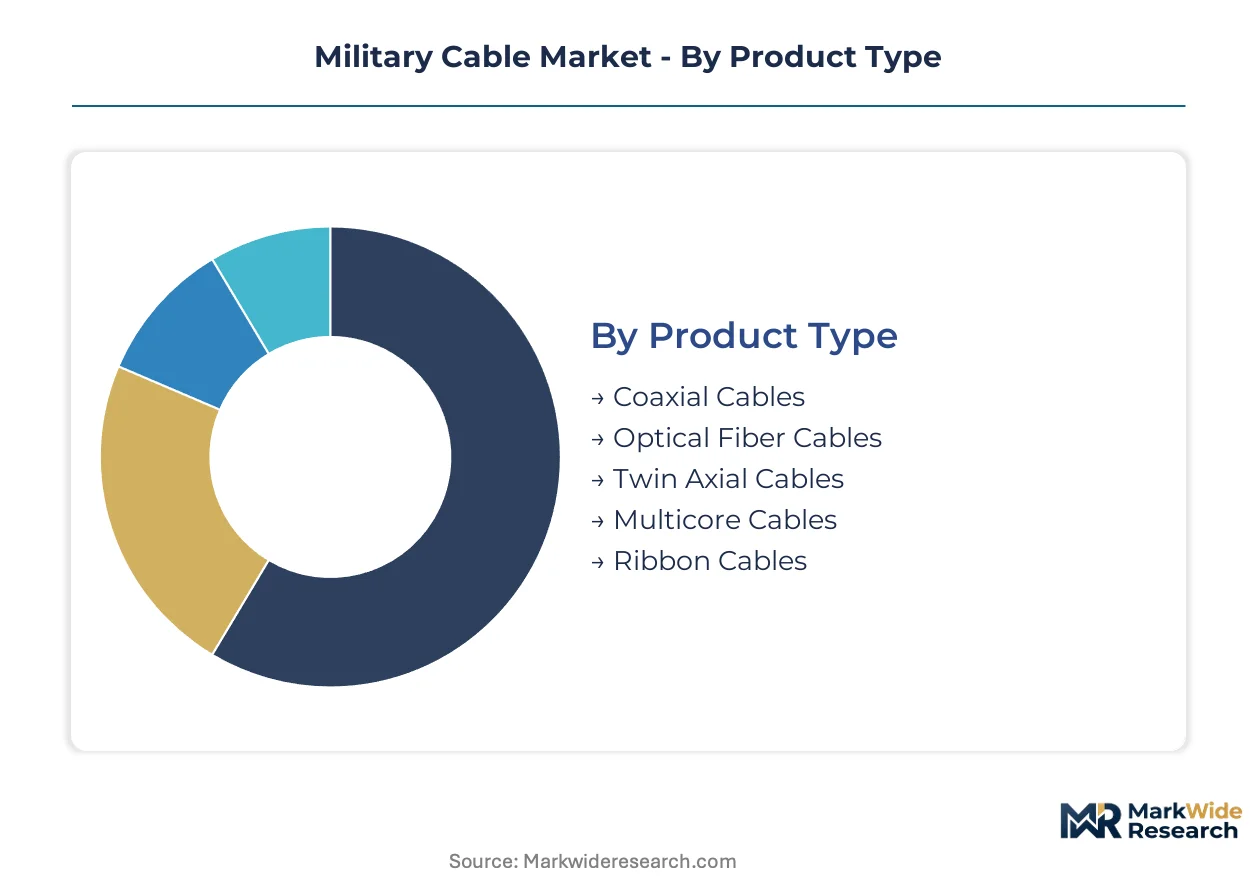
Military cable procurement fragments across technical specifications, environmental hardening levels, and platform-specific integration requirements. Segmentation reveals where supplier qualification investments concentrate and which cable architectures command premium positioning in defense procurement cycles.
Product Type:
Supply concentration tilts toward manufacturers with MIL-DTL-17 coaxial certification and submarine cable assembly capabilities.
- Coaxial Cables:Engineered to MIL-DTL-17 specifications with precision impedance control for radar and communications applications. Pentagon modernization programs and NATO naval fleet upgrades in the United States and Mediterranean basins are compressing replacement cycles for these mature interconnects.
- Optical Fiber Cables:Single-mode and multimode assemblies delivering terabit-scale bandwidth for command and control networks. Demand is concentrating in airborne ISR platforms and naval combat systems where electromagnetic immunity and weight reduction outweigh copper retrofit costs.
- Twin Axial Cables:Paired conductor configurations for balanced differential signaling in avionics databus architectures.
- Multicore Cables:Bundled conductor assemblies reducing harness complexity in vehicle and vessel power distribution.
- Ribbon Cables:Flat conductor arrays for high-density backplane interconnects in rack-mounted communications equipment.
Coaxial cables absorb the bulk of installed capacity; optical fiber cables are expanding most quickly.
Technology:
Cost tiers separate qualified defense suppliers from commercial-grade producers unable to absorb MIL-STD-810 environmental testing overhead.
- Shielded:Metallic braid and foil configurations suppressing electromagnetic interference in tactical radio and electronic warfare platforms. FCC Part 15 emissions constraints on tactical radios in the United States are elevating shielding performance thresholds.
- Armored:Steel or aluminum interlock jackets protecting against abrasion, crush, and projectile threats in ground combat vehicles. Naval fleet electrification programs across Pacific and Mediterranean basins are accelerating procurement for submarine and surface vessel applications.
- Non-Armored:Lightweight assemblies for sheltered infrastructure and fixed communications installations.
- Teflon Insulated:Fluoropolymer dielectrics withstanding thermal shock and chemical exposure in engine-adjacent routing.
- Polyethylene Insulated:Cost-optimized dielectric for benign-environment signal transmission in base infrastructure.
Shielded technology captures the largest qualification investment; armored configurations are climbing the fastest.
Application:
Volume concentration follows platform procurement waves, with naval and airborne programs outpacing ground system refresh rates.
- Communication Systems:Tactical radio, satellite uplink, and network backbone interconnects requiring bandwidth scalability and interference immunity. United States Special Operations Command and NATO allied nation procurement are migrating these systems toward fiber-optic architectures.
- Radar Equipment:Coaxial and waveguide assemblies for active electronically scanned array systems. Legacy platform integration complexity in the United States Air Force fighter modernization programs is sustaining demand for proven copper interconnects despite fiber substitution pressure.
- Weapon Systems:Fire control and guidance cable harnesses subjected to shock, vibration, and thermal cycling.
- Navigation Devices:GPS and inertial reference system interconnects requiring precision signal integrity.
- Command & Control:C4ISR network infrastructure demanding highest-density optical interconnects for battlespace data fusion.
Communication systems absorb the bulk of installed capacity; command and control applications are gaining share fastest.
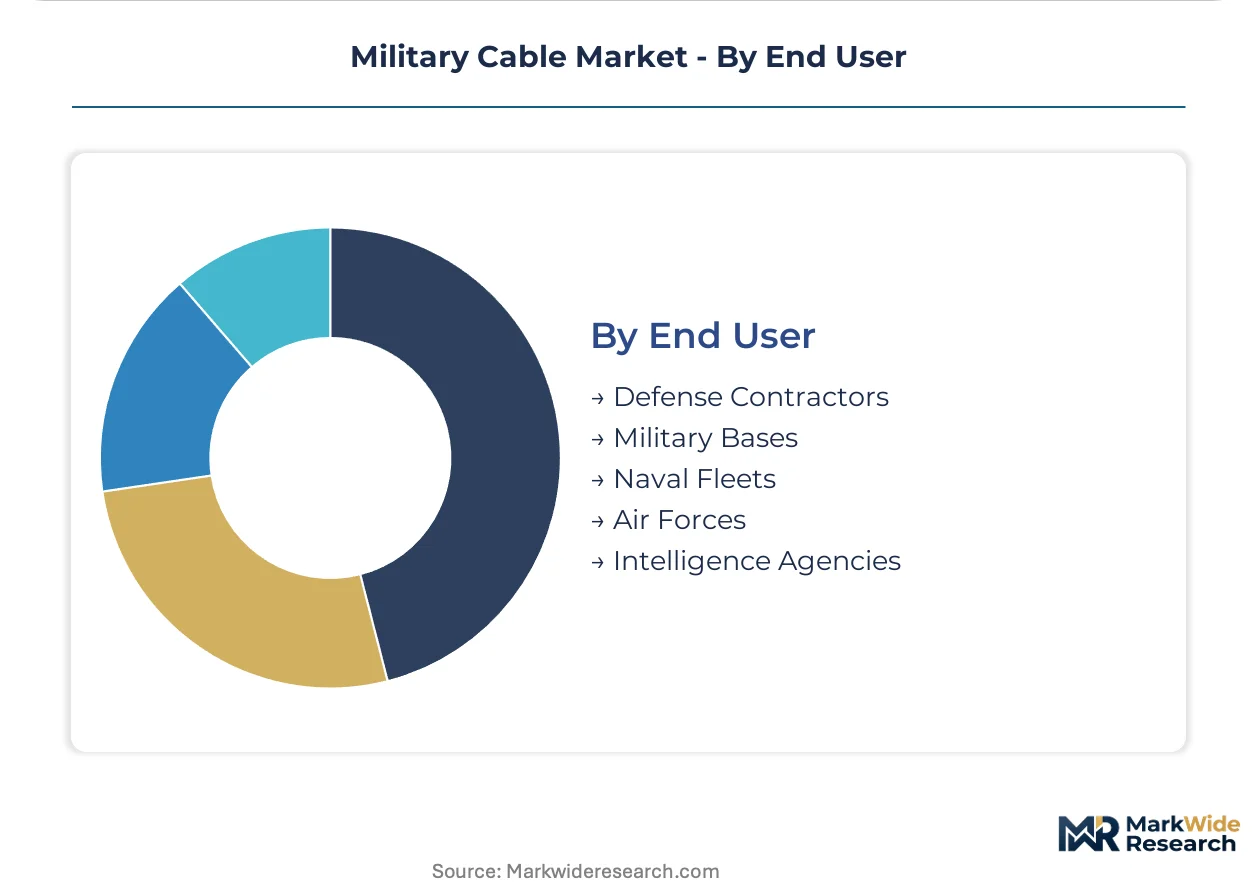
End User:
Customer type determines procurement channel structure, with foreign military sales displacing direct OEM relationships in allied nation markets.
- Defense Contractors:Tier-one system integrators bundling cable procurement under long-term performance-based logistics contracts. United States prime contractors are consolidating subsystem sourcing under platform availability guarantees.
- Naval Fleets:Submarine and surface vessel power distribution and combat system interconnects. Mediterranean and Pacific basin modernization programs are fragmenting procurement authority across foreign military sales channels.
- Military Bases:Fixed infrastructure and training facility cable installations with commercial-grade durability requirements.
- Air Forces:Airborne platform harnesses subject to FAA airworthiness directives and MIL-STD-810 environmental qualification.
- Intelligence Agencies:Specialized communications infrastructure with enhanced electromagnetic security and tamper-evidence specifications.
Defense contractors absorb the bulk of installed capacity; naval fleets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense procurement absorbs the largest share of military cable demand, with Pentagon modernization programs and naval fleet upgrades compressing replacement cycles across combat platforms. Fragmented buying authority now distributes across tier-one system integrators and foreign military sales channels.
United States
Pentagon submarine and surface vessel electrification programs drive armored cable assembly procurement. FCC Part 15 emissions constraints on tactical radios elevate shielding performance thresholds for domestic suppliers. Defense contractors in Connecticut and Virginia cluster around naval shipyard corridors to capture fleet modernization contracts.
Germany
Bundeswehr platform upgrades and NATO standardization agreements concentrate demand for MIL-STD-810 qualified interconnects. EU F-Gas Regulation phase-down schedules force fluoropolymer jacketing reformulation toward halogen-free compounds. Industrial clusters in Bavaria and Baden-Württemberg host specialized cable assembly operations serving European defense corridors.
United Kingdom
Royal Navy fleet renewal and airborne ISR platform procurement sustain coaxial and fiber-optic demand. Ministry of Defence procurement codes align with NATO standardization agreements to reduce supplier qualification barriers. Defense manufacturing concentrates in South England and Scotland around aerospace and naval engineering hubs.
Japan
Maritime Self-Defense Force destroyer and submarine programs accelerate shielded power distribution cable procurement. METI industrial policy supports domestic defense supply chain resilience for critical interconnect technologies. Manufacturing activity clusters in the Chubu region around Nagoya-based system integrators and component suppliers.
France
Naval Group submarine and surface combatant programs drive armored cable specifications for Mediterranean and Pacific basin deployments. ANSM oversight of military medical evacuation systems creates certified supplier niches for biocompatible interconnects. Defense industrial activity concentrates in Provence-Alpes-Côte d'Azur and Brittany around naval shipyards and aerospace clusters.
Military Cable Market Competitive Landscape
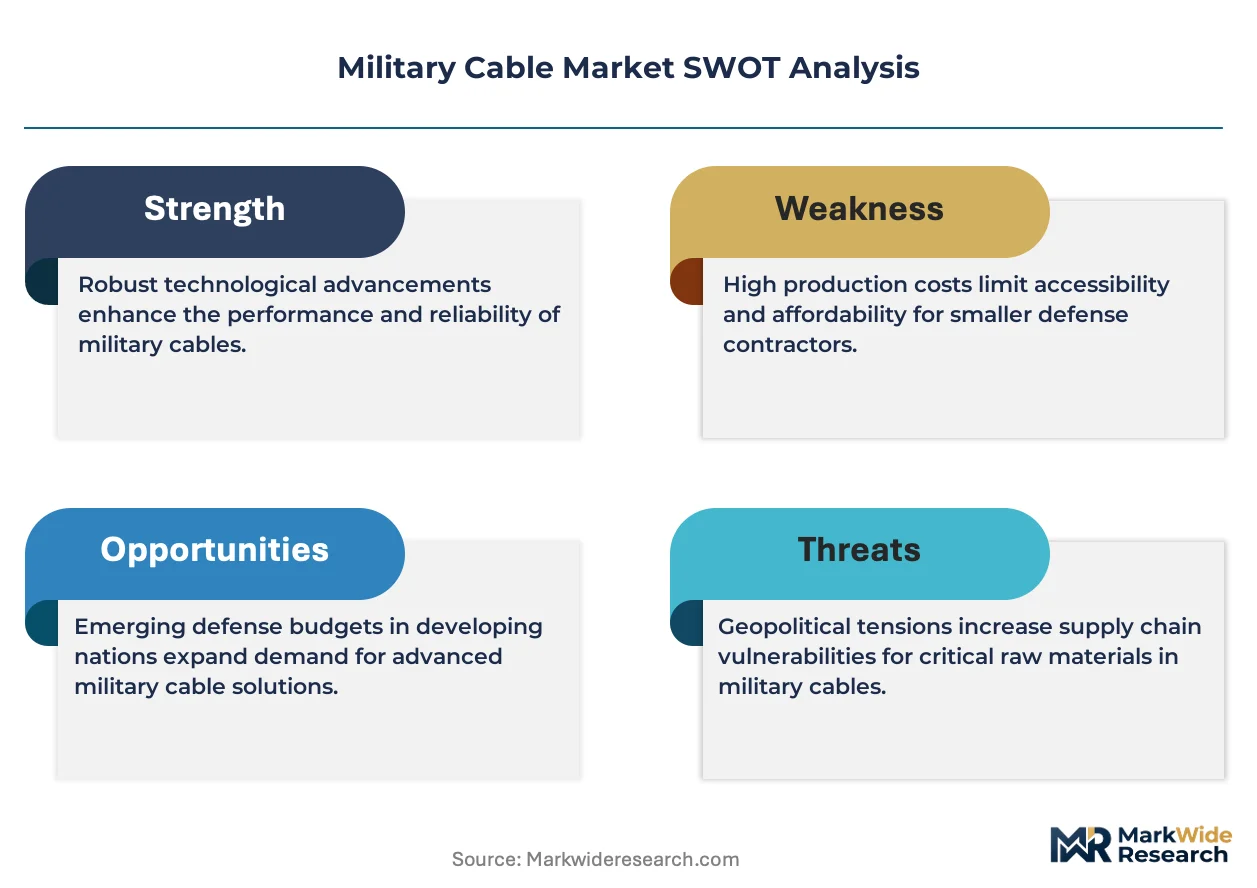
North American producers anchor one tier; European specialists hold qualification depth across NATO procurement channels. Market structure tilts toward consolidated tier-one system integrators bundling cable procurement under long-term performance-based logistics contracts. Two strategic archetypes dominate: submarine cable specialists leveraging naval expertise and avionics interconnect providers competing on density and weight reduction. Competitive moves concentrate on geographic expansion through foreign military sales channels and portfolio diversification into fiber-optic architectures.
Within the submarine cable tier, Prysmian Group and Nexans S.A. represent European-anchored specialists with Mediterranean and Pacific basin naval exposure. TE Connectivity occupies a position exemplifying interconnect density competition for airborne platforms. These three entities sit within distinct archetype categories—submarine systems, European defense corridors, and avionics miniaturization—rather than direct overlap.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans S.A. |
| Sumitomo Electric Industries Ltd |
| Amphenol Corporation |
| TE Connectivity |
| Carlisle Interconnect Technologies |
| Belden |
| Southwire Company |
| Collins Aerospace |
| Others |
Pricing and Supply Chain Analysis
Specialty fluoropolymer jacketing costs cascade from limited Asian refining capacity through three distinct pricing tiers, with MIL-DTL-17 coaxial certification separating premium defense-qualified suppliers from commercial-grade producers unable to absorb qualification overhead. High-purity copper sourcing and EU F-Gas Regulation phase-down schedules further stratify procurement economics across NATO arsenals and Pacific basin naval programs.
Pricing Analysis
Volume concentrates in shielded coaxial configurations while margins pool in armored fiber-optic assemblies for submarine applications. Pricing stratifies across MIL-STD-810 qualified, defense-grade commercial, and industrial-tier levels based on certification depth and environmental hardening. Cost compression in standard shielded copper runs through raw material concentration in Asian refining corridors. Foreign military sales channels exhibit highest price sensitivity due to bundled platform procurement, whereas intelligence agency specifications show lowest sensitivity given security-driven sole-source requirements.
Supply Chain Analysis
MIL-DTL-17 coaxial certification cycles lasting 18-24 months gate supplier entry and freeze procurement relationships with incumbent qualified manufacturers. Production concentrates in the United States, Germany, and Japan around naval shipyard corridors and aerospace engineering hubs. Raw material flows draw from high-purity copper refining in Asia, fluoropolymer compound production in Europe, and specialty optical fiber drawing in Japan and the United States. Single-source vulnerability in Asian refining capacity for jacketing polymers exposes NATO procurement to tariff and logistics disruption. Distribution runs through tier-one system integrators bundling cable replacement under performance-based logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Military Cable Market sits in a technology-transition phase as fiber-optic architectures displace copper-dependent radar and command networks. Photonic power-over-fiber systems and wavelength-multiplexed interconnects are modularizing traditional power distribution hierarchies.
For Market Incumbents: Deploy performance-based logistics contracting to capture aftermarket lifecycle revenue and lock out non-qualified competitors. Deepen backward integration into specialty fluoropolymer compound production to hedge EU F-Gas Regulation supply constraints. Consolidate field service organizations around platform availability guarantees to counter foreign military sales channel fragmentation. For New Entrants and Emerging Players: Unmanned platform electrification programs present the most penetrable buyer archetype given miniaturized high-flexure requirements and absence of entrenched supplier relationships. Medical evacuation system integration offers certified supplier niches under FDA oversight with lower qualification barriers than combat platform categories. Pursue direct relationships with tier-two UAV and UUV subsystem integrators rather than competing for prime-contractor slots. For Investors and Strategic Acquirers: NATO standardization agreement harmonization is the leading indicator that procurement code consolidation will accelerate M&A activity across European defense corridors. Five-to-ten year viability favors submarine cable specialists with Mediterranean and Pacific basin naval exposure over pure-play avionics interconnect providers facing fiber substitution pressure. Monitor electromagnetic spectrum allocation rule changes as the inflection signal for shielding redesign cycles and retesting revenue windows.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-810 Qualification Investment | Defense contractors in Connecticut and Virginia corridors secure naval fleet modernization slots. |
| Fluoropolymer Reformulation Program | European suppliers preserve NATO program eligibility under EU F-Gas Regulation phase-down schedules. |
| Fiber-Optic Architecture Migration | Airborne ISR platforms in United States Special Operations Command reduce weight and electromagnetic vulnerability. |
| Performance-Based Logistics Contracting | Prime contractors bundle cable replacement with platform availability guarantees across foreign military sales channels. |
| Photonic Power-over-Fiber Pilot | Naval research laboratories modularize energy delivery for electromagnetic-sensitive unmanned platforms. |
Research Methodology
Multi-period observation of Pentagon modernization program announcements, NATO naval fleet upgrade schedules, and foreign military sales contract awards anchored the trend analysis, supplemented by interviews with defense procurement officers, cable assembly plant managers, tier-one system integrator sourcing executives, and military standards qualification engineers. Secondary validation drew from Department of Defense budget justification documents, NATO standardization agreement databases, SEC 10-K filings from listed defense contractors, and customs trade data for high-purity copper and fluoropolymer imports. Bottom-up segment sizing triangulated against top-down defense expenditure allocation models.
Segment-weighting approaches distributed value across product type, technology tier, application platform, and end-user procurement channel dimensions throughout the forecast period. CAGRs derived from replacement cycle compression rates, platform electrification adoption curves, and fiber-optic substitution elasticities in command and control networks. Modeling incorporated electromagnetic spectrum allocation rule uncertainty, EU F-Gas Regulation phase-down timelines, and foreign military sales channel displacement rates as scenario variables.
Revisions become necessary when Pentagon program cancellation announcements, NATO procurement code harmonization delays, or raw material supply disruptions from Asian refining capacity materialize. Forecasts reflect assumptions regarding qualification timeline stability and allied defense expenditure commitments. A model refresh is warranted upon material change in electromagnetic spectrum allocation rules or fiber-optic interoperability mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Copper Stranded Wire Market
Cables
Europe HVAC Cables Market
Cables
India Wire and Cable Market
Cables
GCC Cable Accessories Market
Cables
Multicore Cables Market
Cables
Asia-Pacific Premise Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Cable Flange Market
Cables
Europe Cable Accessories Market
Cables
Sensor Cable Market
Cables
Electric Submersible Cable Sales Market
Cables
Solar Cable Market
Cables
North America HVAC Cables Market
Cables
Fire Resistance Cable Market
Cables
Copper Cabling Systems Market
Cables
High Voltage Cable Termination Market