
 Military Fiber Optic Cables Market | 2026-2036
Military Fiber Optic Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Military Fiber Optic Cables Market Foresight
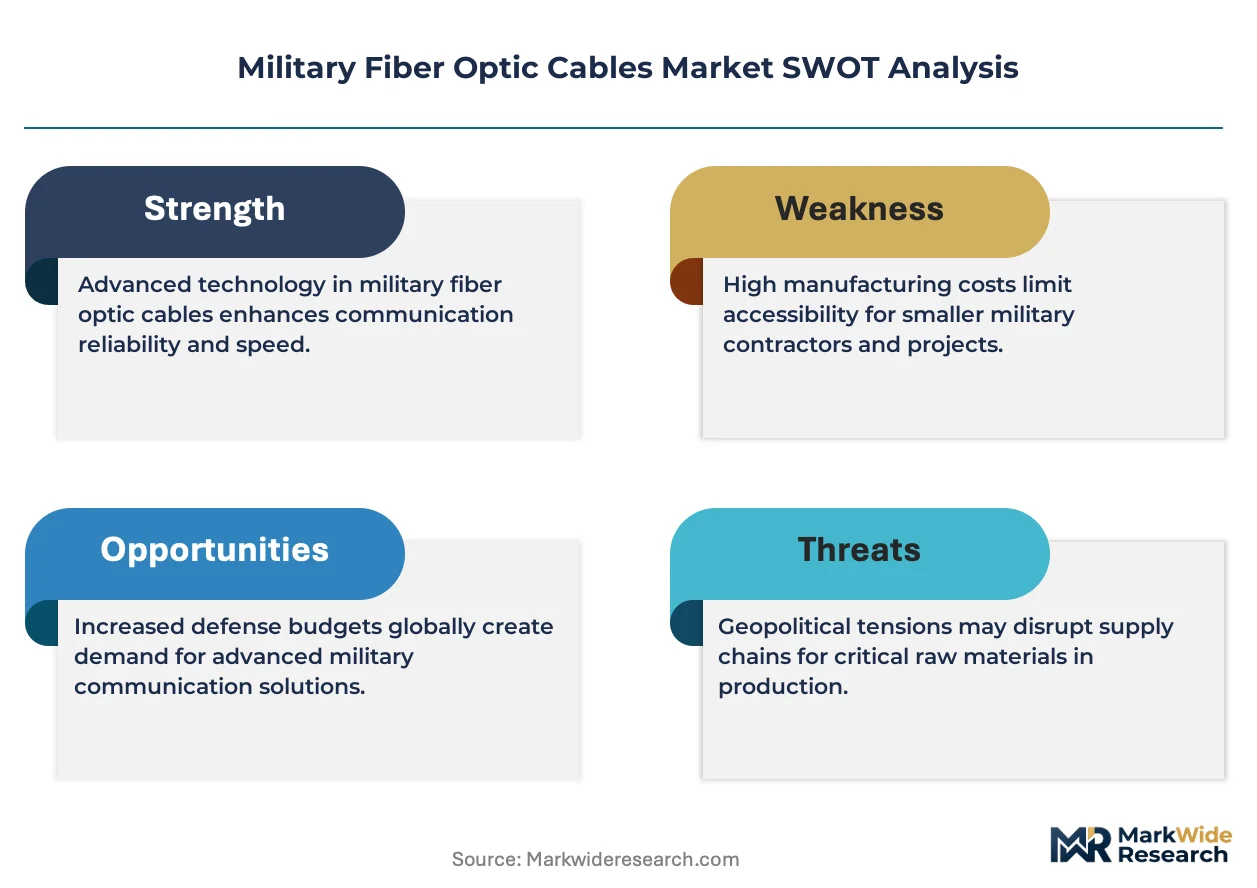
Polyimide coatings are replacing traditional acrylate buffers in harsh-environment military fiber, and this material substitution is repositioning cost structures across the supply base. Prysmian Group leverages integrated glass-drawing and cable-assembly operations to sustain price competitiveness in European defense tenders. TE Connectivity anchors its position through MIL-STD-810H qualification breadth, while W.L. Gore & Associates differentiates via fluoropolymer-jacketed fibers optimized for chemical-exposure scenarios.
Military fiber optic cables deploy silica-core waveguides with specialized jacketing—polyimide, fluoropolymer, or metal armor—to survive temperature extremes, mechanical abrasion, and chemical attack in battlefield conditions; typical designs achieve insertion loss below 0.5 dB/km at 1550 nm for single-mode variants, with bend-insensitive geometries enabling tight-radius routing inside armored vehicles and aircraft avionics bays. The armored product category dominates current procurement volumes given its integration into ground-vehicle turret networks and forward operating base trunk lines, while airborne deployment configurations represent the fastest-expanding segment as fifth-generation fighter platforms multiply internal fiber runs to reduce electromagnetic signatures. Single-mode fibers command premium positioning in long-haul shipboard and inter-facility applications where attenuation budgets are tight.
The U.S. Department of Defense's MIL-PRF-49291 and MIL-STD-810H frameworks mandate environmental and mechanical survivability thresholds that filter non-compliant suppliers from contention, while the EU's CE marking and RoHS substance restrictions shape material choices for NATO-interoperable equipment sold into European forces. The U.S. Federal Communications Commission and FAA coordinate spectrum-management policies that indirectly accelerate fiber substitution for copper in command-and-control networks. Stakeholders must monitor evolving electromagnetic-pulse hardening specifications and dual-use export control classifications as determinants of addressable market scope.
Market Dynamics
The U.S. Department of Defense's electromagnetic interference tightening is forcing platform-wide cable replacement cycles across naval, airborne, and ground combat systems simultaneously.
Growth Catalysts
- Carrier fleet modernization:The United States Navy's Ford-class and Virginia-class programs are mandating fiber backbone upgrades for integrated combat systems, creating sustained procurement pipelines through 2035.
- MIL-STD-810H qualification breadth:Expanded environmental testing requirements are disqualifying legacy suppliers and consolidating demand around certified manufacturers with in-house qualification capabilities.
- Polyimide coating substitution:Material advances in harsh-environment buffers are extending cable lifespans in turret networks and forward operating bases, reducing total cost of ownership for defense procurement officers.
Market Restraints
- High-purity silica supply concentration:Specialty fiber preform manufacturing clusters in Japan and Germany create geopolitical exposure for Western defense supply chains.
- Dual-use export control friction:U.S. International Traffic in Arms Regulations and EU dual-use classifications restrict vendor addressable markets and complicate NATO interoperability certification.
- Copper legacy infrastructure:Existing armored vehicle and aircraft harnesses represent sunk capital that delays fiber substitution despite electromagnetic signature advantages.
Strategic Opportunities
- Unmanned systems proliferation:Autonomous underwater vehicles and tactical drones require miniature, high-bandwidth fiber runs that open new specification tiers beyond traditional platform categories.
- Pacific theater posture requirements:U.S. Indo-Pacific Command's distributed maritime operations doctrine is driving demand for ship-to-shore and expeditionary fiber trunk lines in Guam, Japan, and Australia.
- Electromagnetic-pulse hardening mandates:Emerging Pentagon specifications for nuclear event survivability are creating premium product categories with qualification barriers that favor established defense suppliers.
Industry Challenges
- Specialized termination technician scarcity:Military-grade fiber splicing and connectorization requires cleared personnel with both optical engineering and security clearance credentials that exceed commercial labor pool availability.
- MIL-PRF-49291 compliance timeline compression:Accelerated platform deployment schedules are compressing qualification windows and forcing parallel rather than sequential testing pathways that elevate program risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Fiber Optic Cables Market |
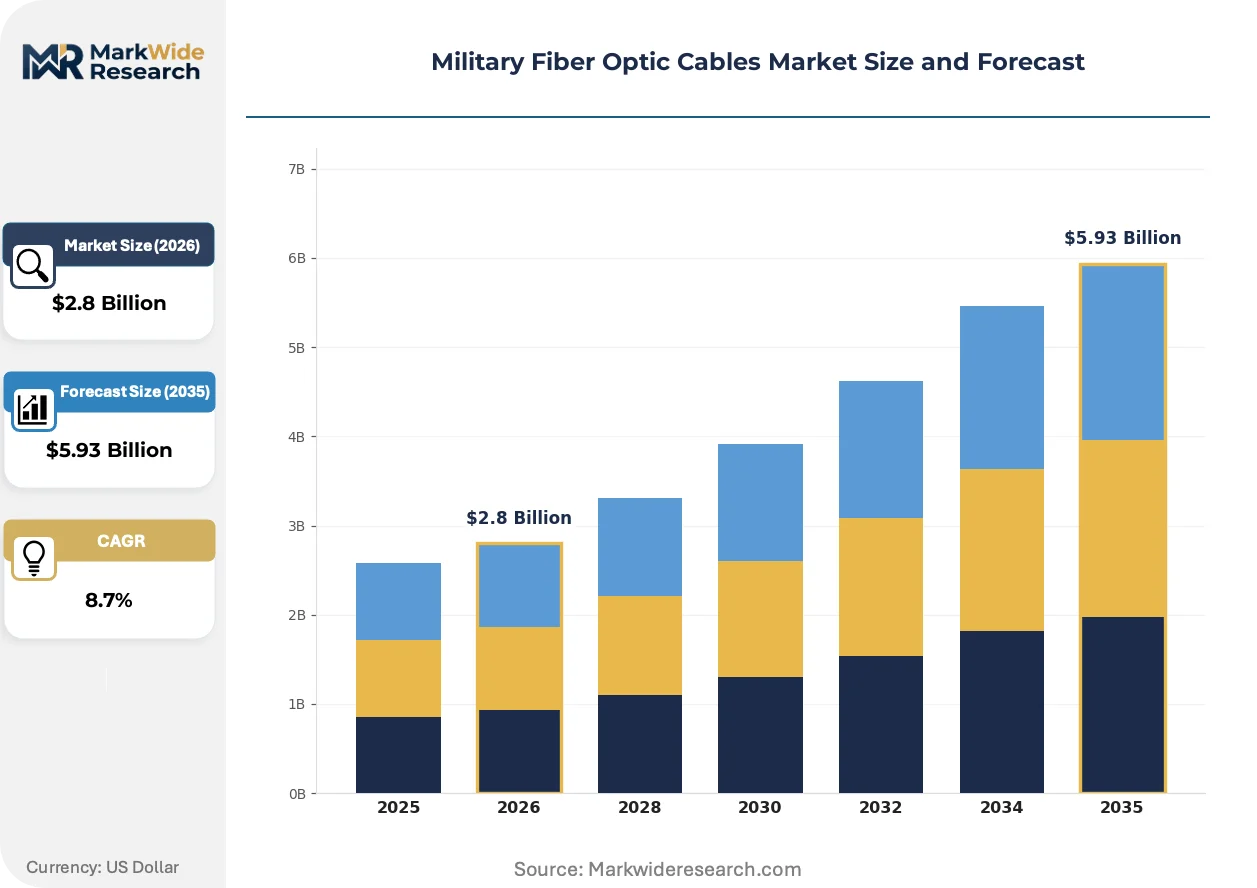
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Armored, Loose Tube Deployment: Ground, Airborne, Marine, Tactical Material: Glass, Plastic, Hybrid, Copper Application: Communication, Surveillance, Data Transmission, Weapon Systems |
| Companies Covered | Prysmian Group, Amphenol Corporation, TE Connectivity, Corning Incorporated, Carlisle Interconnect Technologies, Sumitomo Electric Industries, W.L. Gore & Associates, Optical Cable Corporation, Radiall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Fiber Optic Cables Market Shifts & Advancements
Bend-insensitive fiber geometries are penetrating armored vehicle avionics bays and fifth-generation fighter internal routing systems where space constraints previously forced copper retention.
Robotic fiber handling systems are automating precision cleaving and fusion splicing in cable assembly operations, enabling defense contractors to meet MIL-STD-810H repeatability standards at throughput rates previously unattainable with manual methods. Naval shipyards in the United States and United Kingdom are deploying these systems for carrier fiber backbone installations.
The European Union's RoHS substance restrictions and CE marking requirements are reshaping material selection for NATO-interoperable equipment, compelling suppliers to reformulate jacketing compounds and document supply chain provenance for defense tenders in Germany, France, and Italy. Polymer suppliers are accelerating halogen-free compound development cycles to maintain qualification status.
Defense procurement officers are consolidating vendor relationships around full-spectrum qualification holders, compressing supplier panels from multi-vendor competitive bidding to sole-source or dual-source arrangements for platform-critical fiber systems. This concentration is most visible in U.S. Navy shipbuilding programs where electromagnetic signature reduction has become a design-mandated priority rather than optional upgrade.
Military Fiber Optic Cables Market Segmentation
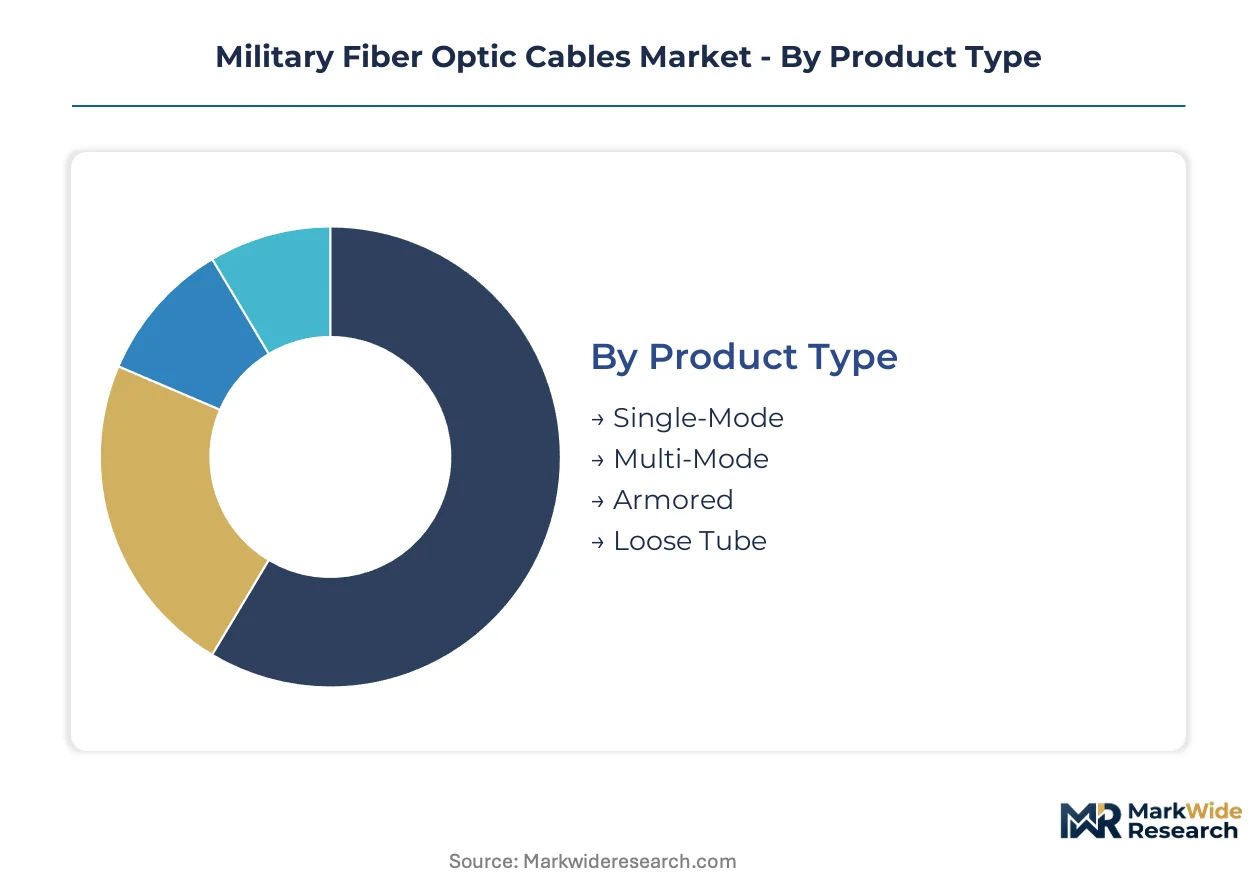
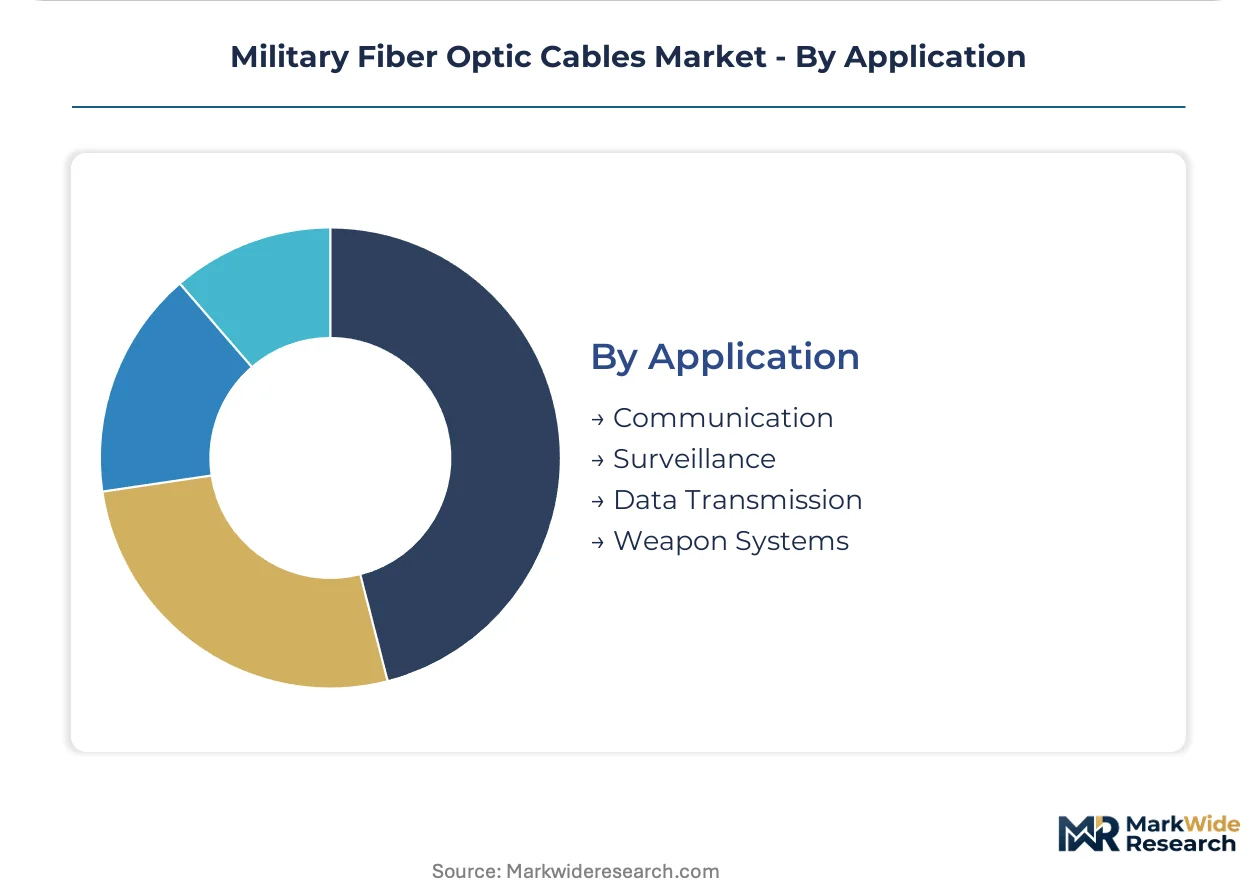
Military fiber optic cable procurement operates through distinct technical and operational lenses that shape supplier qualification pathways and program award probabilities. Segmentation clarity enables vendors to align R&D investments with platform-specific survivability mandates and electromagnetic signature requirements.
Product Type:
Supply concentration in harsh-environment buffers favors manufacturers with captive polymer formulation capabilities and in-house drawing towers.
- Single-Mode:Silica-core waveguides with tight mode-field diameters achieve insertion loss below 0.5 dB/km at 1550 nm. U.S. Navy shipboard trunk lines and Pacific theater inter-facility links concentrate procurement here, driven by attenuation budgets in carrier combat systems.
- Multi-Mode:Larger core geometries support short-reach, high-bandwidth runs inside armored vehicle turrets and avionics bays. Ground combat system modernization programs in the United States favor this category for cost-managed platform upgrades.
- Armored:Metal-jacketed designs dominate current procurement volumes across forward operating base trunk lines and vehicle harnesses.
- Loose Tube:Gel-filled buffer structures accommodate thermal expansion in expeditionary deployments and temporary tactical installations.
Today's leader: Armored. Tomorrow's challenger: Single-Mode.
Deployment:
Cost tier stratification separates platform-integrated systems from expeditionary kit procurement, with qualification burden scaling accordingly.
- Ground:Armored vehicle turret networks and forward operating base infrastructure constitute the largest installed base. U.S. Army modernization timelines compress supplier delivery windows for Stryker and Abrams platform retrofits.
- Airborne:Fifth-generation fighter internal routing systems demand bend-insensitive geometries and weight-optimized jacketing. The fastest-expanding segment as electromagnetic signature reduction becomes design-mandated rather than optional.
- Marine:Carrier and submarine combat system backbones require pressure-resistant, corrosion-proof terminations.
- Tactical:Rapidly deployable spool-based systems support expeditionary and special operations requirements.
Current procurement weight: Ground. Steepest expansion trajectory: Airborne.
Material:
Volume concentration in glass-core solutions reflects defense procurement officer preference for proven optical performance under thermal and mechanical stress.
- Glass:High-purity silica waveguides command platform-critical applications where attenuation and radiation hardness determine mission success. Supply chains cluster in Japan and Germany for specialty preforms.
- Plastic:Polymethyl methacrylate cores serve short-reach, high-flexure tactical patches where weight reduction outweighs optical performance penalties.
- Hybrid:Glass-plastic composite structures balance handling durability with signal integrity for unmanned systems and drone tether applications.
- Copper:Legacy coaxial and twisted-pair harnesses persist in backward-compatible retrofits where fiber conversion costs exceed electromagnetic signature benefits.
Established standard: Glass. Emerging alternative: Hybrid.
Application:
Customer type differentiation separates platform prime contractors from subsystem integrators, with specification authority residing at different program tiers.
- Communication:Command-and-control network backbones prioritize MIL-STD-810H environmental qualification and electromagnetic-pulse hardening. U.S. Indo-Pacific Command distributed operations doctrine drives ship-to-shore trunk line demand in Guam and Japan.
- Surveillance:Sensor fusion architectures require low-latency, high-fidelity optical links for electro-optical and signals intelligence payloads. Intelligence community procurement channels impose security clearance requirements on installation technicians.
- Data Transmission:High-bandwidth computing and storage interconnections support C4ISR platform upgrades.
- Weapon Systems:Fire control and targeting networks demand deterministic latency and mechanical survivability in turret traverse environments.
Procurement volume leader: Communication. Fastest specification evolution: Weapon Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hampton Roads naval cluster anchors military fiber demand through carrier combat system modernization and submarine fiber backbone installations at Newport News Shipbuilding and Norfolk Naval Shipyard.
United States
Ford-class and Virginia-class programs drive sustained procurement pipelines through 2035, with the Department of Defense's MIL-STD-810H qualification requirements filtering supplier pools. FCC and FAA spectrum coordination accelerates fiber substitution for copper in command networks. San Diego and Pearl Harbor shipyards concentrate Pacific theater installation capacity for Indo-Pacific Command distributed operations.
United Kingdom
Carrier strike group modernization and Astute-class submarine programs sustain demand for pressure-resistant terminations. Defence Equipment and Support procurement channels impose CE marking and RoHS compliance for NATO-interoperable systems. Portsmouth Naval Base and Barrow-in-Furness represent the primary industrial concentration for naval fiber integration.
Germany
Type 212 submarine exports and Boxer armored vehicle retrofits create dual procurement channels for armored and single-mode fiber categories. KBA and federal procurement offices enforce REACH substance documentation for jacketing compounds. Kiel and Bremen shipyards specialize in submarine fiber backbone installations for European and export customers.
Japan
Mogami-class frigate construction and Izumo-class carrier modifications drive shipboard fiber demand amid Maritime Self-Defense Force expansion. METI and JIS standards shape domestic qualification pathways for defense suppliers. Yokosuka and Kure naval districts concentrate installation and maintenance capabilities for Pacific fleet requirements.
Australia
Hunter-class frigate and AUKUS submarine commitments position the country as a long-term demand center for naval-grade fiber systems. TGA and Defence export controls govern technology transfer protocols for U.S. and UK suppliers. Osborne Naval Shipyard in South Australia and Henderson in Western Australia form the industrial backbone for domestic assembly and integration.
Military Fiber Optic Cables Market Competitive Landscape
Global majors compete with regional champions across qualification breadth and geographic proximity to naval shipyards, producing a tiered structure where full-spectrum MIL-STD holders capture platform-critical contracts while regional specialists serve retrofit and maintenance channels. Three archetypes dominate: integrated cable manufacturers with captive fiber drawing, specialized harness assemblers with security-cleared workforces, and materials innovators with proprietary jacketing formulations. Competitive moves concentrate on strategic partnerships with prime contractors and in-house qualification capability expansion to compress delivery timelines.
Among European integrated manufacturers, Prysmian Group exemplifies the scale-driven archetype with glass-drawing and cable-assembly operations. TE Connectivity anchors the qualification-breadth tier through MIL-STD-810H environmental testing capabilities. W.L. Gore & Associates occupies a position within the materials innovation segment, with fluoropolymer expertise translating into specialized jacketing solutions for chemical-exposure scenarios.
| Leading Market Players |
|---|
| Prysmian Group |
| Amphenol Corporation |
| TE Connectivity |
| Corning Incorporated |
| Carlisle Interconnect Technologies |
| Sumitomo Electric Industries |
| W.L. Gore & Associates |
| Optical Cable Corporation |
| Radiall |
| Others |
Supply & Pricing Matrix
Cleared fiber-optic termination technicians in the Hampton Roads naval cluster command wage premiums that widen spreads between MIL-STD-810H certified assemblies and commercial-grade alternatives. Labor-cost differentials between security-cleared U.S. defense corridors and European NATO supply bases are repositioning procurement arbitrage strategies for platform-critical cable systems.
Pricing Analysis
Input-cost pass-through from high-purity silica preforms and specialized polyimide buffer compounds dominates pricing structures across armored and single-mode product tiers. Three-tier pricing structure across MIL-PRF-49291 qualified, CE-marked NATO-interoperable, and commercial-hardened levels separates platform-critical shipboard installations from expeditionary retrofit kits. Pricing pressure stems from carrier fleet modernization timelines compressing supplier delivery windows. Ground vehicle retrofit programs exhibit highest price sensitivity due to copper legacy infrastructure sunk costs, while airborne fifth-generation fighter programs show lowest sensitivity given electromagnetic signature mandates.
Supply Chain Analysis
Workforce availability constraints in Japanese and German specialty preform manufacturing centers are tightening feedstock access for Western defense cable assemblers. Geographic supply concentration clusters in Japan, Germany, and the United States for high-purity silica waveguides, polyimide coating formulations, and fluoropolymer jacketing compounds. Raw material dependencies center on semiconductor-grade silicon tetrachloride, specialty polymer resins, and corrosion-resistant metal armor alloys. Single-source vulnerability in Japanese preform drawing capacity creates geopolitical exposure. Distribution runs through prime contractor tier-1 harness assemblers with security-cleared installation workforces at Newport News, San Diego, and Pearl Harbor naval facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where U.S. wage premiums for cleared technicians against European NATO supply bases create cost-structure differentiation for qualification-breadth investments.
For Market Incumbents: Acquire in-house MIL-STD-810H environmental testing facilities to compress qualification timelines against accelerated Ford-class and Virginia-class deployment schedules. Consolidate backward integration into specialty polymer formulation to defend margin position from Japanese and German preform supply concentration risks. Certification investment in electromagnetic-pulse hardening specifications creates platform-lock advantages as Pentagon nuclear survivability mandates emerge. For New Entrants and Emerging Players: Direct-to-prime-contractor digital procurement channels offer lowest barrier-to-entry pathways for unmanned systems miniature fiber specifications. White-space concentrates in autonomous underwater vehicle tether applications and tactical drone high-flexure runs where traditional platform categories lack optimized solutions. Target Australian Hunter-class and AUKUS submarine integration programs through TGA-compliant qualification pathways as Pacific theater posture requirements expand. For Investors and Strategic Acquirers: Defense prime contractors with captive cable assembly divisions are the most active acquirer in this space, seeking to internalize electromagnetic signature reduction capabilities. Long-term viability centers on five-to-ten year carrier modernization and Indo-Pacific distributed operations commitments. Acquisition target archetype: regional harness assemblers with security-cleared workforces and existing MIL-PRF-49291 qualification breadth. Signal to watch: electromagnetic-pulse hardening specification finalization as determinant of premium product category addressable scope.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Formulation | Captive polyimide buffer production insulates margins from ECHA REACH compliance cost volatility in European NATO tenders. |
| MIL-STD-810H Qualification Expansion | Broad environmental testing credentials filter competitors from Ford-class carrier combat system fiber backbone awards. |
| Pacific Theater Installation Capacity Buildout | Guam and Japan-based technical teams capture Indo-Pacific Command distributed operations trunk line demand. |
| Unmanned Systems Specification Development | Miniature bend-insensitive geometries open specification tiers beyond traditional ground-airborne-marine platform categories. |
| Electromagnetic-Pulse Hardening Certification | Pentagon nuclear survivability mandates create qualification barriers favoring established defense suppliers with testing infrastructure. |
Research Methodology
Multiple input streams — defense procurement officer interviews, prime contractor supply chain manager discussions, naval shipyard technical director consultations, and regulatory affairs specialist exchanges — were reconciled against secondary validation from U.S. Department of Defense budget justification documents, NATO standardization office publications, FCC and FAA spectrum coordination filings, and EU Defence Equipment and Support tender databases. Bottom-up platform-level cable content estimates and top-down defense electronics spending allocations were triangulated to establish market sizing boundaries.
Data-stream reconciliation across product type, deployment configuration, material composition, and application function dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from platform deployment schedule modeling and electromagnetic signature reduction mandate adoption curves. Forecast inputs incorporated Virginia-class submarine production rates, F-35 internal fiber run specifications, and Stryker modernization retrofit timelines as volume drivers.
The model assumes a particular technology adoption path; alternative pathways for copper-to-fiber substitution in legacy armored vehicle harnesses would alter the outlook. Forecasts reflect documented assumptions regarding MIL-STD-810H qualification timeline compression and Pacific theater posture commitment durability. Material deviation in electromagnetic-pulse hardening specification finalization or Japanese preform export control tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Drum Market
Cables
Class 1E Electric Cables Market
Cables
Submarine Communication Cables Market
Cables
Instrumentation Cables Market
Cables
High-Temperature Superconducting Cables Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
Electric Vehicle Cables Market
Cables
Electric Submersible Cable Sales Market
Cables
Global Wires and Cables Market
Cables
Low Voltage Cable Accessories Market
Cables
Mexico Wires and Cables Market
Cables
Low-Temperature Cable Market
Cables
Submarine Cable System Market
Cables
Anti-Static Space Wires Market
Cables
Single Core Cables Market
Cables
Power and Signal Cables Market