
 Finger Splint Market | 2026-2036
Finger Splint Market Size, Share, and Industry Trends Forecast 2026-2036
Finger Splint Market Analysis
The capital-intensity divergence between automated thermoforming operations and manual assembly benches is unwinding competitive parity among established suppliers. 3M leverages polymer science capabilities to sustain premium positioning across hospital purchasing networks. Zimmer Biomet anchors its presence through orthopedic surgeon training programs and institutional contracts. Smith & Nephew differentiates via wound-care adjacencies that bundle splint products with dressing portfolios.
A finger splint is a rigid, semi-rigid, or dynamic orthopedic device fabricated from aluminum, polyethylene, neoprene, or thermoplastic materials, designed to immobilize phalangeal joints, maintain tendon alignment, or permit controlled range-of-motion during healing. These devices serve primary commercial purposes across fracture management, post-operative protection, and repetitive strain injury protocols in clinical and athletic settings. Elastic splints and finger wraps command expanding share in home care channels where self-application and washability drive replacement cycles. Rigid splints manufactured from molded plastics retain margin concentration in hospital emergency departments and surgical centers where reimbursement codes favor durable medical equipment. Dynamic splint systems, though narrower in volume, occupy the highest price tier through calibrated tension mechanisms and occupational therapy integration.
The FDA's 510(k) notification process governs market entry for Class I splint devices, while ISO 13485 quality management certification shapes supplier eligibility for European distribution through CE marking requirements. The EU Medical Device Regulation (MDR) intensifies clinical documentation burdens for polymer and metal-based immobilization products, filtering smaller manufacturers from cross-border participation. Stakeholders must monitor evolving reimbursement classifications for outpatient hand therapy and assess material substitution risks as bio-based polymers advance through orthopedic device testing protocols.
Market Dynamics
The finger splint market faces intensifying pressure from automated manufacturing scale economics, where thermoforming equipment investments above $2 million per line are compressing margins for manual assemblers and forcing consolidation among mid-tier suppliers.
Growth Catalysts
- Collegiate athletic procurement:NCAA Division I sports medicine programs are expanding dynamic splint inventory for finger injury protocols, creating institutional demand pull.
- FDA 510(k) pathway efficiency:Class I device clearance timelines averaging 90 days accelerate product iteration cycles for polymer-based designs.
- Direct-to-consumer channel maturation:Amazon and specialized orthopedic e-commerce platforms are bypassing traditional durable medical equipment distributors for elastic splint categories.
Market Restraints
- Aluminum sheet price volatility:Rigid splint manufacturers face margin compression from London Metal Exchange aluminum fluctuations above 15% annual variance.
- EU MDR clinical documentation:The European Medical Device Regulation's expanded technical file requirements filter smaller polymer splint producers from CE marking eligibility.
- 3D-printed custom orthotics:Patient-specific additive manufacturing for finger immobilization threatens standardized splint volume in hand surgery recovery.
Strategic Opportunities
- Occupational therapy integration:Dynamic splint systems with calibrated tension mechanisms command premium positioning through therapist training partnerships.
- Home care reimbursement expansion:CMS durable medical equipment codes for outpatient hand therapy create coverage tailwinds for take-home splint prescriptions.
- Bio-based polymer advancement:PLA and PHA orthopedic testing protocols nearing completion open material substitution pathways for sustainability-positioned suppliers.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for European market access extend 12-18 months, delaying revenue recognition.
- Skilled thermoforming technician scarcity:Automated production lines require operators trained in polymer rheology and CNC programming, tightening labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finger Splint Market |
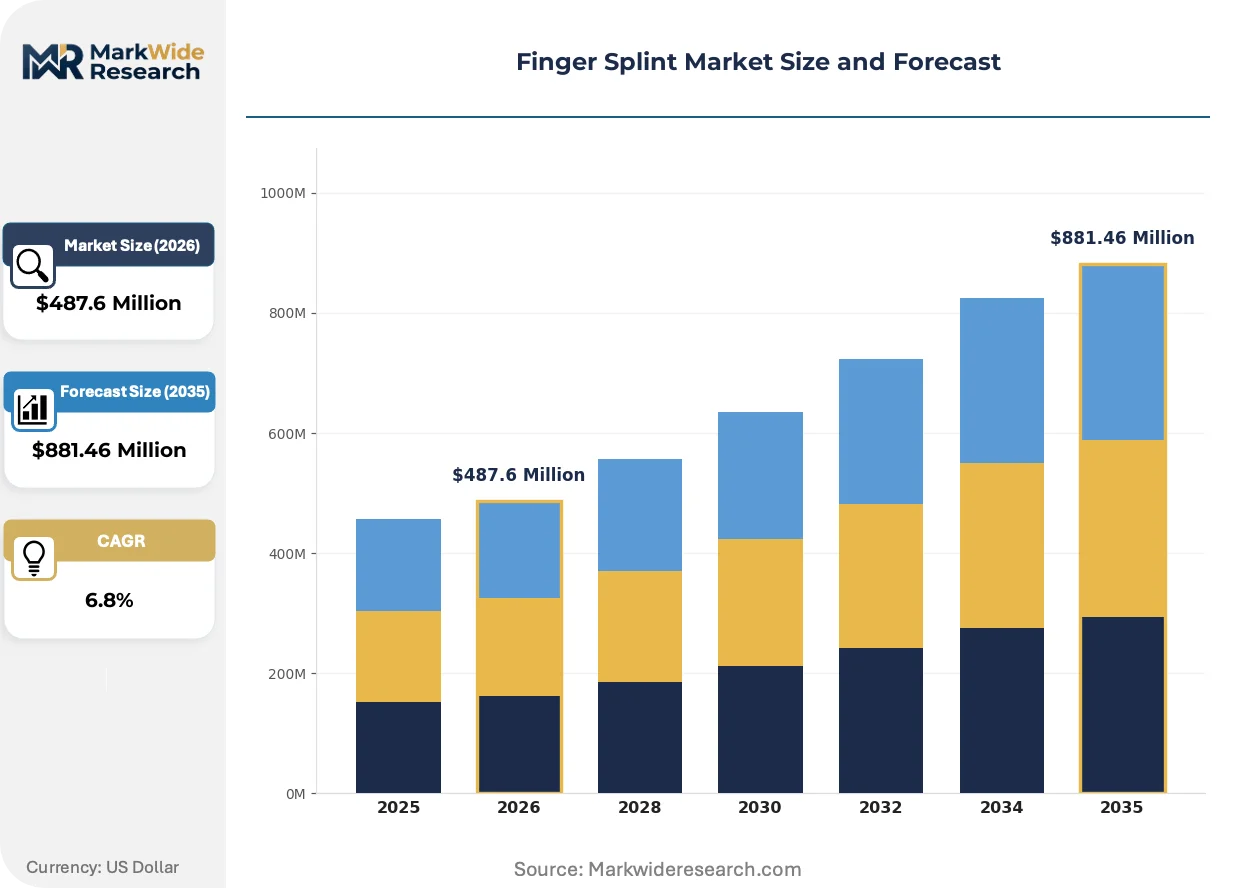
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Splints, Elastic Splints, Finger Wraps, Dynamic Splints Material: Plastic, Foam, Metal, Fabric End User: Medical Facilities, Home Care, Sports Teams, Occupational Therapists Application: Fracture Stabilization, Post-Surgery Support, Injury Prevention, Rehabilitation |
| Companies Covered | DeRoyal Industries, 3M, Zimmer Biomet, Smith & Nephew, Stryker, DJO Global, Orfit Industries, Alimed, OTTOBOCK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finger Splint Market Emerging Trajectories
Material science convergence with digital health integration is redefining finger splint value propositions, shifting competition from passive immobilization toward active rehabilitation monitoring and patient compliance tracking.
Shape-memory polymer alloys with thermally activated stiffness adjustment are fragmenting the traditional rigid-versus-dynamic product taxonomy. Outpatient hand surgery centers in Germany and Japan are piloting these materials for post-operative protocols requiring staged mobility restoration. The technology is fragmenting established price tiers by collapsing multiple splint purchases into single adaptive devices.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing polymer and metal splint producers to retrofit packaging and labeling infrastructure. Manufacturers serving the European Economic Area must embed machine-readable codes by 2026, squeezing smaller suppliers with limited serialization capital. Hospital purchasing networks are consolidating supplier lists to favor MDR-compliant incumbents with verified post-market surveillance systems.
Athletic trainers and occupational therapists are demanding splint systems with embedded range-of-motion sensors and Bluetooth connectivity to smartphone applications. This specification compression is displacing basic aluminum and neoprene designs in Division I collegiate and professional sports settings. The behavioral shift is most visible in the United States, where sports medicine departments budget for integrated injury management platforms rather than discrete orthopedic supplies.
Finger Splint Market Segmentation
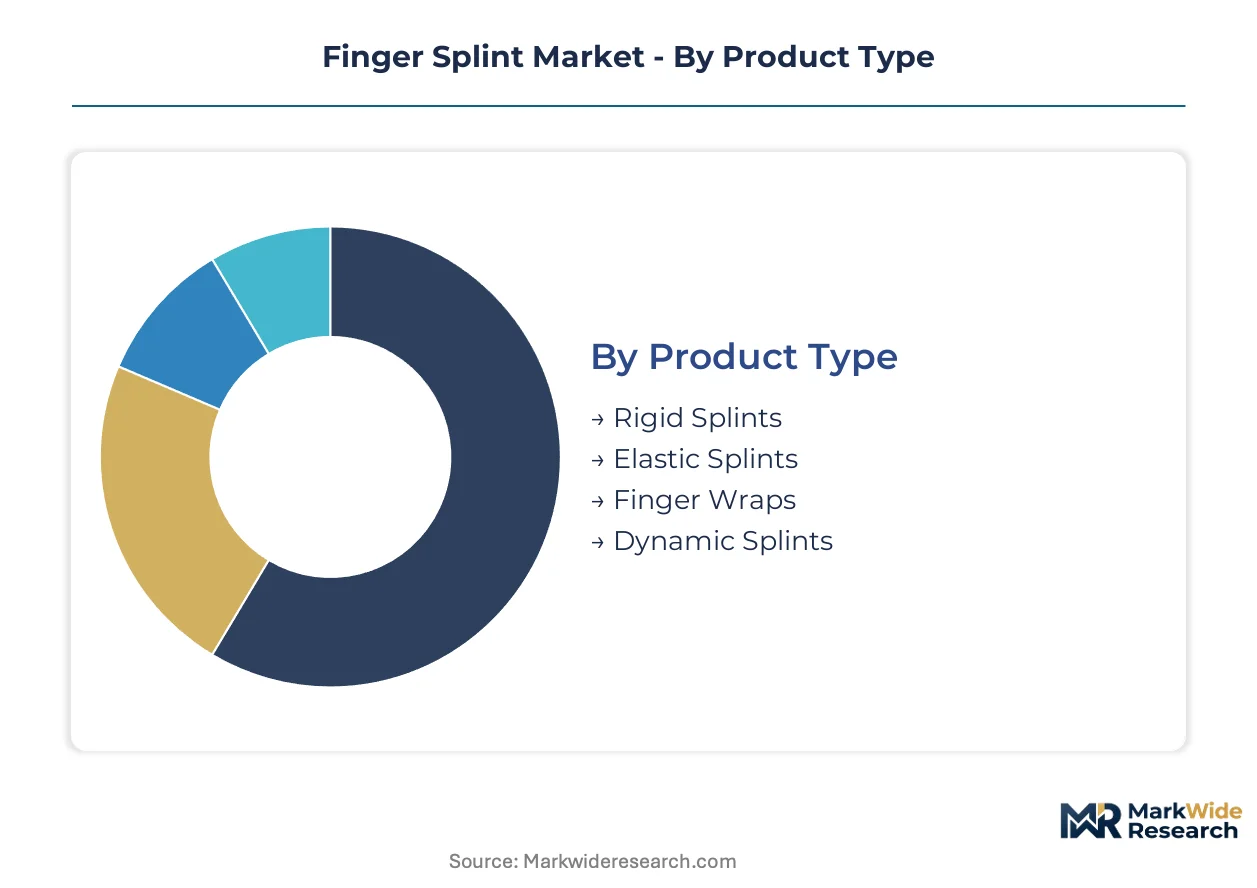
Segmentation in the finger splint market reveals how regulatory pathways, material specifications, and reimbursement codes fragment purchasing behavior across clinical and consumer channels. Suppliers must align product portfolios with distinct certification requirements and end-user procurement protocols to capture value.
Product Type:
FDA 510(k) clearance timelines vary materially across product categories, with Class I device notifications compressing entry barriers for simpler designs while dynamic systems face extended review for tension-calibration mechanisms.
- Rigid Splints:Molded polyethylene and aluminum constructs deliver maximum immobilization for phalangeal fractures. Hospital emergency departments in the United States drive procurement volume through durable medical equipment reimbursement codes favoring single-patient-use rigidity.
- Dynamic Splints:Calibrated tension mechanisms permit staged range-of-motion restoration via adjustable pulley systems. NCAA Division I sports medicine programs and outpatient hand therapy centers command premium positioning through occupational therapist training partnerships.
- Elastic Splints:Neoprene and fabric blends with aluminum stays enable self-application in home care settings where washability drives replacement cycles.
- Finger Wraps:Compression-grade textiles with hook-and-loop closure systems serve athletic taping protocols and minor sprain management.
Rigid Splints handles the majority of throughput; Dynamic Splints is the fastest mover on share.
Material:
Cost tier differentiation separates commodity inputs from performance-grade polymers, with thermoplastic processing investments above $2 million per production line filtering supplier participation.
- Plastic:Thermoformed polyethylene and polypropylene dominate hospital procurement through sterilization compatibility and radiolucency. Automated manufacturing scale economics compress margins for manual assemblers serving this volume segment.
- Metal:Anodized aluminum sheets deliver malleability for custom contouring in emergency settings. London Metal Exchange price volatility above 15% annual variance squeezes margin stability for rigid splint producers dependent on sheet stock.
- Foam:Open-cell polyurethane provides cushioning interfaces for multi-week immobilization protocols.
- Fabric:Nylon-spandex blends and breathable meshes enable athletic and home care applications requiring moisture management.
Plastic captures the greatest production volume; Metal faces the steepest input cost pressure.
End User:
Customer type determines channel configuration, with institutional purchasing networks demanding ISO 13485 certification while direct-to-consumer platforms bypass traditional durable medical equipment distributors.
- Medical Facilities:Hospital emergency departments and surgical centers require FDA-cleared devices with established reimbursement codes. Group purchasing organizations consolidate supplier lists to favor incumbents with verified post-market surveillance systems.
- Home Care:Self-application demand concentrates in Amazon and specialized orthopedic e-commerce platforms where elastic splint categories bypass traditional distribution. CMS durable medical equipment codes for outpatient hand therapy create coverage tailwinds for take-home prescriptions.
- Sports Teams:Collegiate and professional athletic programs specify integrated injury management platforms over discrete supplies.
- Occupational Therapists:Hand therapy specialists drive specification compression toward dynamic systems with calibrated tension and compliance tracking.
Medical Facilities anchor institutional procurement; Home Care is expanding most quickly through e-commerce channel maturation.
Application:
Maturity gradients separate acute intervention protocols from preventive and rehabilitative use cases, with reimbursement availability determining commercial viability across the spectrum.
- Fracture Stabilization:Acute immobilization for phalangeal and metacarpal injuries commands rigid splint deployment in emergency settings. Outpatient hand surgery volumes in the United States sustain demand concentration for post-reduction protection.
- Rehabilitation:Staged mobility restoration protocols favor dynamic splint systems with tension adjustment. Occupational therapy integration requirements in Germany and Japan pilot programs shape product development roadmaps.
- Post-Surgery Support:Tendon repair and arthroplasty recovery protocols specify material biocompatibility and edema management.
- Injury Prevention:Athletic taping alternatives and occupational strain protocols drive elastic and wrap category adoption.
Fracture Stabilization generates the highest procedure-linked volume; Rehabilitation is gaining share fastest through dynamic system premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for finger splints varies sharply across geographies, with United States buyers absorbing premium dynamic systems while Indian and Southeast Asian markets gravitate toward price-elastic aluminum and fabric alternatives. Reimbursement density and sports medicine infrastructure determine where suppliers can extract margin versus where volume throughput dominates.
United States
Outpatient hand surgery volumes and NCAA Division I athletic procurement sustain premium positioning for dynamic splint systems. The FDA's 510(k) clearance pathway averaging 90 days accelerates product iteration for polymer-based designs. Hospital purchasing networks in the Midwest and Southeast consolidate supplier lists around MDR-compliant incumbents with verified post-market surveillance.
Germany
Outpatient hand therapy centers in Bavaria and North Rhine-Westphalia pilot shape-memory polymer alloys for staged mobility restoration protocols. The EU Medical Device Regulation's Unique Device Identification mandate forces retrofitting of packaging infrastructure by 2026. Berlin-Brandenburg hosts polymer science clusters advancing thermoplastic processing investments above $2 million per production line.
Japan
Occupational therapy integration requirements in Kansai and Chubu regions shape product development roadmaps for tension-calibration mechanisms. METI standards govern quality management system audits extending 12-18 months for European market access eligibility. Tokyo's sports medicine departments specify integrated injury management platforms over discrete orthopedic supplies.
China
Domestic consumption concentrates in Yangtze River Delta manufacturing hubs where thermoforming equipment investments compress margins for manual assemblers. NMPA notification processes for Class I devices filter smaller polymer producers from cross-border participation. Pearl River Delta clusters supply aluminum sheet stock facing London Metal Exchange volatility above 15% annual variance.
India
Home care channels through Amazon and specialized orthopedic e-commerce platforms bypass traditional durable medical equipment distributors for elastic splint categories. CDSCO quality management certification shapes supplier eligibility for institutional procurement. Maharashtra and Gujarat host fabrication clusters serving price-sensitive fracture stabilization demand with neoprene and fabric alternatives.
Finger Splint Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with polymer science capabilities and institutional contracting relationships determining tier placement. The upper tier commands premium positioning through orthopedic surgeon training programs and group purchasing organization consolidation. Mid-tier suppliers face compression from automated thermoforming scale economics and ISO 13485 certification barriers. Dominant competitive moves center on M&A-driven portfolio diversification and backward integration into polymer resin supply.
Within the integrated multinational tier, 3M leverages materials science capabilities across hospital purchasing networks, while Zimmer Biomet anchors presence through institutional contracts and surgeon education programs. Smith & Nephew occupies a position linking splint products to wound-care adjacencies. Among specialized fabricators, DeRoyal Industries and Orfit Industries exemplify regional specialists competing on customization velocity and occupational therapy partnerships rather than manufacturing scale.
| Leading Market Players |
|---|
| DeRoyal Industries |
| 3M |
| Zimmer Biomet |
| Smith & Nephew |
| Stryker |
| DJO Global |
| Orfit Industries |
| Alimed |
| OTTOBOCK |
| Others |
Supply Flow & Price Mechanics
Shape-memory polymer alloys replacing conventional aluminum and polyethylene constructs are redrawing sourcing maps toward Germany and Japan while collapsing multiple price tiers into single adaptive devices. This material transition concentrates premium production in polymer science clusters and compresses margin pools for commodity metal fabricators serving emergency departments.
Pricing Analysis
After-sales revenue from occupational therapist training partnerships and tension-calibration servicing drives lifetime value for dynamic splint manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and therapy integration depth. Pricing pressure stems from automated thermoforming scale economics compressing manual assembler margins. Hospital purchasing committees show lowest price sensitivity for FDA-cleared dynamic systems, while home care channels exhibit highest elasticity toward elastic splint alternatives.
Supply Chain Analysis
Strategic stockpiling of aluminum sheet stock dominates rigid splint production given London Metal Exchange volatility, while just-in-time polymer resin delivery serves thermoforming operations in Germany, the United States, and China. Raw material dependencies center on polyethylene pellets, anodized aluminum sheets, and neoprene textile laminates. Single-source vulnerability concentrates in German polymer science clusters supplying shape-memory alloys. Distribution runs through hospital purchasing networks and Amazon-direct orthopedic e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
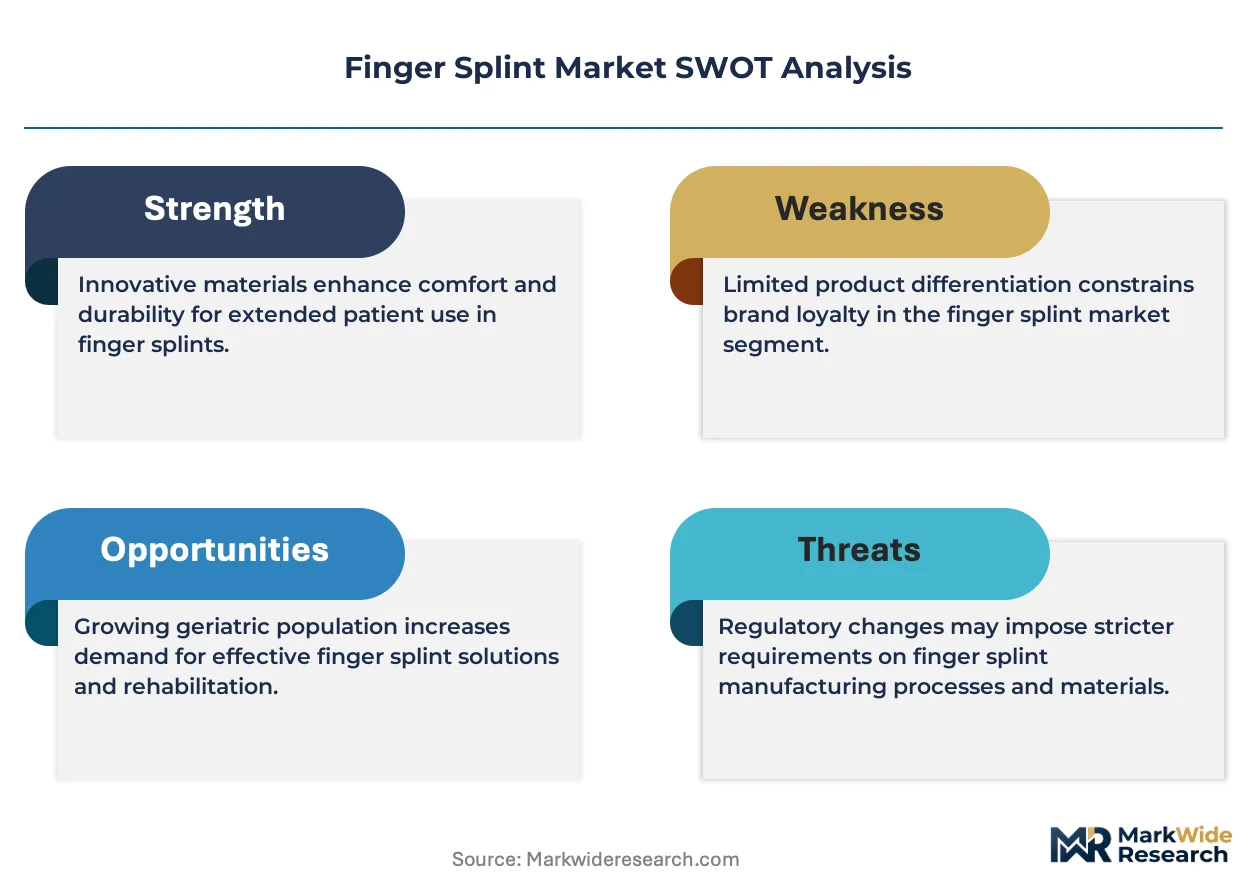
Incumbents face a substitution defense against patient-specific 3D-printed orthotics threatening standardized splint volumes in post-operative recovery protocols.
For Market Incumbents: Fortify market position through backward integration into polymer resin supply and captive production of shape-memory alloy components. Secure ISO 13485 certification ahead of EU MDR enforcement to filter smaller competitors from CE marking eligibility. Prioritize occupational therapist training partnerships as a defensive moat against additive manufacturing substitutes. For New Entrants and Emerging Players: Differentiate on bio-based polymer sustainability positioning as PLA and PHA orthopedic testing protocols near completion. Target home care e-commerce channels where elastic splint categories bypass traditional durable medical equipment distributors. Pursue direct-to-consumer launch with washability-driven replacement cycle marketing. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier fabricators with verified post-market surveillance systems and MDR-compliant packaging infrastructure. Long-term viability hinges on consolidation plays capturing institutional procurement contracts. Watch for aluminum price volatility crossing thresholds that trigger rigid splint manufacturer distress.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance filters smaller polymer producers from European market access. |
| Hospital System Partnership | GPO consolidation favors incumbents with verified post-market surveillance systems. |
| Software Companion Development | Bluetooth-enabled range-of-motion sensors displace basic designs in collegiate sports medicine. |
| Reimbursement Strategy | CMS durable medical equipment codes create coverage tailwinds for take-home prescriptions. |
| Backward Integration | Captive polymer resin supply defends margin against commodity price volatility. |
Methodological Framework
A standing panel of hand surgeons, occupational therapists, hospital purchasing committee members, and biomedical engineers provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and NCAA athletic equipment disclosures. Bottom-up volume modeling across product type, material, end user, and application segments triangulated with top-down macroeconomic anchors.
Consistency checks validated outputs against external benchmarks including aluminum price indices, polymer processing equipment investment flows, and durable medical equipment distributor financial disclosures. Segmentation dimensions spanned product type, material specification, end user procurement protocol, application maturity, and regional reimbursement density. CAGRs derived from procedure volume elasticities, replacement cycle frequencies, and channel shift velocities across the analysis window.
Decision-makers should treat outputs as directional under base assumptions of stable FDA 510(k) timelines and sustained outpatient hand surgery volumes; material deviation would warrant model refresh. Revision becomes warranted when 3D-printed orthotic adoption crosses institutional procurement thresholds or EU MDR enforcement accelerates manufacturer exit rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Nasal Splints Market
Medical Supplies
First Aid Kit Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Global Lancets Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Medical Liners Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Blood Preparation Market