
 Alzheimer's Disease Diagnostics and Therapeutics Market | 2026-2036
Alzheimer's Disease Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Alzheimer's Disease Diagnostics and Therapeutics Market Outlook
The specialty pharmacy channel is narrowing as manufacturers of amyloid-targeting therapies restrict distribution to certified infusion centers. Eli Lilly and Company leverages its manufacturing scale to secure preferential formulary placement. Biogen Inc. anchors its position through deep relationships with academic memory disorder clinics. Johnson & Johnson competes via integrated diagnostic-therapeutic bundling across its neurology portfolio.
Alzheimer's Disease Diagnostics and Therapeutics encompasses biomarker assays, neuroimaging tracers, cognitive enhancers, and disease-modifying antibodies designed to detect, monitor, or alter pathological progression of neurodegeneration. PET ligands targeting amyloid-beta and phosphorylated tau operate at picomolar binding affinity, enabling visual quantification of protein deposition decades before symptom onset. Disease-modifying therapies command the largest margin pools due to biologic complexity and restricted distribution, while biomarker discovery represents the fastest-expanding segment as blood-based p-tau217 assays displace costly PET imaging for screening. Neuroimaging retains structural importance in trial endpoints and reimbursement confirmation despite this shift.
FDA accelerated approval requirements mandate confirmatory trials for amyloid-clearing antibodies, creating compliance cost barriers for smaller developers. EMA parallel scientific advice and Japan PMDA Sakigake designation programs shape parallel development strategies for multinational sponsors. Stakeholders must monitor CMS national coverage determination outcomes for blood-based biomarkers, as these decisions will restructure referral patterns between primary care and specialty neurology.
Market Dynamics
FDA accelerated approval mandates for amyloid-clearing antibodies have restructured clinical trial economics, forcing sponsors to fund parallel confirmatory studies before initial revenue streams materialize. This regulatory architecture favors scaled manufacturers with diversified pipelines over single-asset developers.
Growth Catalysts
- Blood-based p-tau217 assays:These biomarker platforms cut diagnostic costs by seventy percent versus PET imaging. Primary care networks in Germany and Japan are piloting presymptomatic screening programs using these assays.
- CMS national coverage determinations:Pending decisions on biomarker reimbursement will redirect patient flow from specialty neurology toward general practice. This policy inflection point determines whether screening scales beyond academic medical centers.
- Certified infusion center networks:Restricted distribution requirements for disease-modifying antibodies are concentrating treatment capacity. Site certification creates captive referral relationships between diagnostic and therapeutic providers.
Market Restraints
- Biologic manufacturing complexity:Amyloid-targeting antibodies require mammalian cell culture at commercial scale. Capacity constraints at contract manufacturing organizations extend lead times for new entrants.
- Confirmatory trial cost burdens:FDA mandates for post-acceleration efficacy studies impose capital requirements exceeding smaller developers' balance sheets. This structural barrier consolidates development activity among large-cap sponsors.
- Specialist workforce scarcity:Cognitive neurologist training pipelines in the United States produce fewer than four hundred new specialists annually. Diagnostic throughput bottlenecks constrain therapy initiation rates regardless of manufacturing capacity.
Strategic Opportunities
- Home-based digital cognitive monitoring:Smartphone-administered assessments enable longitudinal tracking outside clinic settings. Payers in the Netherlands are testing reimbursement for these tools as triage mechanisms.
- Companion diagnostic bundling:Integrated assay-therapy offerings align with EMA parallel scientific advice pathways. This convergence model streamlines regulatory submissions across European member states.
- Plasma collection infrastructure:Blood-based biomarker scale-up requires specialized processing networks. Independent laboratories in Australia are building dedicated p-tau217 capacity ahead of anticipated TGA approvals.
Industry Challenges
- Biomarker standardization gaps:Preanalytical variability in plasma p-tau217 measurements undermines cross-site comparability. Reference material harmonization efforts through the National Institute of Standards and Technology remain incomplete.
- Electronic health record integration:Cognitive assessment data lacks structured interoperability with existing clinical workflows. Health systems must fund custom interface development to embed new diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alzheimer's Disease Diagnostics and Therapeutics Market |
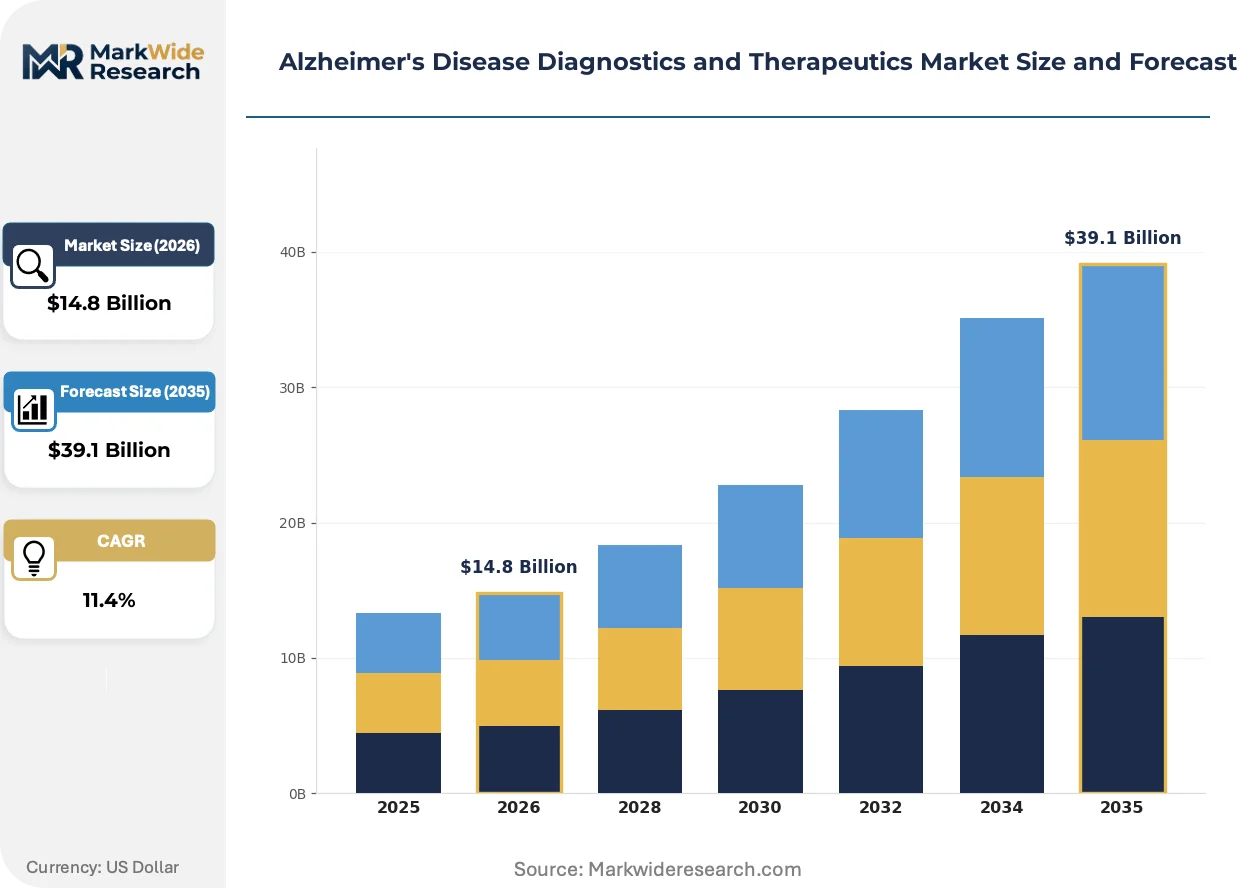
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Agents, Biomarkers, Disease-Modifying Therapies, Cognitive Enhancers End User: Hospitals, Diagnostic Labs, Research Institutions, Home Care Settings Technology: Neuroimaging, Genetic Testing, Biomarker Discovery, Artificial Intelligence Application: Early Detection, Symptom Management, Disease Monitoring, Clinical Trials |
| Companies Covered | F. Hoffmann-La Roche, Eli Lilly and Company, Johnson & Johnson, AbbVie Inc., Biogen Inc., AstraZeneca PLC, Bristol-Myers Squibb, Eisai Co. Ltd, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alzheimer's Disease Diagnostics and Therapeutics Market Strategic Shifts
Diagnostic modality preferences are pivoting toward minimally invasive platforms that compress the interval between symptom recognition and therapeutic intervention. This shift is redrawing competitive boundaries between imaging, laboratory, and digital health segments.
PET ligand utilization is migrating from screening toward confirmatory and trial endpoint applications. Memory disorder clinics in the United States are reserving amyloid imaging for ambiguous cases and treatment monitoring. Blood-based assays are capturing the volume screening position, compressing PET revenue to specialized indication niches.
EMA parallel scientific advice programs are synchronizing diagnostic and therapeutic development timelines. Multinational sponsors now submit coordinated evidence packages for biomarker assays and companion antibodies. This regulatory convergence reduces development risk but requires earlier investment in diagnostic platform partnerships.
Specialty pharmacy channel consolidation is narrowing patient access points for infused therapies. Manufacturers are restricting distribution to certified infusion centers with demonstrated capability in hypersensitivity management. This channel compression concentrates purchasing power among a smaller network of high-volume sites.
Alzheimer's Disease Diagnostics and Therapeutics Market Segmentation
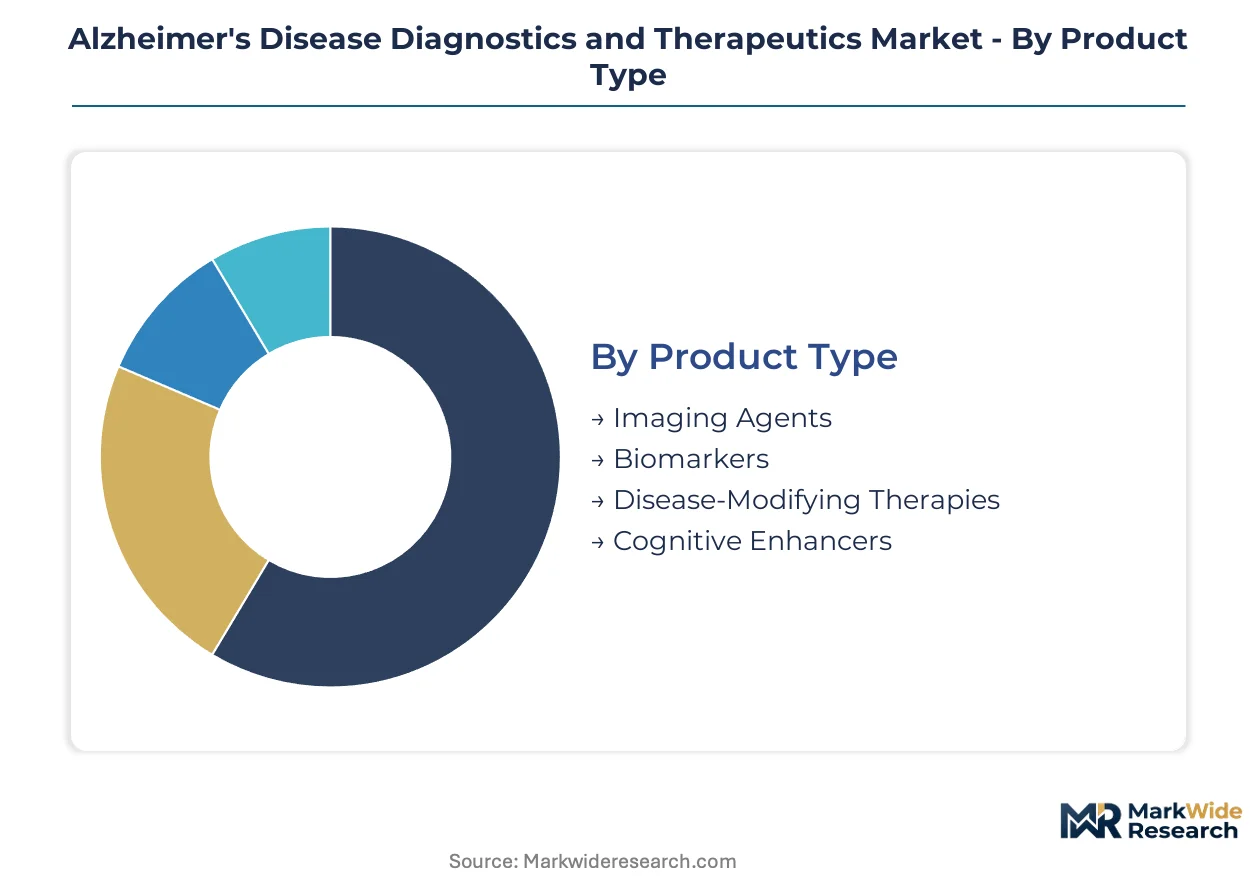
Segmentation in the Alzheimer's market reveals divergent investment cycles across diagnostic and therapeutic modalities. Product categories range from capital-intensive biologic manufacturing to rapidly iterating digital platforms. Understanding these velocity differences shapes portfolio allocation and partnership strategy.
Product Type:
Cycle times stretch from eighteen-month assay development cycles to seven-year antibody maturation timelines. Cash conversion velocity separates segments sharply.
- Disease-Modifying Therapies:Monoclonal antibodies targeting amyloid-beta require mammalian cell culture at commercial scale. Manufacturing complexity in the United States and Germany concentrates production among scaled sponsors with captive bioreactor capacity. FDA confirmatory trial mandates extend development timelines and capital requirements.
- Biomarkers:Blood-based p-tau217 assays iterate rapidly through automated immunoassay platforms. Demand in Japan and Germany is accelerating as primary care networks pilot presymptomatic screening programs. CMS reimbursement decisions will determine whether this segment scales beyond academic medical centers.
- Imaging Agents:PET ligands for amyloid-beta and phosphorylated tau require cyclotron production networks. Clinical utilization is compressing toward confirmatory indications.
- Cognitive Enhancers:Small-molecule symptomatic treatments face generic erosion. Prescription volume concentrates in managed care formularies.
Disease-Modifying Therapies dominates installed base. Biomarkers is where expansion concentrates.
End User:
Customer concentration varies from fragmented home settings to concentrated hospital systems. Procurement authority shapes pricing power distribution.
- Diagnostic Labs:Centralized processing sites in Germany and Japan are building dedicated p-tau217 capacity ahead of reimbursement decisions. Volume aggregation enables equipment amortization across high-throughput analyzers. Laboratory information system integration requirements create switching costs.
- Hospitals:Academic medical centers in the United States anchor PET imaging utilization and infusion center certification. Site credentialing for amyloid-clearing antibodies concentrates purchasing power among high-volume neurology departments. Workforce scarcity limits diagnostic throughput regardless of equipment capacity.
- Research Institutions:Clinical trial endpoints drive demand for standardized biomarker platforms. Funding cycles align with NIH and EU Horizon grant schedules.
- Home Care Settings:Digital cognitive monitoring tools enable longitudinal tracking outside clinic infrastructure. Dutch payers are testing reimbursement for smartphone-administered assessments.
Hospitals dominate installed base. Diagnostic Labs is where expansion concentrates.
Technology:
Platform maturity spans decades-old imaging modalities to emerging AI architectures. Regulatory clarity separates investable from experimental categories.
- Biomarker Discovery:Mass spectrometry and immunoassay platforms are displacing PET for screening applications. Plasma p-tau217 standardization efforts through NIST remain incomplete. Preanalytical variability constrains cross-site comparability.
- Neuroimaging:MRI and PET retain structural importance in trial endpoints and treatment monitoring. Ligand development pipelines in the United States focus on tau pathology quantification.
- Artificial Intelligence:Machine learning models for cognitive assessment lack structured EHR interoperability. Health systems must fund custom interface development.
- Genetic Testing:APOE genotyping supports risk stratification in research settings. Clinical utility remains limited by penetrance variability.
Neuroimaging dominates installed base. Biomarker Discovery is climbing the fastest.
Application:
Use case economics range from preventive screening at population scale to intensive monitoring in selected cohorts. Reimbursement architecture determines viable addressable markets.
- Early Detection:Presymptomatic identification through blood-based assays is redirecting patient flow from specialty neurology toward primary care. German and Japanese pilot programs test population-scale screening feasibility.
- Clinical Trials:Endpoint standardization drives demand for centralized biomarker laboratories. EMA parallel scientific advice programs synchronize diagnostic and therapeutic development timelines.
- Disease Monitoring:Longitudinal tracking supports treatment response assessment and safety surveillance. Infusion centers in the United States are building captive referral relationships with diagnostic providers.
- Symptom Management:Cholinesterase inhibitor utilization is plateauing as disease-modifying therapies capture prescriber attention. Formulary positioning depends on comparative effectiveness data.
Symptom Management dominates installed base. Early Detection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for amyloid-clearing antibodies have concentrated clinical trial infrastructure and reimbursement policy development in the United States. Germany and Japan are scaling parallel regulatory frameworks through EMA parallel scientific advice and PMDA Sakigake designations. Blood-based biomarker pilot programs in primary care networks are redirecting diagnostic demand toward laboratory channels.
United States
Academic medical centers in Boston and San Francisco anchor PET imaging utilization and certified infusion center networks. CMS national coverage determinations for blood-based p-tau217 assays will restructure referral patterns between primary care and specialty neurology. The National Institute of Standards and Technology leads incomplete harmonization efforts for preanalytical variability in plasma biomarker measurements.
Germany
Primary care networks in Bavaria and North Rhine-Westphalia pilot presymptomatic screening programs using automated immunoassay platforms. EMA parallel scientific advice programs synchronize diagnostic and therapeutic development timelines for multinational sponsors submitting coordinated evidence packages. Centralized laboratory processing sites in the Rhine-Ruhr region build dedicated high-throughput analyzer capacity.
Japan
PMDA Sakigake designation programs accelerate review timelines for disease-modifying antibodies and companion diagnostics developed in parallel. Tokyo and Osaka academic medical centers concentrate cognitive neurologist training pipelines and memory disorder clinic infrastructure. METI funding supports domestic plasma collection infrastructure expansion ahead of anticipated biomarker scale-up.
Australia
Independent laboratories in New South Wales and Victoria construct dedicated p-tau217 processing capacity ahead of TGA regulatory decisions. The country's national pharmaceutical regulator evaluates blood-based biomarker submissions through priority review pathways. Sydney and Melbourne health systems test reimbursement frameworks for smartphone-administered cognitive assessments in home care settings.
Netherlands
Payers in the Randstad region pilot reimbursement for digital cognitive monitoring tools as triage mechanisms redirecting patient flow. Dutch health technology assessment frameworks evaluate minimally invasive diagnostic platforms against PET imaging cost benchmarks. Eindhoven-region health informatics clusters develop electronic health record interoperability solutions for structured cognitive assessment data integration.
Alzheimer's Disease Diagnostics and Therapeutics Market Competitive Environment
Integrated pharmaceutical conglomerates and specialized biotechnology developers split the market between diversified manufacturing scale and focused therapeutic innovation. The competitive structure concentrates among scaled sponsors with captive bioreactor capacity and parallel diagnostic platform partnerships. Two dominant archetypes emerge: diversified healthcare conglomerates bundling diagnostic-therapeutic offerings, and specialized neurology-focused developers anchoring positions through academic medical center relationships. Competitive moves center on restricted distribution network certification and companion diagnostic regulatory convergence.
Among diversified healthcare conglomerates, Johnson & Johnson and Eli Lilly and Company exemplify archetypes pursuing integrated portfolio strategies. Biogen Inc. occupies a position within the specialized biotechnology tier, anchoring relationships with academic memory disorder clinics. These three entities represent distinct competitive positioning vectors: manufacturing scale securing formulary placement, diagnostic-therapeutic bundling across neurology portfolios, and deep institutional relationships in cognitive neurology subspecialties.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Eli Lilly and Company |
| Johnson & Johnson |
| AbbVie Inc. |
| Biogen Inc. |
| AstraZeneca PLC |
| Bristol-Myers Squibb |
| Eisai Co. Ltd |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Mammalian cell culture capacity in the United States and Germany concentrates production of amyloid-targeting antibodies among scaled sponsors with captive bioreactor networks. This upstream concentration funnels margin pools toward disease-modifying therapies while compressing returns for diagnostic assays facing commoditization pressure.
Pricing Analysis
Price spreads between United States and German infusion centers exceed those seen in other specialty biologic categories due to CMS reimbursement variability versus statutory health insurance pricing. Three-tier pricing structure across premium antibody therapies, standard biomarker panels, and economy cognitive enhancers reflects certification grade and volume scale differentiation. Cost compression in blood-based assay tiers is intensifying because automated immunoassay platforms displace labor-intensive PET imaging. Hospital systems demonstrate highest price sensitivity due to bundled reimbursement constraints, while academic medical centers retain lowest sensitivity through research funding cross-subsidies.
Supply Chain Analysis
Tariff exposure between United States and Chinese bioprocessing equipment suppliers dominates supply chain risk planning for mammalian cell culture expansion. Manufacturing gravity centers on the United States, Germany, and Switzerland for active pharmaceutical ingredient production, with contract manufacturing organizations in Ireland and Singapore providing overflow capacity. Raw material dependencies include recombinant protein media, single-use bioreactor bags, and chromatography resins sourced from specialized chemical suppliers. Distribution runs through certified infusion center networks with demonstrated hypersensitivity management capability, creating captive referral relationships between diagnostic and therapeutic providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital systems and national payer authorities as reimbursement frameworks narrow provider networks. This consolidation fragments negotiating leverage among smaller diagnostic laboratories and independent neurology practices.
For Market Incumbents: Entrench position through captive plasma collection infrastructure expansion ahead of blood-based biomarker scale-up. Secure preferential formulary placement by bundling diagnostic-therapeutic offerings across neurology portfolios. The emerging threat of automated immunoassay commoditization demands investment in laboratory information system integration to create switching costs. Vertical integration into p-tau217 processing capacity represents the critical lever for margin defense.
For New Entrants and Emerging Players: Mid-market diagnostic laboratories in Australia and the Netherlands represent the most penetrable entry point for blood-based assay platforms ahead of TGA and Dutch reimbursement decisions. Primary care networks in German Bavaria piloting presymptomatic screening programs offer second-mover positioning without academic medical center credentialing barriers. A go-to-market angle emphasizing EMA parallel scientific advice pathway alignment streamlines regulatory submissions for companion diagnostic partnerships.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized neurology-focused developers with deep academic medical center relationships and parallel diagnostic platform partnerships. Long-term viability across the projection horizon hinges on confirmatory trial execution capability under FDA accelerated approval mandates. The signal to watch is CMS national coverage determination outcomes for blood-based biomarkers, as these decisions restructure referral patterns and scale addressable markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Regulatory Convergence | EMA parallel scientific advice programs synchronize biomarker and antibody development timelines for multinational sponsors. |
| Certified Infusion Center Network Expansion | Restricted distribution requirements for amyloid-clearing antibodies concentrate treatment capacity and create captive referral relationships. |
| Plasma Collection Infrastructure Buildout | Specialized processing networks in Australia and Japan enable blood-based p-tau217 scale-up ahead of regulatory approvals. |
| Digital Cognitive Monitoring Platform Integration | Dutch payer pilot programs for smartphone-administered assessments test reimbursement frameworks outside clinic infrastructure. |
| Biomarker Standardization Harmonization | NIST reference material efforts address preanalytical variability constraining cross-site comparability in plasma p-tau217 measurements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS national coverage determination documents. Interviews with drug development executives, regulatory affairs leads, formulary directors at major payers, and hospital procurement managers informed demand-side assumptions. Bottom-up triangulation across patient flow models and top-down validation against manufacturer revenue disclosures anchored volume estimates.
Forecast inputs include treatment line stratification, administration route differentiation, regional regulatory cluster segmentation, and patient population cohort modeling across the projection horizon. CAGRs derive from fitted growth curves adjusted for policy inflection points including reimbursement decisions and accelerated approval pathway outcomes. Manufacturing capacity expansion schedules, cognitive neurologist training pipeline outputs, and biomarker assay adoption curves constitute industry-specific forecast inputs.
Practitioners should monitor CMS national coverage determination timelines, EMA parallel scientific advice program outcomes, and PMDA Sakigake designation decisions for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Global Sepsis Diagnostics Market
Diagnostics
Pathogen Detection Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Johne's Disease Diagnostics Market