
 Global Ovulation Inducing Drugs Market | 2026-2036
Global Ovulation Inducing Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ovulation Inducing Drugs Market Intelligence
The consolidation of independent specialists into large-scale, corporate-backed Fertility Clinic networks is recalibrating purchasing power and standardizing treatment protocols. This dynamic benefits companies with broad portfolios and strong institutional sales teams. Ferring Pharmaceuticals leverages its specialized focus on reproductive medicine to secure contracts with these large centers. Merck & Co. competes through its established brand presence and extensive distribution channels that service both clinics and prescribing hospitals.
Ovulation inducing drugs are pharmaceutical agents designed to stimulate ovarian follicle development and trigger egg release in anovulatory patients. These medications, such as clomiphene citrate or gonadotropins, directly influence hormonal pathways involving FSH and LH. While oral Clomiphene Citrate represents the high-volume, first-line treatment, injectable Gonadotropins lead in value, especially for Polycystic Ovary Syndrome. These advanced therapies are predominantly administered within Fertility Clinics, which are the primary End User for complex cases.
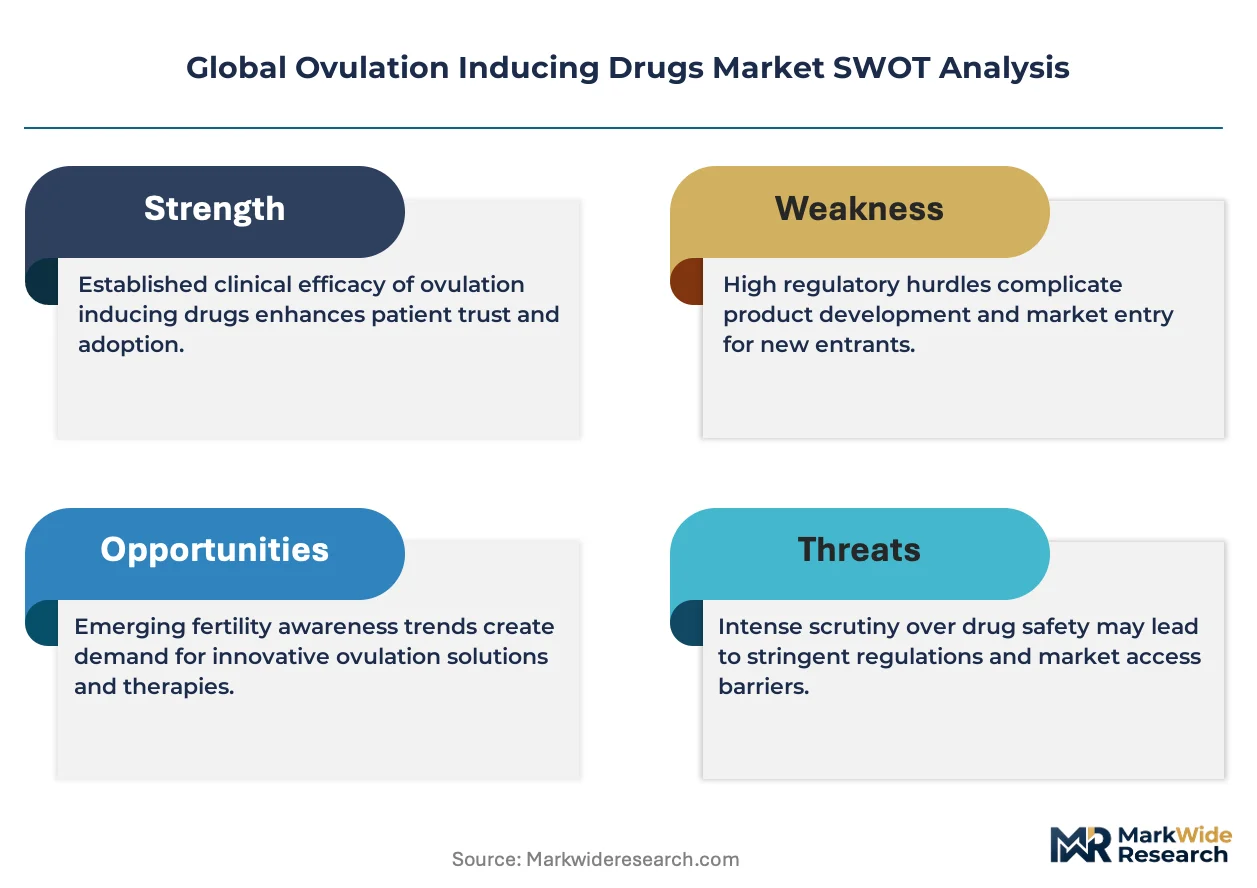
Market access is governed by stringent clinical trial requirements set by national bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These regulations mandate extensive safety and efficacy data, directly shaping R&D investment timelines and the high cost of new drug approvals. Success for drug manufacturers will depend on navigating varied national reimbursement policies and demonstrating superior clinical outcomes in head-to-head trials.
Market Dynamics
The consolidation of independent fertility specialists into large-scale, corporate-backed clinic networks is the central force shaping the market. This structural shift concentrates purchasing power, standardizes treatment protocols, and redefines the supplier-provider relationship for ovulation inducing drugs.
Growth Catalysts
- Injectable Formulation Advances:Development of long-acting and highly-purified recombinant gonadotropins enhances treatment efficacy and patient convenience, particularly for complex cases like Polycystic Ovary Syndrome (PCOS) managed in Assisted Reproduction Centers.
- Demand Concentration in Asia:Rising infertility rates, coupled with increased disposable income and expanding healthcare infrastructure in China and India, are creating significant new patient populations seeking fertility treatments.
- Expanding Reimbursement Policies:Gradual expansion of insurance coverage for infertility treatments, including ovulation induction therapies, in several developed nations is lowering the financial barrier for patients and stimulating procedure volume.
Market Restraints
- Stringent Regulatory Hurdles:Extensive clinical trial data on safety and efficacy required by bodies like the US FDA and the EMA creates high entry barriers and prolongs development timelines, increasing the cost of bringing new drugs to market.
- High Treatment Costs:The substantial cost of injectable gonadotropin cycles, especially when not covered by insurance, limits patient access in many countries and can lead to high dropout rates after initial attempts.
- Social and Ethical Considerations:Cultural stigmas surrounding infertility and ethical debates regarding assisted reproductive technologies in certain regions can suppress patient demand and limit public funding or supportive policies.
Strategic Opportunities
- Pharmacogenomic Integration:Applying genetic testing to predict patient response to specific ovulation inducing drugs presents an opportunity to develop personalized medicine protocols, improving success rates and differentiating products.
- Underpenetrated Market Entry:Markets in Latin America and Southeast Asia exhibit growing middle classes and increasing awareness of fertility solutions, offering significant growth potential for manufacturers who establish an early presence.
- Digital Health Platforms:Developing patient support platforms for injection training, dose reminders, and symptom tracking can enhance adherence and create brand loyalty, providing a value-added service beyond the drug itself.
Industry Challenges
- Biosimilar Competition:The expiration of patents for major biologic gonadotropins is introducing biosimilar competitors, creating price pressure and requiring originator brands to defend market share through non-price-based strategies.
- Centralized Procurement Demands:The consolidation of fertility clinics into large networks creates a challenge for smaller drug makers, who may lack the scale to compete in tenders or meet the logistical demands of national contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ovulation Inducing Drugs Market |
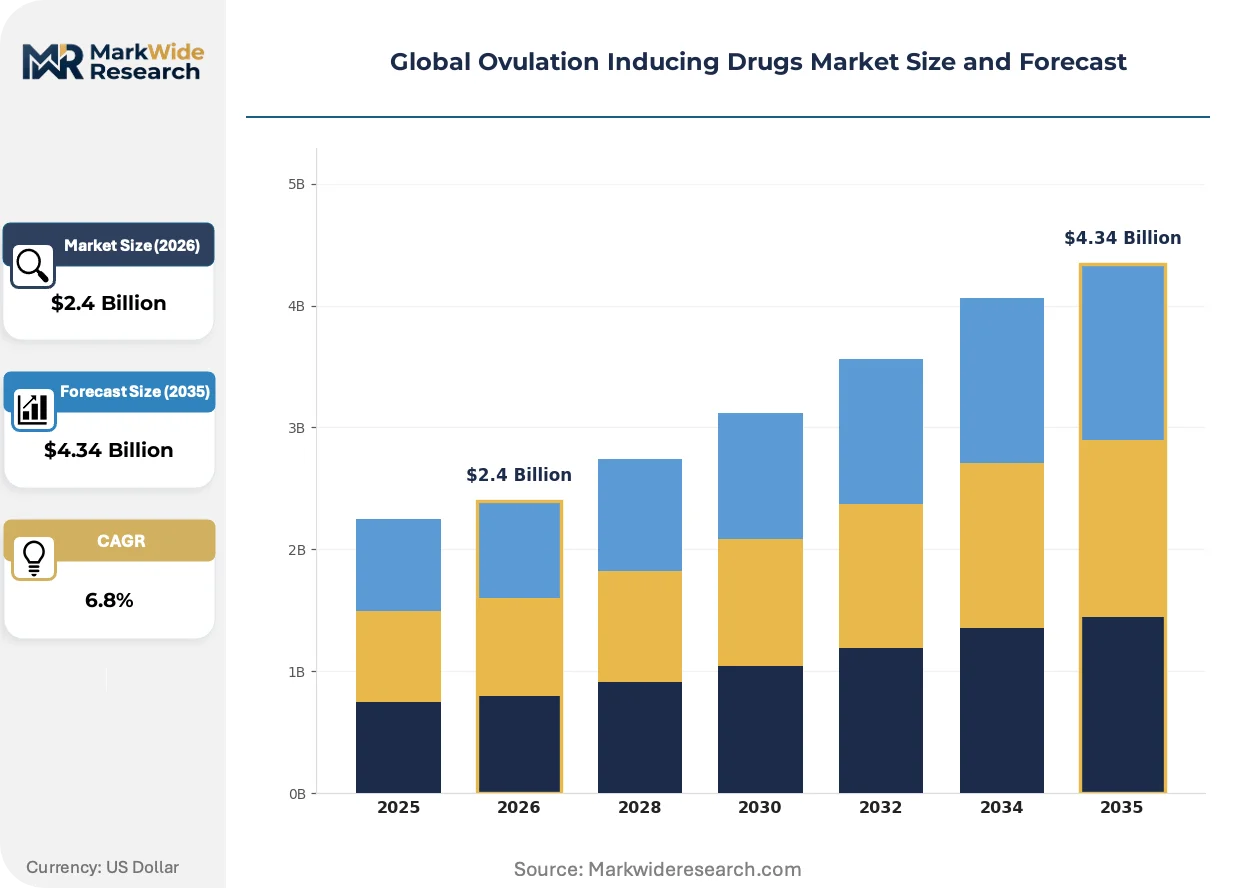
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clomiphene Citrate, Gonadotropins, Letrozole, Metformin, Human Chorionic Gonadotropin, Others Therapy Area: Polycystic Ovary Syndrome, Hypothalamic Amenorrhea, Luteal Phase Defect, Anovulation, Premature Ovarian Failure, Endometriosis End User: Fertility Clinics, Gynecology Centers, Assisted Reproduction Centers, Obstetrics Hospitals, Diagnostic Labs, Independent Specialists Route of Administration: Oral, Injectable, Subcutaneous, Intramuscular, Intravenous |
| Companies Covered | Novartis AG, Ferring Pharmaceuticals, EMD Serono, Merck & Co., Pfizer Inc., Teva Pharmaceutical Industries Ltd, Abbott, Bayer AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ovulation Inducing Drugs Market Strategic Shifts & Innovations
Personalization and patient-centricity are transforming treatment paradigms. Innovations in drug delivery, coupled with data-driven regulatory expectations and evolving procurement models, are pushing manufacturers to demonstrate value beyond clinical efficacy alone.
Long-acting recombinant FSH formulations are a key product evolution, designed to reduce the frequency of injections required during a stimulation cycle. Fertility clinics and their patients are adopting these therapies to improve treatment adherence and lessen the daily burden of the protocol. This technology is expanding into home-based care models, empowering patients with greater autonomy and reducing the clinical resources needed for routine administration.
The European Medicines Agency (EMA) is placing greater emphasis on the collection of real-world evidence (RWE) to monitor the long-term safety and comparative effectiveness of biologic drugs post-approval. This regulatory shift compels manufacturers to invest in patient registries and digital tools for data capture. Manufacturers of gonadotropins are most affected, now needing to generate continuous RWE to support reimbursement negotiations with national health authorities across the EU.
A shift toward centralized formulary management is evident within large, corporate-owned fertility clinic networks. This model is displacing the historical reliance on individual physician preference, creating a more competitive bidding environment where supply chain reliability and portfolio-wide pricing are critical. The trend is most pronounced in the United States and select European countries where private equity is actively consolidating the provider landscape.
Global Ovulation Inducing Drugs Market Segmentation
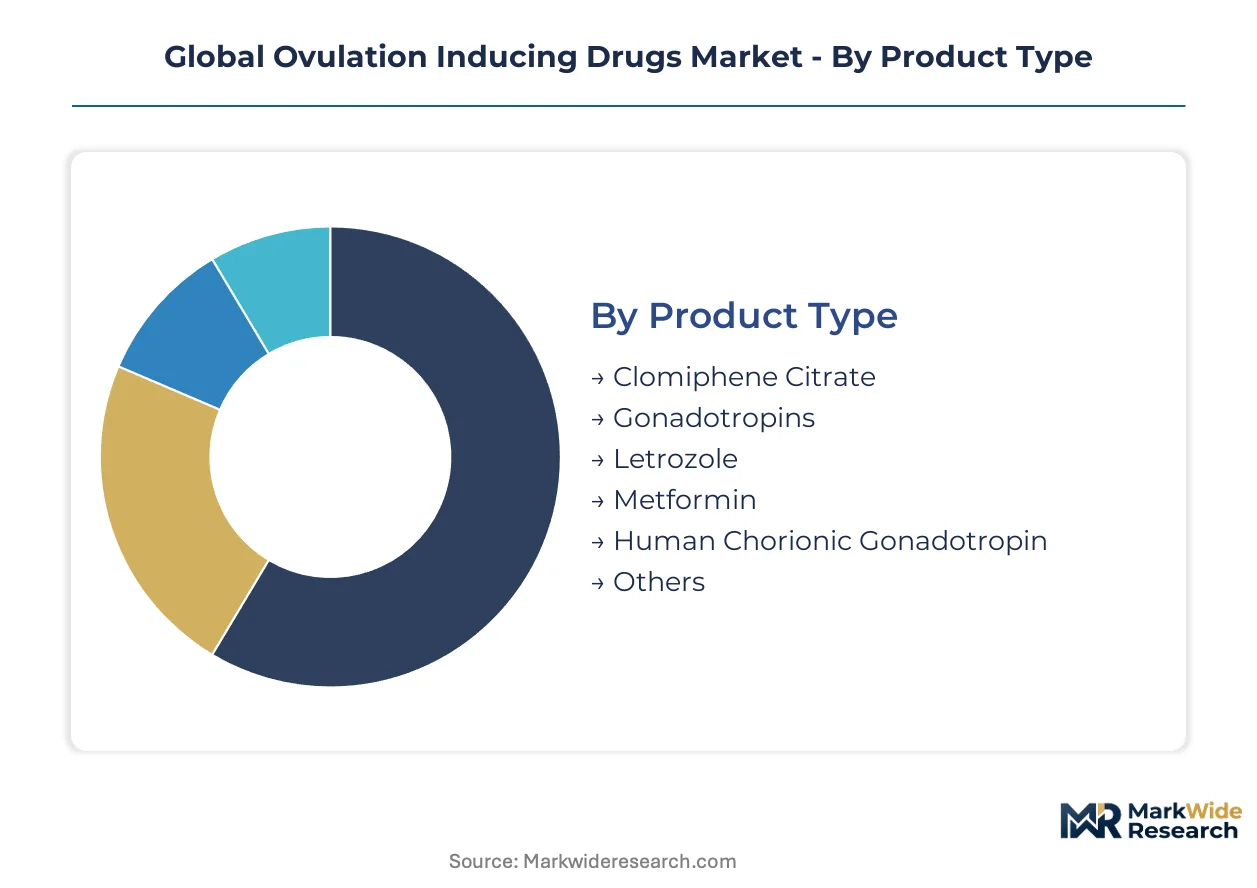
The Global Ovulation Inducing Drugs Market is precisely segmented to reflect the diverse treatment approaches and patient needs within reproductive medicine. Understanding these distinct segments allows manufacturers and providers to tailor product development and service delivery, optimizing outcomes across varied clinical scenarios.
Product Type:
The product type segmentation highlights the spectrum from standardized, widely used oral medications to highly customized, advanced injectable formulations.
- Clomiphene Citrate:This oral anti-estrogen medication acts by blocking estrogen receptors, prompting the pituitary gland to release more FSH and LH. It remains a high-volume, first-line treatment for anovulation, particularly in general gynecology settings across China and India due to its cost-effectiveness.
- Gonadotropins:These injectable hormones, including FSH and LH, directly stimulate ovarian follicle development, offering higher potency for complex cases like Polycystic Ovary Syndrome. Demand concentrates in specialized Fertility Clinics and Assisted Reproduction Centers, where their efficacy improves patient outcomes.
- Letrozole:An aromatase inhibitor, Letrozole is an oral medication used off-label to induce ovulation by reducing estrogen production.
- Metformin:This oral antidiabetic drug improves insulin sensitivity and is often prescribed for ovulation induction in women with Polycystic Ovary Syndrome.
- Human Chorionic Gonadotropin:Administered by injection, HCG triggers the final maturation and release of eggs after follicle stimulation.
- Others:This category encompasses various other pharmaceutical agents and experimental compounds used in specific or niche ovulation induction protocols.
Leading the category by volume: Clomiphene Citrate. Growing fastest: Gonadotropins.
Therapy Area:
Segmentation by therapy area delineates specific patient populations benefiting from ovulation-inducing drugs, reflecting varied underlying causes of infertility.
- Polycystic Ovary Syndrome:PCOS is a hormonal disorder causing enlarged ovaries with small cysts, leading to irregular periods and anovulation, making it a primary target for ovulation-inducing drugs. Injectable gonadotropins are frequently employed in Assisted Reproduction Centers for managing these complex cases.
- Anovulation:This condition involves the absence of ovulation, a common cause of female infertility, directly addressed by most ovulation-inducing medications. Oral clomiphene citrate is widely used as a first-line therapy for this broad patient group in clinics globally.
- Hypothalamic Amenorrhea:Characterized by the cessation of menstruation due to hypothalamic dysfunction, often linked to stress or low body weight.
- Luteal Phase Defect:This involves insufficient progesterone production after ovulation, hindering successful embryo implantation.
- Premature Ovarian Failure:Occurs when ovaries stop functioning before age 40, leading to a decline in egg production.
- Endometriosis:A condition where uterine tissue grows outside the uterus, potentially affecting fertility and requiring ovulation induction in some cases.
The largest application segment is Polycystic Ovary Syndrome. Anovulation therapies are undergoing continuous innovation.
End User:
The end-user segmentation highlights the specialized infrastructure and varying levels of care involved in administering ovulation-inducing drugs.
- Fertility Clinics:These specialized facilities provide comprehensive diagnostic and treatment services for infertility, serving as the primary setting for complex ovulation induction protocols. Their consolidation into larger networks in the United States and Europe centralizes purchasing power.
- Assisted Reproduction Centers:Focused on advanced reproductive technologies like IVF and ICSI, these centers utilize high-value injectable gonadotropins for controlled ovarian stimulation. They represent a significant demand concentration for advanced formulations due to their specialized patient cohorts.
- Gynecology Centers:These centers offer general women's health services, including initial fertility assessments and prescribing first-line oral ovulation induction drugs.
- Obstetrics Hospitals:While primarily focused on pregnancy and childbirth, obstetrics hospitals may manage some basic ovulation induction cases or refer patients to specialized units.
- Diagnostic Labs:These facilities provide essential hormonal testing and monitoring services crucial for guiding ovulation induction treatments.
- Independent Specialists:Individual fertility specialists operating outside large networks also prescribe and manage ovulation induction therapies, though their purchasing power is diminishing.
Fertility Clinics drive the highest volume demand. Assisted Reproduction Centers exhibit the steepest expansion trajectory for advanced therapies.
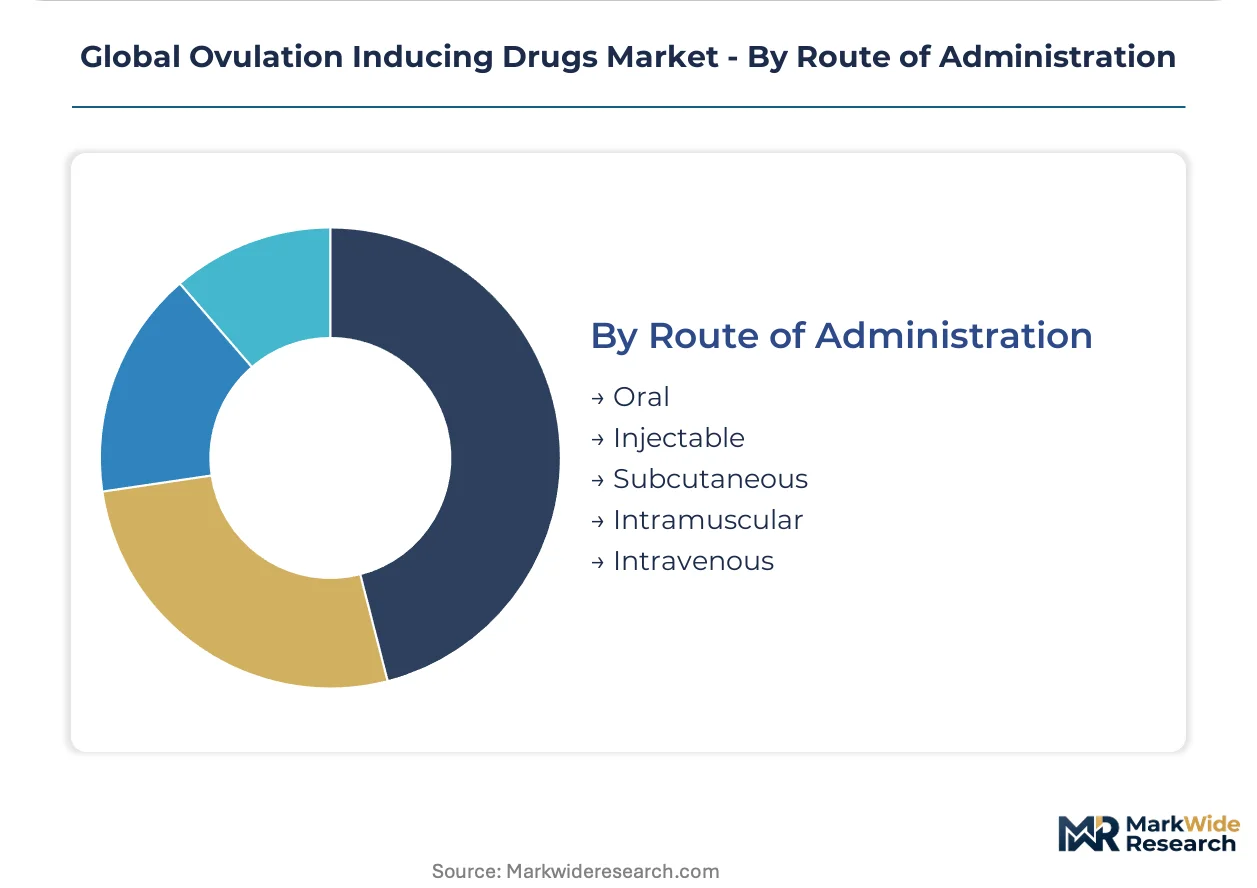
Route of Administration:
This category reflects the diverse methods by which ovulation-inducing drugs are delivered, impacting patient convenience, efficacy, and clinical settings.
- Injectable:This route involves administering drugs directly into the body via needle, offering precise dosing and high bioavailability, particularly for gonadotropins. Its use is prevalent in Assisted Reproduction Centers due to the need for controlled ovarian stimulation and monitoring.
- Oral:Medications taken by mouth, such as clomiphene citrate and letrozole, offer convenience and are typically the first-line treatment for anovulation due to their ease of use. This route dominates initial treatment phases in gynecology centers across India and China.
- Subcutaneous:A specific injectable method where medication is delivered just under the skin, often allowing for easier self-administration by patients.
- Intramuscular:This injection route delivers medication deep into a muscle, used for certain gonadotropin formulations requiring slower absorption.
- Intravenous:Administering drugs directly into a vein, this route is generally reserved for urgent or hospital-based scenarios due to its rapid effect.
Injectable administration commands the highest value segment. Oral administration maintains the largest patient base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding healthcare infrastructure and rising infertility rates anchor significant demand for ovulation inducing drugs. This concentration of patient need drives innovation and market expansion across Asia and other key global markets. Specialized fertility clinics in major urban centers are critical for advanced treatment delivery.
China
China's rising infertility rates and expanding healthcare access create substantial demand for ovulation inducing drugs. The NMPA's stringent approval processes shape market entry for new therapies. Major metropolitan areas like Shanghai and Beijing feature advanced fertility clinics rapidly adopting injectable gonadotropins.
India
India exhibits strong demand for oral ovulation inducing drugs, particularly clomiphene citrate, due to its cost-effectiveness and widespread availability. The CDSCO oversees pharmaceutical approvals, balancing access with safety. Urban centers like Delhi and Mumbai show rapid expansion of gynecology centers offering initial fertility treatments.
United States
The United States market benefits from large, corporate-backed fertility clinic networks concentrating purchasing power for advanced therapies. US FDA regulations mandate extensive safety and efficacy data for new drug approvals. Medical research clusters in Boston and California lead innovation in reproductive medicine.
Germany
Germany presents a significant market for high-value injectable gonadotropins, supported by robust healthcare infrastructure. The European Medicines Agency (EMA) increasingly requires real-world evidence for post-approval monitoring of biologics. Pharmaceutical development clusters in Frankfurt and Munich drive specialized reproductive medicine research.
Brazil
Brazil's growing middle class and increasing awareness of fertility solutions contribute to rising patient demand. ANVISA, the national health surveillance agency, regulates drug market access and pricing. Major urban centers such as São Paulo and Rio de Janeiro are seeing new fertility clinic establishments.
Global Ovulation Inducing Drugs Market Key Industry Players
Established producers occupy the standard tier, offering a broad portfolio of both oral and injectable ovulation inducing drugs across various therapy areas. Emerging entrants pursue niche segments such as personalized medicine protocols or advanced drug delivery systems, often targeting specific patient cohorts. The market structure exhibits a dynamic interplay between large pharmaceutical conglomerates and specialized biotech firms. Portfolio diversification into complementary reproductive health solutions and strategic partnerships with fertility clinic networks are dominant competitive moves.
Specialists in reproductive medicine, such as Ferring Pharmaceuticals, exemplify focused product development and institutional sales strategies. Merck & Co. occupies a position among established pharmaceutical giants, leveraging its extensive distribution channels to service both clinics and hospitals. Novartis AG represents a diversified global pharmaceutical company with a broad therapeutic presence, including some reproductive health offerings. These companies continue to adapt their strategies to the evolving landscape of consolidated fertility clinic networks and biosimilar competition.
| Leading Market Players |
|---|
| Novartis AG |
| Ferring Pharmaceuticals |
| EMD Serono |
| Merck & Co. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd |
| Abbott |
| Bayer AG |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Skilled fertility specialists in major urban centers drive labor-cost differentials, which directly influence pricing-tier spreads for ovulation inducing drugs. These cost variations impact patient access and treatment affordability across regions.
Pricing Analysis
The volume-vs-margin split heavily favors high-value injectable gonadotropins, despite oral clomiphene citrate leading in patient volume. Contract-based long-term offtake agreements dominate pricing for large fertility clinic networks, while individual clinics often use per-unit transactional models. Price differentiation stems from formulation advancements, demonstrated clinical efficacy, and strong brand presence. Pricing pressure intensifies due to biosimilar competition and centralized procurement demands.
Supply Chain Analysis
Direct institutional sales channels handle the majority of advanced ovulation inducing drugs for large fertility clinic networks. Supply concentration for Active Pharmaceutical Ingredients (APIs) and finished products is notable in China, India, and European manufacturing hubs. A key supply chain risk involves regulatory restrictions and potential single-source vulnerabilities for complex biologic gonadotropins. Specialized pharmaceutical distributors also play a role in reaching smaller gynecology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ovulation inducing drugs market is a vertical-integration race, with players actively pursuing control over specialized fertility clinic networks. This downstream integration secures patient access and standardizes treatment protocols.
For Market Incumbents:
Acquire specialized fertility clinic networks to consolidate purchasing power and standardize formulary adoption. Defend market share against biosimilar competition by investing in long-acting recombinant gonadotropin R&D for superior patient outcomes. Leverage institutional sales teams to secure long-term contracts with large centers, mitigating price erosion. Strengthen relationships with Assisted Reproduction Centers through value-added digital health platforms.
For New Entrants and Emerging Players:
Launch personalized medicine protocols integrating pharmacogenomics to target specific patient cohorts with differentiated products. Penetrate under-served markets in Latin America and Southeast Asia with cost-effective oral therapies like Letrozole. Develop digital health platforms for patient support, enhancing adherence and building brand loyalty beyond the drug itself. Focus on demonstrating superior clinical outcomes in head-to-head trials to gain market access.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized biotech firms focused on reproductive medicine given the increasing demand for advanced fertility treatments. Long-term viability rests on innovation in drug delivery and personalized therapies. Target mid-cap companies with strong R&D pipelines for next-generation gonadotropins or unique oral formulations. The signal to watch is the expansion of insurance coverage for infertility treatments in new geographies, unlocking significant patient populations.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Long-Acting FSH | Improves patient convenience and adherence, reducing injection frequency for complex cases like PCOS. |
| Partnership with Large Fertility Clinic Networks | Secures formulary placement and centralized procurement contracts, concentrating demand for advanced therapies. |
| Investment in Pharmacogenomic R&D | Develops personalized medicine protocols, enhancing treatment success rates and product differentiation for patients. |
| Geographic Expansion into Southeast Asia | Captures growing patient demand from expanding middle classes in underpenetrated fertility markets. |
| Digital Health Platform Development | Enhances patient support for injection training and symptom tracking, building brand loyalty beyond medication. |
Research Approach
US FDA filings, EMA submissions, and NMPA guidelines formed the secondary backbone, providing regulatory and market entry insights. Primary interviews with fertility specialists, hospital procurement managers, and regulatory affairs leads offered critical qualitative data. This analysis combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation. Patient advocacy groups also contributed perspectives on treatment access and affordability.
Historical trendline analysis informed the projection of market growth across the analysis window. The framework modeled segmentation by product type, therapy area, end user, route of administration, and regional regulatory cluster. Compound annual growth rates were derived from a synthesis of historical performance and anticipated market dynamics. Key forecast inputs included evolving infertility rates and healthcare expenditure growth in emerging economies.
Unforeseen regulatory changes, accelerated biosimilar market entry, and shifts in reimbursement policies are the dominant revision risks. Forecasts reflect current market assumptions regarding treatment adoption and healthcare infrastructure development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Herbal Drugs Market