
 Fertility Testing Market | 2026-2036
Fertility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Fertility Testing Market Analysis
Modular bundling of hormone panels with app-connected readers is shifting how consumers evaluate at-home fertility solutions. Mira leverages its AI-powered hormone tracking ecosystem to anchor premium positioning among digitally native users. Proov differentiates through progesterone-specific validation kits that sustain clinical credibility beyond basic ovulation strips. Modern Fertility competes by extending affordable mail-in blood testing into employer benefits channels.
Fertility testing encompasses biochemical, microscopic, and molecular diagnostic methods that measure reproductive hormone levels, sperm parameters, or genetic markers to assess conception capability; ELISA and PCR platforms detect follicle-stimulating hormone, luteinizing hormone, and anti-Müllerian hormone with sensitivity thresholds reaching picogram-per-milliliter concentrations. Home Testing Kits command the largest volume pool as smartphone-integrated devices reduce laboratory dependency for baseline screening. Blood Tests capture concentrated margin pools where mail-in services command out-of-pocket premiums for comprehensive hormonal assessment panels.
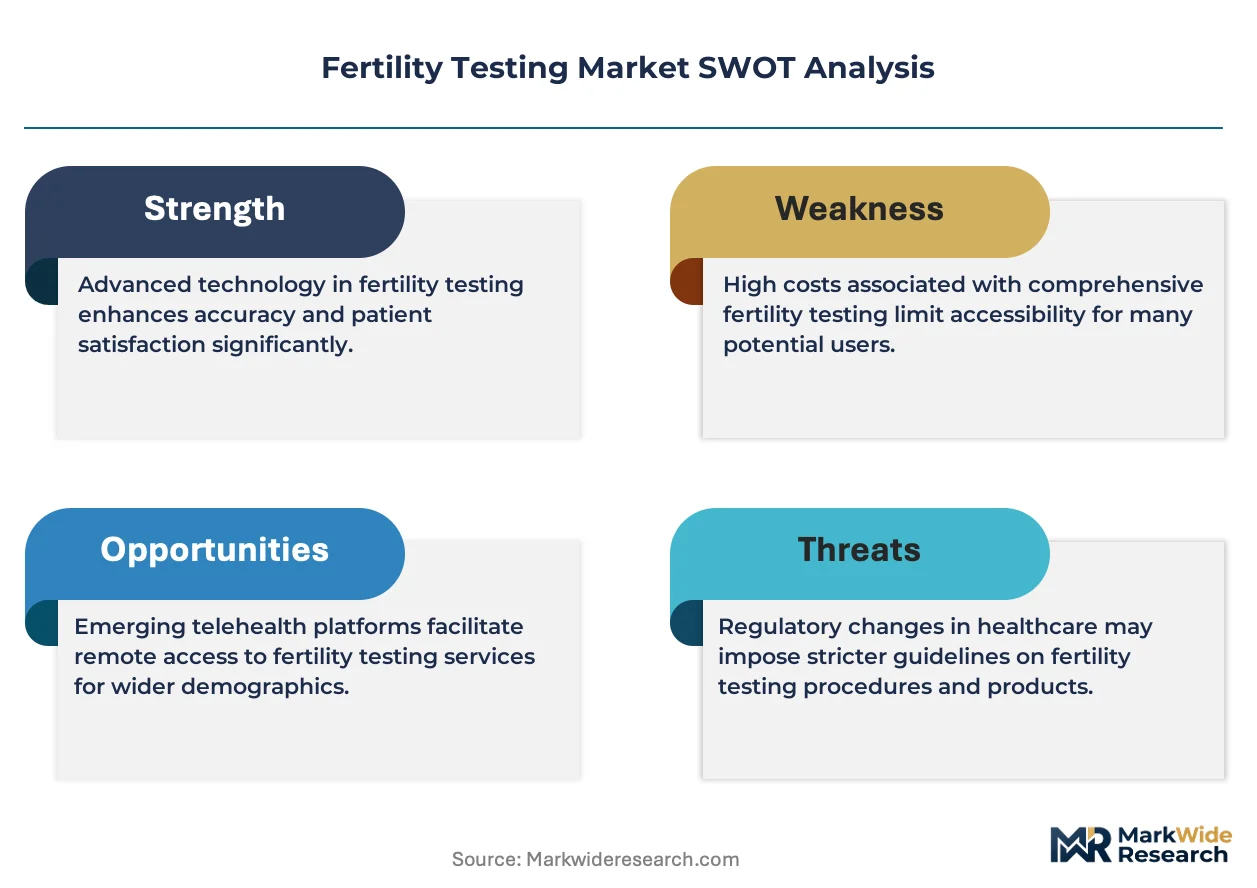
FDA oversight of direct-to-consumer diagnostic devices and HIPAA privacy requirements shape product design constraints and channel economics for US-distributed fertility kits. The EU's MDR and GDPR frameworks impose parallel compliance burdens on any European market entry, elevating documentation costs for app-connected platforms handling biometric data. Stakeholders must monitor how reimbursement policy experiments at CMS and private payers reshape the boundary between clinical and consumer-funded fertility testing spend.
Market Dynamics
Self-monitoring culture among digitally native consumers is compressing the boundary between clinical-grade diagnostics and at-home fertility screening, forcing manufacturers to recalibrate accuracy claims against FDA's evolving direct-to-consumer oversight pathways.
Growth Catalysts
- HIPAA-aligned data frameworks:The US privacy architecture enables app-connected hormone trackers to integrate with employer wellness portals without triggering additional compliance layers.
- Employer benefits channel expansion:Large self-insured employers in the United States are adding mail-in fertility panels to reproductive health bundles, normalizing out-of-pocket spend for baseline screening.
- AI-powered pattern recognition:Machine learning algorithms analyzing luteinizing hormone curves now predict ovulation windows with precision previously requiring serial ultrasound monitoring.
Market Restraints
- FDA 510(k) pathway friction:Direct-to-consumer diagnostic devices face extended review timelines when algorithm outputs claim clinical equivalence to laboratory reference methods.
- Reimbursement code gaps:CMS has not established discrete billing codes for at-home fertility monitoring, limiting channel economics to cash-pay or supplemental benefit models.
- Optical sensor component concentration:Smartphone-integrated readers rely on CMOS image sensors sourced from a concentrated East Asian supplier base, exposing hardware margins to single-source risk.
Strategic Opportunities
- Underpenetrated rural United States:Federally Qualified Health Centers in non-metropolitan counties lack on-site reproductive endocrinology, creating white space for telehealth-integrated mail-in testing.
- Progesterone validation protocols:Post-ovulatory confirmation testing represents an emerging application segment with higher clinical credibility and repeat-purchase economics than one-time AMH screening.
- State-level fertility preservation mandates:Emerging legislation in California and New York requiring insurance coverage for egg freezing is expanding the addressable market for ovarian reserve assessment.
Industry Challenges
- Clinical laboratory scientist staffing:Mail-in blood services require CLIA-certified personnel for result validation, creating recruitment bottlenecks in high-cost metropolitan labor markets.
- Multi-jurisdictional compliance architecture:Platforms handling biometric data must maintain parallel GDPR documentation for EU users and state-level privacy frameworks for California residents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertility Testing Market |
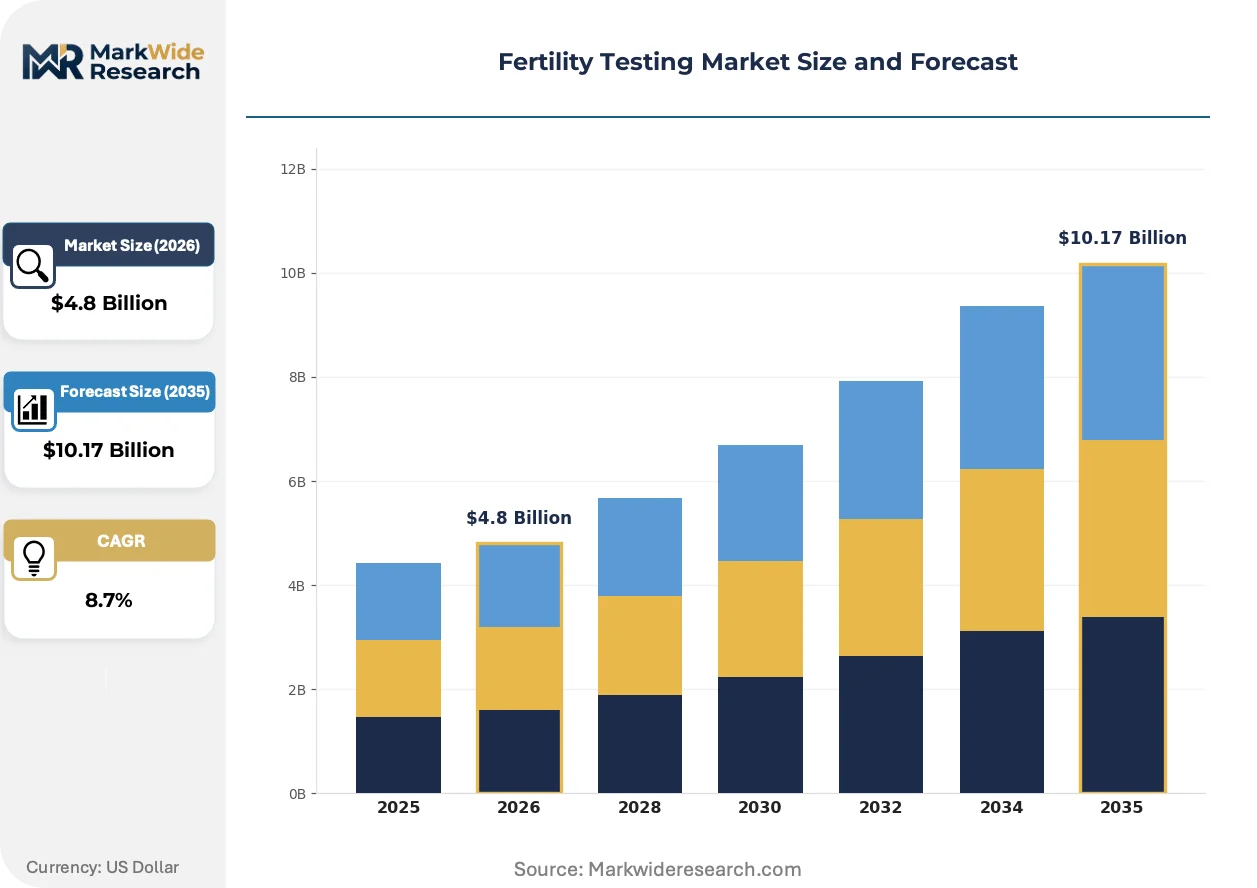
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Testing Kits, Blood Tests, Ovulation Prediction, Sperm Analysis Application: IVF, Hormonal Assessment, Male Fertility, Genetic Testing End User: Clinics, Laboratories, Home Users, Hospitals Technology: ELISA, PCR, Microscopy, Ultrasound |
| Companies Covered | Mira, BluDiagnostics, Proov, Trak Fertility, Give Legacy, OOVA, Bird&Be, Fellow, Modern Fertility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertility Testing Market Emerging Trajectories
Diagnostic accuracy claims are converging with smartphone camera capabilities, while regulatory sandboxes and shifting procurement patterns reshape how fertility solutions reach end users. Three forces currently dominate market evolution.
Smartphone-based colorimetric analysis is converging with cloud-based hormone curve modeling to eliminate dedicated hardware from baseline fertility tracking. Millennial and Gen-Z home users adopt these camera-only solutions faster than clinical guidelines update, compressing the addressable market for standalone reader devices and forcing hardware manufacturers toward premium multi-analyte panels.
The FDA's evolving oversight of software-as-a-medical-device is tightening validation requirements for algorithm-driven fertility predictions. Manufacturers must now submit prospective clinical studies demonstrating equivalence to laboratory immunoassays, extending time-to-market for AI-enhanced platforms and favoring incumbents with existing 510(k) clearances over venture-stage entrants.
Subscription-based hormone monitoring is displacing one-time purchase models in the direct-to-consumer channel. Fertility-focused telehealth platforms bundle monthly test shipments with virtual consultations, capturing recurring revenue and patient data assets that standalone kit manufacturers cannot replicate without vertical integration into clinical services.
Fertility Testing Market Segmentation
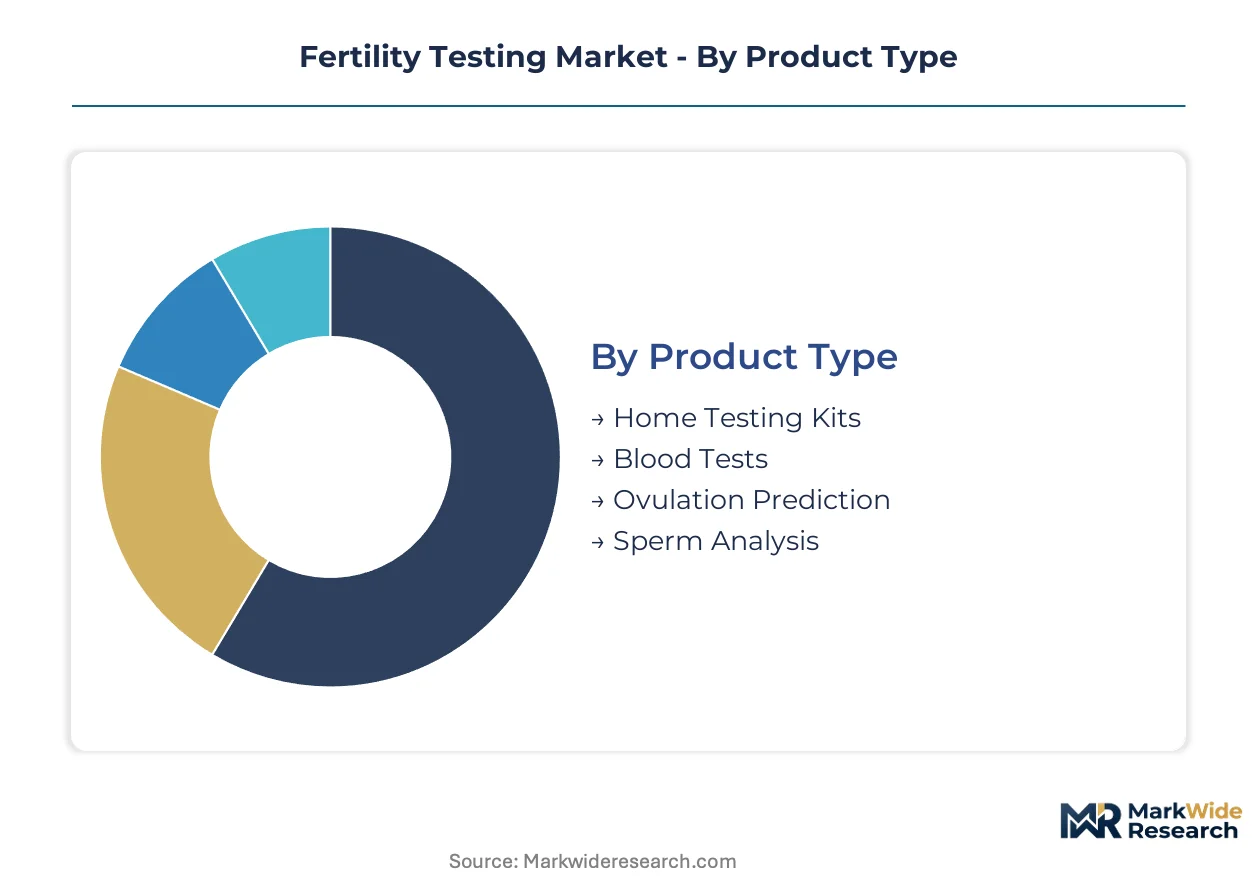
Segmentation in fertility testing reveals how clinical and consumer pathways diverge on accuracy requirements, purchase frequency, and regulatory exposure. Manufacturers must align product architecture with distinct buyer workflows rather than applying uniform specifications across channels.
Product Type:
Buyer decisions pivot on the trade-off between convenience and diagnostic depth, with smartphone integration now reshaping where that boundary falls.
- Home Testing Kits:Smartphone-integrated colorimetric readers detect luteinizing hormone and estrogen metabolites in urine samples. Demand concentrates among digitally native consumers in the United States seeking ovulation window prediction without clinic visits; FDA 510(k) pathway friction limits algorithmic claims for newer entrants.
- Blood Tests:Mail-in dried blood spot or venipuncture panels measure anti-Müllerian hormone, follicle-stimulating hormone, and thyroid markers. Self-insured employers in California and New York bundle these into reproductive health benefits, normalizing out-of-pocket spend for ovarian reserve screening.
- Ovulation Prediction:Single-use lateral flow strips and digital monitors track LH surges to identify fertile windows. Compact form factors suit retail pharmacy distribution with minimal regulatory overhead.
- Sperm Analysis:At-home semen collection kits with smartphone microscope attachments assess concentration and motility. Privacy-sensitive male consumers in urban United States markets drive adoption where clinic-based collection creates psychological barriers.
Volume sits with Home Testing Kits; growth tilts toward Blood Tests.
Application:
Clinical utility and reimbursement eligibility determine which applications attract sustained R&D investment versus opportunistic market entry.
- IVF:Pre-cycle ovarian reserve testing and post-stimulation monitoring require laboratory-grade precision for clinical decision-making. Fertility clinics in Massachusetts and Illinois demand AMH and antral follicle count correlation studies to justify protocol adjustments.
- Hormonal Assessment:Baseline and serial measurement of FSH, LH, estradiol, and progesterone guides both natural conception timing and assisted reproduction preparation. Telehealth platforms in Texas and Florida integrate these panels into virtual endocrinology consultations.
- Male Fertility:Semen analysis and hormonal evaluation address the 40-50% of infertility cases with male-factor contribution. Direct-to-consumer channels bypass urology clinic queues for initial screening.
- Genetic Testing:Carrier screening and preimplantation genetic testing require specialized laboratory infrastructure and genetic counseling workflows. Academic medical centers concentrate this capability due to complexity and liability exposure.
Margins concentrate in Genetic Testing; expansion is steepest in Hormonal Assessment.
End User:
Procurement authority and reimbursement mechanics fragment the addressable market across institutional and consumer channels.
- Clinics:Reproductive endocrinology practices purchase CLIA-waived point-of-care devices for same-day result delivery. Independent clinics in competitive metropolitan United States markets differentiate on speed of diagnostic feedback.
- Laboratories:Reference laboratories process mail-in specimens and hospital outreach testing with automated immunoassay platforms. Scale economies favor high-throughput operators in consolidated health system networks.
- Home Users:Direct-to-consumer purchasers prioritize discretion, app connectivity, and subscription economics over clinical-grade accuracy claims. Social media-informed purchasing drives brand switching in this segment.
- Hospitals:Academic medical centers and community hospital laboratories serve emergency and inpatient fertility-related presentations. Capital equipment procurement cycles extend 18-36 months, slowing technology refresh.
Laboratories capture the volume base; Home Users are expanding most quickly.
Technology:
Platform selection locks manufacturers into specific regulatory pathways, supply chain dependencies, and skill requirements for result interpretation.
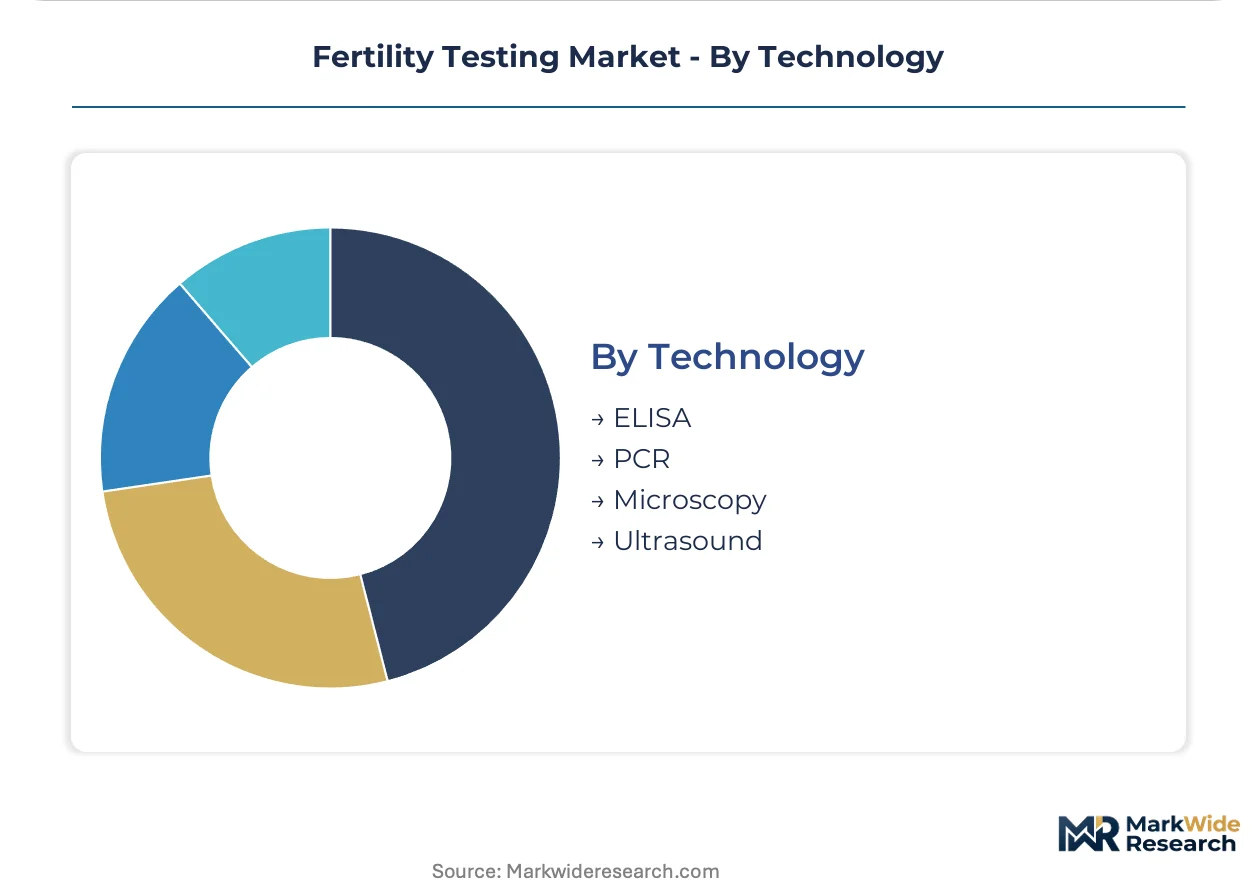
- ELISA:Enzyme-linked immunosorbent assays provide quantitative hormone measurement with picogram-per-milliliter sensitivity in laboratory settings. CLIA-certified personnel requirements constrain deployment in Federally Qualified Health Center settings.
- PCR:Polymerase chain reaction enables genetic marker detection and infectious disease screening relevant to fertility outcomes. Specialized thermal cycler equipment and contamination controls limit point-of-care adaptation.
- Microscopy:Manual and computer-assisted sperm analysis depends on technician training and standardized morphological criteria. Smartphone camera resolution improvements now challenge dedicated hardware for basic screening.
- Ultrasound:Transvaginal follicular monitoring remains the reference standard for ovarian response assessment during stimulation cycles. Equipment cost and sonographer certification requirements restrict this to clinical settings.
ELISA dominates current throughput; PCR is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of fertility testing hardware clusters in East Asian electronics corridors, while consumption concentrates in North American and European markets with established digital health infrastructure and employer-funded reproductive benefits.
United States
Employer-sponsored fertility benefits and direct-to-consumer subscription models drive demand concentration. FDA 510(k) oversight of software-as-a-medical-device creates compliance differentiation among algorithm-dependent platforms. Boston and San Francisco Bay Area clusters host venture-stage entrants integrating telehealth with mail-in hormone panels.
Germany
Reimbursement experimentation within statutory health insurance frameworks expands access to ovarian reserve screening. EU MDR documentation requirements elevate compliance costs for app-connected devices handling biometric data. Munich and Berlin industrial zones concentrate reference laboratory capacity for hormone immunoassay processing.
United Kingdom
NHS fertility pathway waitlists push demand toward private at-home screening alternatives. MHRA alignment with EU MDR post-Brexit maintains parallel regulatory documentation burdens. London and Cambridge clusters concentrate digital health venture activity targeting hormonal assessment workflows.
China
Rising infertility rates and expanding middle-class healthcare spending accelerate adoption of smartphone-integrated ovulation tracking. NMPA oversight of in-vitro diagnostic reagents requires domestic clinical trial data for registration. Shenzhen and Shanghai electronics corridors manufacture CMOS sensor components for fertility reader devices.
Japan
Aging demographics and delayed childbearing expand demand for fertility preservation assessment. PMDA consultation procedures for direct-to-consumer diagnostics remain more restrictive than US pathways. Tokyo and Osaka metropolitan areas concentrate reproductive medicine clinics driving clinical-grade testing volume.
Fertility Testing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the fertility testing landscape, creating a bifurcated structure where scale-driven laboratory operators coexist with venture-backed digital health entrants. Market concentration remains moderate, with no single entity commanding dominant share across both clinical and consumer channels. Three archetypes define competitive positioning: algorithm-native platform developers, CLIA-certified mail-in laboratory services, and hardware-integrated hormone tracker manufacturers. Strategic moves center on backward integration into clinical service delivery and geographic licensing partnerships to bypass regulatory approval timelines in secondary markets.
Within the venture-stage platform tier, Mira and Proov exemplify divergent specialization strategies—one anchoring multi-hormone AI-powered ecosystems, the other occupying progesterone-specific validation niches. Modern Fertility represents the employer benefits channel archetype, extending mail-in blood testing into corporate wellness procurement workflows. These three entities collectively illustrate how competitive positioning fragments across technological sophistication, clinical credibility claims, and distribution channel selection rather than converging on uniform product specifications.
| Leading Market Players |
|---|
| Mira |
| BluDiagnostics |
| Proov |
| Trak Fertility |
| Give Legacy |
| OOVA |
| Bird&Be |
| Fellow |
| Modern Fertility |
| Others |
Supply Flow & Price Mechanics
CMOS image sensor pricing volatility cascades through fertility hardware manufacturing, compressing margins on smartphone-integrated readers while elevating subscription-based software tiers as the primary value-capture mechanism for platform developers.
Pricing Analysis
Cost-down pressure on standalone hormone reader hardware accelerates because smartphone camera resolution improvements eliminate dedicated device requirements for baseline ovulation tracking. Three-tier pricing structure across premium multi-analyte panels, standard LH-digital monitors, and economy lateral-flow strips segments buyers by clinical credibility requirements. FDA 510(k) pathway friction intensifies pricing pressure on algorithm-native entrants lacking existing clearances. Self-insured employers exhibit lowest price sensitivity through benefits bundling, while direct-to-consumer cash-pay buyers drive volume at compressed per-unit economics.
Supply Chain Analysis
Biomedical engineer and CLIA-certified laboratory scientist shortages in Massachusetts and California constrain mail-in blood service expansion. Manufacturing of optical sensor components concentrates in China, South Korea, and Taiwan. Supply chain vulnerability rests on concentrated East Asian CMOS foundry capacity exposed to geopolitical disruption. Distribution runs through direct-to-consumer e-commerce platforms, telehealth-integrated subscription services, and hospital GPO procurement channels for clinical-grade immunoassay equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-a-medical-device oversight functions as a compliance moat, elevating capital requirements for algorithm-driven fertility platforms and advantaging incumbents with existing 510(k) portfolios against venture-stage entrants.
For Market Incumbents: Cement defensible positioning through backward integration into CLIA-certified laboratory capacity in high-employer-density metropolitan markets. Deepen algorithm training datasets via longitudinal patient monitoring relationships that venture-stage competitors cannot replicate without comparable time-to-market investments. Prioritize HIPAA-aligned data architecture investments that sustain employer wellness portal integrations against emerging privacy framework fragmentation. For New Entrants and Emerging Players: Launch via telehealth-integrated subscription models targeting Federally Qualified Health Centers in rural Texas and Florida counties lacking reproductive endocrinology infrastructure. Exploit white-space in progesterone validation protocols where clinical credibility claims sustain premium positioning beyond commodity ovulation strips. Prioritize state-level fertility preservation mandate alignment in California and New York regulatory corridors. For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithm-native platform developers with existing FDA 510(k) clearances in United States digital health corridors. Long-term viability hinges on recurring revenue attachment rates rather than one-time hardware margins. Monitor CMS reimbursement code establishment for at-home fertility monitoring as the critical inflection signal for channel economics expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Algorithm-driven platforms require prospective clinical studies demonstrating equivalence to laboratory immunoassay reference methods. |
| CLIA Laboratory Certification | Mail-in blood services depend on certified personnel for result validation in high-cost metropolitan labor markets. |
| Employer Benefits Channel Partnership | Self-insured employers in California and New York normalize out-of-pocket spend through reproductive health bundle procurement. |
| HIPAA-Aligned Data Architecture | Privacy frameworks enable app-connected hormone trackers to integrate with employer wellness portals without triggering additional compliance layers. |
| State Mandate Alignment Strategy | Emerging legislation requiring insurance coverage for fertility preservation expands addressable market for ovarian reserve assessment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fertility testing market analysis. Primary interviews with reproductive endocrinologists, CLIA laboratory directors, employer benefits consultants, and digital health platform executives combined with FDA 510(k) submission databases, CMS reimbursement policy documents, and hospital procurement system records. Bottom-up test volume modeling and top-down healthcare expenditure allocation triangulated market sizing across home testing kit, blood test, and clinic-based diagnostic segments.
Granularity-level modeling operated at product type, application, end user, and technology platform dimensions throughout the forecast period. CAGRs derived from regression analysis against digital health adoption curves and employer benefit penetration rates. Smartphone camera capability advancement trajectories and AI-powered hormone prediction algorithm accuracy improvements served as technology-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for camera-only colorimetric analysis would alter the outlook for dedicated hardware manufacturers. Forecasts reflect assumptions regarding FDA software-as-a-medical-device oversight evolution and state-level fertility preservation mandate expansion. Material deviation in CMS reimbursement code establishment or East Asian optical sensor supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Apoptosis Testing Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Global Sterility Testing Market
Testing Services
Global Bioburden Testing Market
Testing Services
Global Biologics Safety Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Test Strips Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
IVD Quality Control Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Hospital Acquired Disease Testing Market